
 Welding Materials Market | 2026-2036
Welding Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Welding Materials Market Outlook
The gap between premium alloy filler metals and commodity-grade welding wire is shifting as end-users demand certified performance for critical infrastructure. Lincoln Electric Holdings anchors North American supply through captive wire production and distribution density. ESAB Corporation differentiates via specialized flux formulations for offshore environments. Kobe Steel dominates premium titanium welding rod supply for Japanese aerospace tiers.
Welding materials encompass consumable and auxiliary substances—filler metals, fluxes, shielding gases, and electrodes—engineered to join metals through fusion, typically requiring tensile strength matching or exceeding base materials. These products serve structural integrity in load-bearing assemblies across energy, transport, and heavy fabrication sectors. Filler metals command the largest revenue pool given recurring replacement cycles, while flux-cored technology gains share in high-deposition outdoor construction. Aerospace end-use generates the steepest margin premiums due to qualification barriers and traceability requirements.
FDA oversight of medical device welding and EPA emissions standards for manufacturing facilities shape product formulation and facility investment in the United States. REACH chemical restrictions and CE marking under the EU Machinery Directive govern material composition and equipment interoperability across European supply chains. Stakeholders must monitor evolving alloy certification protocols and carbon border adjustments that could restructure sourcing economics between Asian producers and Western fabricators.
Market Dynamics
Flux-cored wire technology is compressing the performance gap between manual and automated welding, forcing reformulation of shielding gas chemistries and electrode geometries across heavy fabrication supply chains. South Korean shipbuilders and Chinese coastal manufacturers drive this shift through specification tightening for high-deposition outdoor construction.
Growth Catalysts
- EU F-Gas Regulation:Mandates on fluorinated greenhouse gas emissions push shielding gas manufacturers toward low-GWP argon-helium blends and synthetic alternatives in European fabrication facilities.
- Flux-cored wire adoption:High-deposition outdoor construction segments favor self-shielded and gas-shielded flux-cored processes for productivity gains in wind tower and bridge fabrication.
- China's coastal manufacturing belt:Concentrated demand in Jiangsu, Zhejiang, and Guangdong provinces sustains volume pull for commodity-grade consumables and specialized alloy wires.
Market Restraints
- Nickel and molybdenum price volatility:Premium stainless steel and nickel-alloy filler metals face margin compression when London Metal Exchange prices spike, squeezing spot procurement budgets.
- Japanese titanium rod concentration:Aerospace-grade titanium welding rod supply remains captive to a narrow supplier base, creating qualification bottlenecks for tier-2 fabricators.
- REACH chemical restrictions:ECHA substance of very high concern listings force reformulation of flux coatings and electrode coatings, extending R&D cycles for European-market products.
Strategic Opportunities
- India's infrastructure buildout:National highway and metro rail expansion creates underpenetrated demand for certified structural welding consumables beyond current import-dependent supply.
- Medical device welding:FDA oversight of implantable device joining processes opens premium-margin segments for ultra-clean filler metals with full lot traceability.
- Laser-arc hybrid welding:Convergence of laser beam and gas metal arc processes enables single-pass thick-section joining in shipbuilding, reducing filler metal volume per meter.
Industry Challenges
- Certified welder scarcity:Pipeline construction and nuclear fabrication face acute shortages of ASME Section IX-qualified operators, extending project timelines.
- Alloy qualification timelines:Aerospace OEM specification locks require 18-36 month approval cycles for new filler metal compositions, freezing supplier switching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welding Materials Market |
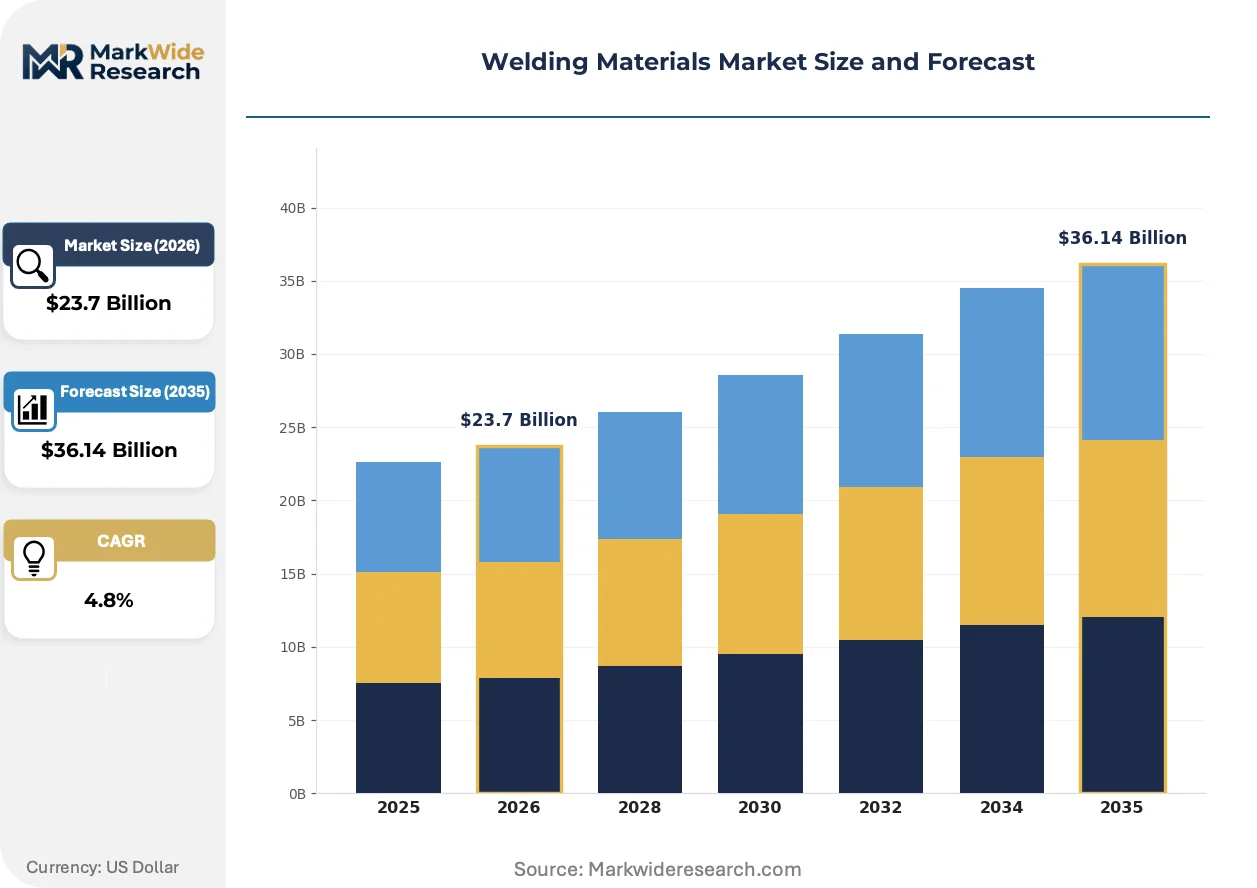
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $36.14 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filler Metals, Welding Rods, Flux, Welding Wire Technology: MIG, TIG, Stick, Flux-Cored End User: Construction, Manufacturing, Automotive, Aerospace Application: Pipe Welding, Structural Welding, Fabrication, Repair |
| Companies Covered | Air Liquide S.A., Kobe Steel, Ltd., Lincoln Electric Holdings, Inc., Air Products and Chemicals, Inc., voestalpine AG, ESAB Corporation, Linde plc, Fronius International GmbH, Illinois Tool Works Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welding Materials Market Strategic Shifts
Active materials science and regulatory chemistry are converging to redefine welding consumable specifications, with traceability systems and low-emission formulations becoming baseline requirements rather than differentiators.
Metal-cored wires are expanding into structural steel fabrication by delivering spray transfer characteristics with lower fume generation than solid wire equivalents. Bridge contractors and heavy equipment manufacturers in Germany and the United States adopt these products for indoor and confined-space work. The technology is expanding into segments previously locked into solid wire procurement through revised AWS D1.1 prequalification protocols.
EPA emissions standards for manufacturing facilities impose fume capture and ventilation mandates on high-volume welding operations. Fabricators in the United States respond by specifying low-manganese filler metal formulations and investing in localized exhaust systems. Shielding gas suppliers now bundle gas delivery with fume monitoring services to maintain facility compliance.
Buyers in energy and transport sectors now unbundle consumable supply from equipment purchase, running separate RFPs for filler metals, gases, and technical support. Distributors in the Gulf Coast petrochemical corridor lose bundled-margin leverage as procurement teams centralize specification control. This pattern concentrates most visibly in Texas and Louisiana process industry facilities with centralized engineering functions.
Welding Materials Market Segmentation
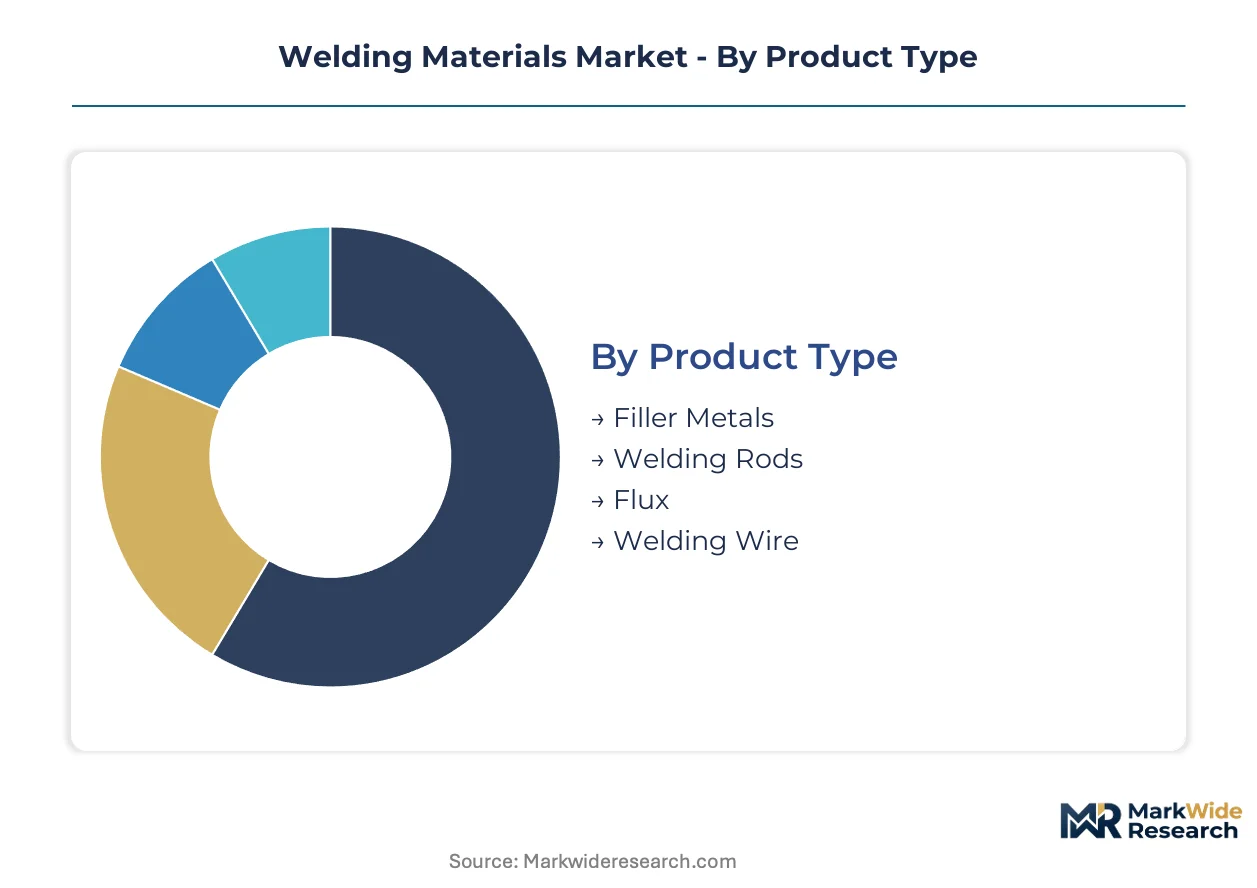
Welding materials buyers prioritize deposition rate, fume generation, and qualification burden differently across process types. Segmentation reveals where specification tightening concentrates margin and where commodity substitution erodes pricing power.
Product Type:
Purchasing managers weight replacement frequency against inventory carrying costs when allocating procurement budgets across consumable categories.
- Filler Metals:Solid and tubular wires deliver tensile strength matching base materials through controlled alloy chemistry. Recurring replacement cycles in heavy fabrication sustain the largest revenue pool, though nickel price volatility squeezes spot procurement budgets for stainless grades.
- Welding Wire:Metal-cored formulations generate lower fume than solid equivalents, expanding into structural steel fabrication through revised AWS D1.1 prequalification protocols. Bridge contractors in Germany and the United States adopt these for confined-space work.
- Welding Rods:Coated electrodes serve manual processes in field repair and maintenance where portability overrides automation economics.
- Flux:Agglomerated and fused formulations shield molten pools from atmospheric contamination, with specialized blends commanding premiums in offshore environments.
Filler metals lead on scale; welding wire leads on momentum.
Technology:
Automation readiness and operator certification requirements split procurement between high-productivity mechanized processes and flexible manual methods.
- Flux-Cored:Self-shielded and gas-shielded variants enable high-deposition outdoor construction without wind sensitivity. South Korean shipbuilders and Chinese coastal manufacturers drive specification tightening for wind tower and bridge fabrication.
- MIG:Gas metal arc welding delivers spray transfer efficiency in repetitive production environments, dominating automotive body-in-white and appliance manufacturing lines.
- TIG:Tungsten inert gas processes provide precision control for thin-section aerospace components and medical device joining where heat input minimization is critical.
- Stick:Shielded metal arc welding persists in pipeline field construction and repair where equipment portability and power flexibility outweigh deposition rate limitations.
Flux-cored processes expand most quickly in heavy fabrication; MIG retains volume dominance in manufacturing.
End User:
Certification burden and traceability requirements stratify demand between safety-critical applications and general fabrication.
- Aerospace:OEM specification locks demand 18-36 month approval cycles for new filler metal compositions, freezing supplier switching and sustaining steep margin premiums through qualification barriers.
- Automotive:High-volume production lines specify low-spatter formulations and robotic wire feeding systems, with procurement centralizing at platform engineering level.
- Construction:Bridge and building fabricators balance productivity gains from flux-cored wire against fume capture investments mandated by EPA emissions standards.
- Manufacturing:General industrial fabrication spans commodity-grade consumables for equipment production, with buyers unbundling consumable supply from equipment purchase.
Construction leads on scale; aerospace leads on margin.
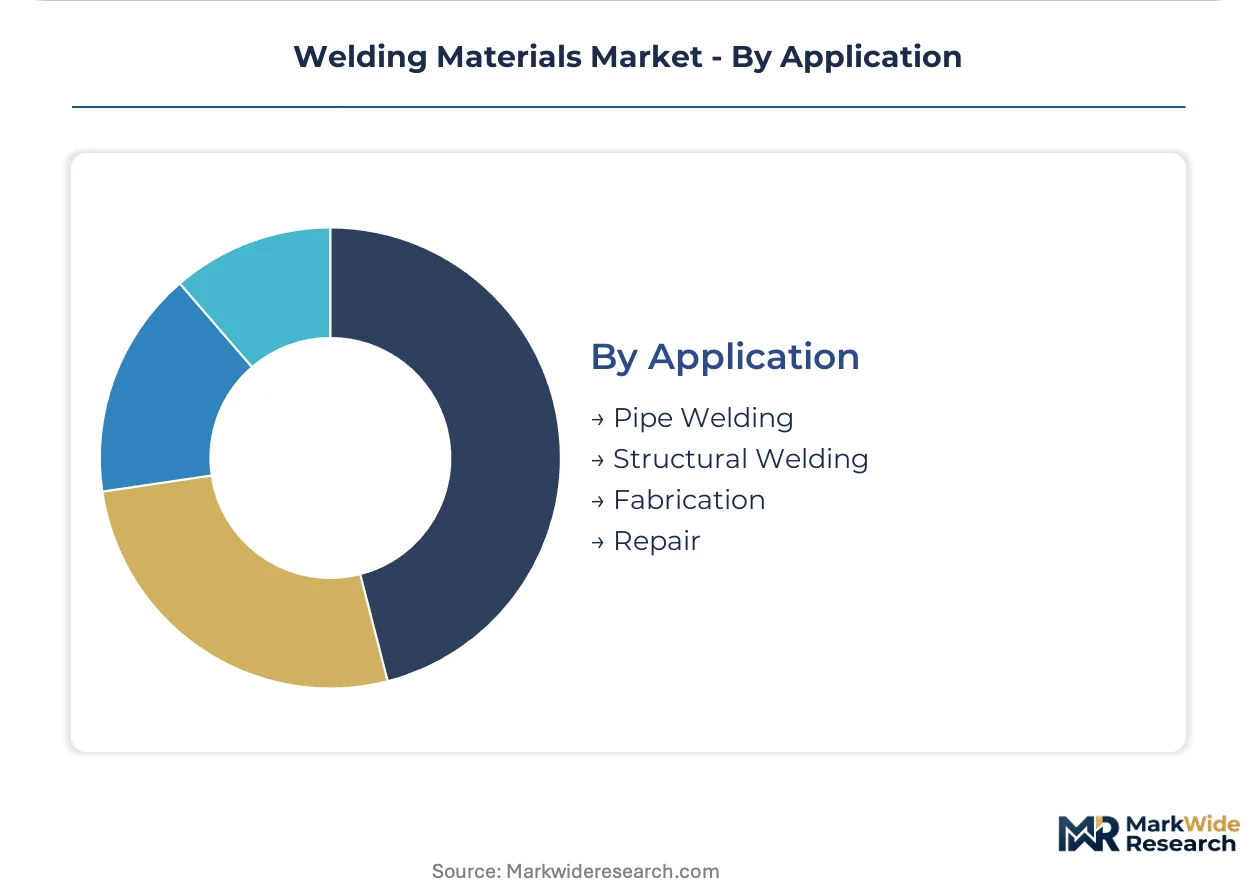
Application:
Joint geometry and accessibility determine consumable selection more than base material alone.
- Structural Welding:Multi-pass groove welds in building frames and bridge girders favor high-deposition processes, with metal-cored wires gaining share through lower fume generation.
- Pipe Welding:ASME Section IX qualification requirements constrain welder supply for pipeline construction, extending project timelines and concentrating demand on proven consumable brands.
- Fabrication:Shop-based production of pressure vessels and process equipment balances automation investment against lot size variability.
- Repair:Field maintenance operations prioritize electrode and wire portability, with stick and self-shielded flux-cored dominating outage and turnaround work.
Structural welding leads on scale; pipe welding leads on qualification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified welder concentrations in South Korea, Germany, and the United States anchor fabrication capacity for critical infrastructure. Regional demand patterns diverge between high-specification aerospace clusters and commodity-grade construction belts.
United States
Gulf Coast petrochemical expansion and shale infrastructure sustain demand for ASME-qualified consumables. EPA emissions standards mandate fume capture investments at high-volume fabrication facilities. Houston and Louisiana process industry corridors concentrate procurement centralization among engineering-led buyers.
Germany
Automotive platform engineering and wind tower fabrication drive specification tightening for low-fume formulations. REACH chemical restrictions force flux coating reformulation cycles extending R&D timelines. Bridge contractors in North Rhine-Westphalia adopt metal-cored wires for confined-space structural work.
China
Jiangsu, Zhejiang, and Guangdong coastal provinces concentrate volume demand for commodity-grade consumables and specialized alloy wires. MIIT industrial standards govern welding material quality certification for domestic infrastructure projects. Shanghai and Shenzhen manufacturing clusters import premium titanium rods for aerospace tier supply.
South Korea
Shipbuilders in Ulsan and Busan drive adoption of advanced filler metals for high-deposition outdoor construction. MFDS oversight of medical device welding opens premium segments for ultra-clean consumables with full lot traceability. Daegu-Gyeongbuk machinery builders specify flux-cored processes for wind tower fabrication.
Japan
Aerospace-grade titanium welding rod supply concentrates among qualified domestic producers serving tier-1 OEMs. METI industrial policy supports advanced manufacturing R&D for next-generation joining processes. Nagoya and Kobe industrial corridors maintain captive supply relationships for critical alloy formulations.
Welding Materials Market Competitive Environment
Top-tier vendors anchor premium alloy and shielding gas supply, while mid-scale regional fabricators compete on commodity wire volume and distribution density. The vendor base stratifies across three tiers: integrated gas-and-consumable majors, specialized filler metal producers, and regional distribution-focused operators. Two dominant competitive moves are reshaping positioning: captive wire production investments to secure raw material margins, and bundled gas-delivery-with-monitoring services to lock in facility compliance contracts.
Among Japan-based producers, Kobe Steel, Ltd. occupies a position exemplifying premium titanium rod concentration for aerospace qualification barriers. Lincoln Electric Holdings, Inc. and ESAB Corporation represent the integrated North American-European tier, anchoring supply through distribution density and specialized flux formulations respectively. These three names illustrate how geographic origin and structural suffixes map to distinct competitive archetypes without requiring specific operational claims.
| Leading Market Players |
|---|
| Air Liquide S.A. |
| Kobe Steel, Ltd. |
| Lincoln Electric Holdings, Inc. |
| Air Products and Chemicals, Inc. |
| voestalpine AG |
| ESAB Corporation |
| Linde plc |
| Fronius International GmbH |
| Illinois Tool Works Inc. |
| Others |
Value Chain & Pricing Dynamics
Procurement centralization among Gulf Coast petrochemical engineering teams unbundles consumable supply from equipment purchase, forcing distributors to compete on specification compliance rather than bundled-margin leverage and compressing pricing power in commodity-grade segments.
Pricing Analysis
The bundled-vs-unbundled service split separates gas-delivery-with-monitoring contracts from standalone consumable procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and lot traceability depth. Price differentiation stems from ASME qualification burden and fume-generation specifications. Cost compression in commodity stainless wire intensifies because nickel price volatility squeezes spot procurement budgets. Construction buyers exhibit highest price sensitivity; aerospace tier-1 OEMs show lowest.
Supply Chain Analysis
Dual-sourcing requirements for ASME-qualified consumables mandate multi-supplier qualification among pipeline contractors and nuclear fabricators. Supply concentrates in China, Japan, and South Korea for titanium rods, specialty fluxes, and high-deposition wire formulations. Raw material dependencies draw from nickel, molybdenum, and helium feedstocks. Single-source vulnerability runs through Japanese aerospace-grade titanium rod concentration. Distribution runs through regional welding supply houses with technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The welding materials market functions as a stable compounder anchored by recurring replacement cycles in heavy fabrication and infrastructure maintenance that resist demand volatility.
For Market Incumbents: Deploy captive wire production investments to secure raw material margins against nickel price volatility. Deepen certification asset moats by accelerating ASME and AWS prequalification protocols for metal-cored formulations. Channel control through bundled gas-delivery-with-monitoring services locks in facility compliance contracts and defends against unbundling pressure from centralized procurement teams.
For New Entrants and Emerging Players: Direct-to-fabricator digital platforms bypass incumbent distributor networks in India's infrastructure buildout corridor. Target underpenetrated demand for certified structural consumables in national highway and metro rail expansion. Specialized flux formulations for offshore wind environments offer qualification-light entry before competing in aerospace specification locks.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional distribution-focused operators consolidating fragmented welding supply house networks. The five-to-ten year viability window favors platforms with technical service density and captive alloy formulation capabilities. Acquisition target archetype: mid-scale regional fabricators with AWS D1.1 prequalified product lines and Gulf Coast petrochemical corridor presence. Monitor carbon border adjustment implementation as inflection indicator for Asian producer sourcing economics restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wire Production | Captive supply of nickel-alloy feedstock insulates margin from London Metal Exchange volatility. |
| Low-GWP Shielding Gas Formulation | EU F-Gas Regulation compliance opens European fabrication facility contracts to qualified suppliers. |
| ASME Section IX Qualification Investment | Prequalified consumable status reduces welder certification friction in nuclear and pipeline construction. |
| Fume Monitoring Service Bundling | EPA emissions standard compliance contracts lock in multi-year facility supply relationships. |
| Medical Device Welding Certification | FDA oversight of implantable device joining creates premium-margin segment with full lot traceability requirements. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with welding engineers, procurement leads at heavy fabricators, distribution channel partners, and technical R&D directors at consumable manufacturers combine with secondary validation from AWS certification databases, EPA emissions compliance filings, customs trade records, and SEC 10-K disclosures from listed suppliers. Triangulation across these sources anchors volume estimates.
Historical trendline analysis of filler metal replacement cycles and shielding gas consumption patterns informs the projection framework. Segmentation dimensions modeled include product type, welding technology, end-use industry, and regional manufacturing cluster. CAGRs derive from regression analysis of deposition rate trends and specification tightening trajectories across the analysis window. Forecast inputs incorporate flux-cored wire adoption curves and laser-arc hybrid welding penetration assumptions.
The model assumes a particular technology adoption path; alternative pathways for laser-arc hybrid welding would alter the outlook for filler metal volume per meter. Forecasts reflect assumptions regarding nickel price stability, REACH chemical restriction timelines, and certified welder pipeline development. Deviation in carbon border adjustment implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Aluminum Sheet Market
Metals
Asia-Pacific Aluminum Casting Market
Metals
Global Welding Powder Market
Metals
Metallic Rope Cords Market
Metals
Steel Sheet for Home Appliances Market
Metals
Niobium Oxide Market
Metals
Osmium Market
Metals
Steel Ingots Market
Metals
GCC Aluminium Cans Market
Metals
Rare Earth Metals Market
Metals
United States Metal Casting Market
Metals
Steel Salvage Drums Market
Metals
Seamless Stainless Steel Products Market
Metals
Medium Carbon Steel Market
Metals
Wear Steel Plate Market
Metals
Steel Wire Market