
 Coatings Raw Materials Market | 2026-2036
Coatings Raw Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Coatings Raw Materials Market Analysis
Multi-source resin procurement is consolidating among top-tier coatings formulators seeking supply security. BASF SE leverages its integrated petrochemical network to captive-produce epoxy and polyurethane intermediates. PPG Industries anchors North American supply through long-term offtake agreements with specialty chemical partners. Covestro AG competes on aliphatic isocyanate technology leadership for automotive clearcoat applications.
Coatings raw materials encompass the functional constituents—resins as film-forming binders, pigments for opacity and color, fillers for rheology and cost reduction, and additives for flow, durability, or cure control—that are compounded into protective or decorative surface finishes. These materials typically undergo dispersion, grinding, and let-down stages to achieve specified particle size distributions, viscosity profiles, and volatile organic compound limits before final application. Resins and additives capture the deepest margin pools due to formulation complexity and performance-critical specifications, while water-based and powder coating formulations are outpacing solvent-based systems on regulatory tailwinds. UV-curable segments occupy a specialized niche where line-speed and energy-cure efficiency justify premium positioning in furniture and electronics finishing.
EPA VOC regulations in the United States, REACH chemical authorization in Europe, and China's MEE emissions standards collectively restrict solvent-borne formulation and redirect investment toward compliant resin architectures. Product registration burdens under these frameworks favor suppliers with dedicated regulatory affairs capabilities and regional testing infrastructure. Stakeholders must monitor bio-based feedstock certification schemes and carbon-border adjustment mechanisms as these will increasingly determine raw material qualification and contract eligibility.
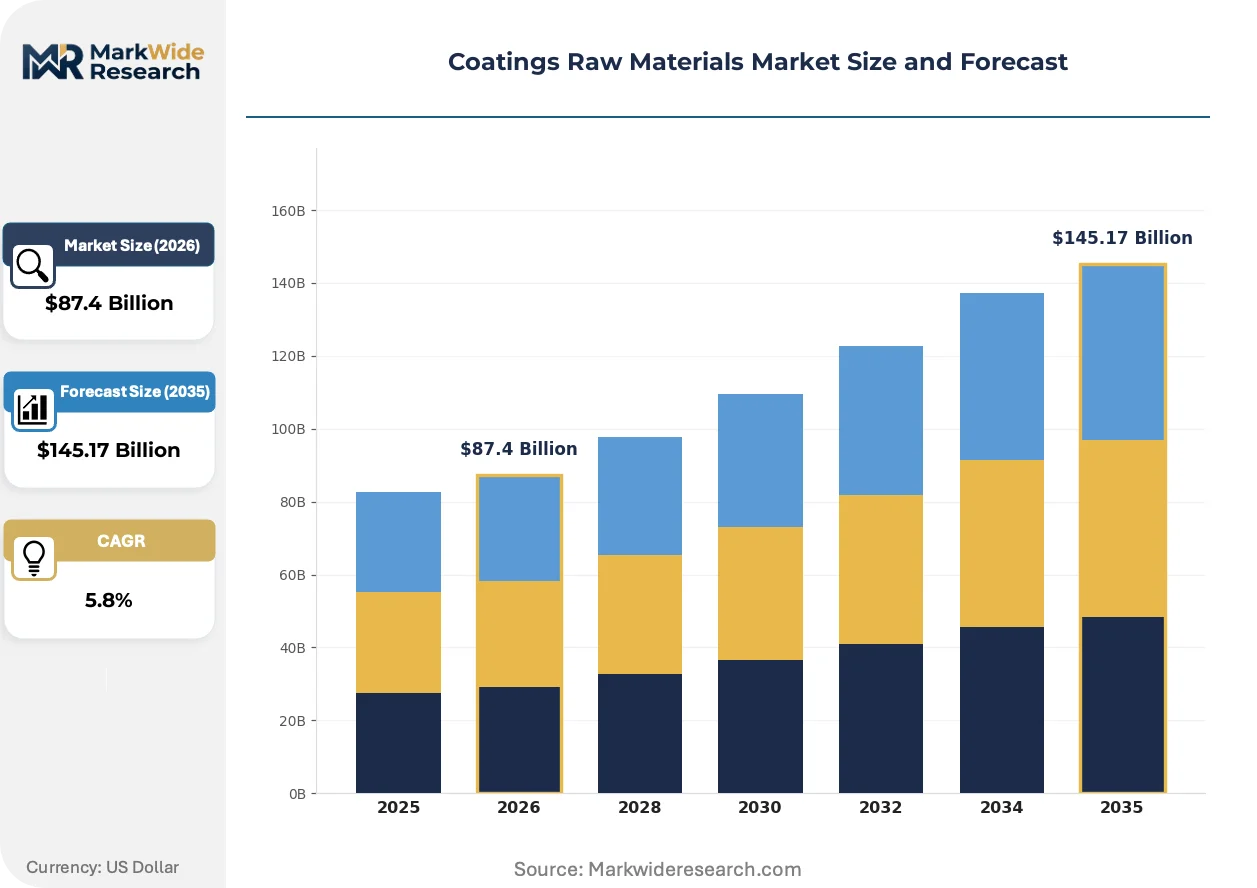
Market Dynamics
Reformulation pressure from REACH and EU Green Deal mandates is compressing solvent-borne resin demand while forcing rapid water-borne and powder coating architecture adoption across formulator R&D pipelines.
Growth Catalysts
- Automotive OEM Specification Pull:Clearcoat durability requirements are elevating aliphatic isocyanate consumption for refinish and OEM assembly lines. This specification cascade propagates through tiered supply agreements.
- China Construction Intensity:Domestic infrastructure and export manufacturing sustain heavy industrial coating precursor offtake. MEE emissions standards simultaneously redirect local production toward compliant resin systems.
- REACH Authorization Deadlines:Sunset dates for hazardous substance registration are accelerating compliant resin substitution programs. Formulators with pre-registered bio-based alternatives capture contract eligibility advantages.
Market Restraints
- Petrochemical Feedstock Volatility:Epoxy and polyurethane intermediate pricing tracks naphtha and propylene oxide swings. Margin compression hits specialty resin producers without backward integration into basic chemicals.
- Isocyanate Supply Concentration:Aliphatic isocyanate production clusters in Germany and China create geographic vulnerability. Single-source dependency for automotive clearcoat-grade HDI constrains formulator procurement flexibility.
- Cure Temperature Limitations:Powder coating thermal requirements exclude heat-sensitive substrates from conversion. Wood and plastic end-uses remain locked into liquid systems despite VOC regulatory pressure.
Strategic Opportunities
- India Industrial Expansion:PLI scheme incentives for domestic manufacturing are expanding protective coating demand. Local resin compounding capacity lags, creating import substitution openings for compliant water-borne systems.
- UV-Curable Furniture Finishing:Line-speed advantages in flat-line wood coating operations justify premium UV oligomer positioning. Energy-cure efficiency offsets higher raw material costs in high-throughput environments.
- Carbon Border Adjustment Mechanisms:EU CBAM implementation is rewarding low-carbon resin certification. Bio-based feedstock verification schemes are becoming contract pre-qualification requirements.
Industry Challenges
- Formulation Chemist Scarcity:Water-borne resin rheology control and film formation expertise sits with aging specialist cohorts. Knowledge transfer gaps constrain compliant product development timelines.
- Multi-Regulatory Registration Burden:Parallel EPA VOC, REACH, and China MEE compliance requires dedicated regional testing infrastructure. Smaller suppliers face exclusion from qualification pools due to fixed regulatory affairs costs.
- Legacy Solvent System Asset Stranding:Existing grinding and dispersion equipment lacks water-borne compatibility. Capital reconfiguration demands compete with R&D spending for constrained formulator budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coatings Raw Materials Market |
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $145.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Resins, Pigments, Fillers, Additives Formulation Type: Solvent-Based, Water-Based, Powder Coating, UV-Curable End Use Industry: Automotive, Construction, Furniture, Aerospace Application: Protective Coatings, Decorative Coatings, Specialty Coatings, Industrial Coatings |
| Companies Covered | Akzo Nobel N.V., The Sherwin-Williams Company, BASF SE, RPM International Inc., Nippon Paint Holdings Co., Ltd., Covestro AG, Axalta Coating Systems, Jotun, PPG Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coatings Raw Materials Market Emerging Trajectories
Bio-based resin feedstocks, digital color matching platforms, and modular additive dosing systems are converging to reshape how coating precursors are specified, supplied, and compounded into finished systems.
Distributed bio-epoxy production from lignin and vegetable oil precursors is decentralizing resin supply geography away from petrochemical hubs. Regional biorefinery partnerships in Brazil and Scandinavia are securing localized feedstock streams. Formulators near these facilities are reducing transport emissions and qualifying for procurement sustainability scorecards.
EPA VOC regulations and state-level air quality management district rules are compressing solvent-borne architectural coating permissible limits. California SCAQMD Rule 1113 and OTC Model Rule harmonization are forcing national product line consolidation. Manufacturers are discontinuing high-VOC SKUs ahead of staggered compliance deadlines to avoid inventory write-downs.
Specification behavior is compressing toward direct resin producer-formulator relationships, bypassing traditional distributor intermediaries. Large coatings manufacturers are negotiating long-term offtake agreements for specialty isocyanates and acrylic dispersions. This channel consolidation is most visible in North American automotive refinish supply chains where PPG and Axalta anchor volume commitments directly with BASF and Covestro.
Coatings Raw Materials Market Segmentation
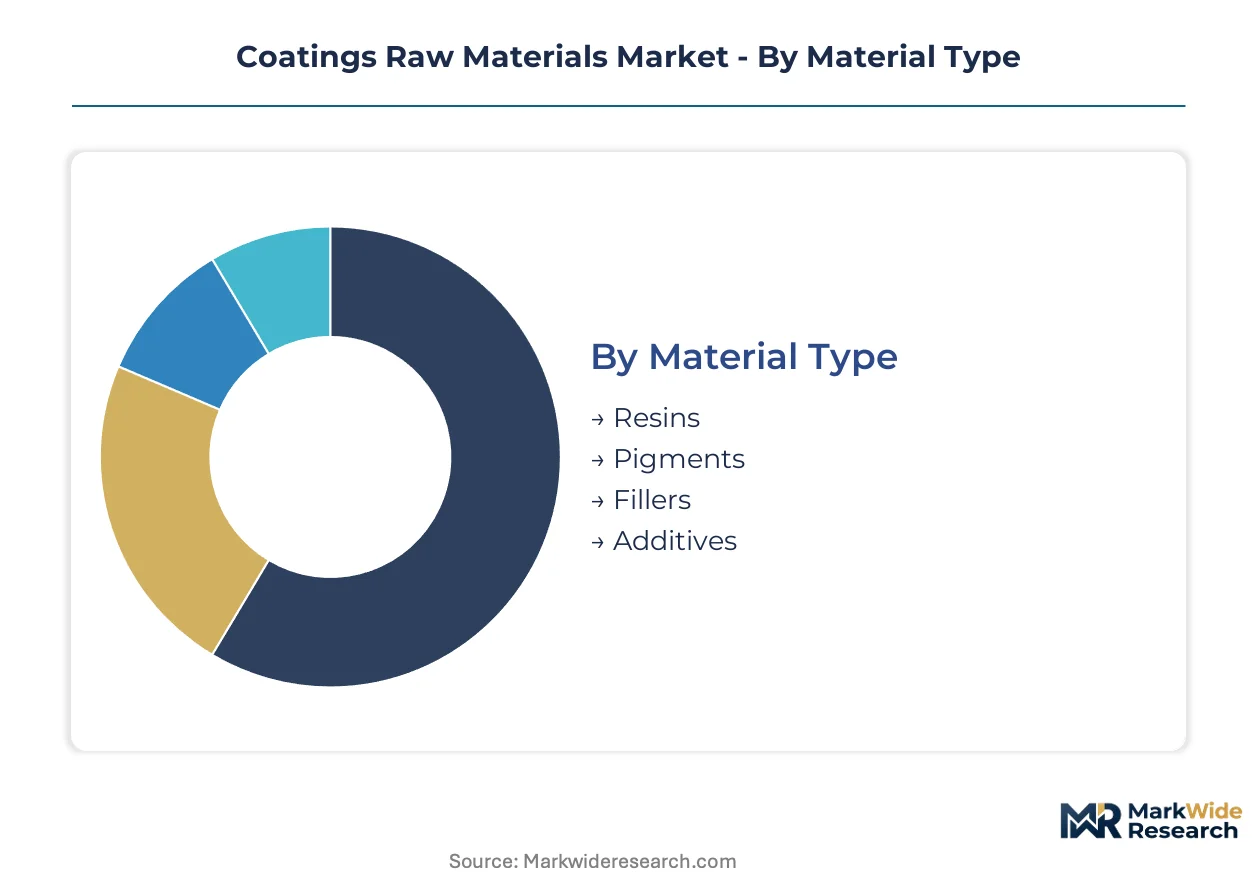
Coatings raw materials segment along functional chemistry, cure mechanism, end-use specification, and application environment. Each axis determines margin capture, regulatory exposure, and supply chain configuration differently.
Material Type:
Resins function as standalone film-formers requiring additive packages, while pigments and fillers embed into resin matrices as performance modifiers.
- Resins:Epoxy, polyurethane, acrylic, and alkyd polymers constitute the continuous phase determining adhesion, flexibility, and chemical resistance. Automotive OEM clearcoat specifications in Germany and Japan are concentrating consumption of aliphatic polyurethane resins for weathering durability. REACH authorization deadlines are accelerating substitution toward water-borne acrylic dispersions.
- Pigments:Titanium dioxide, iron oxides, and organic colorants provide opacity, UV absorption, and aesthetic control. Construction coating demand in China and India absorbs the majority of commodity TiO2 volumes, though sulfate-process chloride-grade differentials are widening on energy-cost disparities.
- Fillers:Calcium carbonate, talc, and silica extend volume, control rheology, and reduce raw material costs. These materials embed universally across formulation types with limited standalone specification.
- Additives:Defoamers, dispersants, and rheology modifiers fine-tune application properties and shelf stability. Fluorosurfactant shortages are constraining high-performance water-borne architectural coating production.
Resins lead volumes today; additives are gaining share fastest on formulation complexity premiums.
Formulation Type:
Cost tiers separate legacy solvent systems from compliant alternatives, with cure energy and capital intensity as secondary differentiators.
- Solvent-Based:Traditional alkyd and nitrocellulose systems in hydrocarbon carriers deliver fast dry and substrate tolerance. EPA VOC limits and China MEE emissions standards are compressing permissible applications to specialized industrial maintenance where cure speed overrides compliance.
- Water-Based:Acrylic and polyurethane dispersions in aqueous media satisfy regulatory limits with reformulated rheology packages. Construction and furniture finishing in California and EU member states are redirecting volume here ahead of Rule 1113 and REACH sunset dates.
- Powder Coating:Thermoset resins applied electrostatically and cured at elevated temperature eliminate VOCs entirely. Automotive under-hood components and appliance exteriors in Mexico and Turkey absorb volume where thermal tolerance permits.
- UV-Curable:Acrylate oligomers photopolymerize on demand for line-speed-sensitive operations. Flat-line wood finishing in Italy and electronics conformal coating in South Korea justify premium oligomer positioning through energy-cure efficiency.
Solvent-based retains volume leadership; UV-curable is expanding most quickly in premium niches.
End Use Industry:
Application environments dictate performance specifications, with automotive and aerospace demanding embedded systems versus construction and furniture permitting standalone material selection.
- Automotive:OEM assembly and refinish operations specify multi-layer systems with precise color matching and chip resistance. Aliphatic isocyanate consumption concentrates here for clearcoat durability under UV and chemical exposure.
- Construction:Architectural and protective coatings for infrastructure and buildings prioritize cost efficiency and weatherability. China's domestic property development and India's PLI-scheme manufacturing expansion are absorbing industrial coating precursor volumes.
- Furniture:Wood finishing for residential and commercial fixtures balances aesthetic depth with production throughput. UV-curable segments are displacing conventional acid-cured systems in European flat-line operations.
- Aerospace:MRO and OEM applications demand chromate-free pretreatments and high-solids polyurethane topcoats for fuel resistance and rain erosion protection. Specification authority rests with Boeing and Airbus tiered supplier qualifications.
Construction leads volumes today; aerospace is climbing the fastest on specification premium capture.
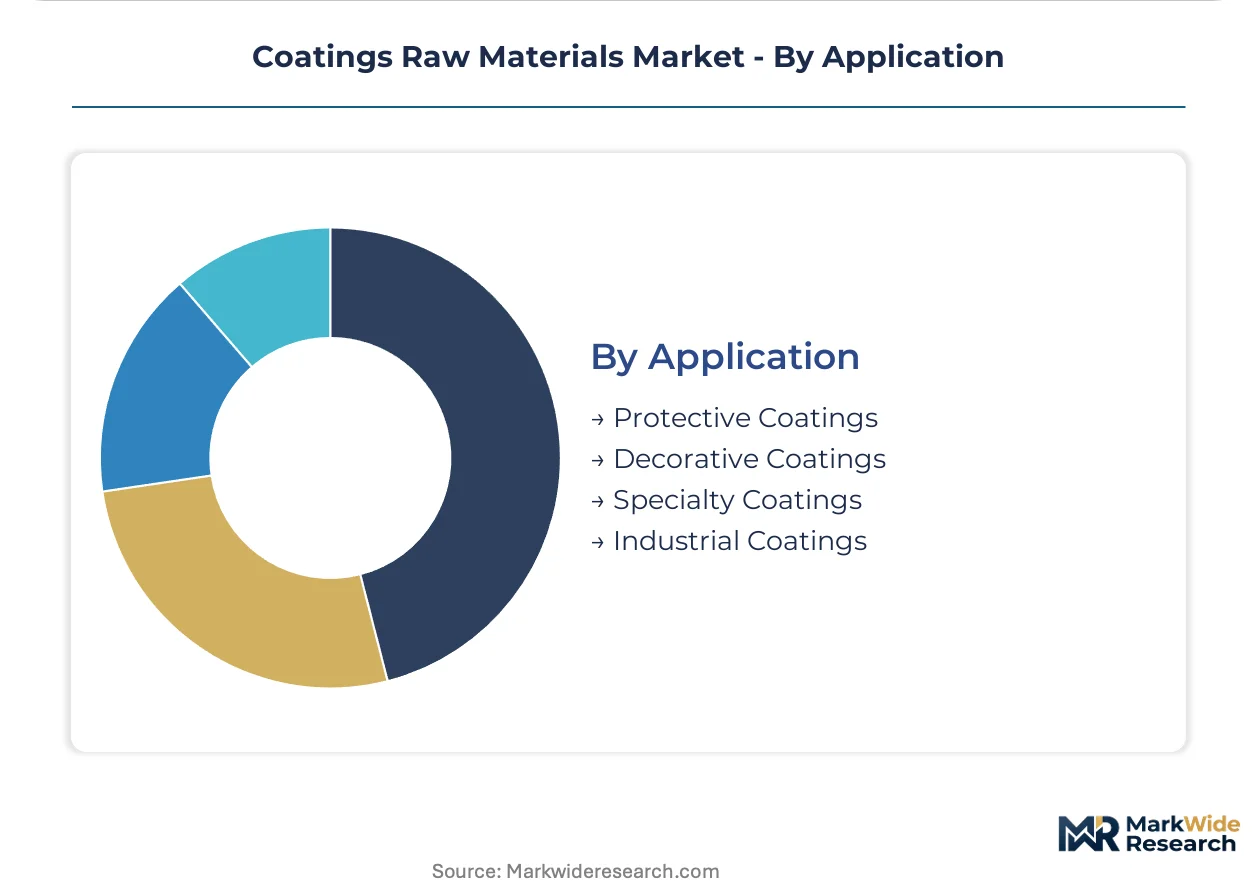
Application:
Customer type separates specification-driven industrial buyers from price-sensitive decorative purchasers, with protective coatings bridging both segments.
- Protective Coatings:Heavy-duty systems for bridges, pipelines, and marine structures prioritize corrosion inhibition over aesthetics. Offshore wind installations in the North Sea and Gulf of Mexico are specifying epoxy and glass-flake reinforced systems for splash-zone durability.
- Decorative Coatings:Architectural paints and wood stains emphasize color retention and application ease. DIY retail channels in the United States and professional painting contractors in France drive formulation standardization.
- Specialty Coatings:Functional layers for electronics, medical devices, and optical applications require precise thickness control and dielectric properties. Conformal coating for PCBs in Taiwan and South Korea consumes specialized acrylic and silicone formulations.
- Industrial Coatings:General manufacturing finishes for machinery, appliances, and metal fabrication balance cost and appearance. Appliance manufacturers in Mexico and Turkey are converting from liquid to powder systems on line efficiency gains.
Decorative coatings lead volumes today; specialty coatings are gaining share fastest on functional premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European coatings raw material consumption through integrated petrochemical refining and automotive OEM assembly density.
China
Construction activity in the Yangtze River Delta and Pearl River Delta sustains heavy consumption of industrial coating precursors for infrastructure and export manufacturing. MEE emissions standards redirect local production toward water-borne resin systems and powder coating architectures. Shanghai and Guangdong province concentrate domestic formulation capacity serving appliance and automotive tier suppliers.
Germany
Automotive OEM clearcoat specifications from Stuttgart and Munich elevate aliphatic isocyanate consumption for weathering durability. REACH authorization deadlines accelerate substitution programs toward compliant water-borne acrylic dispersions. The Cologne-Leverkusen chemical cluster hosts integrated epoxy and polyurethane intermediate production captive to major formulators.
United States
EPA VOC regulations and California SCAQMD Rule 1113 compress solvent-borne architectural coating limits ahead of staggered compliance deadlines. Automotive refinish operations in Michigan and Ohio specify multi-layer systems with precise color matching requirements. Gulf Coast petrochemical infrastructure supplies propylene oxide and naphtha derivatives to specialty resin producers.
India
PLI scheme incentives for domestic manufacturing expand protective coating demand across Maharashtra and Gujarat industrial zones. Local resin compounding capacity lags consumption growth, creating import substitution openings for compliant water-borne systems. The Delhi-Mumbai Industrial Corridor concentrates new appliance and automotive component fabrication requiring industrial finishes.
Japan
Automotive OEM assembly lines in Aichi and Kanagawa prefectures specify high-durability clearcoat systems for export vehicle production. METI guidelines on chemical emissions influence formulator R&D priorities toward low-VOC alternatives. The Keihin industrial zone maintains specialized isocyanate handling and distribution infrastructure for refinish and assembly applications.
Coatings Raw Materials Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based feedstock certification and regional compounding partnerships. The market structure concentrates around integrated petrochemical players with captive intermediate production and specialty resin houses with formulation expertise. Three archetypes dominate: backward-integrated chemical conglomerates, technology-focused isocyanate specialists, and regional distribution-anchored compounders. Competitive moves center on long-term offtake agreements for supply security and biorefinery partnerships for sustainability qualification.
Among European-integrated chemical producers, BASF SE and Covestro AG exemplify the backward-integrated archetype with captive production of epoxy and polyurethane intermediates. PPG Industries anchors North American supply relationships through direct procurement arrangements with specialty chemical partners. These three companies represent distinct competitive positioning: BASF through petrochemical network integration, Covestro through aliphatic isocyanate technology leadership, and PPG through automotive refinish channel consolidation.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| The Sherwin-Williams Company |
| BASF SE |
| RPM International Inc. |
| Nippon Paint Holdings Co., Ltd. |
| Covestro AG |
| Axalta Coating Systems |
| Jotun |
| PPG Industries, Inc. |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon-border adjustment mechanisms gate qualified supply and premium-tier pricing access for coatings raw materials, as bio-based feedstock certification becomes a contract pre-qualification requirement and low-carbon resin architectures command pricing premiums over conventional petrochemical alternatives.
Pricing Analysis
Epoxy and polyurethane intermediate pricing tracks naphtha and propylene oxide swings, with cost pass-through varying by backward integration depth. Three-tier pricing structure across premium certified-bio, standard compliant, and economy solvent-based levels separates qualified from conventional supply. Pricing pressure stems from REACH authorization deadlines accelerating substitution timelines. Automotive OEMs exhibit lowest price sensitivity due to specification lock-in, while construction contractors face acute cost compression.
Supply Chain Analysis
Aliphatic isocyanate supply rests on German and Chinese specialty chemical producers, with HDI production clustering around Leverkusen and Shanghai. Epoxy intermediates draw from Gulf Coast propylene oxide and Rhine-Ruhr naphtha derivatives. Single-source vulnerability for automotive clearcoat-grade inputs creates geographic concentration risk. Distribution runs through direct long-term offtake agreements bypassing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, as automotive OEM specification pull toward high-durability clearcoat systems concentrates demand among qualified resin suppliers with proven weathering performance.
For Market Incumbents: Anchor supply security through captive isocyanate production or locked-in offtake agreements with specialty chemical partners. Defend against bio-based entrants by accelerating water-borne acrylic dispersion R&D ahead of REACH sunset dates. Prioritize certification investment for EU CBAM eligibility to maintain premium-tier pricing access. For New Entrants and Emerging Players: Digital color-matching platforms and modular additive dosing systems offer channel routes into mid-tier formulator relationships. Target India's PLI-scheme manufacturing expansion where local resin compounding capacity lags consumption. Pursue biorefinery partnerships in Brazil or Scandinavia for feedstock security and sustainability scorecard qualification. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distribution-anchored compounders lacking backward integration. Five-to-ten-year viability favors technology-focused isocyanate specialists with automotive OEM qualification. Watch bio-based feedstock certification scheme adoption rates as the inflection signal for contract eligibility shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive epoxy and polyurethane intermediate production insulates margin from naphtha volatility. |
| Long-term Supply Agreement | Direct offtake contracts with automotive OEMs lock in volume through tiered supplier qualifications. |
| Green Manufacturing Transition | Water-borne and powder coating architectures satisfy EPA VOC and China MEE compliance deadlines. |
| Joint Venture | Regional biorefinery partnerships in Brazil and Scandinavia secure localized bio-epoxy feedstock streams. |
| Capacity Expansion | India domestic compounding capacity additions capture PLI-scheme protective coating demand growth. |
Methodological Framework
Multiple input streams — technical R&D directors at resin producers, procurement leads at automotive OEMs, distribution channel partners, and regulatory affairs specialists — were reconciled against secondary validation from customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA VOC regulation filings. Bottom-up volume modeling across resin type, formulation chemistry, and end-use industry segments was triangulated with top-down macroeconomic drivers.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled included material chemistry tier, cure mechanism, end-use specification intensity, and regional production hub classification. CAGRs were derived from fitted growth curves applied to baseline consumption data, with forecast inputs incorporating REACH authorization timelines and automotive platform electrification content shifts.
The model assumes a particular technology adoption path; alternative pathways for UV-curable oligomer penetration would alter the outlook for conventional liquid system demand. Forecasts reflect assumptions about regulatory compliance deadlines and bio-based feedstock scale-up timelines. A small set of triggers — carbon-border adjustment mechanism enforcement intensity, isocyanate supply disruption events, and water-borne formulation chemist availability — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
United States Automotive OEM Coatings Market
Coatings
Metallic Powder Coating Market
Coatings
Asia-Pacific Marine Coatings Market
Coatings
Coating Thickness Gauge Market
Coatings
Wire Enamels Market
Coatings
Bio-Based Coatings Market
Coatings
Mexico Protective Coatings Market
Coatings
Polyurethane Powder Coatings Market
Coatings
Perfluoroalkoxy (PFA) Coatings Market
Coatings
South Korea Marine Coatings Market
Coatings
Global PET Film Coated Steel Coil Market
Coatings
Coated Casing Market
Coatings
Superhydrophobic Coatings Market
Coatings
United Kingdom Protective Coatings Market
Coatings
Conductive Polymer Coatings Market
Coatings
Europe Powder Coatings Market