
 Steel Ingots Market | 2026-2036
Steel Ingots Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Ingots Market Intelligence
Direct mill-to-fabricator procurement is tilting as large steelmakers bypass traditional traders. ArcelorMittal controls integrated supply routes from European blast furnaces to automotive-tier rolling mills. Tata Steel Group anchors South Asian distribution through captive ports and rail-linked stockyards. Nippon Steel Corporation leverages high-purity vacuum-degassed ingot output for specialty machinery contracts.
Steel ingots are semi-finished cast metal blocks produced by pouring molten steel into molds, typically ranging from 0.5 to 40 tonnes, with carbon content varying by grade to determine tensile strength and weldability. These ingots serve as feedstock for rolling, forging, or extrusion into structural shapes, engine components, and rail profiles. Carbon steel ingots dominate volume flows for construction rebar and plate production, while alloy steel grades command margin premiums in crankshaft and turbine shaft applications. Stainless steel ingots in slab form feed cold-rolling lines for chemical processing equipment and marine fittings.
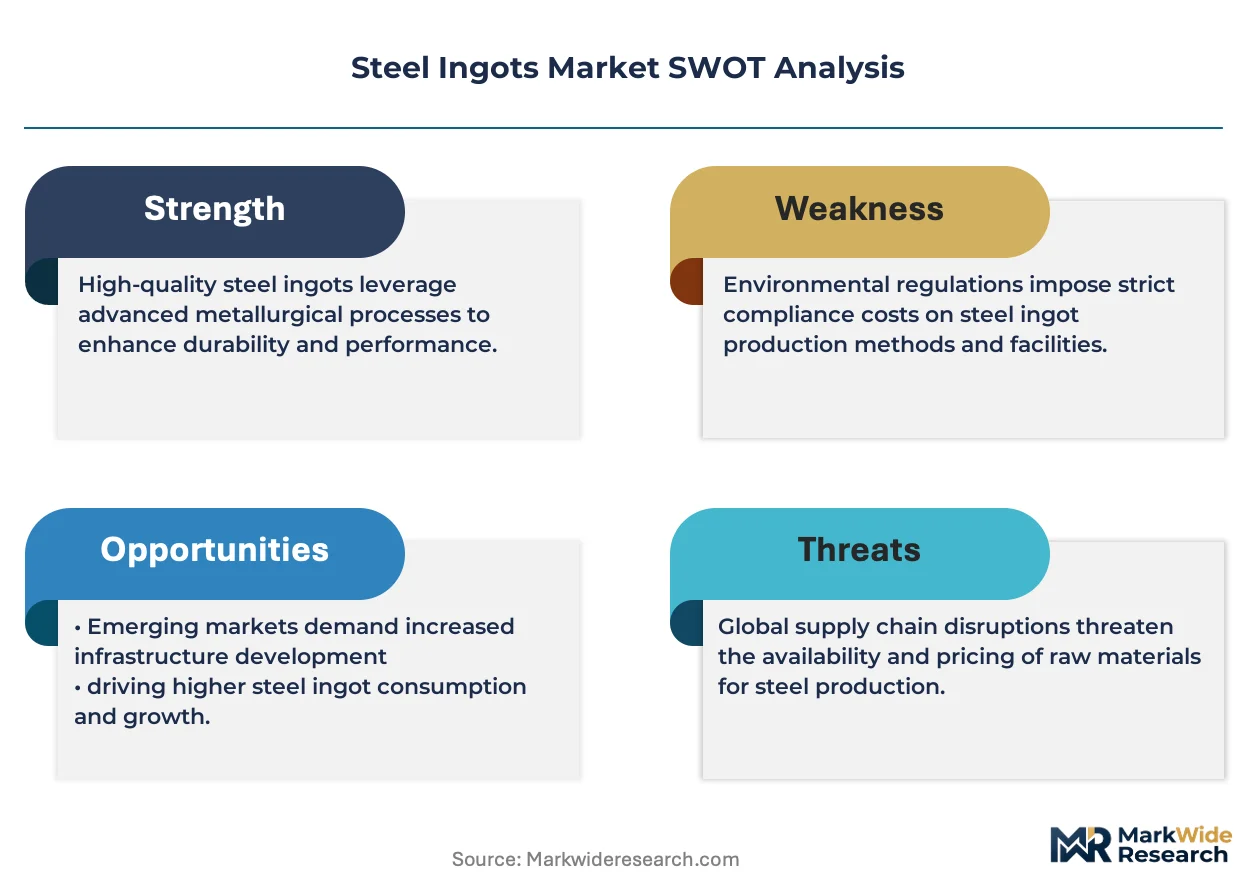
EPA emissions rules and OSHA workplace exposure limits tighten particulate and silica standards at US melt shops, raising compliance costs for basic oxygen furnace operators. REACH substance restrictions and the EU Green Deal carbon border adjustment mechanism reshape import competitiveness for non-European ingot suppliers. Stakeholders must track which regulatory jurisdiction—Washington, Brussels, or Beijing—sets the binding standard for their export destinations.
Market Dynamics
China's dual carbon goals and MEE emissions protocols are forcing a wholesale shift from blast furnaces to electric-arc furnace capacity, compressing the traditional integrated mill model while fragmenting supply routes toward scrap-fed mini-mills and direct-reduction iron pathways.
Growth Catalysts
- India's BIS certification mandate:Domestic railway and shipbuilding expansion requires certified alloy steel ingots, pulling capacity toward high-margin grades and away from commodity carbon steel.
- MEE emissions enforcement:Stricter protocols in China are accelerating EAF investments, creating demand for high-quality scrap and direct-reduced iron feedstocks that favor specialized ingot producers.
- Automotive lightweighting:Advanced high-strength steel requirements for electric vehicle chassis and battery enclosures are expanding vacuum-degassed and micro-alloyed ingot specifications.
Market Restraints
- Scrap supply concentration:Premium scrap grades cluster in developed economies with mature recycling infrastructure, limiting EAF expansion in emerging markets lacking feedstock security.
- Iron ore price volatility:Blast furnace operators face margin compression from seaborne ore cost swings, discouraging capital commitment to long-asset replacement cycles.
- Carbon border friction:The EU Green Deal carbon border adjustment mechanism disadvantages non-European ingot suppliers lacking verified emissions accounting systems.
Strategic Opportunities
- Southeast Asia infrastructure buildout:Vietnam, Indonesia, and the Philippines are expanding port, rail, and power generation capacity, opening demand for construction-grade carbon steel ingots.
- Hydrogen-based direct reduction:Convergence of green hydrogen production with shaft furnace technology enables near-zero-carbon steelmaking for premium automotive and machinery contracts.
- Mill-to-fabricator digital platforms:Blockchain-tracked ingot provenance and specification matching are bypassing traditional trader intermediaries in European and North American supply chains.
Industry Challenges
- EAF metallurgical expertise shortage:The shift from basic oxygen furnace operations requires scarce electrical engineers and scrap chemists capable of managing variable feedstock compositions.
- Multi-jurisdiction certification lag:Ingot producers seeking automotive-tier contracts must simultaneously satisfy IATF 16949, ISO 14001, and customer-specific material approvals, extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Ingots Market |
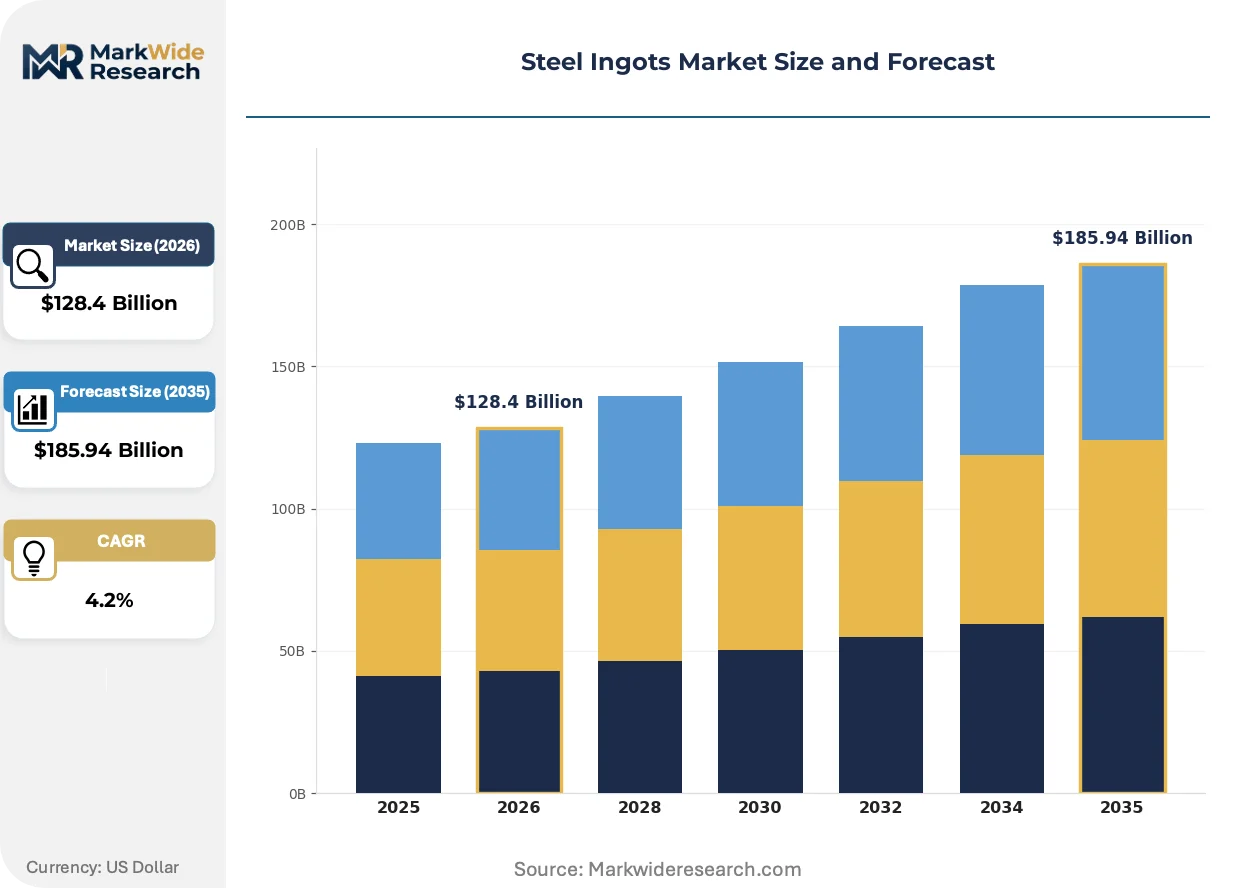
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $185.94 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Steel, Alloy Steel, Stainless Steel, Tool Steel Form: Blooms, Billets, Slabs, Bars Application: Construction, Shipbuilding, Machinery Manufacturing, Railways End User Industry: Manufacturing Plants, Foundries, Metal Fabricators, Engineering Workshops |
| Companies Covered | POSCO Holdings, Ansteel Group, China Baowu Group, Shagang Group, HBIS Group, ArcelorMittal, Tata Steel Group, Jianlong Group, Nippon Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Ingots Market Strategic Shifts & Innovations
Digital thread technologies and green metallurgy pathways are compressing traditional production cycles while fragmenting long-established supply hierarchies between integrated mills and specialized mini-mill operators.
Continuous casting near-net-shape technology is collapsing the conventional ingot-to-slab-to-coil processing chain. Automotive tier-one suppliers in Germany and Japan are adopting thin-slab casting that bypasses ingot stages entirely for standard grades, compressing lead times from weeks to days while reducing energy intensity by eliminating reheating cycles.
The EU Green Deal carbon border adjustment mechanism is reshaping import competitiveness for Turkish, Russian, and Ukrainian ingot suppliers. Non-European producers must now deploy verified emissions monitoring systems and secure third-party carbon intensity certifications to maintain access to German and Italian rolling mills, with compliance costs favoring larger integrated operators over trading intermediaries.
Direct mill procurement contracts are displacing spot-market trader intermediation in North American and European supply chains. Large fabricators and rolling mills are establishing multi-year offtake agreements with specific melt shops, with contract structures now incorporating carbon intensity clauses and scrap-content minimums that favor EAF-based suppliers in Ohio and northern Italy.
Steel Ingots Market Segmentation
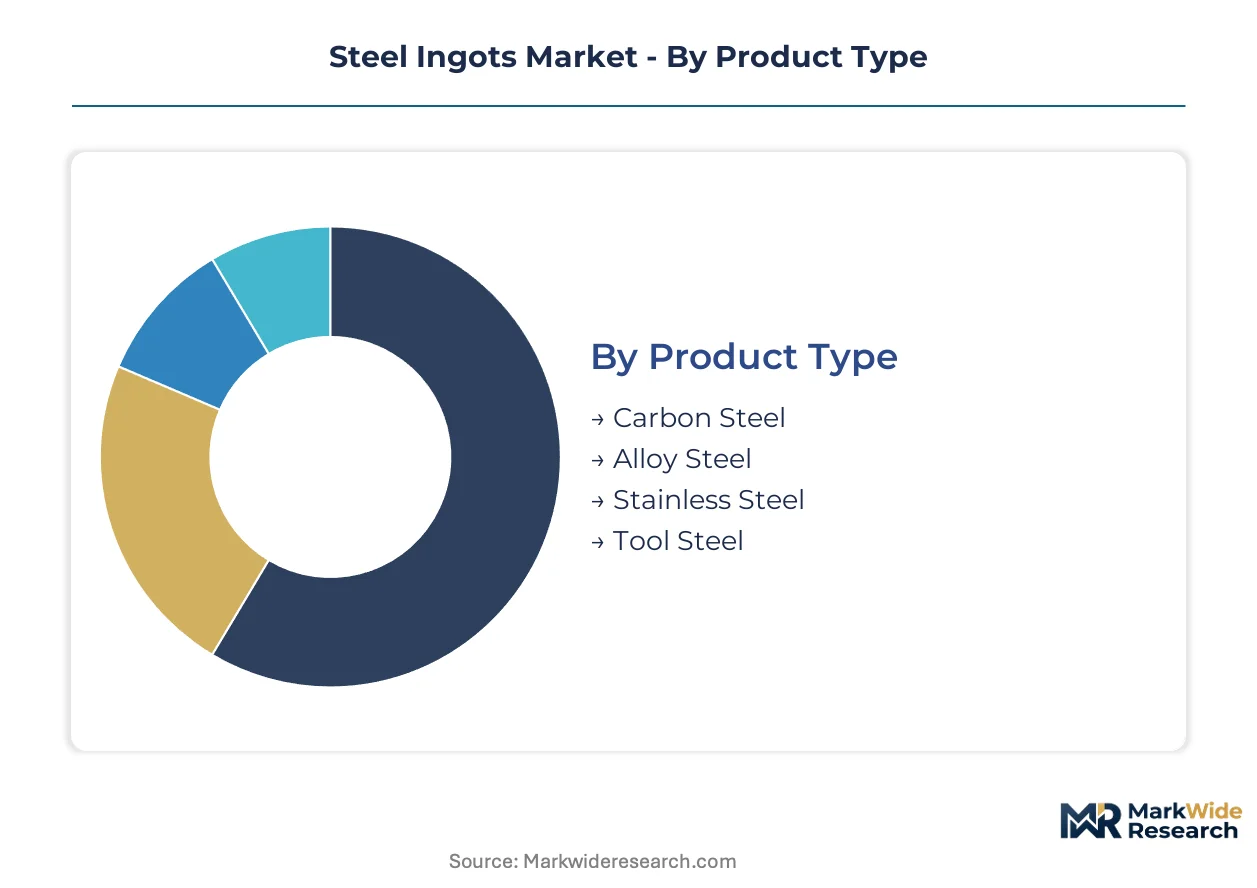
Steel ingot segmentation determines procurement cycles, margin structures, and metallurgical qualification pathways. Buyers select grades based on end-use performance requirements rather than commodity pricing alone.
Product Type:
Carbon steel ingots turn inventory fastest through construction rebar mills, while tool steel grades sit in specification queues for months awaiting aerospace-tier approvals.
- Carbon Steel:Basic grades with carbon content below 0.25% dominate volume flows for structural rebar and plate production. Indian BIS-certified producers feed railway expansion with medium-carbon variants, though margin compression from scrap-fed EAF competition limits pricing power.
- Alloy Steel:Chromium, nickel, and molybdenum additions deliver tensile strength above 800 MPa for crankshaft and turbine shaft applications. Vacuum-degassed specifications from Japanese producers command qualification premiums in German automotive-tier contracts.
- Stainless Steel:Slab-form ingots with 10.5% minimum chromium feed cold-rolling lines for chemical processing equipment.
- Tool Steel:High-speed and cold-work grades with tungsten and vanadium carbides serve die and cutting tool manufacturers.
Carbon steel dominates installed base. Alloy steel is where expansion concentrates.
Form:
Cost tiers separate continuous-cast near-net shapes from traditional ingot remelting, with slab premiums reflecting energy savings in downstream rolling.
- Blooms:Rectangular cross-sections above 200mm thickness serve heavy forging presses for rail wheels and marine crankshafts. German and Italian rolling mills source blooms from integrated blast furnace routes to meet ultrasonic testing requirements for wind turbine shafts.
- Slabs:Wide rectangular castings feed hot-strip mills for automotive body panels and appliance-grade cold-rolled sheet. Thin-slab casting adoption in Ohio and northern Italy collapses traditional ingot-to-slab processing chains, eliminating reheating energy costs.
- Billets:Smaller square sections below 150mm drive wire rod and rebar production.
- Bars:Rolled or cast rounds supply machine shops and forging operations directly.
Slabs capture the highest value per tonne. Billets move the largest absolute tonnage.
Application:
Customer type determines specification stringency, with automotive and aerospace buyers imposing IATF 16949 traceability that commodity construction buyers waive.
- Construction:Rebar and structural plate specifications tolerate wider chemistry bands, enabling scrap-fed EAF producers to compete on cost. Southeast Asian port and power projects in Vietnam and Indonesia pull carbon steel blooms from Chinese and Indian suppliers.
- Railways:Wheel and axle grades require vacuum degassing and sulfur below 0.015% for fatigue resistance. Indian Railways' dedicated freight corridors and high-speed line expansion consume alloy steel billets from domestic BIS-certified melt shops.
- Shipbuilding:Hull plate and marine shaft grades demand through-thickness ductility certification.
- Machinery Manufacturing:Gear, bearing, and hydraulic cylinder producers specify micro-alloyed grades for as-forged properties.
Construction absorbs the highest volume. Railways present the steepest expansion trajectory.
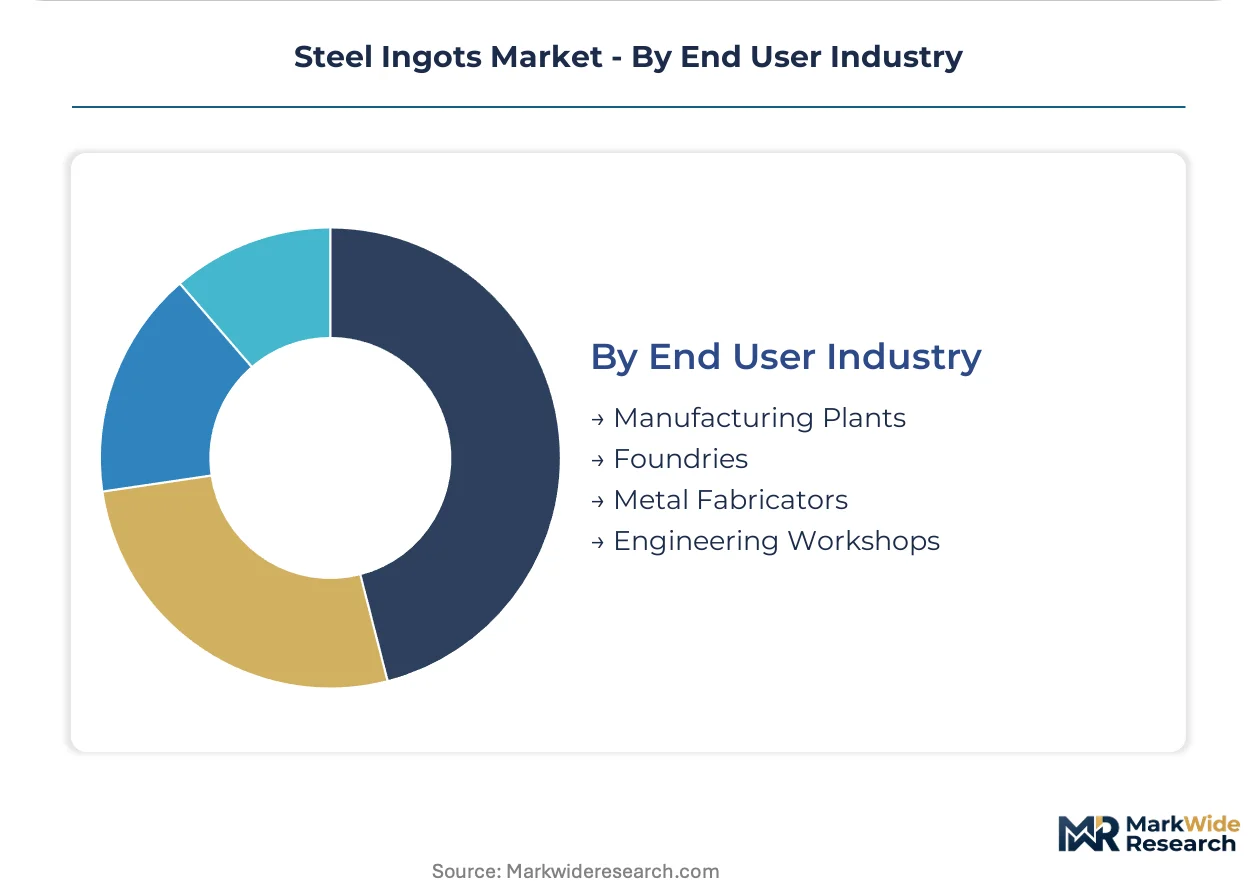
End User Industry:
Supply concentration varies by buyer scale, with integrated mills capturing foundry demand through captive forging divisions while independent fabricators source through distributor networks.
- Manufacturing Plants:Tier-one automotive and machinery producers establish direct mill contracts with carbon intensity clauses and scrap-content minimums. ArcelorMittal and Tata Steel anchor these relationships through rail-linked stockyards and port terminals.
- Metal Fabricators:Job shops and structural steel contractors purchase standard grades through distributor channels with shorter lead times and smaller minimum order quantities.
- Foundries:Investment and sand casting operations source remelt-grade ingots for complex near-net shapes.
- Engineering Workshops:Maintenance and repair operations consume small-lot specialty grades for replacement components.
Manufacturing plants drive contract innovation. Metal fabricators sustain spot-market liquidity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward Indian BIS-certified producers feeding railway expansion, while Chinese mills absorb margin compression from MEE emissions compliance costs and EAF conversion investments.
China
Blast furnace operators in Hebei and Jiangsu provinces face forced EAF conversions under MEE emissions protocols. The dual carbon goals mandate scrap-fed capacity expansion, fragmenting traditional integrated mill dominance toward mini-mill clusters. Tangshan steel corridor mills redirect alloy ingot output toward domestic automotive and machinery contracts.
India
Domestic railway and shipbuilding expansion consumes BIS-certified alloy steel ingots from Jharkhand and Odisha melt shops. Dedicated freight corridors and high-speed line projects pull capacity toward vacuum-degassed grades. Jamshedpur and Rourkela industrial clusters anchor captive supply routes through rail-linked stockyards.
Japan
Automotive lightweighting requirements from Toyota and Honda expand vacuum-degassed ingot specifications for electric vehicle chassis. METI industrial policy supports hydrogen-based direct reduction pilots. Chubu and Kansai manufacturing belts concentrate high-purity output for specialty machinery and turbine shaft contracts.
Germany
EU Green Deal carbon border adjustment mechanism disadvantages Turkish and Russian ingot suppliers lacking verified emissions accounting. Thyssenkrupp and Salzgitter mills source blooms for wind turbine shafts through ultrasonic-tested supply chains. Ruhr Valley and Bremen port clusters integrate blockchain-tracked provenance systems for automotive-tier contracts.
United States
EPA emissions rules and OSHA silica standards raise compliance costs for basic oxygen furnace operators in Ohio and Indiana. Direct mill procurement contracts displace spot-market traders, with carbon intensity clauses favoring EAF-based suppliers. Great Lakes and Ohio Valley mini-mills capture construction rebar demand through scrap-fed production.
Steel Ingots Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream. The steel ingots sector structures around three tiers: integrated blast furnace operators with captive mining and rolling assets, scrap-fed EAF mini-mills with regional feedstock advantages, and specialty alloy producers with vacuum-degassing capabilities. Strategic moves concentrate on EAF capacity conversion in China, hydrogen-based direct reduction pilots in Europe, and BIS certification investments in India. Geographic expansion and carbon intensity verification dominate competitive positioning.
Among Asian integrated operators, China Baowu Group and Ansteel Group exemplify state-backed consolidation archetypes with blast furnace-to-rolling mill control. POSCO Holdings anchors the Korean position through specialized alloy output. ArcelorMittal and Tata Steel Group represent Western and South Asian platform integrators with port-terminal and rail-linked distribution infrastructure. Nippon Steel Corporation occupies the high-purity specialty tier serving German and Japanese automotive contracts.
| Leading Market Players |
|---|
| POSCO Holdings |
| Ansteel Group |
| China Baowu Group |
| Shagang Group |
| HBIS Group |
| ArcelorMittal |
| Tata Steel Group |
| Jianlong Group |
| Nippon Steel Corporation |
| Others |
Cost & Logistics Intelligence
Blast furnace undercapacity in Hebei province drives divergent supplier behavior, with integrated mills extracting alloy-grade premiums while scrap-fed EAF operators absorb carbon steel margin compression. This utilization gap feeds directly into pricing posture, as certificate-backed Indian producers command railway contract premiums while Chinese mills discount commodity grades to maintain operating rates.
Pricing Analysis
The customization-premium spread between vacuum-degassed alloy specifications and standard carbon grades now exceeds the historical band, with IATF 16949-certified output from Japanese melt shops capturing automotive-tier premiums against commodity billet spot markets. Price differentiation hinges on BIS certification status and sulfur content guarantees, with Indian railway procurement imposing the strictest chemistry bands. Cost compression in Chinese carbon steel intensifies because MEE compliance investments raise fixed costs without corresponding quality premiums. Construction fabricators in Southeast Asia exhibit highest price sensitivity, while German wind turbine shaft buyers waive cost concerns for ultrasonic-tested bloom supply.
Supply Chain Analysis
Tariff exposure between Turkish suppliers and German rolling mills dominates supply chain risk planning, as EU Green Deal carbon border adjustments fragment traditional Black Sea export routes. Geographic supply concentration centers on China, India, and Japan, with Hebei and Jiangsu provinces anchoring integrated capacity and Jharkhand feeding domestic alloy demand. Raw material dependencies draw from seaborne iron ore, premium scrap grades clustered in developed economies, and direct-reduced iron pilot volumes. Single-source vulnerability persists in high-purity vacuum-degassed output, where Chubu and Kansai manufacturing belts control automotive-tier qualification pathways. Distribution runs through mill-to-fabricator digital platforms bypassing trader intermediaries in European and North American corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steel ingot procurement is transitioning toward platform-economics dynamics, with blockchain-tracked provenance systems and carbon-intensity scoring creating interoperability layers that favor integrated operators over fragmented trader networks.
For Market Incumbents: Insulate alloy-grade margin pools by accelerating BIS certification investments in Jharkhand and Odisha melt shops before Indian railway expansion peaks. Defensive consolidation should target captive scrap collection networks in Ohio and northern Italy, where EAF feedstock security determines operating continuity against emerging mini-mill competition.
For New Entrants and Emerging Players: Establish a beachhead in Southeast Asian construction-grade billet supply, where Vietnamese and Indonesian port expansion outpaces domestic melt shop capacity. Hydrogen-based direct reduction pilots in Europe present the most penetrable technology entry point, with automotive-tier offtake agreements offering qualification pathways that bypass traditional integrated mill dominance.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across EAF conversion projects, favoring scaled operators with existing grid infrastructure and scrap logistics. Long-term viability over the next decade rests on carbon intensity verification capabilities and multi-jurisdiction certification holdings. Acquisition targets should display verified emissions accounting systems and IATF 16949 automotive-tier approvals. The signal to watch is EU carbon border adjustment enforcement stringency against Turkish and Russian suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| EAF Capacity Conversion | China's MEE protocols force scrap-fed investments that fragment traditional blast furnace dominance in Hebei. |
| BIS Certification Investment | Indian railway expansion pulls capacity toward certified alloy grades with premium pricing power. |
| Hydrogen Direct Reduction Pilot | Green hydrogen convergence enables near-zero-carbon output for German automotive-tier contracts. |
| Mill-to-Fabricator Digital Platform | Blockchain-tracked provenance bypasses trader intermediaries in European supply chains. |
| Captive Scrap Collection Network | Feedstock security determines EAF operating continuity in Ohio Valley mini-mill corridors. |
Research Approach
Cross-validation between melt shop operating data and customs trade records anchors the qualitative findings in this steel ingots analysis. Primary interviews with plant managers at integrated blast furnace operators, procurement leads at German automotive-tier rolling mills, scrap collection network coordinators, and technical R&D directors at EAF conversion projects informed capacity and specification trends. Secondary validation drew from SEC filings of listed steel producers, Chinese MEE emissions disclosure databases, Indian BIS certification registries, and EU carbon border adjustment mechanism draft regulations. Bottom-up capacity modeling triangulated against top-down apparent steel consumption estimates across the analysis window.
Calibration against historical capacity utilization rates and price spread dynamics shaped the projection framework across the modeling period. Segmentation dimensions included product type tier, end-use application stringency, regional regulatory cluster, and feedstock route. CAGRs derived from fitted growth curves applied to certified alloy grade expansion and EAF capacity replacement cycles. Industry-specific forecast inputs incorporated MEE enforcement timelines, Indian railway procurement schedules, and EU carbon border adjustment phase-in assumptions.
Sensitivities concentrate around Chinese emissions policy enforcement intensity, Indian infrastructure execution pace, and scrap supply availability in emerging markets. Forecasts reflect documented assumptions regarding technology adoption curves and regulatory implementation schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Industrial Metal Strips Market
Metals
Nickel Sulfate Market
Metals
Iron Ore Market
Metals
Europe Metal Service Centers Market
Metals
Aluminum Wire Market
Metals
Aluminum Smelting Market
Metals
Metal Injection Molding (MIM) Parts Market
Metals
Aluminum Flat Products Market
Metals
North America Electrical Steel Market
Metals
Global Metal and Metal Manufactured Products Market
Metals
Copper Smelting Market
Metals
Clutch Spring Wires Market
Metals
Osmium Market
Metals
Ferrosilicon Magnesium Market
Metals
Global Tin Market
Metals
Global Aluminum Extruded Products Market