
 GCC Aluminium Cans Market | 2026-2036
GCC Aluminium Cans Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Aluminium Cans Market Intelligence
Market Context
Skilled aluminium metallurgist availability is rotating from legacy construction applications toward beverage packaging specialization across Gulf states. Crown Holdings, Inc. leverages its regional manufacturing footprint to supply major beverage bottlers with lightweight two-piece can bodies. SAPIN anchors domestic production capacity through its Bahrain and Saudi facilities, reducing import dependency for GCC beverage brands. Ball Corporation differentiates via advanced printing and shaping technologies that support brand differentiation on retail shelves.
Technical Definition and Segment Structure
GCC aluminium cans are cylindrical single-serve containers fabricated from aluminium alloy 3104-H19 or 3004-H19, typically 0.097 mm thick in the body wall, engineered to withstand internal pressures exceeding 90 psi while remaining fully recyclable through remelt processes. Soda cans dominate current volume flows across retail and convenience store channels, reflecting the region's high per-capita carbonated beverage consumption. Beer cans represent a structurally constrained but premium-margin segment shaped by licensing frameworks in select emirates. The 330ml capacity tier captures the largest share of food service and retail transactions, while 500ml formats gain traction in e-commerce bulk purchasing.
Regulatory Framework and Outlook
Saudi Standards, Metrology and Quality Organization (SASO) technical regulations govern food-contact material migration limits and dimensional tolerances for domestically distributed cans. UAE's Ministry of Industry and Advanced Technology enforces conformity assessment protocols through the Emirates Conformity Assessment Scheme (ECAS) for imported aluminium packaging. Gulf Cooperation Council standardization initiatives are harmonizing cross-border material certification requirements. Stakeholders must monitor evolving extended producer responsibility frameworks and deposit-return scheme pilots across multiple emirates and kingdom provinces.
Market Dynamics
Domestic recycling mandates across Gulf Cooperation Council member states are compressing supply chains toward localized circular material flows, forcing beverage packaging converters to reconfigure procurement strategies around remelt alloy availability rather than primary aluminium imports.
Growth Catalysts
- Deposit-return scheme pilots:Multiple emirates are testing container recovery infrastructure that incentivizes closed-loop aluminium circulation. Beverage bottlers anticipate material cost stabilization through captive scrap streams.
- Carbonated soft drink bottling clusters:Concentrated production facilities in Saudi Arabia's Eastern Province generate economies of scale in can procurement. Regional co-location reduces logistics expenditure per thousand units.
- Lightweighting process advances:Body wall thickness reduction below 0.097 mm is cutting alloy input per can. Rolling mills serving GCC markets are retooling for higher-strength 3104-H19 temper specifications.
Market Restraints
- Primary aluminium ingot price volatility:London Metal Exchange fluctuations transmit directly to can body material costs. Regional converters lack hedging depth against commodity swings.
- Domestic rolling capacity concentration:GCC beverage can sheet supply depends on a limited set of regional flat-rolled aluminium producers. Bottlers face single-source risk for alloy 3004-H19 coil.
- Glass bottle substitution in premium positioning:Certain beverage categories retain packaging preference for perceived quality differentiation. Aluminium can penetration faces ceiling effects in high-margin segments.
Strategic Opportunities
- Kuwait and Oman market underpenetration:Per-capita aluminium can consumption lags Saudi Arabia and UAE benchmarks. Local bottling infrastructure expansion creates first-mover positioning for packaging suppliers.
- Extended producer responsibility frameworks:Anticipated GCC-wide regulations will mandate producer-funded collection systems. Early compliance investments yield preferred supplier status with major beverage brands.
- E-commerce bulk purchasing channels:500ml multi-pack formats are gaining traction through online grocery platforms. Direct-to-consumer logistics favor shelf-stable aluminium over alternative packaging.
Industry Challenges
- Alloy metallurgist skill scarcity:Regional workforce development programs have prioritized construction aluminium over beverage packaging specialization. Technical recruitment competes with oil sector compensation benchmarks.
- ECAS conformity assessment timelines:UAE Ministry of Industry and Advanced Technology certification protocols create import clearance friction. Documentation bottlenecks delay new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Aluminium Cans Market |
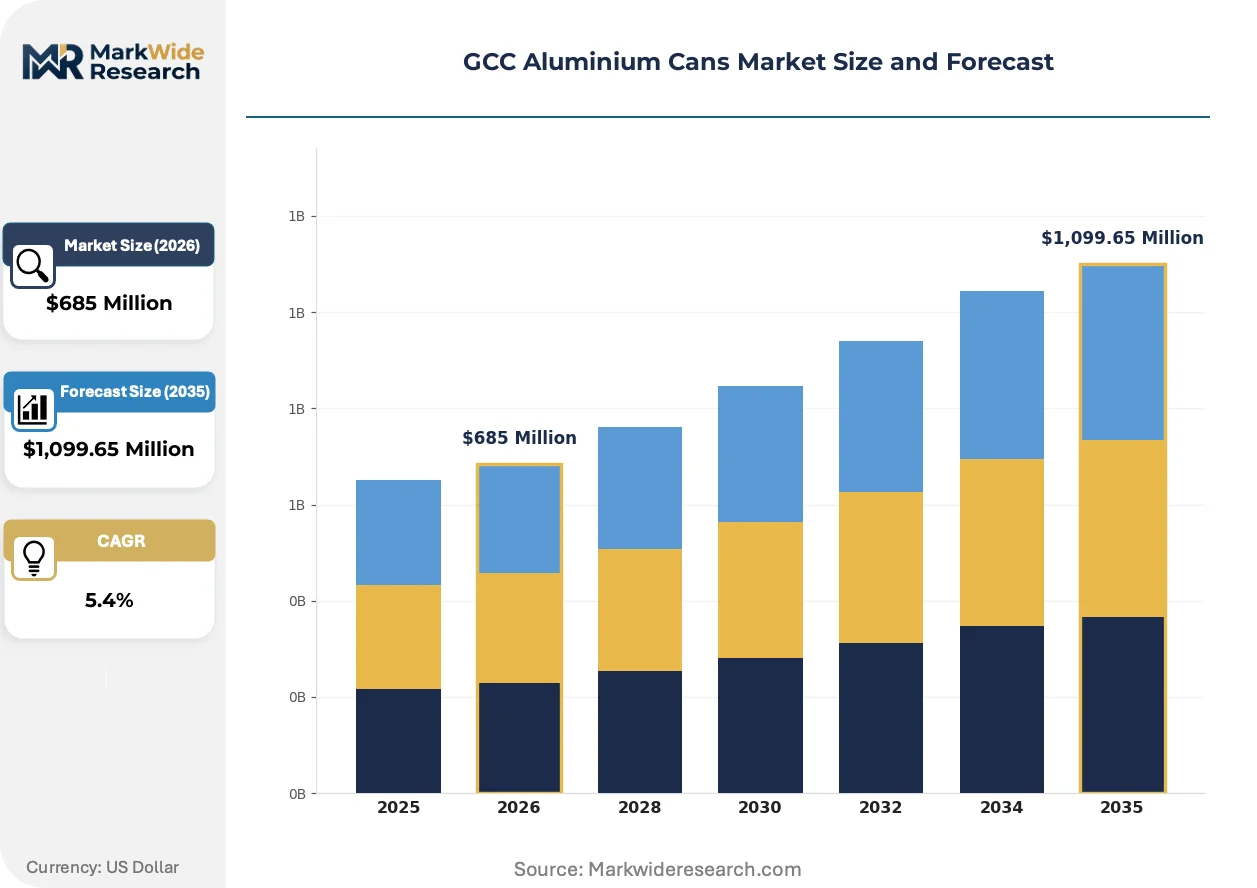
| Market Size in 2026 | $685 Million |
| Market Size in 2035 | $1,099.65 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soda Cans, Beer Cans, Food Cans, Specialty Cans Capacity: 250ml, 330ml, 500ml, 1L End User: Retail, Food Services, E-Commerce, Beverage Manufacturers Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Crown Holdings, Inc., Silgan Holdings Inc., Saudi Arabia Packaging Industry WLL (SAPIN), CCL Container Inc., CAN-PACK S.A., Gulf Cans Industries CANCO, Ardagh Group S.A., Tecnocap Group, Ball Corporation, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Aluminium Cans Market Strategic Shifts & Innovations
Digital printing and shaping technologies are collapsing minimum order quantities for branded aluminium cans, enabling beverage marketers to execute regional campaign versioning without conventional cylinder engraving lead times.
High-definition direct-to-can digital printing is supplanting traditional offset lithography with photorealistic graphics capability. Mid-tier energy drink brands in the UAE are adopting this technology for limited-edition seasonal releases. The shift is compressing design-to-shelf cycles from twelve weeks to under three weeks.
SASO technical regulations governing food-contact material migration limits are tightening testing protocols for epoxy-based internal coatings. Domestic can manufacturers are accelerating migration to non-BPA lining chemistries. Saudi beverage bottlers face reformulation timelines to maintain market access under evolving conformity requirements.
Food service operators are consolidating procurement through centralized beverage distribution platforms rather than direct mill relationships. Quick-service restaurant chains across the GCC are negotiating system-wide can supply agreements with volume-tier pricing. This concentration is most visible in Saudi Arabia's Jeddah corridor, where consolidated buying groups now represent over forty percent of 330ml format demand.
GCC Aluminium Cans Market Segmentation
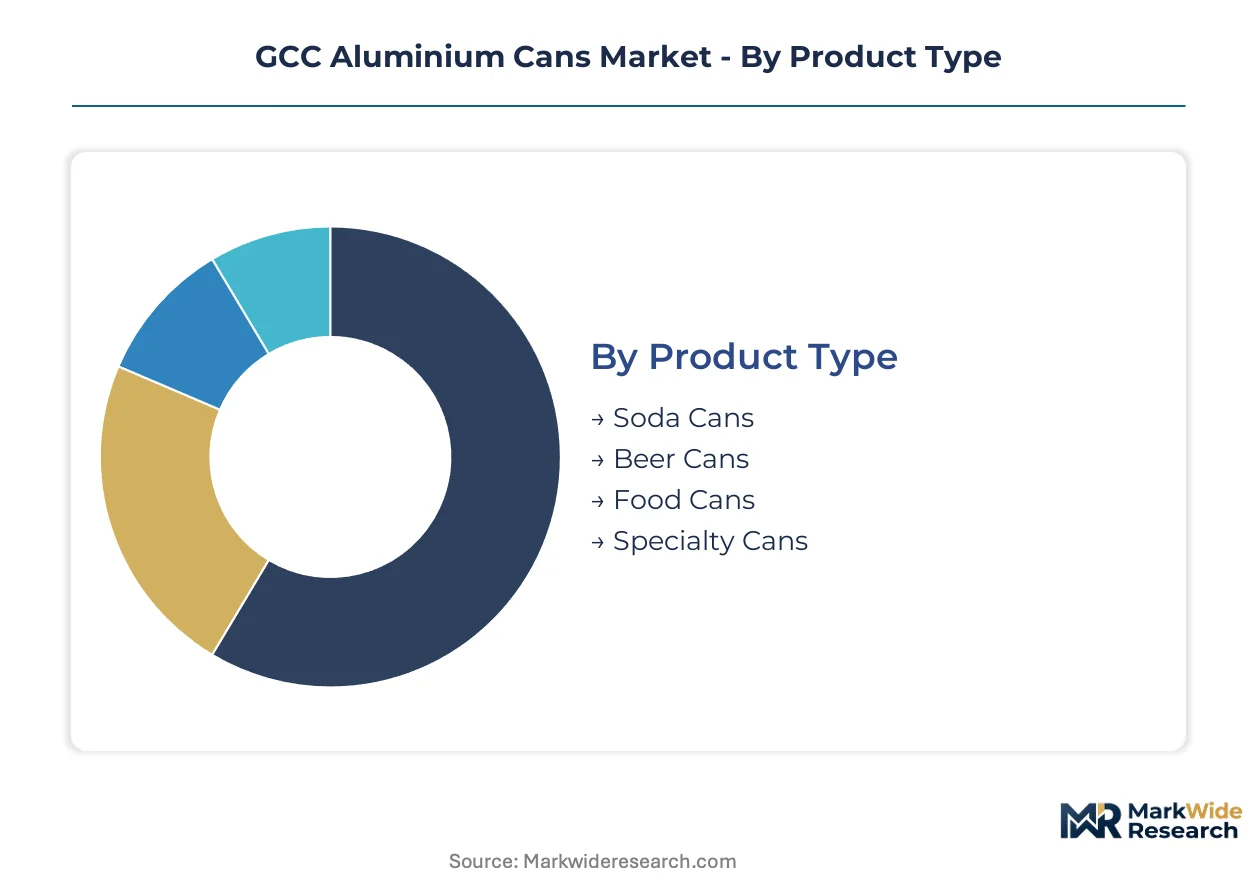
Segmentation in the GCC aluminium cans market reveals how beverage packaging specifications diverge across consumption occasions, distribution channels, and regulatory environments. Each dimension carries distinct margin profiles and supply chain requirements that shape procurement strategies for regional bottlers.
Product Type:
Margin pools concentrate in beverage cans where lightweighting investments and high-volume production lines generate operating leverage, while food cans face compressed returns due to slower line speeds and coating complexity.
- Soda Cans:Fabricated from alloy 3104-H19 with internal epoxy coatings rated for acidic carbonated beverages. Demand clusters in Saudi Arabia's Eastern Province bottling corridors where concentrated production generates procurement economies. Crown Holdings and Ball Corporation supply regional carbonated soft drink manufacturers through long-term volume agreements.
- Beer Cans:Constructed with enhanced barrier properties and premium surface finishes for alcohol licensing compliance in select UAE emirates. Per-unit margins exceed soda cans substantially, though volume flows remain constrained by distribution restrictions outside Dubai and Abu Dhabi free zones.
- Food Cans:Require thicker gauge aluminium and specialized internal linings for thermal processing compatibility. Saudi canneries serving date paste and processed tomato segments source through SAPIN's domestic rolling facilities.
- Specialty Cans:Encompass slim-profile energy drink formats and shaped containers for brand differentiation. UAE energy beverage marketers drive specification innovation through digital printing partnerships.
The dominant share belongs to Soda Cans, while Specialty Cans are expanding most quickly through energy drink portfolio expansion.
Capacity:
Production tooling dedications and filling line configurations create distinct cost structures across volume tiers, with mid-range formats capturing the broadest installed equipment base.
- 330ml:The standard food service and retail transaction size across Saudi Arabia and UAE convenience channels. Jeddah corridor quick-service restaurant chains negotiate system-wide supply agreements at this specification. Quick consumption occasions and single-serve pricing psychology sustain volume concentration.
- 500ml:Gaining traction through e-commerce bulk purchasing platforms where multi-pack economics favor larger individual units. UAE online grocery operators are consolidating procurement around this format for home delivery segments.
- 250ml:Premium positioning for mixer and niche beverage categories. Limited production runs require flexible manufacturing setups that compress margins relative to standard formats.
- 1L:Family-size and sharing occasions in Saudi retail channels. Requires specialized end reinforcement for structural integrity under stacking loads.
Format leadership sits with 330ml, though 500ml is gaining share fastest through digital commerce channel expansion.
End User:
Procurement sophistication varies sharply across buyer categories, with consolidated beverage manufacturers extracting volume-based pricing while fragmented food service operators accept premium terms for logistical flexibility.
- Beverage Manufacturers:Integrated bottling facilities in Saudi Arabia's Eastern Province and UAE industrial zones source directly through mill relationships. Technical specifications for alloy temper and coating migration limits are negotiated at contract inception.
- Retail:Hypermarket and supermarket chains across Riyadh and Dubai stock standard 330ml formats with private label expansion in select GCC markets.
- Food Services:Quick-service restaurant chains and catering operations require just-in-time delivery coordination. Consolidated buying groups in the Jeddah corridor now aggregate substantial demand for negotiated tier pricing.
- E-Commerce:Online grocery platforms favor shelf-stable aluminium over glass for logistics resilience. Direct-to-consumer fulfillment centers in Dubai South and Riyadh logistics hubs drive 500ml multi-pack specifications.
Beverage Manufacturers command the dominant procurement volume, while E-Commerce is climbing the fastest as digital grocery penetration accelerates.
Distribution Channel:
Channel economics determine packaging specification requirements, with modern trade demanding pallet-optimized configurations and traditional wholesale accepting loose handling.
- Supermarkets:Hypermarket operators in Saudi Arabia and UAE require shelf-ready packaging with retail-facing graphics. Crown Holdings supplies through direct store delivery coordination with major retail banners.
- Wholesale:Serves independent retailers and institutional buyers across Kuwait and Oman with bulk pallet configurations. Lower service requirements trade off against price sensitivity.
- Convenience Stores:High-frequency replenishment cycles in urban Saudi corridors favor 330ml singles and six-pack formats. Chilled display requirements influence coating specifications for condensation resistance.
- Online:Direct-to-consumer shipments require enhanced pack integrity for last-mile handling. UAE e-commerce operators are specifying reinforced secondary packaging to reduce transit damage claims.
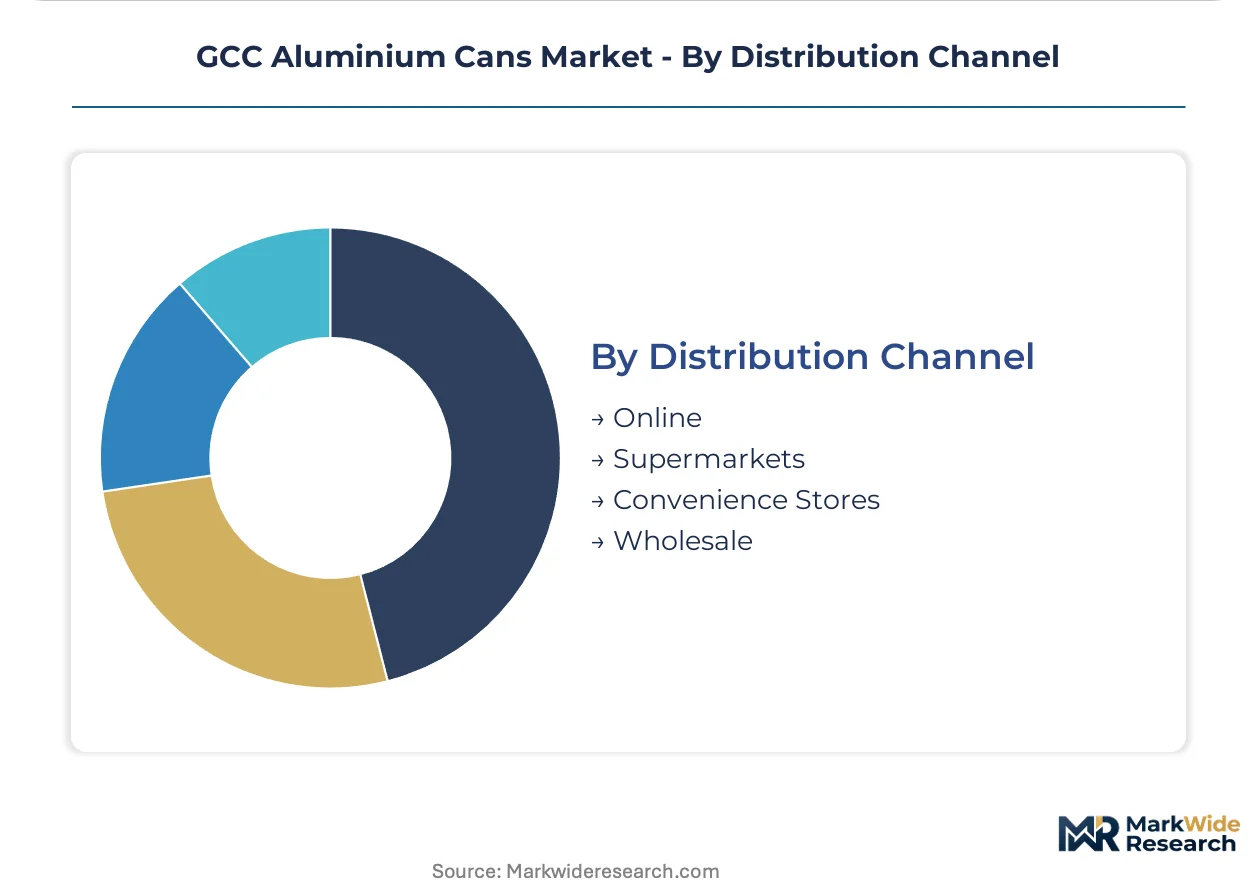
Supermarkets retain the dominant channel position, while Online is expanding most quickly through platform consolidation and delivery infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia and the UAE consume aluminium cans at substantially higher per-capita rates than Kuwait, Oman, Bahrain, and Qatar, where glass bottles and aseptic cartons retain larger beverage packaging shares.
Saudi Arabia
Carbonated soft drink bottling clusters in the Eastern Province and Jeddah corridor generate concentrated procurement demand from Crown Holdings and Ball Corporation. SASO technical regulations govern food-contact material migration limits and dimensional tolerances for domestically distributed cans. Riyadh's retail and food service channels absorb the kingdom's largest 330ml format volumes.
United Arab Emirates
Energy beverage marketers in Dubai drive specification innovation through digital printing partnerships for limited-edition seasonal releases. The Ministry of Industry and Advanced Technology enforces ECAS conformity assessment protocols for imported aluminium packaging. Abu Dhabi's beverage distribution free zones handle premium beer can flows under emirate-specific licensing frameworks.
Kuwait
Per-capita aluminium can consumption lags Saudi and UAE benchmarks, creating first-mover positioning for packaging suppliers expanding local bottling infrastructure. The country's national standards body oversees food-contact material certification for imported beverage packaging. Kuwait City's retail modernization is gradually displacing traditional glass bottle preferences in convenience channels.
Oman
Domestic beverage manufacturing remains underdeveloped relative to import-dependent retail structures. General functional regulators oversee packaging material safety without dedicated beverage can specifications. Muscat's logistics corridor serves as a transshipment node for Saudi-produced can stock entering Yemeni and East African markets.
Bahrain
SAPIN anchors regional production capacity through its domestic rolling facilities, reducing import dependency for GCC beverage brands. The country's central standards authority aligns with Gulf Cooperation Council harmonization initiatives for cross-border material certification. Sitra's industrial zone concentrates aluminium flat-rolled product manufacturing serving Saudi and UAE bottlers.
GCC Aluminium Cans Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with Crown Holdings and Ball Corporation commanding scale advantages in beverage can body production while regional fabricators compete on logistics proximity. The market structure rewards backward integration into aluminium rolling capacity and captive alloy supply. Three archetypes dominate: multinational packaging converters with GCC manufacturing footprints, domestic rolling specialists serving regional bottlers, and diversified metal packaging groups with beverage-focused divisions. Competitive intensity centers on lightweighting process advances and deposit-return scheme pilot participation.
Among multinational converters with established GCC presence, Crown Holdings, Inc. and Ball Corporation exemplify the integrated leader archetype through their regional manufacturing footprints and long-term volume agreements with major beverage bottlers. Saudi Arabia Packaging Industry WLL (SAPIN) occupies a distinct position as a domestic rolling specialist, anchoring regional production capacity through Bahrain and Saudi facilities that reduce import dependency for GCC beverage brands.
| Leading Market Players |
|---|
| Crown Holdings, Inc. |
| Silgan Holdings Inc. |
| Saudi Arabia Packaging Industry WLL (SAPIN) |
| CCL Container Inc. |
| CAN-PACK S.A. |
| Gulf Cans Industries CANCO |
| Ardagh Group S.A. |
| Tecnocap Group |
| Ball Corporation |
| Others |
Cost & Logistics Intelligence
Twelve-to-fourteen-week ECAS conformity assessment timelines in the UAE compress inventory turns for imported can stock, concentrating pricing power with domestic rolling mills in Bahrain and Saudi Arabia that bypass import clearance friction. Beverage bottlers in Saudi Arabia's Eastern Province negotiate from weaker positions when alloy 3104-H19 coil availability tightens during peak summer bottling cycles.
Pricing Analysis
Long-term offtake agreements dominate procurement between Saudi bottling clusters and regional rolling mills, though spot purchases spike during seasonal demand surges. Price differentiation stems from volume scale commitments and SASO certification tier, with ECAS-compliant imports commanding premiums over domestic supply. Pricing pressure stems from London Metal Exchange aluminium volatility transmitting directly to can body material costs. Consolidated beverage manufacturers in the Eastern Province exhibit lowest price sensitivity, while fragmented food service operators in Kuwait accept premium terms for logistical flexibility.
Supply Chain Analysis
Bahrain and Saudi Arabia anchor regional aluminium flat-rolled production through SAPIN's Sitra and Dammam facilities, feeding coil stock to GCC beverage can converters. The supply chain draws from primary aluminium ingot imports and captive remelt scrap streams, with alloy 3104-H19 temper specifications tightening across rolling mill outputs. Single-source vulnerability concentrates in domestic rolling capacity, where limited regional producers create bottleneck risk for alloy 3004-H19 supply. Distribution runs through direct mill relationships for integrated bottlers and consolidated buying groups for fragmented food service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deposit-return scheme pilots across multiple GCC jurisdictions signal early-cycle infrastructure buildout, with closed-loop aluminium circulation creating captive scrap economics for first-mover packaging converters. Per-capita consumption gaps in Kuwait and Oman against Saudi benchmarks indicate penetration runway for bottling infrastructure expansion.
For Market Incumbents: Compound lightweighting technology leadership through body wall thickness reduction below 0.097 mm, locking in alloy input advantages against regional competitors. Secure backward integration into remelt scrap processing to defend margin position against primary aluminium price volatility. Accelerate SASO pre-certification for non-BPA lining chemistries before regulatory deadlines tighten.
For New Entrants and Emerging Players: Digital printing service gaps in seasonal campaign versioning expose white-space where incumbents under-serve mid-tier energy drink brands with twelve-week conventional cylinder lead times. Target Oman and Kuwait bottling infrastructure expansion with mobile can printing units that collapse design-to-shelf cycles. Lead with photorealistic graphics capability and three-week turnaround guarantees as the go-to-market wedge.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified metal packaging groups with underperforming beverage-focused divisions, particularly those lacking GCC manufacturing footprint. Long-term viability centers on regulatory compliance infrastructure and captive alloy supply rather than pure conversion capacity. Watch deposit-return scheme pilot conversion into mandatory frameworks as the inflection signal for scrap-stream economics dominance.
| Strategic Initiative | Industry Significance |
|---|---|
| Lightweighting Process Investment | Body wall thickness reduction below 0.097 mm cuts alloy input per can for Crown Holdings and Ball Corporation. |
| Domestic Rolling Capacity Expansion | SAPIN's Bahrain and Saudi facilities reduce import dependency for GCC beverage brands against ECAS friction. |
| Digital Printing Technology Adoption | Direct-to-can photorealistic graphics compress design-to-shelf cycles from twelve weeks to under three weeks. |
| Closed-Loop Scrap Infrastructure | Deposit-return scheme participation secures captive remelt alloy streams ahead of GCC-wide EPR mandates. |
| Non-BPA Lining Migration | SASO tightening on epoxy-based coatings accelerates reformulation timelines for Saudi market access. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with beverage procurement directors at Saudi bottling clusters, rolling mill metallurgists at Bahrain flat-rolled facilities, ECAS certification specialists, and quick-service restaurant supply chain managers across the Jeddah corridor. Secondary validation incorporated SASO technical regulation filings, Emirates Conformity Assessment Scheme protocols, Gulf Cooperation Council standardization harmonization documents, and London Metal Exchange aluminium price series. Bottom-up volume estimates from bottling line capacity and top-down alloy consumption figures were triangulated for convergence.
Across the analysis window, the analytical framework modeled segmentation dimensions including product type, capacity tier, end-user category, and distribution channel, with regional regulatory cluster as an additional industry-specific dimension. CAGRs were derived from installed bottling capacity expansion trajectories, per-capita consumption convergence assumptions, and lightweighting penetration curves. Forecast inputs incorporated ECAS clearance timeline distributions and deposit-return scheme pilot scaling probabilities.
Forecasts assume regulatory continuity in SASO food-contact material regimes and ECAS conformity assessment protocols; material policy shifts would require re-modeling. Specific risks include primary aluminium price volatility spikes, alloy metallurgist skill scarcity constraining rolling mill output, and glass bottle substitution in premium beverage categories. Recalibration cycles align with material shifts in GCC extended producer responsibility framework adoption and lightweighting technology penetration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Niobium Oxide Market
Metals
Tungsten Metal Powder Market
Metals
Metal Injection Molding (Mim) Powders Market
Metals
Precious Metals Wire Market
Metals
Barium Market
Metals
Aluminum Scrap Recycling Market
Metals
Prebaked Anodes for Aluminum Market
Metals
Silico Manganese Market
Metals
Cerium Market
Metals
North America Aluminum Casting Market
Metals
Electrodeposited Copper Foil Market
Metals
Beryllium Copper Plate Market
Metals
Tantalum and Niobium Material Market
Metals
Silver-Platinum Paste Market
Metals
Brazing Strips Market
Metals
Steel Long Products Market