
 Global Precious Metal Market | 2026-2036
Global Precious Metal Market Size, Share, and Industry Trends Forecast 2026-2036
Global Precious Metal Market Foresight
Buyer concentration among automotive suppliers is hardening as exhaust-system manufacturers consolidate procurement around fewer qualified refiners. Newmont sustains broad geographic coverage across Nevada and Ghana deposits. Barrick Gold anchors its portfolio with deep Carlin Trend reserves. Rio Tinto competes through integrated copper-gold complexes in Mongolia and Australia.
Precious metals comprise naturally occurring metallic elements with high economic value, characterized by superior electrical conductivity, corrosion resistance, and catalytic activity; these properties make them irreplaceable in electronic bonding wire, autocatalyst substrates, and dental alloy formulations. Gold dominates value pools in jewelry and investment bar fabrication, while palladium leads automotive catalyst loadings amid stricter tailpipe standards. Silver powders and foils are expanding fastest in photovoltaic cell metallization and semiconductor packaging.
The EPA tailpipe rules, REACH substance restrictions, and China's MEE emissions standards collectively tighten permissible impurity levels in refined precious metal feedstock. ISO 14001 environmental management certification now gates supplier qualification for European electronics producers and Japanese automotive tier ones. Stakeholders must monitor how carbon-border adjustments and recycled-content mandates reshape competitive advantage between primary miners and urban refiners.
Market Dynamics
Automotive exhaust-system manufacturers are consolidating procurement around fewer qualified refiners capable of meeting tightening emissions standards, hardening buyer concentration and reshaping competitive access across the value chain.
Growth Catalysts
- EPA tailpipe rules:Stricter permissible impurity levels in refined feedstock are expanding platinum and palladium offtake for catalytic converters across North American automotive production.
- Photovoltaic cell metallization:Silver powders and foils are displacing traditional conductive materials in solar panel manufacturing, creating new demand vectors outside jewelry and investment.
- China:Dual carbon goals and MEE emissions standards are reshaping sourcing requirements for low-carbon refined output, favoring integrated miners with verified carbon accounting.
Market Restraints
- Input cost volatility:Energy-intensive refining processes expose margins to natural gas and electricity price swings, particularly acute for European urban refiners.
- Supply concentration risk:Deep Carlin Trend reserves and Nevada-Ghana deposit dominance concentrate primary supply among a handful of geographic clusters, amplifying disruption exposure.
- Substitution threat:Copper-gold complexes and base-metal alternatives in electronics bonding wire are eroding silver's historical cost-performance advantage in semiconductor packaging.
Strategic Opportunities
- India:Jewelry fabrication and electronics plating are lifting import volumes of gold and silver, creating underpenetrated downstream value capture for integrated refiners.
- EU Green Deal:Carbon-border adjustments and recycled-content mandates are advantaging urban refiners with circular feedstock capabilities over primary extraction.
- ISO 14001 convergence:Environmental management certification is gating supplier qualification for Japanese automotive tier ones, creating first-mover certification premiums.
Industry Challenges
- REACH substance restrictions:Compliance timeline compression for impurity documentation is straining analytical chemistry capacity at mid-scale refiners.
- Skill scarcity:Metallurgical expertise in fire assay and wet chemistry is concentrating among aging workforces in traditional refining hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Precious Metal Market |
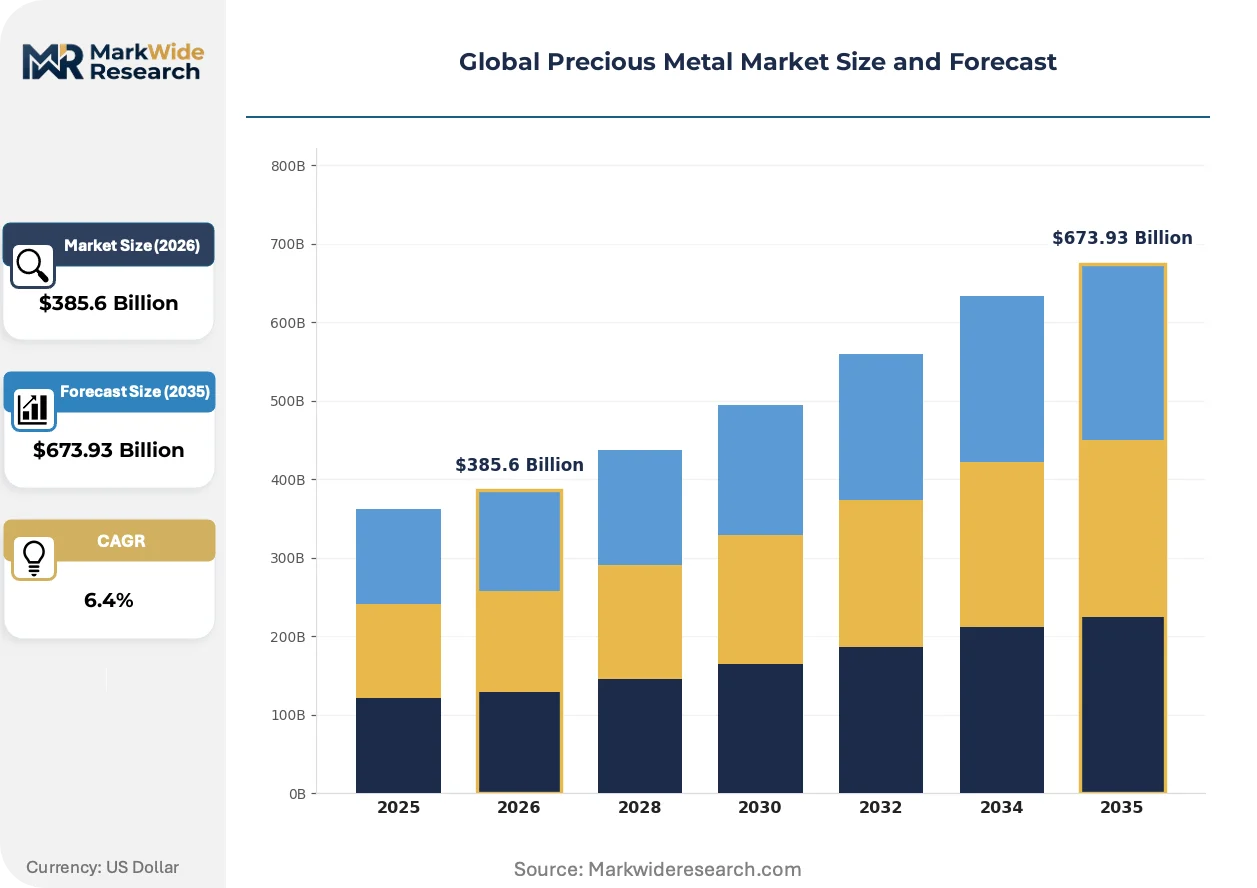
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $673.93 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gold, Silver, Platinum, Palladium, Rhodium Application: Jewelry, Electronics, Automotive Catalysts, Dentistry, Chemical Processing End User: Jewelry Manufacturers, Electronics Producers, Automotive Suppliers, Dental Clinics, Chemical Companies Form: Bars, Coins, Powders, Foils, Granules |
| Companies Covered | Lundin Gold, Andean Precious Metals, Newmont, Rio Tinto, Discovery Silver, Barrick Gold, Heliostar Metals, Freeport-McMoRan, AngloGold Ashanti, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Precious Metal Market Shifts & Advancements
Digital traceability platforms and low-carbon refining technologies are actively restructuring how precious metal provenance is verified and valued across automotive and electronics supply chains.
Blockchain-enabled origin tracking is unifying assay data with carbon intensity metrics into immutable certification records. Tier-one automotive suppliers in Germany and Japan are mandating these platforms for platinum group metal procurement. The technology is unifying previously fragmented compliance documentation into single-source verification, compressing supplier qualification cycles and raising barriers for non-integrated refiners.
REACH substance restrictions and the EU Green Deal are tightening permissible impurity thresholds while embedding carbon accounting into supplier contracts. European electronics producers now require ISO 14001 certification as a baseline qualification gate. The regulatory pressure is most acute for silver refiners serving photovoltaic manufacturers, who must document recycled content percentages to maintain contract eligibility.
Buyer concentration among exhaust-system manufacturers is compressing procurement cycles and demanding longer-term offtake commitments. Spot market purchasing is retreating in favor of multi-year contracts with embedded price collars and sustainability clauses. This behavioral shift is most visible in Germany and South Korea, where automotive OEMs are consolidating qualified supplier lists to fewer than five refiners per metal category.
Global Precious Metal Market Segmentation
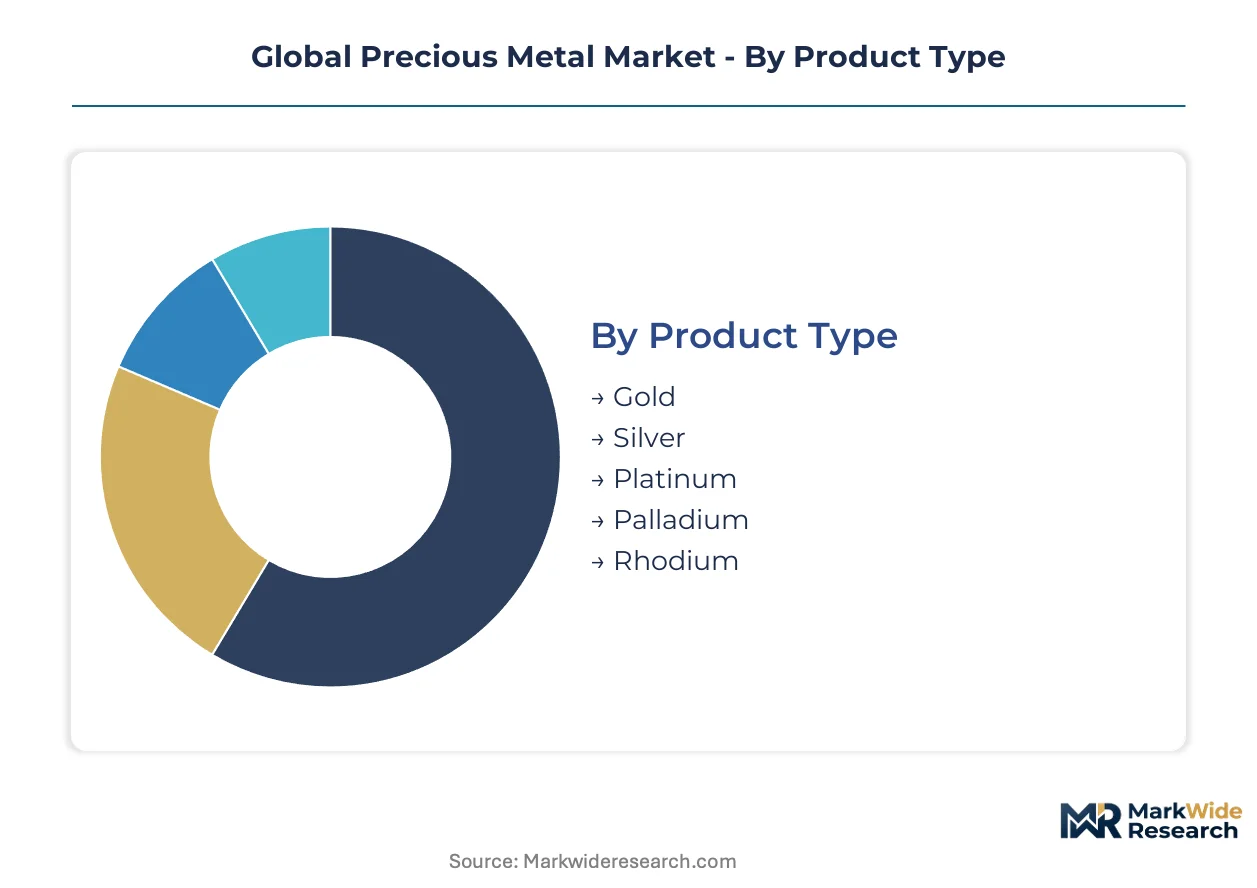
Precious metal demand fragments across fundamentally different integration models. Standalone investment products compete with embedded industrial feedstocks for refinery capacity and carbon accounting priority.
Product Type:
Integration depth separates exchange-traded stores of value from catalytic and conductive industrial inputs.
- Gold:High-density metallic element with exceptional corrosion resistance and electrical conductivity. Jewelry fabrication in India and investment bar accumulation in Turkey concentrate physical offtake, with central bank purchasing tightening available float.
- Silver:Highest electrical and thermal conductivity among all metals, available in purities from 99.9% to 99.99%. Photovoltaic cell metallization in China and semiconductor packaging in Taiwan are displacing traditional photographic and battery applications.
- Platinum:Dense, malleable metal with superior catalytic activity for oxidation reactions. Automotive catalyst loadings in Germany and hydrogen fuel cell electrode production in Japan anchor industrial consumption.
- Palladium:Lighter platinum group metal optimized for gasoline engine catalytic reduction. EPA tailpipe enforcement in the United States and MEE emissions standards in China harden specification requirements for automotive suppliers.
- Rhodium:Rarest platinum group metal with highest catalytic activity per unit mass. Nitric acid production catalysts and glass fiber manufacturing in Russia and South Africa concentrate limited supply.
Gold leads volumes today; silver is gaining share fastest through photovoltaic and electronics penetration.
Application:
Cost tier stratification separates discretionary consumer purchases from mandated industrial compliance spending.
- Jewelry:Fabrication of ornamental objects ranging from 18-karat alloy to 24-karat pure metal. Indian wedding season cycles and Chinese retail investment patterns drive seasonal demand spikes.
- Electronics:Bonding wire, contact plating, and conductive paste applications requiring high reliability. REACH substance restrictions in Europe and RoHS directives tighten permissible impurity thresholds.
- Automotive Catalysts:Exhaust emission control substrates using platinum, palladium, and rhodium coatings. KBA certification requirements in Germany and Tier 2/3 supplier consolidation compress qualified refiner lists.
- Dentistry:Alloys combining gold, silver, and platinum for crowns, bridges, and prosthetic frameworks. Aging demographics in Japan and Germany sustain replacement-driven demand.
- Chemical Processing:Heterogeneous catalysts for petrochemical cracking and pharmaceutical synthesis. Hydrogenation reactor loadings in the Netherlands and polymer production in Belgium specify low-sulfur feedstock.
Jewelry commands the largest value pool; automotive catalysts show the steepest expansion trajectory through emissions regulation tightening.
End User:
Customer type determines procurement sophistication, with automotive OEMs demanding traceability that jewelry distributors rarely match.
- Jewelry Manufacturers:Fabricators of finished ornamental products across karat specifications. Istanbul's Grand Bazaar traders and Mumbai's Zaveri Bazaar wholesalers concentrate physical distribution.
- Electronics Producers:Semiconductor foundries and contract manufacturers requiring ISO 14001-certified feedstock. TSMC in Taiwan and Samsung in South Korea mandate blockchain-enabled origin documentation.
- Automotive Suppliers:Exhaust system manufacturers and tier-one component integrators. Bosch, Denso, and Faurecia consolidate procurement around five-refiner qualified lists per metal category.
- Dental Clinics:Individual practitioners and dental laboratory networks purchasing alloy formulations. Laboratory consolidation in the United States and Germany shifts volume toward larger distributors.
- Chemical Companies:Petrochemical crackers and specialty chemical manufacturers. BASF in Germany and Johnson Matthey in the United Kingdom operate captive refining for catalyst recycling.
Jewelry manufacturers move the highest tonnage; electronics producers are expanding procurement fastest through semiconductor capacity buildouts.
Form:
Supply concentration varies dramatically by physical state, with bars and coins consolidating around London and Zurich vaults while powders fragment across regional processors.
- Bars:Cast or minted rectangular ingots in weights from 1 gram to 400 troy ounces. London Bullion Market Association good delivery standards govern wholesale settlement.
- Coins:Government-minted legal tender with guaranteed purity and weight. American Eagle, Canadian Maple Leaf, and Australian Kangaroo programs dominate retail investment.
- Powders:Atomized or chemically precipitated particulate for additive manufacturing and paste formulation. Solar paste producers in China and conductive adhesive manufacturers in Japan specify particle size distributions.
- Foils:Rolled thin sheets for semiconductor packaging and capacitor electrodes. Thickness tolerances below 5 microns serve advanced electronics bonding applications.
- Granules:Small, free-flowing pellets optimized for vacuum casting and investment jewelry production. Italian and Turkish refiners dominate aesthetic alloy formulation.
Bars anchor institutional holdings; powders are climbing fastest through electronics and photovoltaic process adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metallurgical expertise concentrates in traditional refining hubs where fire assay and wet chemistry skills anchor production quality. Workforce scarcity in these specialized disciplines is reshaping competitive access across major producing territories.
United States
EPA tailpipe enforcement is expanding platinum and palladium offtake for catalytic converters across North American automotive production. IRA clean energy provisions subsidize domestic refining capacity for low-carbon output. The Carlin Trend in Nevada hosts deep gold reserves that concentrate primary supply among integrated miners with verified carbon accounting.
China
Photovoltaic cell metallization is displacing traditional conductive materials in solar panel manufacturing, creating silver demand vectors outside jewelry. MEE emissions standards and dual carbon goals reshape sourcing requirements for low-carbon refined output. The Yangtze River Delta clusters solar paste producers specifying particle size distributions for conductive adhesive applications.
Germany
KBA certification requirements compress qualified refiner lists for automotive exhaust-system manufacturers. REACH substance restrictions tighten permissible impurity thresholds in refined feedstock. Stuttgart's automotive tier-one suppliers consolidate procurement around fewer than five refiners per metal category, hardening buyer concentration.
India
Jewelry fabrication and electronics plating lift import volumes of gold and silver, creating downstream value capture opportunities. BIS quality standards govern wholesale settlement for cast and minted ingots. Mumbai's Zaveri Bazaar wholesalers concentrate physical distribution for wedding season demand cycles.
South Africa
Rhodium supply for nitric acid production catalysts and glass fiber manufacturing concentrates limited output among deep reef operations. The country's national mining regulator enforces safety and environmental standards for underground platinum group metal extraction. The Bushveld Complex anchors global palladium and rhodium reserves with integrated smelting infrastructure.
Global Precious Metal Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across extraction, refining, and fabrication tiers. The vendor base stratifies between integrated miners controlling upstream reserves and urban refiners capturing circular feedstock advantages. Three archetypes dominate: geographically diversified majors with multi-continent asset portfolios, regional specialists leveraging proximity to automotive or electronics clusters, and technology-integrated players embedding blockchain traceability into certification workflows. Capacity expansion and strategic partnerships represent the dominant competitive moves, particularly around low-carbon refining installations and multi-year offtake commitments with embedded sustainability clauses.
Among the geographically diversified majors, Newmont and Barrick Gold exemplify the multi-continent asset archetype with Nevada and Ghana deposit coverage. Rio Tinto occupies a position representing integrated copper-gold complex operators competing through Mongolia and Australian production bases. AngloGold Ashanti anchors the African-focused tier with deep reef expertise in the Bushveld Complex. These three represent distinct strategic positioning vectors: North American reserve depth, diversified commodity integration, and regional specialization in platinum group metal geology.
| Leading Market Players |
|---|
| Lundin Gold |
| Andean Precious Metals |
| Newmont |
| Rio Tinto |
| Discovery Silver |
| Barrick Gold |
| Heliostar Metals |
| Freeport-McMoRan |
| AngloGold Ashanti |
| Others |
Supply & Pricing Matrix
Automotive tier-one exhaust-system manufacturers consolidate procurement around fewer than five qualified refiners per metal category, embedding multi-year offtake contracts with sustainability clauses as the dominant pricing mechanism. This buyer concentration hardens contract-based pricing over spot market purchasing, compressing supplier margins while rewarding integrated miners with verified carbon accounting.
Pricing Analysis
Refined precious metal supply splits between bundled long-term contracts with embedded price collars and unbundled spot transactions for residual volumes. Three-tier pricing structure across LBMA good delivery, ISO 14001-certified industrial feedstock, and uncertified secondary material separates premium tiers by traceability grade and carbon intensity documentation. Pricing pressure stems from energy cost volatility exposing European urban refiner margins to natural gas price swings. Electronics producers in Taiwan and semiconductor foundries show highest price sensitivity, while central bank gold purchasers and German automotive OEMs absorb premiums for certified provenance.
Supply Chain Analysis
Primary refined output rests on ore concentrate flows from Nevada's Carlin Trend, Ghana's Ahafo deposits, and South Africa's Bushveld Complex. Fire assay reagents, high-purity chlorine for wet chemistry, and metallurgical coke for smelting constitute critical input dependencies. Single-source vulnerability concentrates around South African rhodium output and Chinese solar paste production for silver powders. Distribution runs through London and Zurich vaults for investment bars, while industrial powders fragment across regional processors in China, Japan, and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon-border adjustment mechanisms between the EU and China create geographic-arbitrage opportunities for refiners with dual-hemisphere certification, exploiting the regulatory cost differential for low-carbon output verification.
For Market Incumbents: Extend carbon accounting transparency through blockchain-enabled origin tracking to defend contract eligibility against emerging urban refiners with circular feedstock capabilities. Backward integration into photovoltaic paste formulation in China's Yangtze River Delta captures silver demand displacement from traditional applications. Prioritize ISO 14001 certification renewal ahead of Japanese automotive tier-one supplier audits. For New Entrants and Emerging Players: Begin with India's jewelry fabrication and electronics plating import corridors, where BIS quality standard compliance creates lower barriers than REACH-gated European markets. Solar paste production for Chinese photovoltaic manufacturers represents the most penetrable industrial segment lacking established refiner relationships. Pursue toll-refining partnerships with mid-scale miners in West Africa to bypass reserve acquisition capital requirements. For Investors and Strategic Acquirers: Automotive OEMs with captive catalyst recycling operations are the most active acquirer in this space, consolidating urban refiner capabilities to secure circular platinum group metal supply. Long-term viability hinges on positioning for carbon-border adjustment permanence and recycled-content mandate expansion. Watch for EPA tailpipe rule enforcement acceleration as the inflection signal tightening specification requirements and compressing qualified supplier lists further.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Carbon Refining Capacity Expansion | EU Green Deal carbon-border adjustments advantage certified output in German automotive supply chains. |
| Blockchain Traceability Platform Deployment | TSMC and Samsung mandate origin documentation, gating contract eligibility for uncertified refiners. |
| Urban Refiner Acquisition | Captive recycling capabilities secure circular platinum group metal feedstock against primary supply disruption. |
| India Distribution Partnership | Mumbai's Zaveri Bazaar wholesalers concentrate wedding season demand cycles for gold and silver. |
| Photovoltaic Paste Formulation Joint Venture | Yangtze River Delta solar producers specify particle size distributions for conductive adhesive applications. |
Research Methodology
Multiple input streams — primary interviews with mining operations executives, automotive tier-one procurement leads, and precious metals traders; secondary validation through LBMA trade statistics, EPA enforcement disclosures, and SEC 10-K filings; plus customs and refinery production data — were reconciled through bottom-up and top-down triangulation. Conversations with Indian jewelry manufacturers, Chinese solar paste producers, and German automotive suppliers informed demand-side calibration. Secondary sources included REACH substance restriction updates, MEE emissions standard documentation, and ISO certification registry analysis.
Historical production volumes were cross-referenced against panel input from refinery operations managers and commodity trading desks across the analysis window. Segmentation dimensions modeled encompass product type, application end-use, physical form, and regional regulatory cluster. CAGRs were derived from slope analysis of annualized demand trajectories, incorporating automotive catalyst loading specifications, photovoltaic cell silver intensity trends, and central bank gold purchasing patterns as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced regulatory enforcement acceleration, geopolitical disruption of South African deep reef operations, and breakthrough substitution in semiconductor bonding wire. Forecasts reflect documented assumptions regarding emissions standard implementation timelines and carbon-border adjustment permanence. Material deviation in EPA rule enforcement, EU Green Deal scope expansion, or Chinese dual carbon goal acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Aluminum Tubes Market
Metals
Beryllium Copper for Industrial Equipment Market
Metals
Metal Powder Market
Metals
Iron Ore Market
Metals
Global Chromium Market
Metals
Nickel Foam Market
Metals
Zirconium Market
Metals
Lightweight Aluminium Pistons Market
Metals
Steel Ingots Market
Metals
Aluminium Powder Market
Metals
Bearing Steel Market
Metals
Europe Metal Service Centers Market
Metals
Anodized Titanium Market
Metals
Aluminum Plates and Sheet Coils Market
Metals
High Carbon Bearing Steel Market
Metals
Copper and Copper Alloy Market