
 Cerium Market | 2026-2036
Cerium Market Size, Share, and Industry Trends Forecast 2026-2036
Cerium Market Intelligence
Advanced catalytic converter architectures is tilting cerium procurement toward higher-purity oxide grades. Lynas Rare Earths Ltd leverages Australian mining assets to sustain non-Chinese supply security. China Northern Rare Earth (Group) High-Tech Co., Ltd. anchors domestic capacity through integrated Baotou refining operations. MP Materials controls Mountain Pass extraction while navigating downstream processing gaps.
Cerium, a lanthanide element with atomic number 58, occurs primarily as cerium(IV) oxide in bastnäsite and monazite ores; its 4f electron configuration enables reversible Ce³⁺/Ce⁴⁺ redox cycling critical for oxygen storage in automotive catalysts. Cerium oxide dominates product type revenue due to entrenched use in exhaust gas treatment and optical polishing slurries. Glass and polishing applications compete with catalysts for volume leadership, though catalyst-grade oxide commands premium specification thresholds. Powder form leads procurement across most end-use industries because of superior dispersion characteristics in catalytic washcoats.
China's MIIT and SAMR enforce production quotas and export licensing that directly constrain global cerium availability. EPA Tier 3 and Euro 7 emission standards tighten cerium loading requirements per catalyst unit. REACH registration in Europe adds compliance cost layers for importers. Stakeholders must monitor quota announcements from Beijing and emission rulemakings in Brussels and Washington to anticipate supply-cost inflections.
Market Dynamics
China's dual carbon goals and rare earth processing restrictions are redirecting supply chain investment toward non-Chinese mining jurisdictions. This concentration of refining capacity in Inner Mongolia and Jiangxi is forcing automotive catalyst manufacturers to secure alternative oxide sources.
Growth Catalysts
- Euro 7 emission standards:Tighter cerium loading requirements per catalyst unit are expanding addressable volume for high-purity oxide suppliers. European automakers face compliance deadlines that mandate oxygen storage capacity upgrades.
- Hydrogen fuel cell membrane manufacturing:Cerium-doped electrolytes are gaining traction in proton exchange membrane fabrication. Korean and Japanese stack producers are qualifying cerium-stabilized zirconia for next-generation systems.
- Optical polishing for compound semiconductors:Silicon carbide wafer manufacturers in Taiwan and Germany are consuming precision-grade ceria slurries for substrate finishing. This application demands sub-micron particle distribution control.
Market Restraints
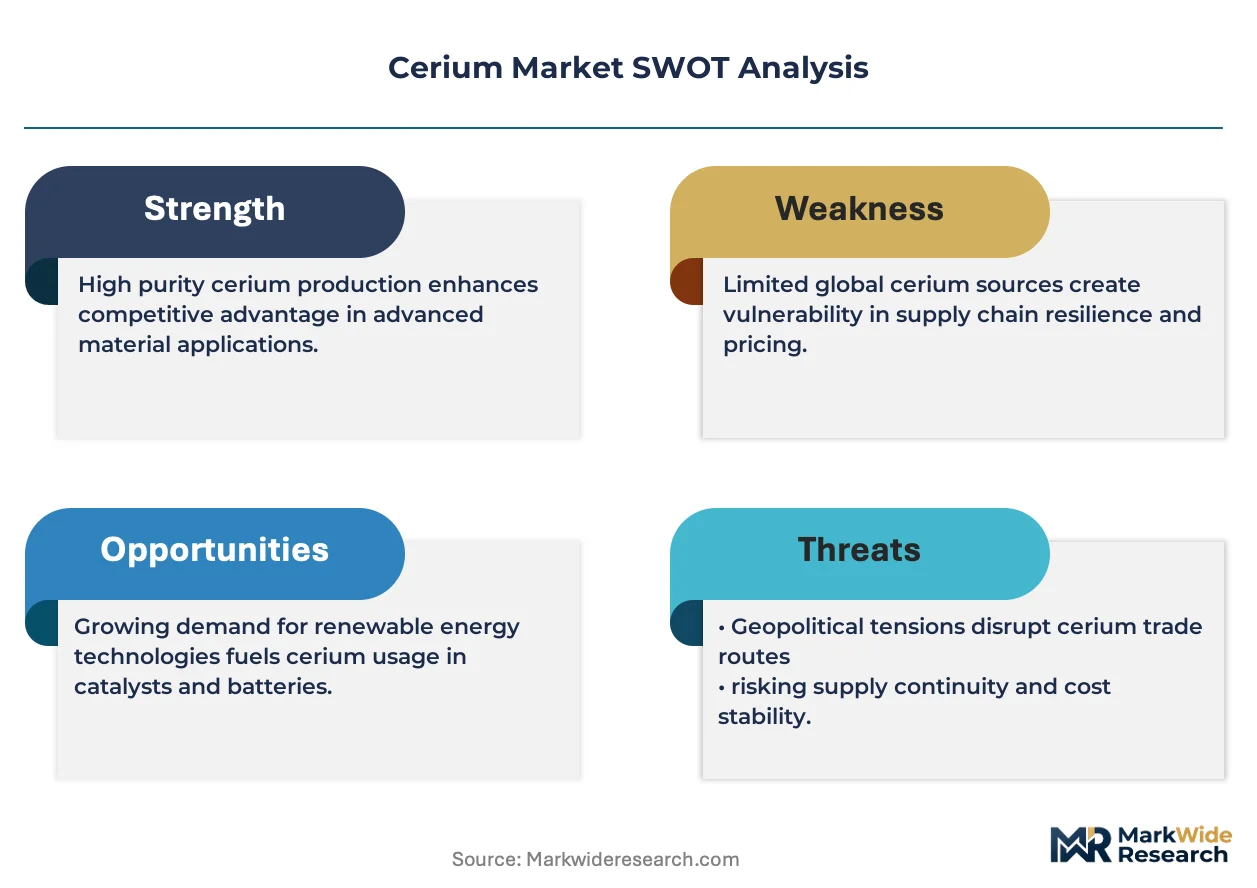
- Bastnäsite concentrate supply concentration:Over 60% of mined feedstock originates from Chinese-controlled operations. Australian and US deposits face permitting and metallurgical complexity barriers.
- Thorium and uranium co-extraction:Monazite processing generates radioactive byproduct streams requiring MEE-licensed disposal facilities. This technical limitation restricts new entrant capacity in Southeast Asia and Africa.
- REACH registration cost layers:European importers face extended compliance timelines and testing expenditure for cerium compound dossiers. ECHA substance evaluation creates regulatory friction for spot market participants.
Strategic Opportunities
- US downstream processing gap closure:MP Materials and emerging developers are constructing solvent extraction circuits at Mountain Pass. Domestic oxide production would bypass Chinese refining chokepoints entirely.
- Glass decolorization substitution:Neodymium-doped alternatives are penetrating premium optical glass applications. Cerium-free formulations threaten traditional volume in Japanese and German specialty glasshouses.
- India PLI scheme for rare earth magnet manufacturing:Downstream incentives are attracting separation circuit investment in Odisha and Kerala. BIS standards alignment would enable export-grade oxide qualification.
Industry Challenges
- Redox chemistry expertise scarcity:Ce³⁺/Ce⁴⁺ cycle optimization for catalyst washcoats requires specialized surface science knowledge. Automotive exhaust engineering teams report hiring friction for this skill set.
- ISO 14001 environmental management certification:New separation facilities face 18-24 month accreditation timelines. Auditors scrutinize tailings management and water recycling protocols against evolving thresholds.
- Legacy furnace integration:Existing rotary kiln infrastructure at older refineries cannot achieve the temperature uniformity required for 99.99% oxide production. Retrofit capex competes with greenfield project returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cerium Market |
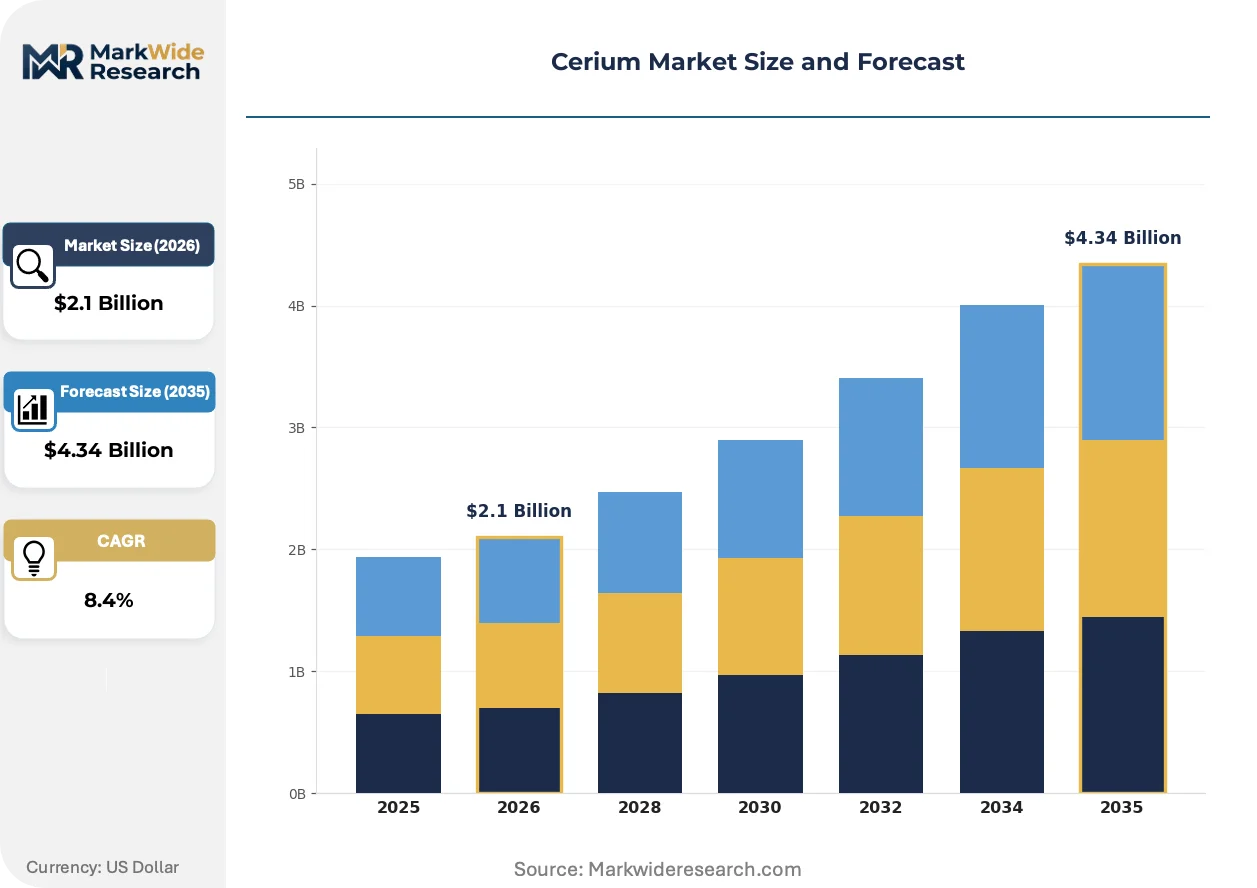
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cerium Oxide, Cerium Carbonate, Cerium Nitrate, Cerium Fluoride, Cerium Sulfate End Use Industry: Catalysts, Glass & Polishing, Electronics, Automotive Components, Ceramics Application: Exhaust Gas Treatment, Optical Polishing, UV Stabilizers, Alloy Additives, UV Absorption Form: Powder, Granules, Pellets, Solution |
| Companies Covered | Lynas Rare Earths Ltd, China Northern Rare Earth (Group) High-Tech Co., Ltd., Mitsui Mining & Smelting Co., Ltd., Shepherd Chemical, American Elements, Arafura Rare Earths Ltd, China Minmetals Rare Earth Co. Ltd., MP Materials, IREL (India) Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cerium Market Strategic Shifts & Innovations
Automotive catalyst architectures are demanding higher-purity cerium oxide grades with tighter particle size distribution. This specification creep is compressing margins for standard-grade producers while rewarding integrated refiners with separation expertise.
Nanostructured ceria-zirconia solid solutions with engineered oxygen vacancy density are rendering obsolete conventional micron-grade oxide loadings in three-way catalyst formulations. European OEM catalyst procurement teams are mandating these advanced materials for Euro 7 compliance programs. The shift is compressing specification tolerance bands from percent-level to parts-per-million impurity thresholds.
EPA Tier 3 emission standards are tightening sulfur tolerance requirements for gasoline catalyst systems. US refiners are reformulating washcoat compositions to maintain oxygen storage capacity under lean-burn conditions. California Air Resources Board certification protocols now specify accelerated aging tests that favor high-surface-area ceria stabilizers.
Long-term supply agreements are displacing spot market purchases among tier-one automotive catalyst manufacturers. Japanese and Korean automakers are locking in five-year oxide offtakes with Australian and US mining developers. This procurement consolidation is visible in contract structures that prioritize origin traceability over price flexibility.
Cerium Market Segmentation
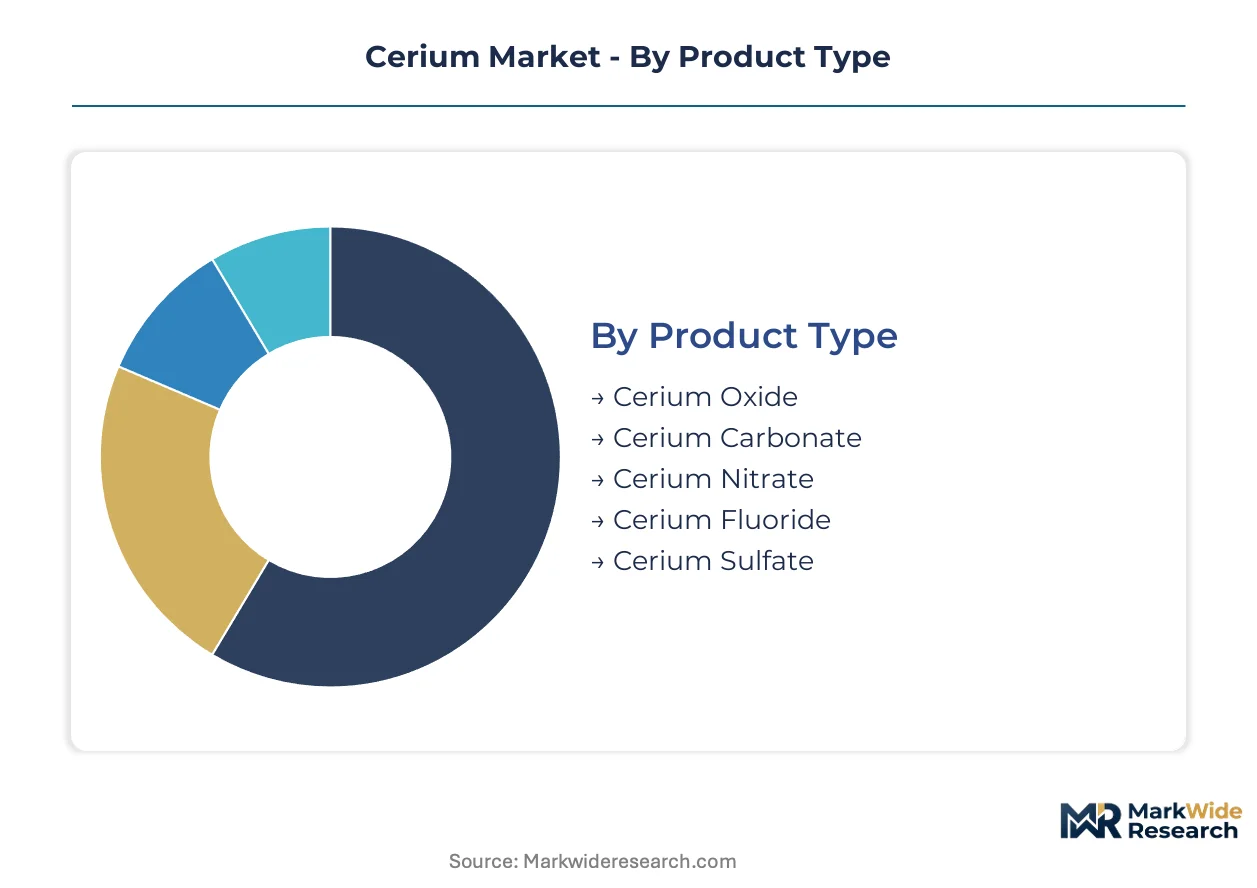
Cerium procurement patterns diverge sharply across product grades and application specifications. Automotive catalyst manufacturers drive premium oxide demand while glass polishers optimize for cost-efficient carbonate supply. Form factors and purity thresholds determine pricing tiers and supplier qualification requirements.
Product Type:
Mature oxide formulations anchor established revenue streams while specialty salts capture emerging specification premiums.
- Cerium Oxide:Dominates automotive catalyst washcoats through reversible Ce³⁺/Ce⁴⁺ oxygen storage capacity. EPA Tier 3 and Euro 7 compliance deadlines are tightening purity requirements to 99.9%+ grades for three-way catalyst formulations.
- Cerium Carbonate:Serves as the primary feedstock for glass decolorization and polishing compound manufacturing. Chinese refineries in Inner Mongolia and Jiangxi process carbonate intermediates before final oxide conversion.
- Cerium Nitrate:Enables precision deposition in electronics coating applications.
- Cerium Fluoride:Supports optical glass and specialized ceramic formulations.
- Cerium Sulfate:Finds niche use in chemical synthesis and laboratory reagent markets.
Cerium Oxide handles the majority of throughput; Cerium Carbonate is climbing the fastest on share as polishing applications expand.
End Use Industry:
Cost tier stratification separates specification-intensive catalyst demand from commodity-driven glass processing volume.
- Catalysts:Automotive exhaust systems consume high-purity oxide with sub-micron particle distribution. Korean and Japanese catalyst manufacturers are locking in long-term offtake agreements with Australian mining developers to bypass Chinese refining chokepoints.
- Glass & Polishing:Optical substrate finishing and glass decolorization drive volume procurement of standard-grade carbonate. German and Japanese specialty glasshouses face substitution pressure from neodymium-doped alternatives in premium applications.
- Electronics:Semiconductor polishing slurries demand precision particle control.
- Automotive Components:Alloy additives leverage cerium's oxygen scavenging properties.
- Ceramics:Structural and functional ceramic formulations utilize stabilized oxide phases.
Catalysts command the highest value per kilogram; Glass & Polishing moves the largest absolute tonnage.
Application:
Volume concentration in emission control systems contrasts with emerging traction in electronic materials.
- Exhaust Gas Treatment:Three-way catalyst architectures require nanostructured ceria-zirconia solid solutions with engineered oxygen vacancy density. California Air Resources Board certification protocols now specify accelerated aging tests that favor high-surface-area stabilizers.
- Optical Polishing:Silicon carbide wafer manufacturers in Taiwan and Germany consume precision-grade ceria slurries for substrate finishing. This application demands sub-micron particle distribution control and low trace metal contamination.
- UV Stabilizers:Polymer and coating formulations exploit cerium's absorption characteristics.
- Alloy Additives:Metallurgical applications improve oxidation resistance in specialty steels.
- UV Absorption:Sunscreen and cosmetic applications utilize cerium oxide nanoparticles.
Exhaust Gas Treatment anchors procurement volume; Optical Polishing is expanding most quickly on specification premiums.
Form:
Customer type differentiation separates dispersed powder users from integrated pellet consumers.
- Powder:Superior dispersion characteristics in catalytic washcoats make powder the default specification for automotive catalyst manufacturers. Powder form leads procurement across most end-use industries due to handling flexibility and blending uniformity.
- Granules:Glass melting furnaces prefer free-flowing granular feedstock for automated batching systems.
- Pellets:Integrated catalyst substrate producers utilize pre-formed pellets for direct washcoat application.
- Solution:Electronics coating and precision deposition processes require stabilized aqueous formulations.
Powder dominates shipment volume; Solution is gaining share fastest in semiconductor polishing applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in refined cerium oxide are reshaping procurement geography. Chinese processing restrictions have amplified Australian and North American mining development. Automotive catalyst manufacturers now diversify supply origins to mitigate quota-driven disruption risks.
China
Inner Mongolia and Jiangxi refining corridors dominate global oxide output. MIIT production quotas and SAMR export licensing constrain international availability. Baotou integrated operations anchor domestic capacity expansion despite dual carbon policy pressures.
United States
EPA Tier 3 emission standards tighten sulfur tolerance requirements for gasoline catalyst systems. California Air Resources Board certification protocols specify accelerated aging tests favoring high-surface-area stabilizers. Mountain Pass extraction assets feed emerging domestic separation circuit construction.
Germany
Euro 7 compliance deadlines mandate oxygen storage capacity upgrades for European automakers. ECHA REACH registration creates regulatory friction for spot market participants. German specialty glasshouses face substitution pressure from neodymium-doped alternatives in premium optical applications.
Japan
Korean and Japanese catalyst manufacturers lock in five-year oxide offtakes with non-Chinese mining developers. METI industrial policy supports rare earth stockpiling and recycling infrastructure. Japanese stack producers qualify cerium-stabilized zirconia for next-generation hydrogen fuel cell membrane fabrication.
Australia
Lynas Rare Earths leverages domestic mining assets to sustain non-Chinese supply security. Western Australian deposits provide bastnäsite concentrate feedstock bypassing Chinese refining chokepoints. Emerging developers pursue solvent extraction circuit construction to close downstream processing gaps.
Cerium Market Key Industry Players
On the supply side, the industry is consolidating around integrated miners with separation expertise and fragmented among specialty chemical distributors. State-affiliated Chinese refiners and Australian mining developers represent contrasting archetypes. Western developers pursue backward integration into oxide production while distributors emphasize specification breadth. Capacity expansion and long-term offtake contracting dominate competitive maneuvering.
Within the integrated mining tier, Lynas Rare Earths Ltd and China Northern Rare Earth (Group) High-Tech Co., Ltd. exemplify divergent geographic positioning. MP Materials occupies a position at the extraction-focused end of the value chain. Mitsui Mining & Smelting Co., Ltd. represents the diversified materials conglomerate archetype bridging mining and advanced materials fabrication.
| Leading Market Players |
|---|
| Lynas Rare Earths Ltd |
| China Northern Rare Earth (Group) High-Tech Co., Ltd. |
| Mitsui Mining & Smelting Co., Ltd. |
| Shepherd Chemical |
| American Elements |
| Arafura Rare Earths Ltd |
| China Minmetals Rare Earth Co. Ltd. |
| MP Materials |
| IREL (India) Limited |
| Others |
Cost & Logistics Intelligence
Freight corridors connecting Baotou to Shanghai ports transmit Chinese domestic oxide pricing power into global catalyst procurement, with logistics cost differentials separating premium-grade Australian supply from standard-grade carbonate shipments. This transport-cost wedge amplifies price stratification between integrated refiners and spot-market distributors serving automotive washcoat formulators.
Pricing Analysis
Next-generation nanostructured ceria-zirconia formulations command substantial premiums over conventional micron-grade oxide, while legacy carbonate grades face cost compression from neodymium-doped glass alternatives. Contract-based long-term offtake structures dominate procurement, with price differentiation driven by ISO 14001 certification status and volume scale commitments. Pricing pressure intensifies in standard-grade carbonate as Chinese export quotas tighten spot availability. Glass polishers exhibit highest price sensitivity; hydrogen fuel cell membrane manufacturers demonstrate lowest sensitivity due to qualification timelines.
Supply Chain Analysis
China's MIIT export licensing regime restricts oxide flows to automotive catalyst manufacturers in Germany, Japan, and the United States. Bastnäsite concentrate from Australia and the United States feeds separation circuits dependent on solvent extraction technology and rare earth cracking capacity. Single-source vulnerability concentrates in Chinese-controlled refining chokepoints. Distribution runs through integrated miners with captive oxide production and specialty chemical distributors serving spot requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where hydrogen fuel cell membrane qualification protocols are creating interoperability standards that will consolidate supplier tiers around certified oxide sources.
For Market Incumbents: Build regulatory moats through REACH dossier completion and EPA Tier 3 pre-certification investments. Secure backward integration into Australian bastnäsite mining to bypass Chinese quota restrictions. Expand solvent extraction capacity in Western jurisdictions before emerging developers capture non-Chinese supply security premiums. Neodymium-doped glass substitution threatens traditional carbonate volume in Japanese and German optical applications. For New Entrants and Emerging Players: Build out hydrogen fuel cell membrane supply relationships with Korean and Japanese stack producers before qualification windows close. Target precision-grade ceria slurry demand from Taiwan silicon carbide wafer manufacturers. Pursue BIS standards alignment in Odisha and Kerala to capture India PLI scheme downstream incentives. Qualify oxide through automotive catalyst distributor networks rather than direct OEM penetration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors separation-circuit developers with metallurgical expertise over pure-play mining assets. Five-to-ten year viability hinges on closing downstream processing gaps outside China. Monitor MP Materials and Lynas Rare Earths construction timelines as inflection indicators for non-Chinese oxide supply security. Acquisition targets should demonstrate solvent extraction operational readiness and automotive catalyst customer qualification progress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Separation Circuit Construction | Mountain Pass and Western Australian developers bypass Chinese refining chokepoints entirely. |
| Long-term Supply Agreement with Automotive Catalyst Tier 1s | Korean and Japanese automakers lock in origin-traceable oxide offtakes. |
| REACH Registration Completion for European Market Access | ECHA compliance removes regulatory friction for spot market participation. |
| Hydrogen Fuel Cell Membrane Qualification Program | Cerium-stabilized zirconia certification opens proton exchange membrane fabrication demand. |
| ISO 14001 Environmental Management Certification | Eighteen-to-twenty-four month accreditation timelines separate qualified from speculative capacity. |
Research Approach
The analysis maps automotive catalyst, glass polishing, and hydrogen fuel cell membrane sub-sectors, each validated through rare earth separation plant managers, automotive procurement leads, and glasshouse technical directors. Primary interviews with downstream OEMs and distribution channel partners combined with MIIT quota announcements, EPA emission rulemakings, and customs trade data support bottom-up and top-down triangulation.
Assumptions held fixed include Chinese dual carbon policy enforcement intensity and Euro 7 compliance deadline adherence, while oxide purity requirement trajectories and hydrogen fuel cell adoption curves were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product grade tier, end-use industry, and regional production hub. CAGRs were derived from production capacity buildout schedules and emission regulation implementation timelines. Forecast inputs incorporated bastnäsite concentrate availability and solvent extraction circuit commissioning progress.
Sensitivities concentrate around Beijing quota announcement timing and Brussels emission rulemaking acceleration. Forecasts reflect these documented assumptions. Material shifts in Chinese rare earth export licensing or hydrogen fuel cell membrane qualification standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
United States Metal Casting Market
Metals
Magnesium Metal Market
Metals
Battery Metals Market
Metals
Barium Market
Metals
Lithium Foil Market
Metals
Aluminum Scrap Recycling Market
Metals
Global Precious Metal Market
Metals
Metal Injection Molding (MIM) Parts Market
Metals
Beryllium Copper for Industrial Equipment Market
Metals
Europe Metal Casting Market
Metals
Global Galvanized Steel Wire Market
Metals
Steel Casting Market
Metals
Aluminum Tubes Market
Metals
Lightweight Aluminium Pistons Market
Metals
North America Aluminum Market
Metals
Huntite Market