
 Aluminum Hot Rolling Mill Market | 2026-2036
Aluminum Hot Rolling Mill Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Hot Rolling Mill Market Insights
The divergence between premium aerospace-grade coils and commodity construction sheet is repositioning how mill operators allocate furnace capacity and quality certification investments. Novelis Inc. leverages its recycling-integrated footprint to sustain margin stability across volatile ingot prices. Hindalco Industries Limited anchors South Asian supply through backward integration into bauxite and smelting. Norsk Hydro ASA differentiates via low-carbon primary metal streams that command preferential placement with European Automotive Suppliers.
Aluminum hot rolling mills reduce cast slabs or ingots to precise thicknesses between 2 and 250 millimeters at temperatures above 350°C, yielding wrought forms with directional grain structures optimized for subsequent cold forming or direct fabrication. Continuous Casting technology leads volume throughput for standardized coil, while Direct Chill Casting retains dominance in aerospace and defense plate where metallurgical homogeneity commands premium positioning. Thin Slab Casting is gaining share among newer installations serving automotive skin panel demand with reduced energy intensity per ton. Building Materials applications represent the mature volume base, whereas Transportation—particularly EV battery enclosure and body-in-white programs—carries the fastest expansion trajectory and deepest margin pools.
EPA emissions standards in the United States and REACH compliance obligations under ECHA in Europe are tightening allowable thresholds for rolling lubricants and surface treatment chemistries, forcing mill-level reformulation investments. China's MEE enforces dual carbon goals that constrain coal-fired reheating furnace operations and accelerate electric induction retrofits. Stakeholders must monitor how regulatory stringency divergence across these jurisdictions reshapes capital deployment timelines and equipment sourcing decisions without assuming harmonized compliance pathways.
Market Dynamics
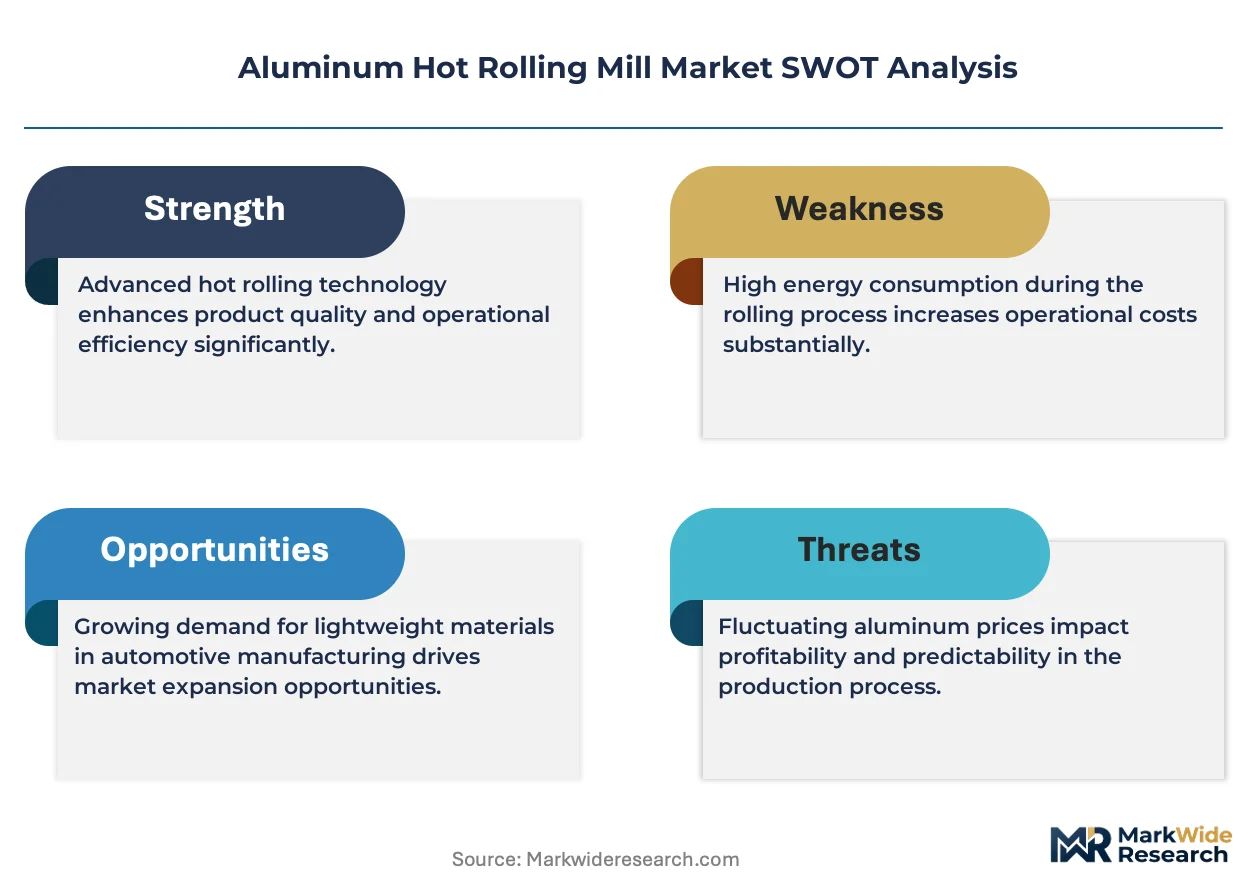
Thin Slab Casting adoption is compressing furnace energy intensity per ton and forcing legacy Continuous Casting operators to accelerate retrofit timelines or accept margin erosion in automotive-grade coil supply.
Growth Catalysts
- EU Green Deal carbon border adjustments:European Automotive Suppliers now demand low-carbon primary aluminum certification, redirecting procurement toward mills with verified Scope 3 emissions data.
- China's EV battery enclosure demand:Domestic EV production scaling is consuming hot-rolled coil at rates that outpace traditional construction sheet consumption growth.
- Direct Chill Casting for aerospace plate:Defense procurement programs in multiple jurisdictions are prioritizing metallurgical homogeneity standards that only this casting method reliably delivers.
Market Restraints
- Primary aluminum ingot price volatility:London Metal Exchange pricing swings compress rolling margins for non-integrated operators lacking captive smelting capacity.
- Bauxite supply concentration:Guinea and Australia dominate ore exports, creating geopolitical exposure for mills without diversified raw material sourcing.
- REACH compliance reformulation costs:ECHA-mandated rolling lubricant chemistry changes require capital-intensive mill-level equipment modifications.
Strategic Opportunities
- India's PLI scheme for automotive:Domestic component manufacturing incentives are creating localized demand for precision hot-rolled aluminum structural parts.
- Recycling-integrated mill configurations:Secondary aluminum feedstock integration reduces Scope 3 emissions and qualifies for preferential placement with carbon-conscious buyers.
- Induction furnace retrofits:China's MEE dual carbon enforcement is subsidizing electric reheating conversions that lower operational emissions intensity.
Industry Challenges
- Aerospace certification timelines:AS9100 and NADCAP accreditation cycles extend 18-24 months, delaying market entry for new plate suppliers.
- Skilled furnace operator scarcity:Temperature control precision for 350°C+ rolling requires specialized metallurgical training that regional vocational programs inadequately supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Hot Rolling Mill Market |
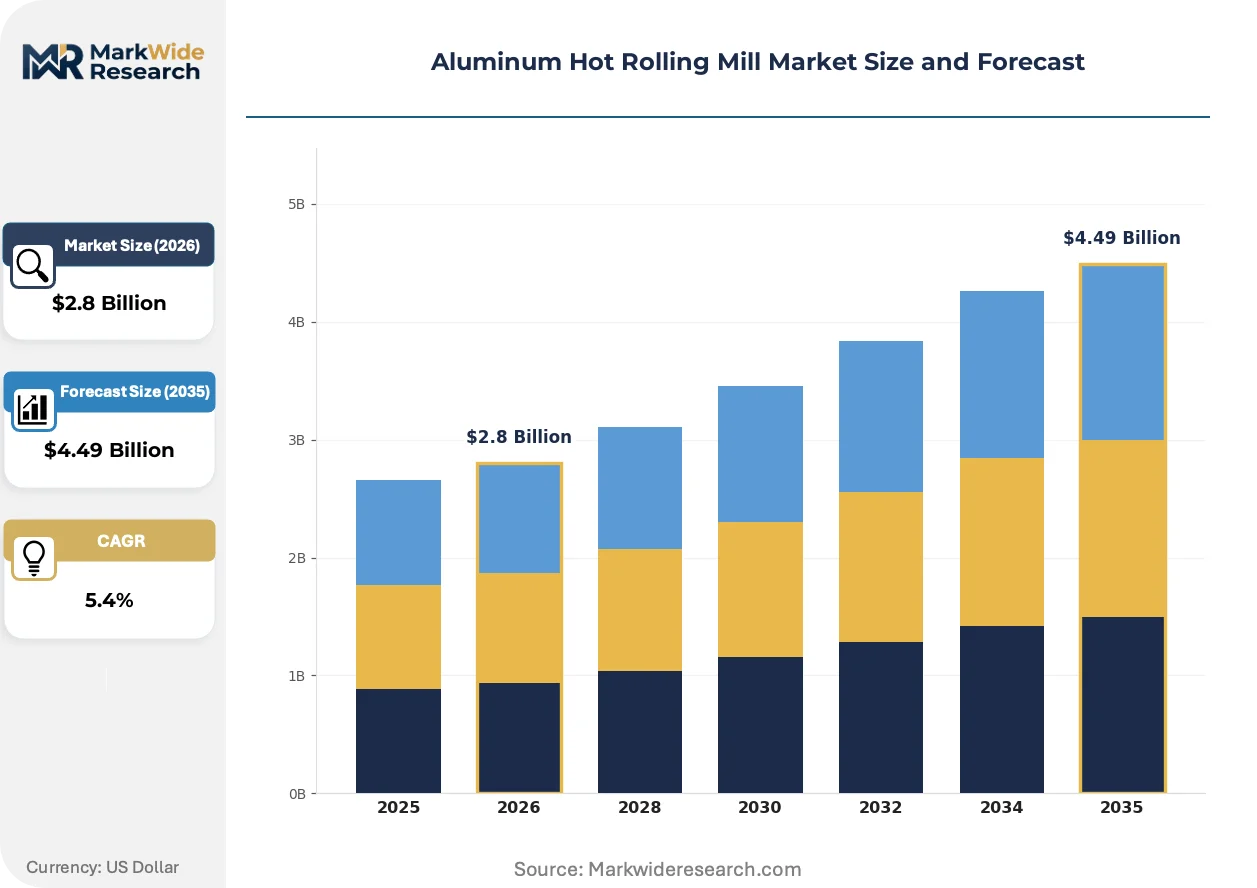
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Rolled Sheet, Hot Rolled Plate, Coil, Foil End User: Aerospace, Automotive Suppliers, Construction, Packaging Technology: Continuous Casting, Direct Chill Casting, DC Process, Thin Slab Casting Application: Building Materials, Transportation, Consumer Goods, Industrial Equipment |
| Companies Covered | Novelis Inc., Alcoa Corporation, Constellium, UACJ Corporation, Norsk Hydro ASA, Hindalco Industries Limited, Aluminum Corporation of China (Chalco), JW Aluminum, Arconic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Hot Rolling Mill Market Trends and Innovations
Digital twin deployment and predictive maintenance algorithms are reshaping mill uptime economics, while regulatory emissions tracking is becoming a competitive differentiator rather than a compliance cost.
Thin Slab Casting technology reduces slab thickness at the casting stage, eliminating multiple reheating cycles before final rolling. Automotive skin panel producers in Germany and Japan are adopting this method to meet OEM energy-per-ton targets. The technology is decentralizing capacity planning decisions away from centralized engineering teams toward plant-level optimization units.
EPA emissions standards for rolling lubricants are tightening volatile organic compound thresholds in the United States. Mill operators must reformulate surface treatment chemistries or face enforcement actions. California-based suppliers serving aerospace are absorbing the highest compliance costs and passing through premiums to defense contractors.
Automotive OEMs are consolidating hot-rolled coil suppliers to reduce qualification overhead for EV platform launches. Tier-1 stamping operations in Michigan and Bavaria are shifting from spot purchasing to multi-year offtake agreements with volume commitments. This concentration is most visible in battery enclosure programs where crashworthiness certification locks in supplier relationships for entire vehicle generations.
Aluminum Hot Rolling Mill Market Segmentation
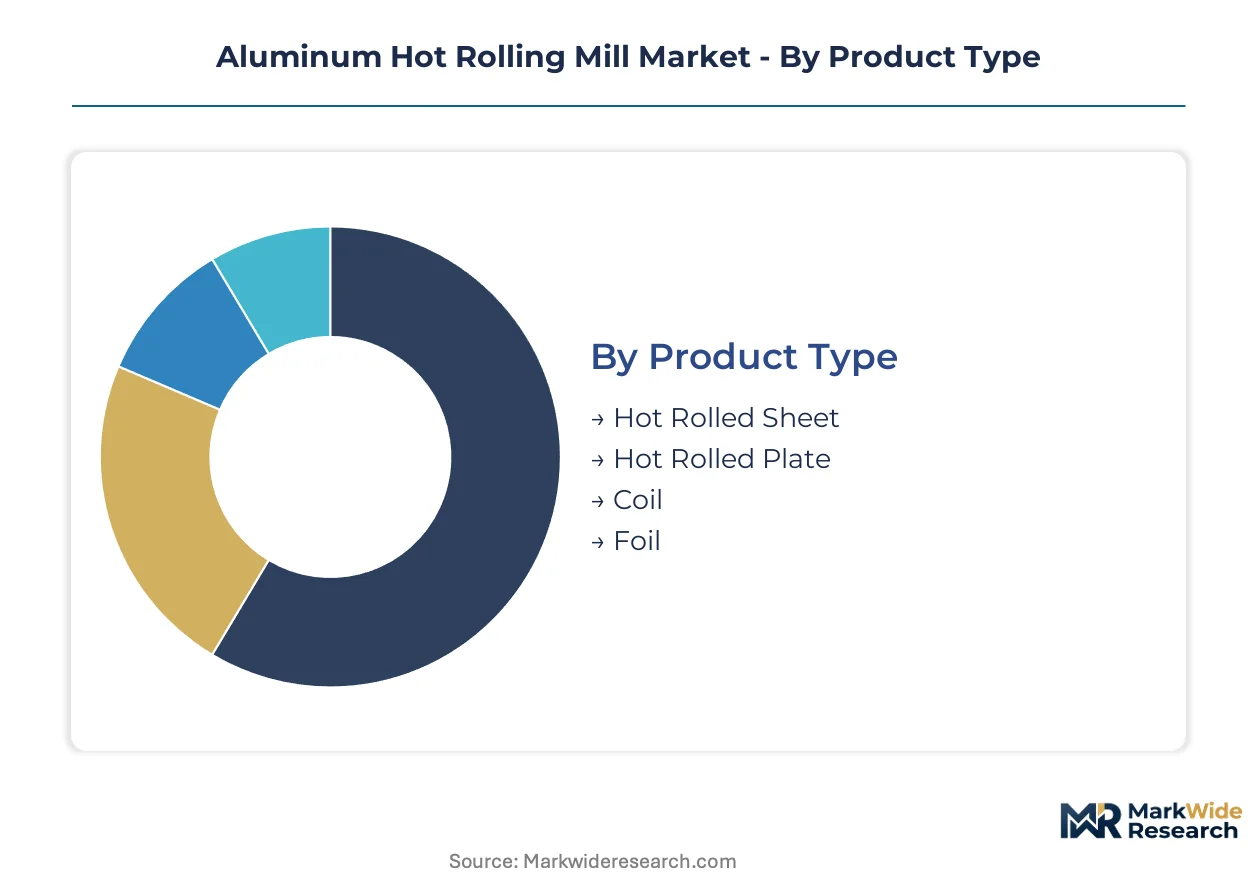
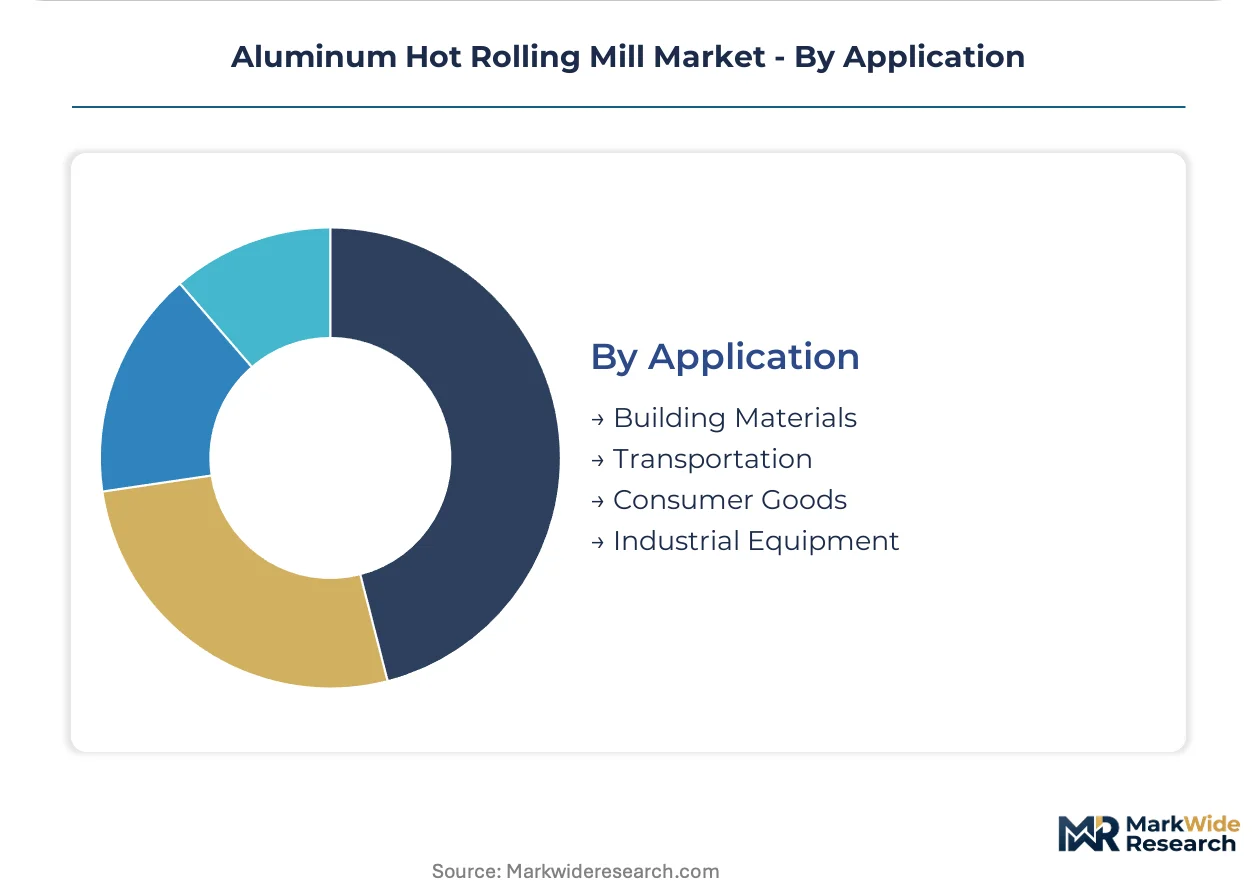
Aluminum hot rolling mill output splits across product forms, end-use specifications, casting technologies, and application sectors. Each dimension carries distinct margin profiles, certification requirements, and capital intensity thresholds that determine competitive positioning.
Product Type:
Customization intensity spans from standardized commodity coil to specification-critical aerospace plate, with thickness tolerance and surface finish requirements dictating furnace configuration and quality system investments.
- Hot Rolled Sheet:Thickness ranges from 2 to 6 millimeters with moderate surface finish requirements. Automotive Suppliers in Germany and Japan consume this grade for body-in-white structural stampings where OEM energy-per-ton targets favor thin slab casting integration.
- Hot Rolled Plate:Thickness exceeds 6 millimeters with stringent metallurgical homogeneity standards. Defense procurement programs across multiple jurisdictions prioritize this form for armor and airframe applications where Direct Chill Casting certification remains mandatory.
- Coil:Continuous wound format optimized for high-volume processing lines.
- Foil:Ultra-thin gauges below 0.2 millimeters requiring specialized rolling mill configurations.
Leading the category by volume: Coil. Growing fastest: Hot Rolled Sheet.
End User:
Customer sophistication tiers separate AS9100-certified aerospace primes from commodity construction distributors, with procurement patterns dictating contract duration and technical service intensity.
- Aerospace:AS9100 and NADCAP accreditation requirements extend qualification cycles to 18-24 months. OEMs in Toulouse and Seattle mandate lot-level chemical certification for plate used in wing spar and fuselage applications.
- Automotive Suppliers:Tier-1 stamping operations in Michigan and Bavaria are consolidating supplier bases under multi-year offtake agreements. EV battery enclosure programs lock in relationships for entire vehicle generations through crashworthiness certification requirements.
- Construction:Volume base for standardized sheet in building cladding and roofing systems.
- Packaging:Foil and thin-gauge coil for food and pharmaceutical containment.
Construction maintains the largest volume position. Automotive Suppliers command the steepest expansion trajectory.
Technology:
Energy intensity per finished ton varies dramatically across casting methods, with newer installations capturing automotive skin panel demand through reduced reheating cycles.
- Continuous Casting:High-throughput method for standardized coil production. Legacy operators face margin compression as thin slab casting adopters achieve lower energy intensity per ton in automotive-grade supply.
- Direct Chill Casting:Water-cooled mold solidification yields superior metallurgical homogeneity. This method retains dominance in aerospace and defense plate where premium positioning depends on consistent grain structure.
- DC Process:Variant configuration for specialized alloy development.
- Thin Slab Casting:Reduces slab thickness at casting stage, eliminating multiple reheating cycles. Installations in Germany and Japan serve automotive OEM energy targets.
Continuous Casting dominates current installed capacity. Thin Slab Casting gains share fastest among new investments.
Application:
Margin pools concentrate in transportation applications where lightweighting specifications command technical premiums, while building materials represent the mature volume foundation.
- Building Materials:Mature demand base for cladding, roofing, and structural sheet. China's domestic construction cycle absorbs substantial coil volume at compressed margins.
- Transportation:EV battery enclosures and body-in-white programs carry the deepest margin pools. China's domestic EV production scaling consumes hot-rolled coil at rates outpacing traditional construction growth.
- Consumer Goods:Appliance and electronics housings requiring moderate formability.
- Industrial Equipment:Machinery frames and process vessels with standard mechanical property requirements.
Building Materials leads by tonnage. Transportation climbs the fastest with EV platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chongqing's aluminum processing corridor dominates China's hot rolling capacity expansion, with domestic EV manufacturers consuming coil volumes that outpace traditional construction demand. Germany's Ruhr industrial basin and Japan's Kansai region anchor precision-grade supply for automotive skin panels.
China
Domestic EV battery enclosure programs in Shenzhen and Shanghai are absorbing hot-rolled coil at unprecedented rates. The MEE enforces dual carbon goals that constrain coal-fired reheating furnaces and subsidize electric induction retrofits. Chongqing's aluminum corridor hosts the fastest capacity additions serving BYD and CATL supply chains.
Germany
BMW and Volkswagen battery platform launches in Bavaria are consolidating multi-year offtake agreements with precision coil suppliers. The EU Green Deal's carbon border adjustments redirect procurement toward mills with verified Scope 3 emissions data. The Ruhr Basin retains concentration in automotive-grade thin slab casting installations.
United States
Michigan-based Tier-1 stampers are locking in supplier relationships for EV body-in-white programs spanning entire vehicle generations. EPA emissions standards tighten volatile organic compound thresholds for rolling lubricants, forcing reformulation investments. The Detroit-Toledo corridor concentrates qualification activity for crashworthiness-certified battery enclosures.
India
PLI scheme incentives for automotive component manufacturing are creating localized demand for precision structural parts in Tamil Nadu and Gujarat. BIS certification requirements for aluminum construction products are tightening quality system investments. The Delhi-Mumbai Industrial Corridor hosts emerging capacity serving Maruti Suzuki and Tata Motors programs.
Japan
Toyota and Honda lightweighting programs in Aichi Prefecture prioritize thin slab casting integration for OEM energy-per-ton targets. METI industrial decarbonization roadmaps accelerate furnace electrification timelines. The Kansai region's Osaka-Kobe cluster maintains dominance in high-surface-finish automotive skin panel supply.
Aluminum Hot Rolling Mill Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity and captive raw material access. The vendor base concentrates among integrated aluminum producers with smelting capacity and specialized engineering houses serving retrofit demand. Three archetypes dominate: recycling-integrated multinationals with Scope 3 advantages, state-backed Chinese champions with domestic EV capture, and European low-carbon specialists commanding carbon-border premiums. Competitive moves center on thin slab casting technology licensing and backward integration into bauxite sourcing.
Among the recycling-integrated tier, Novelis Inc. and Hindalco Industries Limited exemplify margin stability through secondary feedstock control. Norsk Hydro ASA occupies a position within the low-carbon primary metal segment that qualifies for EU Green Deal preferential placement. Chinese state-backed capacity represented by Aluminum Corporation of China anchors volume scale in domestic EV supply chains.
| Leading Market Players |
|---|
| Novelis Inc. |
| Alcoa Corporation |
| Constellium |
| UACJ Corporation |
| Norsk Hydro ASA |
| Hindalco Industries Limited |
| Aluminum Corporation of China (Chalco) |
| JW Aluminum |
| Arconic |
| Others |
Pricing and Supply Chain Analysis
Thin Slab Casting adoption simultaneously compresses energy costs per ton and redistributes pricing power toward mills with newer installations serving automotive OEM targets. London Metal Exchange volatility for primary aluminum ingot amplifies margin divergence between integrated smelter operators and non-integrated rolling specialists.
Pricing Analysis
Contract-based long-term offtake agreements anchor value-based pricing for automotive-grade coil, with crashworthiness certification locking in supplier relationships across entire vehicle generations. Price differentiation separates AS9100-certified aerospace plate from commodity construction sheet, with metallurgical homogeneity standards commanding substantial premiums. Cost compression in standardized coil supply intensifies as thin slab casting operators achieve lower energy intensity per ton. Construction distributors exhibit highest price sensitivity due to spot purchasing patterns, while EV battery enclosure programs demonstrate lowest sensitivity given qualification lock-in requirements.
Supply Chain Analysis
Scrap aluminum collection and secondary feedstock reintegration flows are reshaping raw material procurement economics for recycling-integrated operators. Guinea, Australia, and Indonesia concentrate bauxite supply, creating geopolitical exposure for mills lacking diversified ore sourcing. Rolling lubricant chemistry and high-purity alloying elements draw from specialized chemical suppliers concentrated in Germany and Japan. Tariff exposure on primary aluminum imports threatens margin stability for North American operators without captive smelting. Distribution runs through mill-direct relationships with Tier-1 automotive stampers and regional service centers for construction sheet.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Aluminum Hot Rolling Mill Market sits in a casting-technology transition phase, with Thin Slab Casting displacing legacy Continuous Casting configurations in automotive-grade supply.
For Market Incumbents: Cement backward integration into bauxite and smelting capacity to insulate rolling margins from London Metal Exchange volatility. Accelerate AS9100 and NADCAP accreditation investments to defend aerospace plate positioning against emerging Chinese capacity. Prioritize induction furnace retrofits to qualify for EU Green Deal carbon border preferential placement. For New Entrants and Emerging Players: Digital platform-enabled supplier qualification tools offer a route to bypass traditional 18-24 month aerospace certification barriers through predictive compliance documentation. Target India's PLI scheme automotive component manufacturing incentives in Tamil Nadu and Gujarat for localized precision structural parts supply. Pursue recycling-integrated mill configurations to capture Scope 3 emissions advantages with European Automotive Suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in recycling-integrated multinationals with verified secondary feedstock control and low-carbon primary metal specialists commanding EU Green Deal premiums. Long-term viability favors operators with captive bauxite access and thin slab casting technology licensing positions. Monitor China's MEE dual carbon enforcement intensity as the inflection signal for electric furnace retrofit subsidy durability.| Strategic Initiative | Industry Significance |
|---|---|
| Thin Slab Casting Technology Licensing | German and Japanese automotive OEMs prioritize energy-per-ton targets that only this method reliably achieves. |
| Backward Integration into Bauxite Mining | Guinea and Australia ore concentration creates geopolitical exposure that captive supply mitigates. |
| Induction Furnace Electrification Retrofit | China's MEE subsidizes conversions that lower operational emissions intensity for dual carbon compliance. |
| AS9100 Aerospace Certification Investment | Toulouse and Seattle OEMs mandate lot-level chemical certification for wing spar and fuselage plate supply. |
| Recycling-Integrated Mill Configuration | Secondary aluminum feedstock reduces Scope 3 emissions and qualifies for EU Green Deal preferential placement. |
Research Methodology
Trade association filings, customs export databases, and SEC 10-K disclosures formed the secondary backbone for capacity and margin analysis. Primary interviews with rolling mill operations directors, Tier-1 automotive procurement managers, and EPC contractors specialized in furnace retrofits validated technology adoption timelines. Bottom-up and top-down triangulation reconciled equipment installation data with end-use consumption patterns across automotive, aerospace, and construction segments.
Bottom-up modeling aggregated individual mill capacity, technology configuration, and end-use certification positions, while top-down analysis cross-checked against regional aluminum consumption surveys and OEM platform launch schedules. Segmentation dimensions included product thickness grade, casting technology type, end-use certification tier, and regional regulatory cluster. CAGRs derived from equipment investment pipelines and EV production scaling trajectories. Forecast inputs incorporated MEE dual carbon enforcement intensity and EU Green Deal carbon border adjustment implementation pace.
The model holds under sustained EV platform rollout schedules and current MEE subsidy levels; deviation in bauxite supply disruption or REACH compliance timeline acceleration would shift capacity expansion trajectories. Practitioners should monitor London Metal Exchange volatility spikes and aerospace defense procurement program announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Ferrochrome Market
Metals
Aluminum Ingots Market
Metals
Titanium Sponge Market
Metals
Aluminum Casting Market
Metals
Motor Lamination Material Market
Metals
Ferro Vanadium Market
Metals
TMCP Steel Market
Metals
Stainless Steel 400 Series Market
Metals
Base Metals Market
Metals
Carbon Steel Market
Metals
Reconditioned Steel Drums Market
Metals
Global Stretch Spring Wire Market
Metals
Huntite Market
Metals
Aluminum Welding Wires Market
Metals
Steel Drums Market
Metals
Middle-East and Africa Metal Finishing Market