
 Ore Metals Market | 2026-2036
Ore Metals Market Size, Share, and Industry Trends Forecast 2026-2036
Ore Metals Market Analysis
Subscription-based ore-grade analytics and predictive maintenance contracts for autonomous haul fleets is hardening the commercial model around throughput guarantees rather than commodity spot exposure. Vale leverages its integrated logistics network across Brazilian iron ore corridors to sustain mine-to-port cost advantages. Rio Tinto anchors its position through proprietary autonomous drilling and rail systems that dominate Pilbara operations. BHP Group competes via diversified copper-nickel assets that extend exposure to electrification metal demand.
Ore metals encompass naturally occurring mineral deposits containing economically extractable base and ferrous metals, typically requiring crushing, grinding, flotation, and smelting to achieve commercial grades of 62% Fe for iron ore or 99.9% purity for electrolytic copper. Their primary purpose lies in supplying feedstock for steelmaking, wire rod casting, and alloy production that underpins industrial infrastructure. Iron ore shipments to construction and automotive buyers command the largest revenue pool, while nickel ore directed toward battery precursor manufacturers represents the fastest-expanding application segment. Open-pit extraction methods retain margin dominance through scale economies, though underground mining for high-grade copper deposits captures premium pricing in concentrate markets.
China's MEE enforces tailings storage facility standards that constrain unlicensed ore processing, while Australia's EPA mandates progressive rehabilitation bonds that reshape mine closure economics. ISO 14001 environmental management certification increasingly gates supplier eligibility for European automotive and aerospace OEM procurement frameworks. Stakeholders must monitor how carbon border adjustment mechanisms and scope-three emissions disclosure requirements redefine competitive access to integrated steel mill and battery cell manufacturer supply chains.
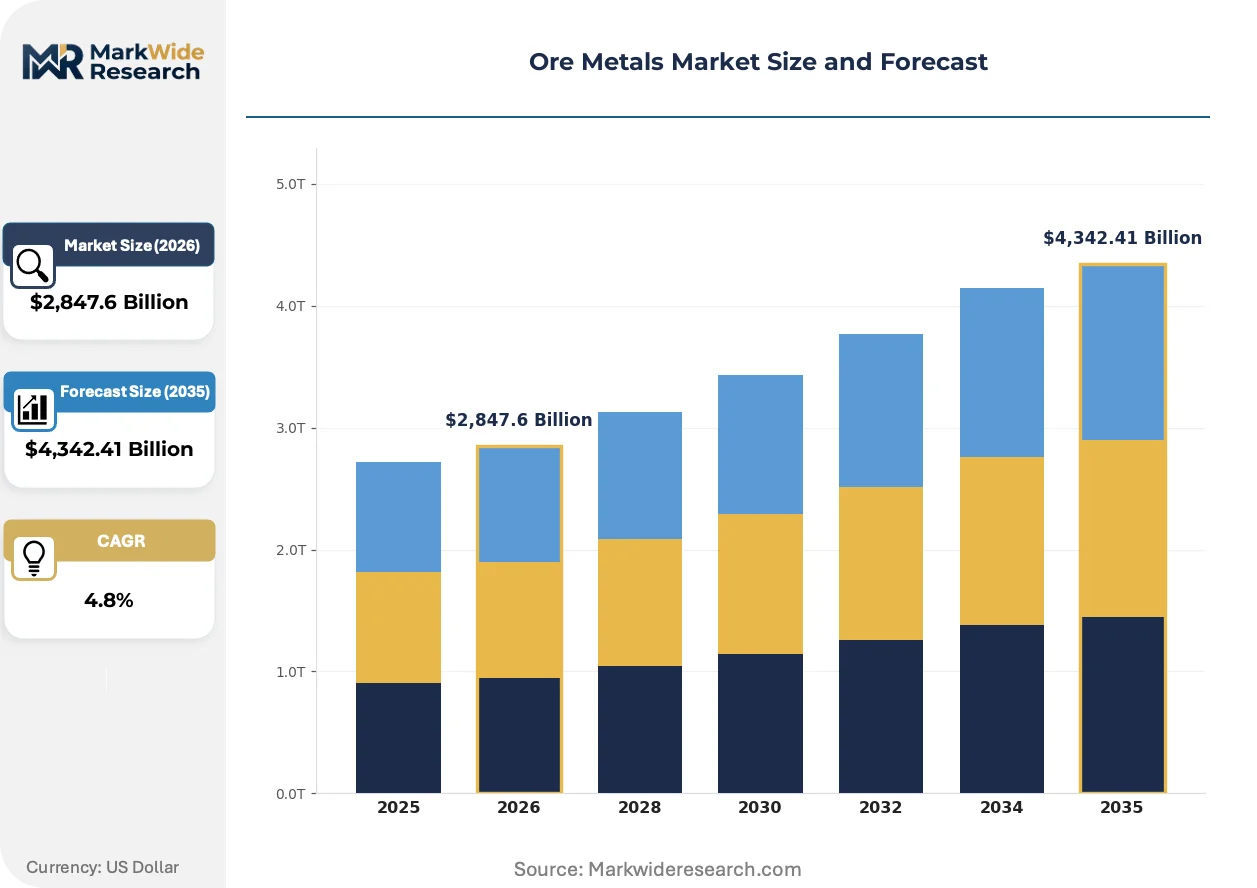
Market Dynamics
Autonomous haulage systems and predictive ore-grade analytics are compressing operating margins and forcing asset owners toward throughput-guaranteed service contracts rather than spot commodity exposure.
Growth Catalysts
- Electric vehicle cathode demand:Battery manufacturers are accelerating offtake agreements for refined nickel and copper concentrates to secure precursor supply chains.
- China's MEE tailings standards:Stricter enforcement is shuttering unlicensed processing capacity and redirecting concentrate flows toward compliant Australian and Brazilian exporters.
- Autonomous drilling adoption:Rio Tinto's proprietary Pilbara systems are setting throughput benchmarks that force competitors to accelerate fleet modernization.
Market Restraints
- Indonesian nickel laterite concentration:Processing capacity clustering in Sulawesi and Halmahera creates single-point-of-failure risk for battery-grade nickel supply.
- Energy input cost volatility:Diesel and electricity account for 25-35% of open-pit cash costs, exposing margin compression during fuel price spikes.
- High-grade copper deposit depletion:Underground mining depth extensions face technical barriers that concentrate premium concentrate supply among legacy assets.
Strategic Opportunities
- Western Australian Pilbara expansion:Greenfield iron ore developments with integrated rail-port infrastructure can capture seaborne premium pricing.
- EU Carbon Border Adjustment Mechanism:Scope-three emissions disclosure requirements create first-mover advantage for low-carbon concentrate suppliers.
- Sensor-based ore sorting convergence:Machine vision and X-ray transmission integration is enabling real-time grade control that reduces downstream processing waste.
Industry Challenges
- Autonomous systems integration:Legacy fleet retrofits require specialized mechatronics expertise that concentrates among a narrow contractor base.
- Progressive rehabilitation bonds:Australia's EPA mandates are extending closure liability timelines and reshaping project finance structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ore Metals Market |
| Market Size in 2026 | $2,847.6 Billion |
| Market Size in 2035 | $4,342.41 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iron Ore, Copper Ore, Bauxite, Nickel Ore Application: Construction, Automotive, Electronics, Aerospace Extraction Method: Open-Pit Mining, Underground Mining, Alluvial Mining, Placer Mining End User: Manufacturers, Traders, Exporters, Industrial Plants |
| Companies Covered | Vale, China Molybdenum, Glencore, Fortescue Metals Group, Newmont Corporation, BHP Group, ArcelorMittal Mining, MMC Norilsk Nickel, Rio Tinto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ore Metals Market Emerging Trajectories
Digital twin deployment and sensor fusion are collapsing the lag between extraction decisions and processing outcomes, compressing the traditional mine-to-mill optimization cycle.
Real-time ore characterization using combined X-ray fluorescence and laser-induced breakdown spectroscopy is integrating into autonomous drill rigs. Major Pilbara operators are retrofitting blasthole drills with these sensors to enable selective blasting and load-haul dispatch optimization. This integration is compressing grade variability penalties and reducing downstream beneficiation costs.
China's MEE is enforcing tailings storage facility stability standards that mandate independent dam safety audits and real-time monitoring instrumentation. Unlicensed capacity closures are redirecting concentrate demand toward Australian EPA-compliant exporters. Indonesian laterite processors are responding by accelerating dry-stack tailings investments to maintain offtake eligibility.
Battery cell manufacturers are consolidating cathode precursor procurement through long-term offtake contracts rather than spot concentrate purchases. This channel shift is disintermediating traditional traders and forcing miners to integrate directly with precursor chemical plants. The pattern is most visible in nickel laterite offtake negotiations linking Indonesian processing hubs to South Korean and Japanese battery material divisions.
Ore Metals Market Segmentation
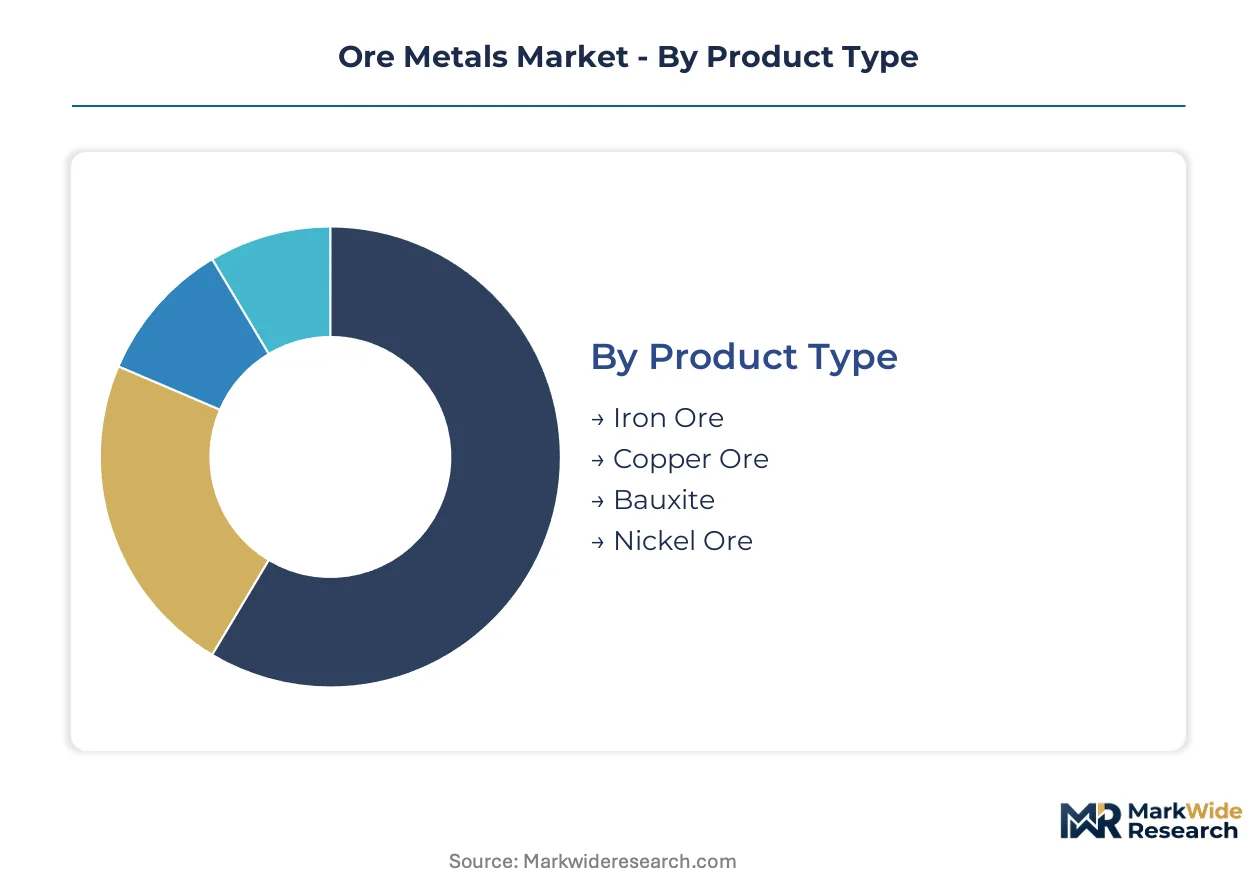
Ore metals segmentation reveals divergent capital requirements across extraction methods and product categories. Capital allocation decisions hinge on grade profiles, infrastructure intensity, and downstream integration options.
Product Type:
Iron ore demands the heaviest upfront infrastructure investment due to rail-port integration requirements, while nickel laterite processing carries steep hydrometallurgical capital intensity.
- Iron Ore:Hematite and magnetite deposits require beneficiation to achieve 62% Fe benchmark grades for blast furnace feed. Pilbara producers anchor seaborne supply through integrated heavy-haul rail networks serving Chinese steel mills facing MEE emissions scrutiny.
- Copper Ore:Sulfide and oxide ores concentrate in porphyry deposits demanding milling, flotation, and smelting to reach 99.9% electrolytic purity. Chilean and Peruvian open-pit operations feed wire rod casting for electrification infrastructure.
- Bauxite:Lateritic aluminum ore requires Bayer process refining to produce alumina for smelter feedstock. Guinea-Australian supply corridors dominate Atlantic basin shipments.
- Nickel Ore:Laterite and sulfide deposits supply battery precursor and stainless steel markets. Indonesian processing hubs concentrate HPAL and RKEF capacity for cathode material offtake.
Iron ore absorbs the bulk of installed capacity; nickel ore is expanding most quickly.
Application:
Construction and automotive applications generate divergent margin profiles based on steel grade specifications and alloy complexity requirements.
- Construction:Rebar and structural steel demand drives consumption of lower-grade iron ore fines processed through sintering. Chinese property sector fluctuations redirect spot cargo flows toward Indian and Southeast Asian infrastructure projects.
- Automotive:Advanced high-strength steel and aluminum body-in-white applications require pelletized iron ore and metallurgical-grade bauxite. European OEM procurement frameworks increasingly gate supplier eligibility through ISO 14001 certification.
- Electronics:High-purity copper cathode feeds printed circuit board and semiconductor interconnect manufacturing. Korean and Japanese smelters dominate cathode refining for this channel.
- Aerospace:Titanium and aluminum alloys demand specialized ore grades with tight impurity tolerances. Superalloy nickel requirements concentrate among a narrow base of certified processors.
Construction commands the largest volume share; electronics applications are climbing the fastest.
Extraction Method:
Open-pit operations achieve scale economies through truck-shovel fleets, while underground methods capture premium pricing for high-grade copper deposits.
- Open-Pit Mining:Surface benching and haulage systems exploit near-surface deposits with favorable stripping ratios. Autonomous haulage adoption in Western Australia compresses unit operating costs below underground alternatives.
- Underground Mining:Block caving and cut-and-fill methods access deep ore bodies with grades exceeding open-pit thresholds. Chilean porphyry extensions face technical barriers that concentrate premium concentrate supply among legacy assets.
- Alluvial Mining:Surface excavation of unconsolidated sediments targets placer deposits with minimal overburden removal. Artisanal and small-scale operations dominate certain tantalum and tin ore segments.
- Placer Mining:Water-based separation recovers heavy minerals from alluvial deposits. Limited scale constrains commercial significance outside precious metals and rare earth applications.
Open-pit mining anchors the bulk of production volume; underground methods retain the steepest margin expansion trajectory.
End User:
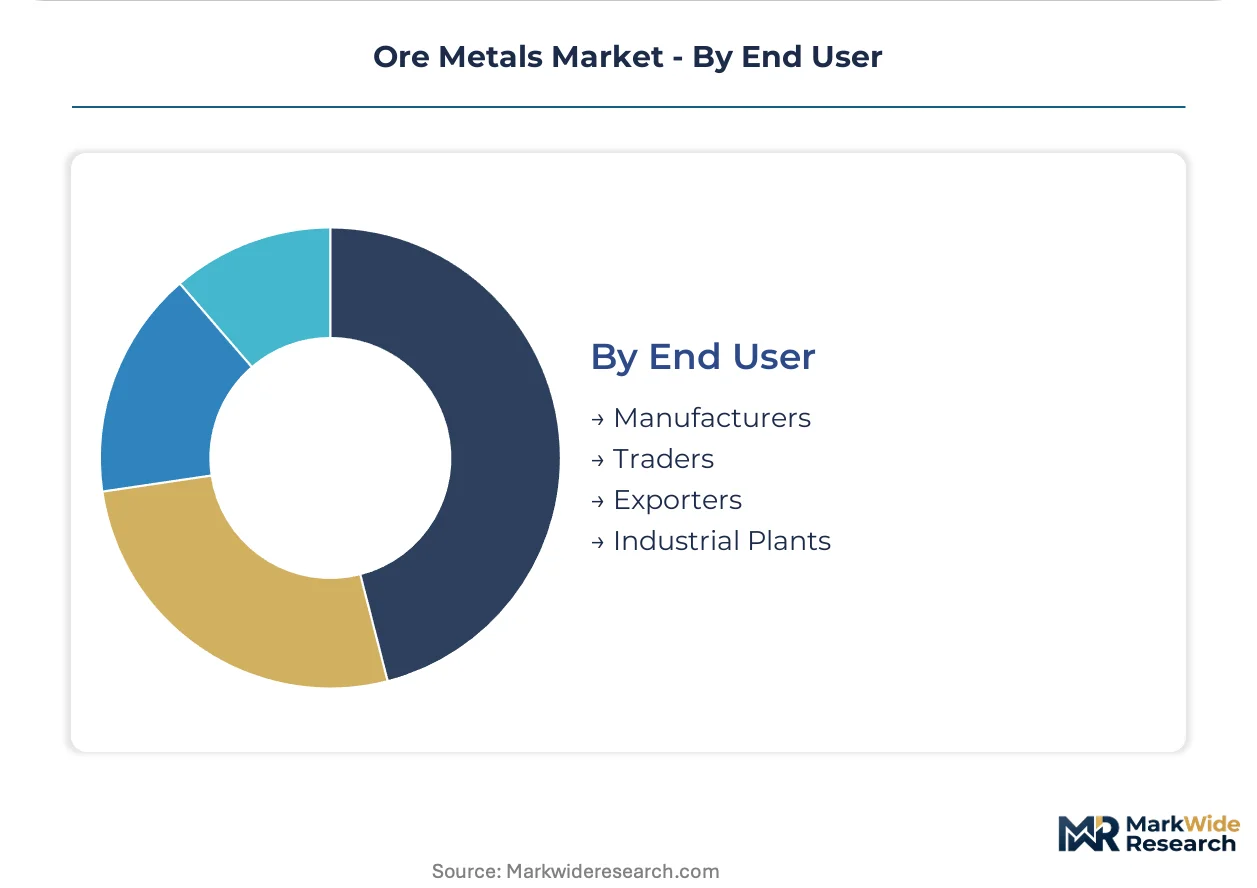
Industrial plants and manufacturers exhibit contrasting procurement patterns between long-term offtake contracts and spot market exposure.
- Manufacturers:Integrated steel mills and smelters source raw ore feedstock for captive processing. Chinese state-owned enterprises dominate procurement volumes through annual contract negotiations.
- Traders:Merchants arbitrage grade differentials and freight spreads across regional markets. Concentrate blending operations in Singapore and Rotterdam intermediate between miners and consumers.
- Exporters:National champions and diversified miners coordinate mine-to-port logistics for seaborne delivery. Brazilian and Australian exporters leverage dedicated rail corridors and deepwater terminal capacity.
- Industrial Plants:Battery precursor chemical plants and specialty alloy foundries procure refined concentrates with tight specification requirements. South Korean cathode material divisions consolidate nickel laterite offtake through direct miner integration.
Industrial plants capture the dominant procurement volume; battery precursor chemical plants are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara iron ore district in Western Australia anchors seaborne supply chains serving Asian steel mills. Autonomous haulage corridors and deepwater port infrastructure concentrate extraction capacity in this sparsely populated region.
Australia
Western Australia's Pilbara region hosts Rio Tinto and BHP Group's integrated rail-port networks feeding Chinese blast furnaces. The country's EPA mandates progressive rehabilitation bonds that extend mine closure liability timelines. Port Hedland and Dampier terminals handle the bulk of hematite shipments to East Asian steelmakers facing MEE emissions scrutiny.
China
Domestic iron ore consumption from Hebei and Liaoning provinces supports the world's largest steel output, though import dependence remains acute. The MEE enforces tailings storage facility standards that shutter unlicensed processing capacity. Shandong and Jiangsu steel clusters redirect concentrate demand toward compliant Australian and Brazilian exporters.
Brazil
Vale's integrated logistics network across Minas Gerais and Pará states sustains mine-to-port cost advantages in iron ore corridors. Stricter tailings dam regulations following Brumadinho have forced extraction method upgrades. The Carajás mineral province concentrates high-grade hematite deposits with favorable stripping ratios.
Indonesia
Sulawesi and Halmahera islands concentrate nickel laterite processing capacity for battery precursor supply chains. HPAL and RKEF investments respond to South Korean and Japanese cathode material offtake negotiations. Dry-stack tailings adoption maintains eligibility for European automotive OEM procurement frameworks.
Chile
Atacama Desert porphyry deposits feed copper concentrate to wire rod casting for electrification infrastructure. State-owned Codelco and private operators face technical barriers extending underground mining depths. Antofagasta and Calama clusters anchor smelter feedstock supply to Asian fabricators.
Ore Metals Market Vendor Landscape
Capital-heavy producers compete with asset-light traders across a tiered structure where integrated miners control logistics corridors while merchants arbitrage grade differentials. The vendor base consolidates around national champions with captive rail-port infrastructure and diversified miners with copper-nickel exposure to electrification metal demand. Three archetypes dominate: integrated logistics operators, diversified base metal miners, and pure-play iron ore exporters. Competitive intensity centers on autonomous fleet modernization and direct precursor chemical plant integration.
Among diversified mining conglomerates, BHP Group and Rio Tinto exemplify the integrated logistics archetype through Pilbara autonomous systems and heavy-haul rail dominance. Vale occupies a position representing Brazilian corridor control with mine-to-port cost engineering. Glencore sits within the trader-miner hybrid tier, anchoring concentrate arbitrage across regional blending operations.
| Leading Market Players |
|---|
| Vale |
| China Molybdenum |
| Glencore |
| Fortescue Metals Group |
| Newmont Corporation |
| BHP Group |
| ArcelorMittal Mining |
| MMC Norilsk Nickel |
| Rio Tinto |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in Brazil and Australia anchor supply discipline through captive rail-port infrastructure, translating logistics control into contract pricing power against spot market volatility. Their financing structures prioritize throughput guarantees over commodity exposure, compressing margin variability for integrated operators while squeezing trader intermediaries.
Pricing Analysis
Value-based pricing anchored to blast furnace yield performance dominates iron ore procurement, with Pilbara hematite commanding premiums over Brazilian blends due to lower alumina penalties. Price differentiation hinges on Fe grade consistency and MEE emissions compliance certification, with Chinese steel mills showing highest sensitivity to delivered cost spikes. Cost compression in mid-grade concentrates is intensifying because Indonesian nickel laterite supply expansion is redirecting capital toward battery precursor integration.
Supply Chain Analysis
Freight cost differentials between Capesize bulk routes from Port Hedland and Tubarão determine competitive access to Chinese blast furnaces, with Australian exporters holding structural advantages. Supply concentrates in Australia, Brazil, and Indonesia, with concentrate flows drawing from Pilbara iron ore corridors, Carajás hematite deposits, and Sulawesi nickel laterite belts. Single-source vulnerability clusters in Indonesian HPAL processing capacity. Distribution runs through long-term offtake contracts disintermediating traditional traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous haulage systems are displacing legacy truck-shovel fleets, forcing asset owners toward predictive maintenance subscriptions rather than capital-intensive fleet ownership. This technology transition rewards operators with proprietary drilling and rail integration.
For Market Incumbents: Extend autonomous fleet modernization to compress unit operating costs below underground alternatives, while accelerating direct cathode precursor integration to capture battery supply chain margin. Threat substitution from dry-stack tailings compliance requirements in Indonesia and Australia demands EPA-grade environmental certification investment as a defensive moat.
For New Entrants and Emerging Players: Premium-to-economy price gaps in high-grade copper concentrate present white-space entry points for junior developers with porphyry extensions in Chilean Atacama clusters. Target unlicensed Chinese processing capacity displacement by Australian EPA-compliant exporters. Go-to-market leverage rests on sensor-based ore sorting technology partnerships with established Pilbara operators.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier nickel laterite developers with HPAL construction permits in Sulawesi and Halmahera. Long-term viability over the coming decade hinges on offtake contract duration with South Korean and Japanese battery material divisions. Watch South Korean cathode material procurement consolidation velocity as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Fleet Modernization | Rio Tinto's proprietary Pilbara systems set throughput benchmarks competitors must match. |
| Direct Precursor Integration | Indonesian HPAL operators bypass traders through South Korean cathode material offtake. |
| Dry-Stack Tailings Adoption | Indonesian processors maintain EU automotive OEM eligibility against MEE standards. |
| Sensor-Based Ore Sorting | Machine vision integration reduces downstream beneficiation waste in blasthole operations. |
| Progressive Rehabilitation Bond Structuring | Australia's EPA mandates reshape project finance timelines for Pilbara greenfield developments. |
Methodological Framework
Independent corroboration across mine operations executives, procurement leads at integrated steel mills, logistics corridor managers, and battery precursor chemical plant directors underwrites the qualitative findings. Secondary validation draws from Australian Bureau of Statistics mineral export data, Brazilian mining regulator tailings dam filings, Chinese MEE environmental compliance disclosures, and Indonesian investment coordination board HPAL project registrations. Bottom-up capacity modeling and top-down demand triangulation from construction and automotive end-use sectors anchor the analytical framework.
Rate-of-change decomposition across the projection horizon isolates volume drivers by extraction method, product grade tier, and end-user procurement channel. The modeling framework segments by iron ore, copper ore, bauxite, and nickel ore categories, with application splits across construction, automotive, electronics, and aerospace. CAGRs derive from mine-level production forecasts, smelter capacity expansion pipelines, and battery cell manufacturing buildout trajectories. Key inputs include diesel energy cost pass-through coefficients and autonomous haulage adoption curves.
Inputs from primary stakeholder interviews were available through the study window; gaps in Indonesian nickel laterite project commissioning timelines introduce uncertainty bands around supply growth assumptions. Forecasts reflect documented assumptions regarding Chinese steel output intensity and EV cathode chemistry evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Vanadium Market
Metals
Monel Alloy Market
Metals
Copper and Copper Alloy Scrap and Recycling Market
Metals
Electrolytic Manganese Metal Market
Metals
High Purity Tungsten Market
Metals
United States Metal Casting Market
Metals
Ruthenium Market
Metals
Silver-Platinum Paste Market
Metals
Global Bronze Market
Metals
Aluminum Sheet Market
Metals
Titanium Market
Metals
Cold Drawn Wire Market
Metals
Global Titanium Metal Market
Metals
GCC Metal Forging Market
Metals
Global High Purity Titanium Powder Market
Metals
Metal Injection Molding (MIM) Parts Market