
 Recycled Copper Market | 2026-2036
Recycled Copper Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Copper Market Outlook
Buyer concentration in the electrical utility sector is decoupling from traditional construction offtake as power grid operators diversify their copper sourcing. Aurubis anchors European smelting capacity with integrated refining operations across Belgium and Germany. Commercial Metals Company leverages its US mill network to process industrial scrap into rod and wire products. Sims Metal Management competes through dense collection infrastructure in North American urban corridors.
Recycled copper comprises post-consumer and post-industrial scrap that undergoes fire refining or electrolytic purification to achieve conductivity standards exceeding 99.9% International Annealed Copper Standard. The material serves primarily as a feedstock substitute for primary cathode in electrical conductors, plumbing systems, and heat exchangers where thermal and conductive performance must match virgin metal. Wire and tubes command the largest volume shares within product type segmentation, while Grade A scrap captures the tightest supply premiums due to minimal contamination and direct melt suitability. The automotive end-use segment is expanding fastest as electric vehicle manufacturers specify recycled content targets for motor windings and battery busbars.
The US EPA oversees hazardous waste classifications that affect scrap sorting and smelter emissions permitting, while the EU REACH framework restricts certain alloy contaminants in secondary metal destined for consumer products. China's SAMR enforces GB standards for recycled non-ferrous metals that control impurity thresholds in imported scrap. Stakeholders must monitor evolving cross-border scrap certification schemes and smelter carbon accounting rules that will determine which geographic processing hubs retain cost-competitive access to premium end-use markets.
Market Dynamics
Grid decarbonization mandates across Germany, China, and the United States are forcing utilities to source certified secondary copper with verified carbon footprints, compressing procurement timelines and rewarding smelters with integrated traceability systems.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Mandatory digital product passports for copper-containing goods are accelerating certified scrap demand from cable manufacturers in Belgium and the Netherlands.
- Electric vehicle motor windings:Automotive OEMs in China and Germany now specify minimum recycled content thresholds for traction motor conductors, pulling Grade A scrap into automotive supply chains.
- Fire refining technology advancement:New oxygen-enriched smelting processes at German and US facilities are expanding the share of lower-grade scrap suitable for electrical-grade cathode production.
Market Restraints
- Scrap supply geographic concentration:Collection infrastructure density varies sharply between North American urban corridors and secondary cities, creating feedstock access disparities for inland smelters.
- China's GB standards for imported scrap:Strict impurity thresholds enforced by SAMR have redirected trade flows, forcing Southeast Asian processors to absorb volumes rejected from direct Chinese entry.
- Primary copper price volatility:London Metal Exchange cathode pricing swings compress secondary smelter margins when scrap discounts narrow below processing cost floors.
Strategic Opportunities
- India's PLI scheme for electrical equipment:Domestic cable and transformer manufacturers face cost pressure to substitute imported cathode with certified secondary feedstock as production scales.
- Blockchain-enabled provenance tracking:Integration of distributed ledger systems with smelter ERP platforms creates audit trails that unlock premium pricing from ESG-mandated buyers in the EU and California.
- Building wire recovery from demolition:Urban renewal projects in US Rust Belt cities and China's northeastern industrial zones are generating concentrated post-consumer scrap streams with minimal alloy contamination.
Industry Challenges
- Fire assay technician shortage:Smelters in Germany and the United States report extended hiring timelines for analysts capable of rapid impurity detection in mixed scrap lots.
- Cross-border certification harmonization:Divergent carbon accounting methodologies between EU emissions trading systems and California's LCFS create compliance friction for multi-destination exporters.
- Legacy furnace retrofit requirements:Converting traditional reverberatory capacity to meet MEE emission standards in China demands capital deployment that mid-scale operators struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Copper Market |
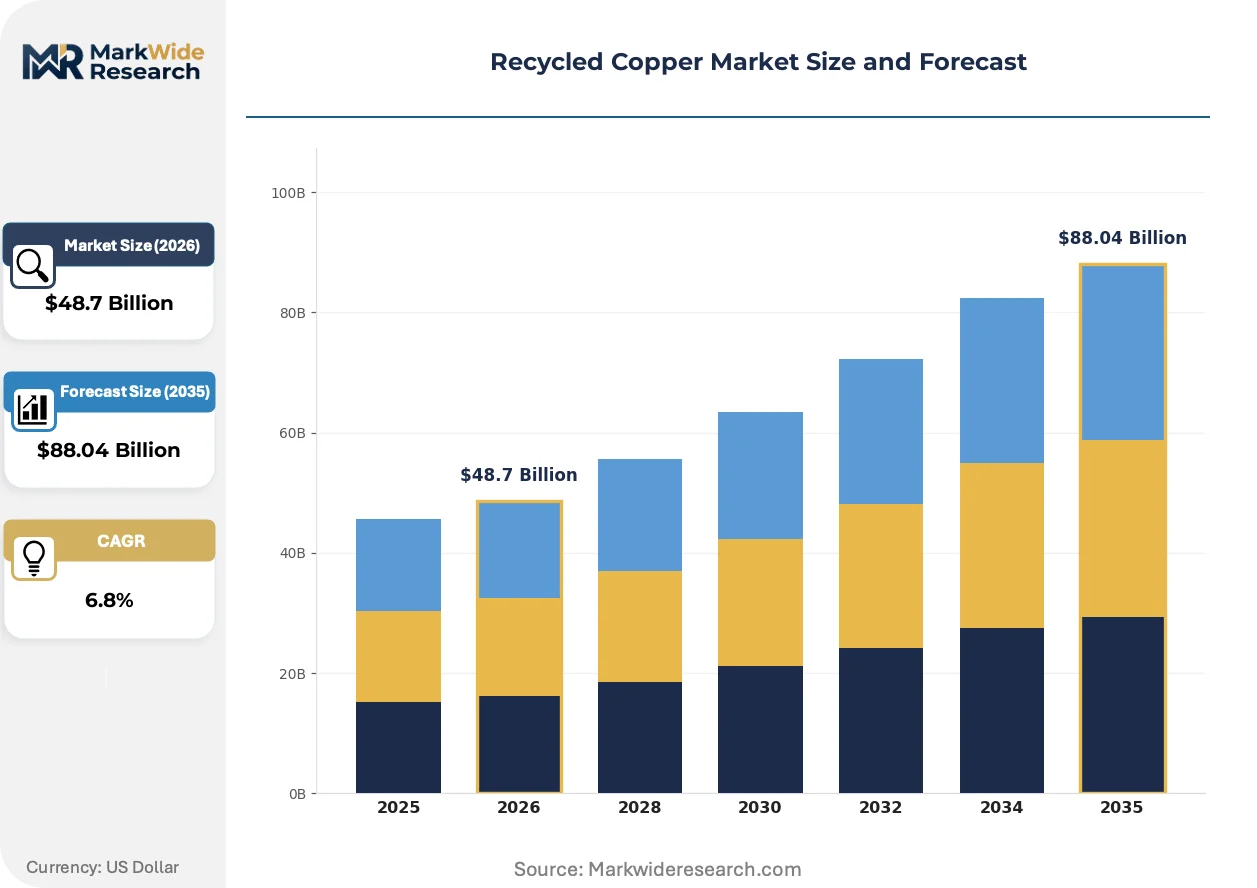
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire, Tubes, Sheets, Ingots Grade: Grade A, Grade B, Grade C, Industrial Scrap End Use Industry: Electrical, Construction, Automotive, Electronics Packaging Type: Bales, Drums, Containers, Loose Bulk |
| Companies Covered | Metallo-Chimique, Commercial Metals Company, Aurubis, Sims Metal Management, Scrap Metal Services, Glencore, Primex Plastics, OmniSource Corporation, CME Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Copper Market Strategic Shifts
Processing technology convergence and regulatory data requirements are compressing the gap between scrap collection and certified cathode output, rewarding operators who control both ends of the value chain.
Sensor-based scrap sorting using X-ray fluorescence and laser-induced breakdown spectroscopy is consolidating quality control at collection facilities. European and North American yards are deploying these systems to pre-sort mixed copper alloys before smelter delivery, reducing downstream refining costs. The technology is compressing the traditional merchant middle layer by enabling direct mill-to-yard contracting.
REACH restrictions on lead and cadmium content in secondary copper destined for consumer products are tightening alloy segregation requirements. Smelters serving plumbing and cookware end-uses must now maintain separate processing lines for low-lead scrap streams. German and French regulators are enforcing these thresholds most aggressively, pushing non-compliant material toward industrial electrical applications with less stringent contact standards.
Long-term offtake agreements tied to carbon intensity metrics are displacing spot market transactions for major cable producers. Procurement teams at utilities in California, Germany, and China's eastern corridor now require documented lifecycle emissions data from smelter partners. This specification shift is most visible in high-voltage transmission projects where ESG-linked financing mandates cascade into material sourcing requirements.
Recycled Copper Market Segmentation
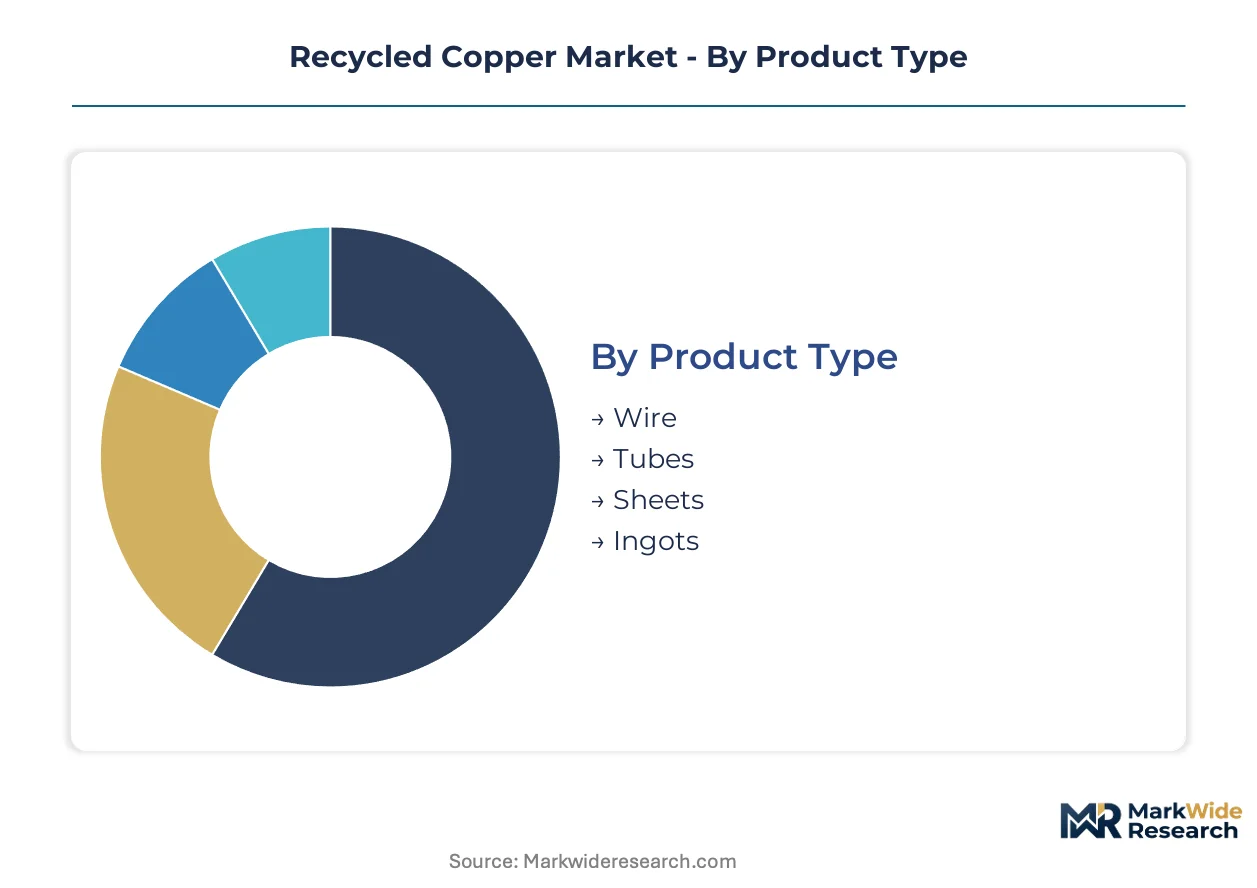
Recycled copper segmentation tracks how material purity, physical form, and end-use specifications determine processing economics and buyer qualification requirements. Grade differentiation and product type selection directly govern smelter yield rates and carbon intensity certification eligibility for grid and automotive offtake.
Product Type:
Wire and tube segments dominate standalone electrical applications, while sheets and ingots serve as embedded feedstock for downstream fabrication systems.
- Wire:Continuous-cast rod and drawn conductors processed from Grade A scrap achieve conductivity standards exceeding 99.9% IACS for high-voltage transmission cables. Demand concentrates in China's eastern manufacturing corridor where cable producers maintain aggressive secondary procurement targets tied to grid decarbonization mandates.
- Tubes:Seamless and welded tubing extruded from fire-refined scrap serves plumbing and heat exchanger applications requiring thermal performance parity with virgin metal. German and US utilities specify tube products for substation cooling systems under lower-carbon sourcing protocols.
- Sheets:Rolled plate and strip from electrolytically refined cathode feed architectural cladding and industrial equipment housings.
- Ingots:Cast primary forms for remelting at downstream fabricators lacking integrated smelting capacity.
Wire leads volumes today; tubes are gaining share fastest through HVAC and automotive thermal management expansion.
Grade:
Grade stratification determines direct melt suitability versus refining intensity, with purity thresholds governing end-use access and pricing premiums.
- Grade A:Bare, unalloyed scrap with minimal oxidation and contamination qualifies for direct fire refining to electrical-grade cathode. Automotive OEMs in Germany and China specify Grade A for traction motor windings under recycled content thresholds.
- Grade B:Coated or lightly contaminated material requiring oxygen-enriched smelting or electrolytic purification to meet conductivity standards.
- Grade C:Mixed alloy scrap with higher impurity loads suitable for non-electrical applications or blending with primary metal.
- Industrial Scrap:Post-manufacturing turnings, borings, and solids from machining operations with predictable composition and lower collection costs.
Grade A commands the tightest supply premiums; industrial scrap is expanding most quickly through manufacturing waste recovery programs.
End Use Industry:
Electrical and automotive applications impose the strictest purity and traceability requirements, while construction and electronics tolerate broader grade ranges.
- Electrical:Grid infrastructure, power cables, and transformers absorb the largest certified secondary volumes as utilities in Germany, China, and the United States diversify sourcing under carbon reduction mandates.
- Automotive:Electric vehicle motor windings and battery busbars drive the steepest demand expansion as manufacturers specify minimum recycled content.
- Construction:Building wire, plumbing, and roofing applications utilize broader grade ranges with less stringent conductivity requirements.
- Electronics:Printed circuit boards and connectors require high-purity feedstock with controlled alloy specifications.
Electrical maintains volume leadership; automotive is climbing the fastest on EV production scaling.
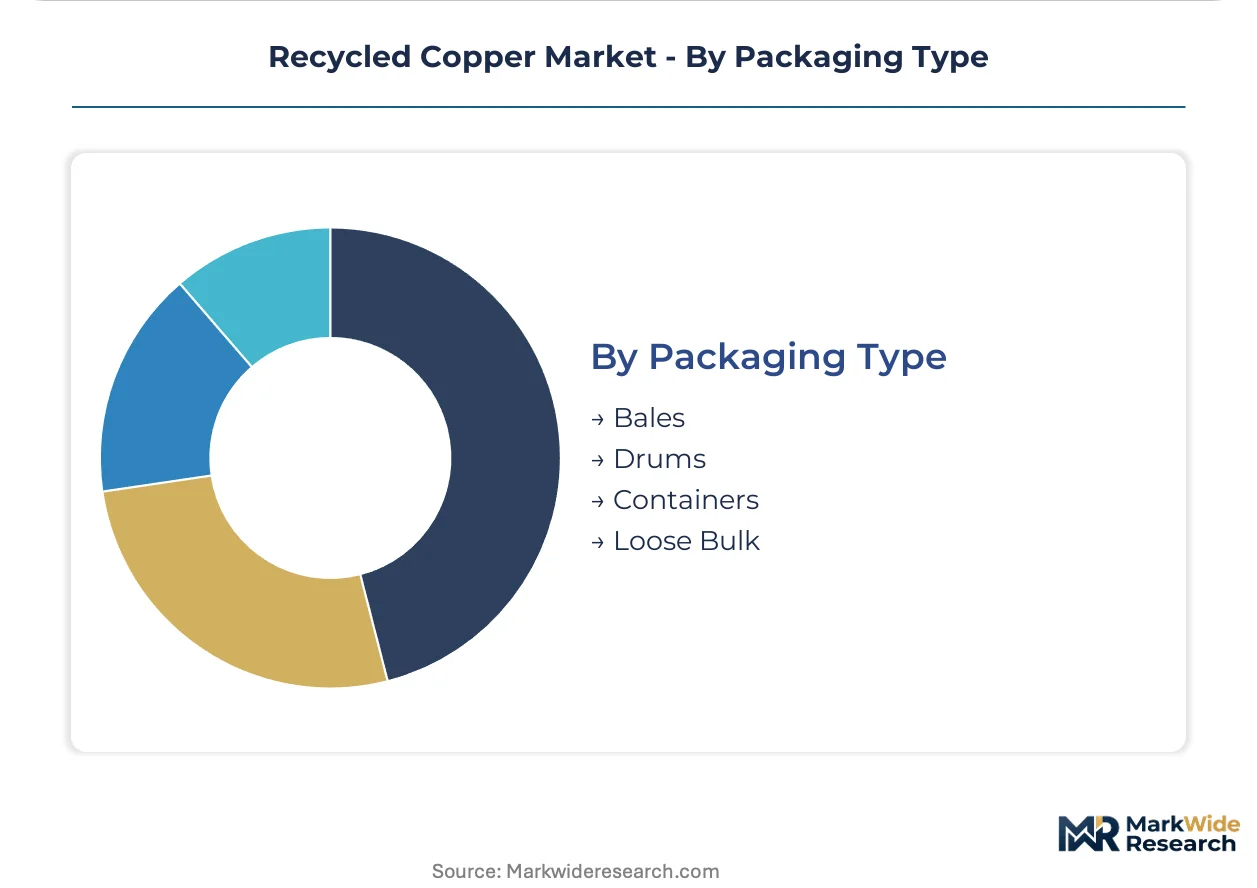
Packaging Type:
Packaging configuration affects logistics economics and contamination risk, with density and handling requirements varying by scrap morphology and transport distance.
- Bales:Compressed wire and cable bundles maximize container utilization for ocean freight from North American collection yards to Asian smelters.
- Drums:Sealed containment for fine turnings and powders prevents oxidation and moisture absorption during storage.
- Containers:Bulk box systems for mixed industrial scrap enable mechanized unloading at large-scale refining facilities.
- Loose Bulk:Uncompressed material for short-haul domestic movements where density penalties are offset by reduced processing labor.
Bales dominate intercontinental trade; drums are expanding most quickly through precision alloy scrap specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor processes more secondary copper than Germany and the United States combined, yet regulatory divergence across these three markets is fragmenting trade flows and redirecting scrap toward Southeast Asian intermediaries.
China
Power grid operators in Jiangsu and Zhejiang provinces specify certified secondary copper for high-voltage transmission expansions under provincial dual carbon implementation timelines. SAMR's GB standards for imported scrap enforce strict impurity thresholds that reject volumes now flowing to Malaysian and Indonesian processors. Cable manufacturers in Dongguan and Foshan maintain aggressive procurement targets for Grade A scrap to supply automotive OEMs with recycled content documentation.
Germany
Utilities in North Rhine-Westphalia and Bavaria source secondary cathode for substation infrastructure under federal grid decarbonization procurement rules. The EU Ecodesign for Sustainable Products Regulation mandates digital product passports that trace copper from scrap collection to finished cable. Aurubis operates integrated refining capacity in Hamburg and Lünen to serve Belgian and Dutch cable producers facing similar traceability requirements.
United States
California utilities and Texas grid operators require documented carbon intensity data for secondary copper under state-level clean energy procurement mandates. The EPA oversees hazardous waste classifications affecting scrap sorting and smelter emissions permitting across the Midwest and Southeast. Commercial Metals Company processes industrial scrap through its mill network to supply rod and wire products for Rust Belt building wire recovery projects.
India
Domestic cable and transformer manufacturers in Maharashtra and Gujarat face cost pressure to substitute imported cathode with certified secondary feedstock under the PLI scheme for electrical equipment. The Bureau of Indian Standards enforces quality specifications for recycled non-ferrous metals that control impurity thresholds in domestic scrap streams. Smelters in Haryana and Tamil Nadu are expanding capacity to serve this substitution demand as production scales.
Belgium
Cable producers in the Antwerp port region source fire-refined secondary copper for European distribution networks under REACH restrictions on lead and cadmium content. The country's dense collection infrastructure and proximity to German refining capacity create efficient feedstock access. Smelters serving the Belgian market maintain separate processing lines for low-lead scrap streams destined for plumbing and consumer product applications.
Recycled Copper Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the recycled copper value chain, creating a tiered structure where scale-driven processors and technology-intensive refiners occupy distinct competitive positions. Consolidation pressure concentrates around integrated smelter-refiner operations capable of delivering certified cathode with verified carbon footprints. Three archetypes dominate: mining-house trading divisions with scrap collection networks, dedicated secondary metal refiners with fire and electrolytic capacity, and merchant processors focused on geographic collection density. Capacity expansion and backward integration into scrap collection infrastructure represent the dominant competitive moves as procurement teams demand shorter certified supply chains.
Within the integrated refining tier, Aurubis and Glencore exemplify scale-driven operators with cross-border processing footprints. Commercial Metals Company occupies a position among North American mill-based processors converting industrial scrap into downstream rod and wire products. Sims Metal Management anchors the collection-density archetype through urban corridor infrastructure in multiple countries.
| Leading Market Players |
|---|
| Metallo-Chimique |
| Commercial Metals Company |
| Aurubis |
| Sims Metal Management |
| Scrap Metal Services |
| Glencore |
| Primex Plastics |
| OmniSource Corporation |
| CME Group |
| Others |
Value Chain & Pricing Dynamics
Oxygen-enriched fire refining at German and US facilities is compressing processing costs for lower-grade scrap while simultaneously concentrating output among operators with capital-intensive furnace retrofits. This technology transition rewards integrated smelter-refiners with scale advantages and narrows viable supply sources for cable manufacturers seeking certified cathode.
Pricing Analysis
Capacity additions in Southeast Asian processing hubs are reshaping price floors for Grade A scrap as Malaysian and Indonesian facilities absorb volumes rejected under China's GB standards. Long-term offtake agreements tied to carbon intensity metrics now dominate procurement between utilities and smelters, displacing spot market transactions. Price differentiation hinges on certification grade and documented lifecycle emissions data, with ESG-mandated buyers in Germany and California paying premiums for blockchain-verified provenance. Price erosion runs through standard-grade material as oxygen-enriched smelting expands supply of electrical-grade cathode from lower-purity feedstock. Construction and electronics segments exhibit highest price sensitivity, while automotive OEMs and grid operators prioritize traceability over unit cost.
Supply Chain Analysis
Fire assay technician shortages in Germany and the United States are constraining quality control throughput at secondary smelters and extending delivery timelines for certified cathode. Supply concentrates in China, Germany, and the United States, with China's eastern manufacturing corridor processing the largest volumes. Raw material flows draw from post-consumer demolition scrap, industrial machining waste, and imported baled cable, with feedstock quality varying sharply between North American urban corridors and secondary cities. Single-source vulnerability sits with Southeast Asian intermediaries now absorbing redirected trade flows under China's SAMR restrictions. Distribution runs through direct mill-to-yard contracting enabled by sensor-based pre-sorting technology, compressing traditional merchant middle layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The recycled copper market compounds steadily as grid decarbonization mandates across major economies institutionalize secondary metal procurement. Carbon accounting requirements embedded in utility procurement rules create durable demand visibility for certified smelter output.
For Market Incumbents: To counter margin compression from primary copper price volatility, deepen backward integration into scrap collection infrastructure in North American urban corridors and China's northeastern industrial zones. Invest in blockchain-enabled ERP integration to capture premium pricing from ESG-mandated buyers. Prioritize fire assay technician training pipelines to resolve quality control bottlenecks constraining throughput. For New Entrants and Emerging Players: Begin with India's PLI scheme for electrical equipment, where domestic cable manufacturers face cost pressure to substitute imported cathode with certified secondary feedstock. Target building wire recovery from Rust Belt demolition projects and China's aging industrial zones, where concentrated post-consumer streams minimize alloy contamination. Pursue direct contracting with automotive OEMs specifying recycled content thresholds for traction motor windings. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale processors lacking integrated refining capacity or carbon accounting systems. Frame long-term viability around operators controlling both scrap collection and certified cathode output as procurement teams demand shorter supply chains. Watch for inflection in cross-border certification harmonization between EU emissions trading systems and California's LCFS, which would unlock multi-destination premium pricing for compliant exporters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Collection | Direct mill-to-yard contracting compresses merchant margins and secures feedstock access for certified cathode production. |
| Blockchain-Enabled Provenance Tracking | Distributed ledger integration with smelter ERP platforms unlocks premium pricing from ESG-mandated utilities in Germany and California. |
| Oxygen-Enriched Fire Refining Capacity | New furnace technology expands lower-grade scrap suitability for electrical-grade output, reshaping competitive cost positions. |
| Fire Assay Technician Training Programs | Specialized analyst pipelines resolve quality control bottlenecks constraining throughput at German and US facilities. |
| Cross-Border Certification Harmonization | Aligned carbon accounting methodologies between EU and California systems reduce compliance friction for multi-destination exporters. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with secondary metal refiners, cable manufacturer procurement leads, scrap yard operators, and utility sustainability officers with validation against customs trade data, SEC filings from integrated processors, EPA hazardous waste classifications, and EU Ecodesign regulatory documentation. Bottom-up volume estimates from segment-level procurement targets triangulated against top-down smelter capacity utilization rates.
Segment-weighting across product type, grade classification, end-use industry, and packaging configuration governed volume allocation throughout the forecast period. CAGRs derived from elasticity modeling against primary copper price scenarios and regulatory implementation timelines. Industry-specific inputs included SAMR GB standard enforcement patterns, EU digital product passport rollout schedules, and automotive OEM recycled content threshold commitments.
Several conditions sit outside the modeled scope, including abrupt shifts in London Metal Exchange cathode pricing, unilateral tariff modifications affecting scrap trade flows, and technological breakthroughs in primary copper extraction. Forecasts reflect documented assumptions regarding regulatory implementation pacing and carbon accounting methodology convergence. Material deviation in SAMR import policy, EU Ecodesign enforcement intensity, or fire refining technology diffusion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Global Artificial Rutile Market
Metals & Minerals
US Coated Steel Market
Metals & Minerals
Andalusite Market
Metals & Minerals
Gold Recycling Market
Metals & Minerals
Zinc Hydroxide Market
Metals & Minerals
Laminated Steel Market
Metals & Minerals
Global Chromium Salt Market
Metals & Minerals
Global Magnesium Carbonate Minerals Market
Metals & Minerals
Phosphorus Ore Market
Metals & Minerals
Selenium Market
Metals & Minerals
Recycled Scrap Metal Market
Metals & Minerals
Solder Materials Market
Metals & Minerals
Global Gold Potassium Cyanide Market
Metals & Minerals
Zinc Sulphate Market
Metals & Minerals
Sapphire Mining Market
Metals & Minerals
Global Ferrous Scrap Recycling Market