
 Italy Facade Market | 2026-2036
Italy Facade Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Facade Market Foresight
The capital-intensity divergence between integrated system suppliers and component fabricators is rotating competitive advantage toward firms with in-house engineering and installation capabilities. Permasteelisa S.p.A. leverages its vertically controlled project delivery to dominate complex commercial envelopes across Italian metropolitan cores. Bluesteel S.r.l. anchors its position through specialized metal-glass unitized systems for high-rise applications. ITALGRANITI GROUP S.p.A. differentiates via ceramic cladding solutions that compete on material durability and aesthetic customization.
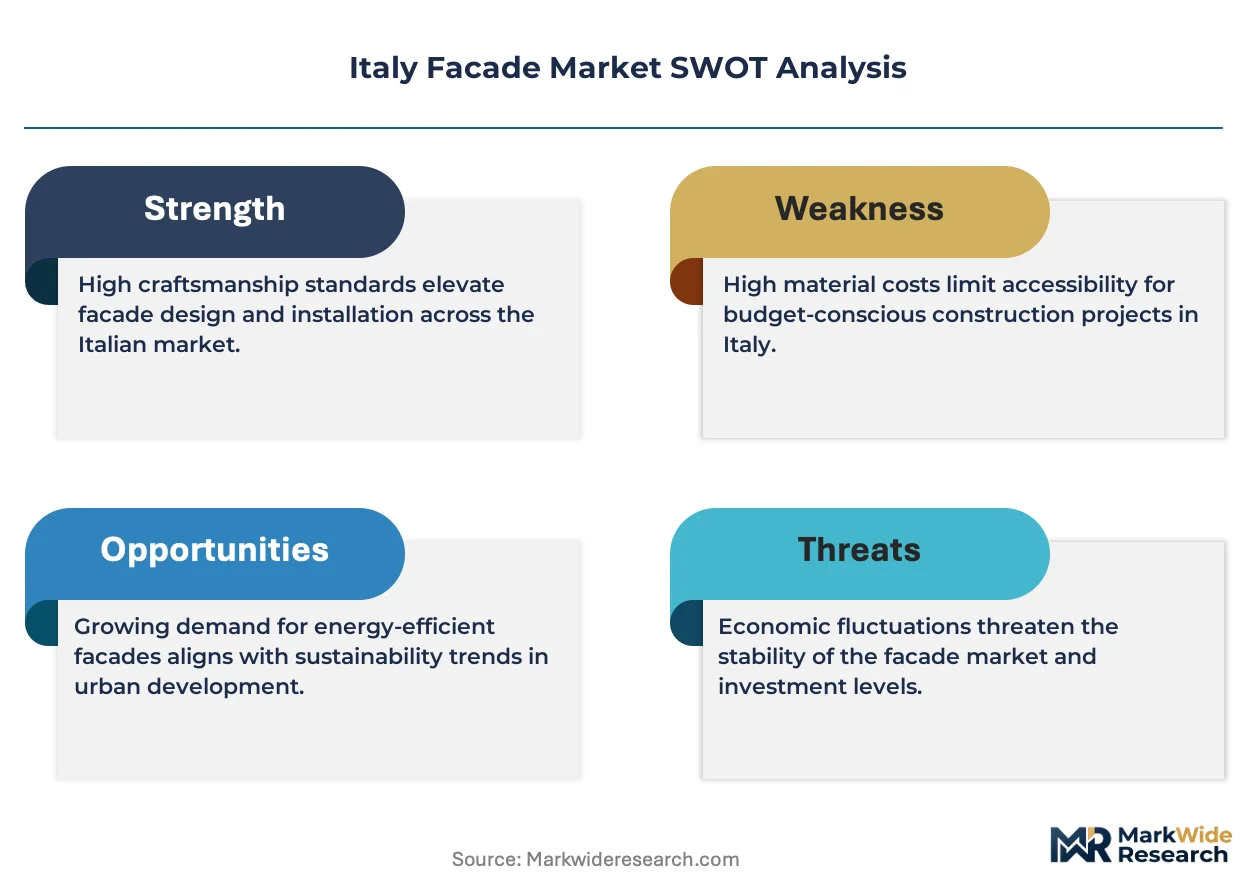
A facade constitutes the exterior envelope of a building, comprising curtain walls, cladding panels, and structural glazing systems engineered to manage thermal insulation, air permeability, and wind loads while meeting specified U-values and fire resistance ratings. Its primary purpose is to protect interior spaces from environmental exposure while enabling daylight penetration and controlled ventilation. Glass and metal composite systems lead new construction installations across Italian commercial towers, while stone cladding retains margin concentration in heritage restoration projects where material authenticity commands premium positioning. The renovation and restoration segment is expanding fastest as Italy's Superbonus fiscal incentives drive deep energy retrofit demand across aging residential and institutional building stock.
Italy's facade sector operates under CE marking requirements, the EU Green Deal's building performance standards, and national fire safety protocols enforced through the country's construction regulator. These frameworks mandate minimum thermal performance for envelope components and restrict combustible materials in high-rise applications, directly shaping product specifications and procurement criteria. Stakeholders must monitor how tightening energy performance thresholds and evolving fire safety classifications will reshape material substitution patterns and certification costs across the Italian construction value chain.
Market Dynamics
The EU Green Deal's tightening energy performance standards are compressing specification cycles for Italian facade contractors, forcing rapid material substitution toward high-thermal-performance assemblies. Milan and Rome developers now mandate U-value compliance at pre-bid stages, reshaping competitive positioning toward engineering-capable system integrators.
Growth Catalysts
- Superbonus fiscal incentives:Italy's 110% tax credit for deep energy retrofits is accelerating renovation demand across aging residential and institutional envelopes in northern industrial zones.
- Curtain wall technology:Unitized glass-metal systems are penetrating Milan's commercial tower pipeline, reducing on-site labor exposure and compressing installation schedules for high-rise developers.
- Lombardy building stock concentration:Aging industrial facilities across Milan, Turin, and Genoa corridors generate sustained cladding replacement demand as energy audits proliferate.
Market Restraints
- Aluminum input volatility:Primary aluminum price swings squeeze fabricator margins on metal-glass composite systems, forcing hedging costs onto mid-tier suppliers.
- CE marking compliance costs:Extended certification timelines for fire-rated assemblies delay product launches, particularly for SMEs lacking in-house testing facilities.
- Stone cladding substitution:Ceramic and sintered stone panels are capturing heritage restoration specifications previously reserved for natural stone, compressing premium material volumes.
Strategic Opportunities
- Southern Italy underpenetration:Naples and Palermo commercial construction remains below cladding intensity levels of northern metros, offering first-mover positioning for system suppliers.
- Photovoltaic facade convergence:Building-integrated photovoltaics fused with curtain wall systems open new revenue streams as Italian net-zero mandates tighten.
- Digital specification platforms:Online technical documentation and BIM-integrated procurement are reducing friction for architects specifying complex envelope assemblies.
Industry Challenges
- Fire safety certification delays:Updated UNI 9177 reaction-to-fire classifications require retesting of legacy product lines, extending time-to-market for reformulated composites.
- Installation labor scarcity:Specialized curtain wall rigging skills concentrate among aging northern Italian crews, constraining project throughput during peak construction seasons.
- Legacy building integration:Deep retrofit of 1960s-70s concrete frame structures demands custom engineering that standard unitized systems cannot address profitably.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Facade Market |
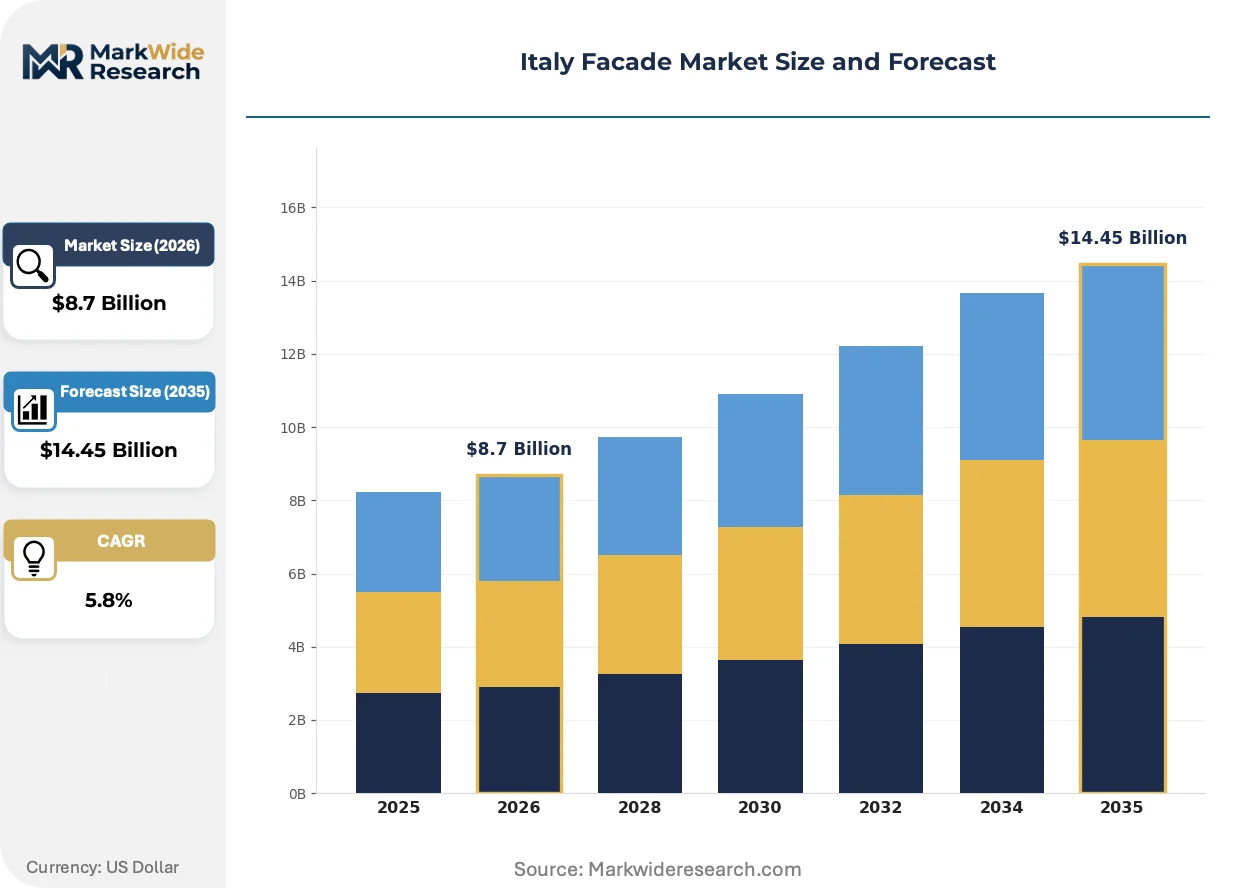
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Metal, Stone, Composite Building Type: Residential, Commercial, Industrial, Institutional Installation Type: New Construction, Renovation, Restoration, Retrofits Design Style: Modern, Traditional, Minimalist, Eclectic |
| Companies Covered | Bluesteel S.r.l., ITALGRANITI GROUP S.p.A., Permasteelisa S.p.A., Zanetti Srl, BEMO SYSTEMS GmbH, Ramboll Group A/S, CANTORI S.r.l., Incide Engineering SRL, Aghito Zambonini S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Facade Market Shifts & Advancements
Italian facade engineering is pivoting toward performance-guaranteed envelope solutions that compress total-project risk for developers. Material science advances and digital specification tools are converging to reshape how architects and contractors collaborate on complex commercial envelopes.
Triple-glazed, argon-filled insulating glass units with warm-edge spacers are displacing conventional double-glazed assemblies in Milan's premium office towers. Lombardy developers specify these units to meet EU Green Deal thermal thresholds without expanding frame profiles. The technology is compressing aluminum extrusion volumes per square meter of facade while elevating engineering premiums for system integrators.
Italy's transposition of the EU Energy Performance of Buildings Directive is mandating near-zero energy standards for new commercial construction from 2030. The regulation is forcing early specification of high-performance cladding in Rome and Turin development pipelines. Curtain wall suppliers are pre-certifying assemblies to accelerated timelines, locking out competitors lacking testing infrastructure.
Architects and developers are consolidating specification authority through design-build contracts that bundle engineering, fabrication, and installation risk. This procurement compression favors vertically integrated envelope specialists with captive installation crews over component-only suppliers. The shift is most visible in Milan's Porta Nuova and Rome's EUR business district towers, where single-source accountability reduces interface disputes.
Italy Facade Market Segmentation
Italian facade procurement patterns diverge sharply between Milan-Rome commercial towers and heritage restoration corridors. Segment-specific engineering capabilities determine which suppliers capture specification authority across these distinct demand pools.
Material:
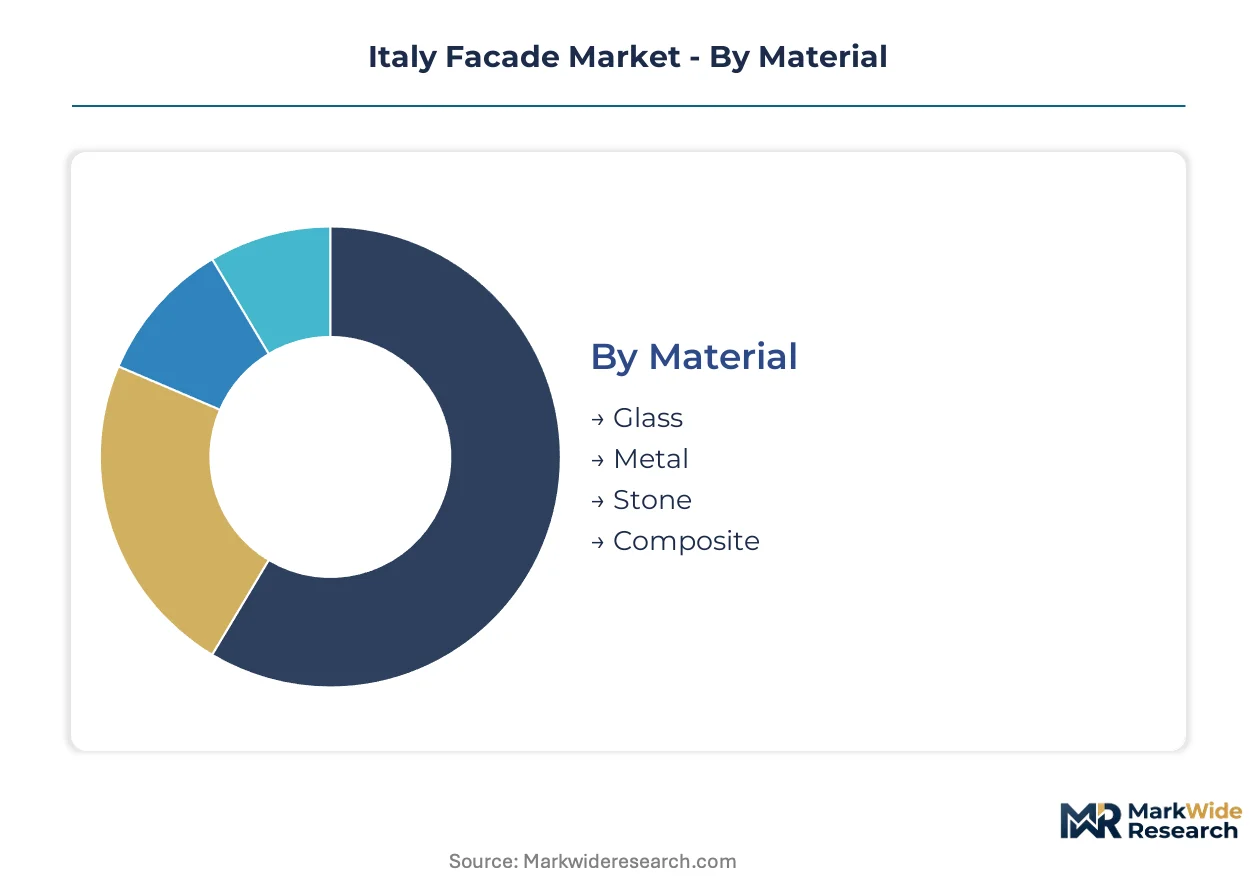
Glass and metal composites dominate Milan's new commercial construction, while stone retains export-led heritage positioning.
- Glass:Triple-glazed insulating units with warm-edge spacers now specify across Lombardy premium office towers. Milan developers mandate these assemblies to meet EU Green Deal thermal thresholds without expanding frame profiles.
- Metal:Aluminum composite panels and unitized curtain wall framing anchor high-rise installations across Rome's EUR district. Price volatility in primary aluminum squeezes fabricator margins, forcing hedging costs onto mid-tier suppliers.
- Stone:Natural travertine and marble retain heritage restoration specifications where material authenticity commands premium positioning.
- Composite:Ceramic and sintered stone panels penetrate specifications previously reserved for natural stone, compressing premium material volumes.
Glass holds the largest share; momentum sits with Composite.
Building Type:
Cost tier stratification separates engineering-intensive commercial envelopes from standardized residential cladding.
- Commercial:Curtain wall systems with integrated Building-Integrated Photovoltaics specify across Milan Porta Nuova and Rome business district towers. Design-build procurement bundles engineering, fabrication, and installation risk with vertically integrated specialists.
- Residential:Superbonus fiscal incentives accelerate deep energy retrofits across aging northern Italian apartment stock. Ceramic cladding and insulated render systems dominate this price-sensitive segment.
- Industrial:Aging facilities across Milan-Turin-Genoa corridors generate sustained metal panel replacement demand as energy audits proliferate.
- Institutional:Schools and hospitals in Lombardy and Veneto specify fire-rated assemblies under tightened UNI 9177 classifications.
Commercial commands premium engineering margins; residential climbs the fastest on retrofit incentives.
Installation Type:
Volume concentration tilts toward renovation as Italy's building stock ages and energy regulations tighten.
- New Construction:Unitized glass-metal systems reduce on-site labor exposure across Milan's commercial tower pipeline.
- Renovation:Deep energy retrofits of 1960s-70s concrete frame structures demand custom engineering that standard unitized systems cannot address profitably.
- Restoration:Heritage projects in Florence and Venice require material authenticity compliance, preserving natural stone and traditional mortar specifications.
- Retrofits:Façade-integrated photovoltaic upgrades specify across public buildings seeking net-zero compliance pathways.
Renovation holds the largest share; momentum sits with Retrofits.
Design Style:
Customer type stratification separates architect-specified modern envelopes from developer-driven traditional restorations.
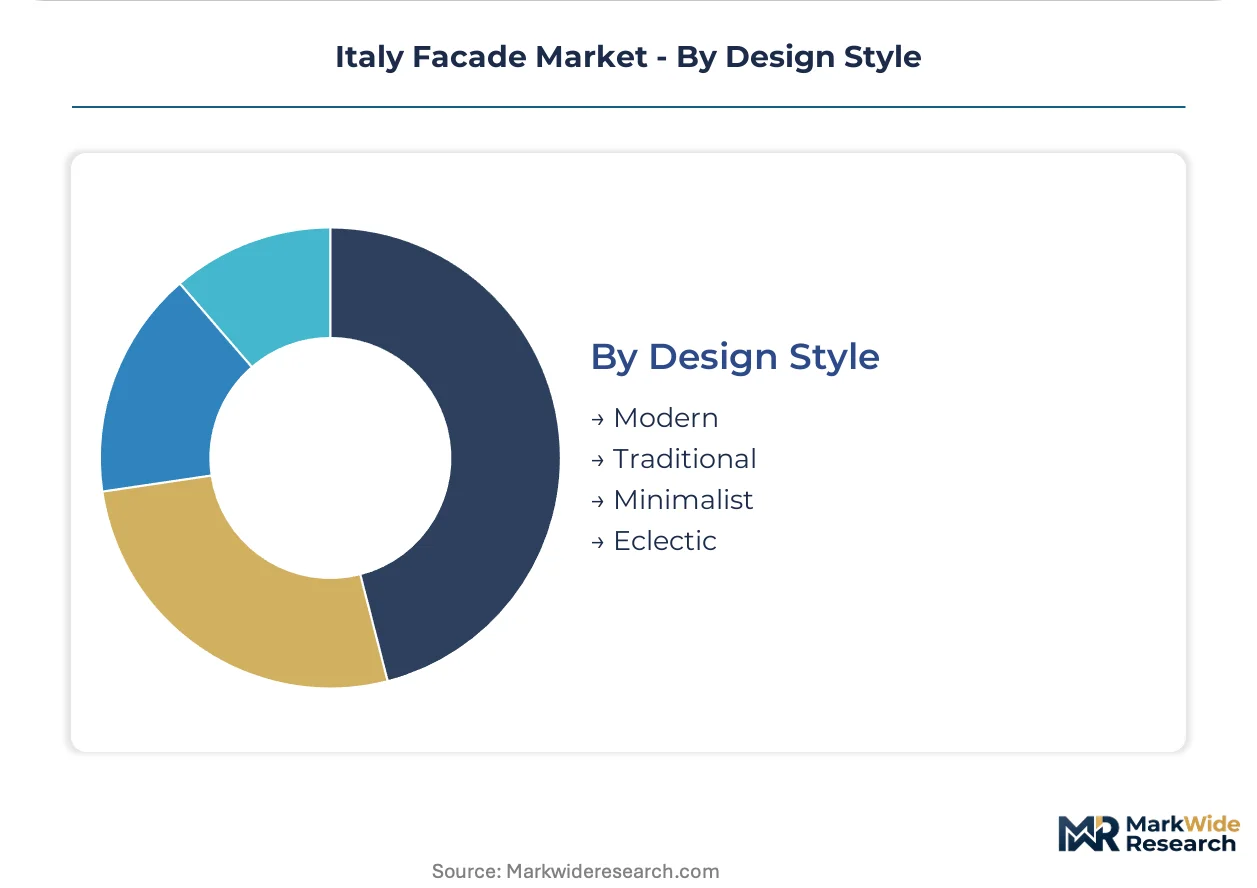
- Modern:Minimal frame profiles and expansive glazing ratios define Milan's premium office specifications. BIM-integrated procurement reduces friction for architects specifying these complex envelope assemblies.
- Traditional:Material authenticity requirements govern heritage restoration in UNESCO-protected zones across Rome, Florence, and Venice.
- Minimalist:Flush panel systems with concealed fixings penetrate boutique commercial and high-end residential segments.
- Eclectic:Mixed material compositions specify across cultural and hospitality projects seeking distinctive visual identity.
Modern holds the largest share; momentum sits with Minimalist as detailing sophistication advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Italian sub-regions, with northern industrial zones absorbing premium engineering costs while southern markets prioritize cost-efficient retrofit solutions.
Lombardy
Milan's commercial tower pipeline drives demand for unitized curtain wall systems with integrated photovoltaics. The EU Green Deal's building performance standards mandate pre-bid U-value compliance, compressing specification cycles. Porta Nuova and CityLife districts concentrate design-build procurement with vertically integrated envelope specialists.
Piedmont
Turin's aging automotive industrial facilities generate sustained metal panel replacement demand as energy audits proliferate under Superbonus fiscal incentives. Regional fire safety protocols enforce UNI 9177 classifications on institutional retrofits. The Milan-Turin corridor anchors specialized curtain wall rigging crews.
Veneto
Venice heritage restoration projects preserve natural stone and traditional mortar specifications under UNESCO protection frameworks. Padua and Verona commercial construction specifies ceramic cladding systems for price-sensitive mixed-use developments. The region balances material authenticity requirements with energy retrofit mandates.
Lazio
Rome's EUR business district towers consolidate single-source accountability through bundled engineering-fabrication-installation contracts. Net-zero compliance pathways drive photovoltaic facade upgrades across public buildings. The capital's institutional segment tightens fire-rated assembly specifications under national construction regulator oversight.
Emilia-Romagna
Bologna's logistics and manufacturing facilities prioritize rapid-install metal composite panels over engineered curtain wall systems. Regional ceramic producers supply sintered stone alternatives penetrating heritage-adjacent specifications. The Po Valley industrial belt shows below-average cladding intensity compared to Lombardy metros.
Italy Facade Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with engineering-capable system integrators commanding premium positioning while component fabricators compete on input cost management. The vendor base stratifies across three tiers: vertically integrated envelope specialists, specialized material fabricators, and regional installation contractors. Dominant competitive moves include backward integration into captive installation crews and pre-certification of assemblies to accelerated regulatory timelines.
Within the vertically integrated tier, Permasteelisa S.p.A. and Bluesteel S.r.l. exemplify engineering-led positioning, while ITALGRANITI GROUP S.p.A. anchors the material-specialist archetype through ceramic cladding solutions. These three occupy positions reflecting distinct capability investments: project-delivery control, high-rise unitized systems, and material durability customization respectively.
| Leading Market Players |
|---|
| Bluesteel S.r.l. |
| ITALGRANITI GROUP S.p.A. |
| Permasteelisa S.p.A. |
| Zanetti Srl |
| BEMO SYSTEMS GmbH |
| Ramboll Group A/S |
| CANTORI S.r.l. |
| Incide Engineering SRL |
| Aghito Zambonini S.p.A. |
| Others |
Supply & Pricing Matrix
Ceramic and sintered stone panel substitution for natural travertine is compressing premium material premiums while shifting procurement geography toward domestic Emilia-Romagna producers. This input displacement simultaneously erodes stone importer margins and elevates regional fabricator pricing power as architects accept engineered alternatives for heritage-adjacent specifications.
Pricing Analysis
After-sales service contracts for facade maintenance and thermal performance monitoring drive lifetime value capture for system integrators. Project-based pricing dominates, with premiums attaching to CE-marked fire-rated assemblies and BIM-integrated documentation. Cost compression in aluminum-dependent metal-glass systems is intensifying because primary aluminum volatility transfers hedging burdens onto mid-tier fabricators. Residential retrofit buyers exhibit highest price sensitivity, while Milan commercial developers absorb engineering premiums for single-source accountability.
Supply Chain Analysis
Strategic aluminum stockpiling prevails among large fabricators buffering against LME volatility, while smaller operators run just-in-time glass deliveries from Pilkington and AGC European float plants. Primary aluminum draws from Norway, Iceland, and domestic Portovesme smelter output; glass substrates rest on Belgian and German furnace capacity. Single-source vulnerability concentrates in specialized warm-edge spacer components sourced from Swiss and Austrian precision manufacturers. Distribution runs through architect-specified design-build channels that bypass traditional merchant distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized curtain wall rigging crews are aging out faster than apprenticeship pipelines refill, creating acute capability scarcity that constrains project throughput regardless of fabrication capacity. This labor bottleneck shapes competitive outcomes more than material access or capital availability.
For Market Incumbents: Shield engineering premiums by locking Milan and Rome developers into multi-tower master service agreements that bundle pre-certification, installation, and decade-long thermal performance guarantees. Backward integration into captive rigging crews defends against labor scarcity, while accelerated UNI 9177 testing investment raises certification barriers for reformulating competitors.
For New Entrants and Emerging Players: Lead with photovoltaic facade convergence as the wedge into public building retrofits across Naples and Palermo, where cladding intensity lags northern metros and net-zero compliance deadlines create urgent specification windows. Digital specification platforms reduce architect friction for unknown suppliers, enabling bypass of incumbent design-build relationships.
For Investors and Strategic Acquirers: The market sits at a regulatory-acceleration phase that favors vertically integrated envelope specialists with captive installation infrastructure and pre-certified assembly libraries. Acquisition targets should demonstrate proven EU Green Deal compliance pathways and established relationships with Lombardy energy audit consultants. Watch for inflection when Superbonus fiscal incentive modifications alter retrofit project economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certification Investment | Accelerated UNI 9177 testing locks out competitors lacking in-house fire-rated assembly validation. |
| Captive Installation Crew Development | Specialized curtain wall rigging capacity commands premium pricing during peak construction seasons. |
| Photovoltaic Facade Integration | Building-integrated photovoltaics fused with curtain walls capture Italian net-zero mandate budgets. |
| Digital Specification Platform Launch | BIM-integrated procurement reduces architect friction for complex envelope assembly selection. |
| Southern Italy Geographic Expansion | Naples and Palermo commercial construction offers first-mover positioning below northern cladding intensity levels. |
Research Methodology
A spread of perspectives from facade system engineering directors, commercial construction procurement managers, energy audit consultants, and regional installation contractors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against CE marking databases, Superbonus fiscal incentive disbursement records, and Lombardy building permit filings. Customs data on aluminum and glass substrate imports, UNI standard revision documentation, and EU Energy Performance of Buildings Directive transposition texts anchored bottom-up and top-down triangulation.
Segmentation dimensions modeled span material type, building application, installation category, and design style across the projection horizon. CAGRs derived from unit volume build-ups by metropolitan construction pipeline, weighted by cladding intensity coefficients and retrofit penetration curves. Forecast inputs incorporated Superbonus policy continuity assumptions, aluminum price band scenarios, and fire safety classification evolution timelines.
Underlying assumptions cover regulatory enforcement consistency, skilled labor availability, and primary input price stability, with deviation risk concentrated in fiscal incentive modification and UNI 9177 retesting backlog duration. Revision becomes warranted when Superbonus uptake rates or fire certification queue lengths cross threshold disruption levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Steel Sleepers Market
Building Materials
Saudi Arabia GRC Cladding Market
Building Materials
Cement Tiles Market
Building Materials
Asia-Pacific Kinetic Tiles Market
Building Materials
Global Corrugated Steel Sheets Market
Building Materials
North America Spray Polyurethane Foam for Building and Construction Market
Building Materials
Global Glass Fiber Reinforced Concrete Market
Building Materials
Recycled Concrete Aggregates Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market
Building Materials
Light Gauge Steel Framing Market
Building Materials
Stone Adhesive Market
Building Materials
Blind Bolts Market
Building Materials
Bolt (Fastener) Market
Building Materials
Singapore Architectural Coatings Market
Building Materials
Europe Fireproof Cladding Market
Building Materials
Construction Materials Market