
 End Mill Holder Market | 2026-2036
End Mill Holder Market Size, Share, and Industry Trends Forecast 2026-2036
End Mill Holder Market Analysis
ISO 9001 and AS9100 qualification cycles is bifurcating the competitive landscape between certified precision suppliers and uncertified regional fabricators. Sandvik AB leverages its captive materials science division to sustain vertical integration from powder metallurgy through finished holder assembly. Haimer GmbH anchors its position through specialized balancing technology that commands premium positioning in German automotive supplier networks. Kennametal Inc. competes across North American aerospace corridors with hardened steel holder portfolios qualified to Boeing and Lockheed Martin supplier standards.
An end mill holder is a tapered or cylindrical tool interface that secures rotating cutting tools within machine tool spindles, typically manufactured from alloy steel or hardened stainless grades with HSK or BT taper geometries ground to micron-level concentricity tolerances. Its primary function is to transmit torque and axial clamping force while minimizing runout during high-speed material removal operations. Shrink fit holders now capture expanding margin pools in aerospace CNC machining where thermal interference fits outperform mechanical clamping at spindle speeds exceeding 20,000 RPM. Hydraulic holders dominate automotive transfer line applications where quick tool change protocols and vibration damping properties reduce cycle times in high-volume production environments. Standard collet holders retain volume leadership in general metal fabrication and job shop settings where capital constraints favor lower acquisition cost over performance optimization.
REACH substance restrictions and RoHS compliance directives in Europe constrain surface coating chemistries and heat treatment processes used in holder manufacturing, pushing suppliers toward environmentally compliant nitrocarburizing alternatives. The US FAA and NHTSA supplier qualification frameworks extend regulatory reach into aerospace and automotive tooling procurement, mandating traceable material certifications and statistical process control documentation. China's GB standards and MIIT industrial equipment directives establish parallel conformance requirements for import substitution programs targeting domestic CNC ecosystem development. Stakeholders must monitor divergence between Western and Chinese technical standards as dual supply chain strategies reshape certification investments and regional manufacturing footprints.
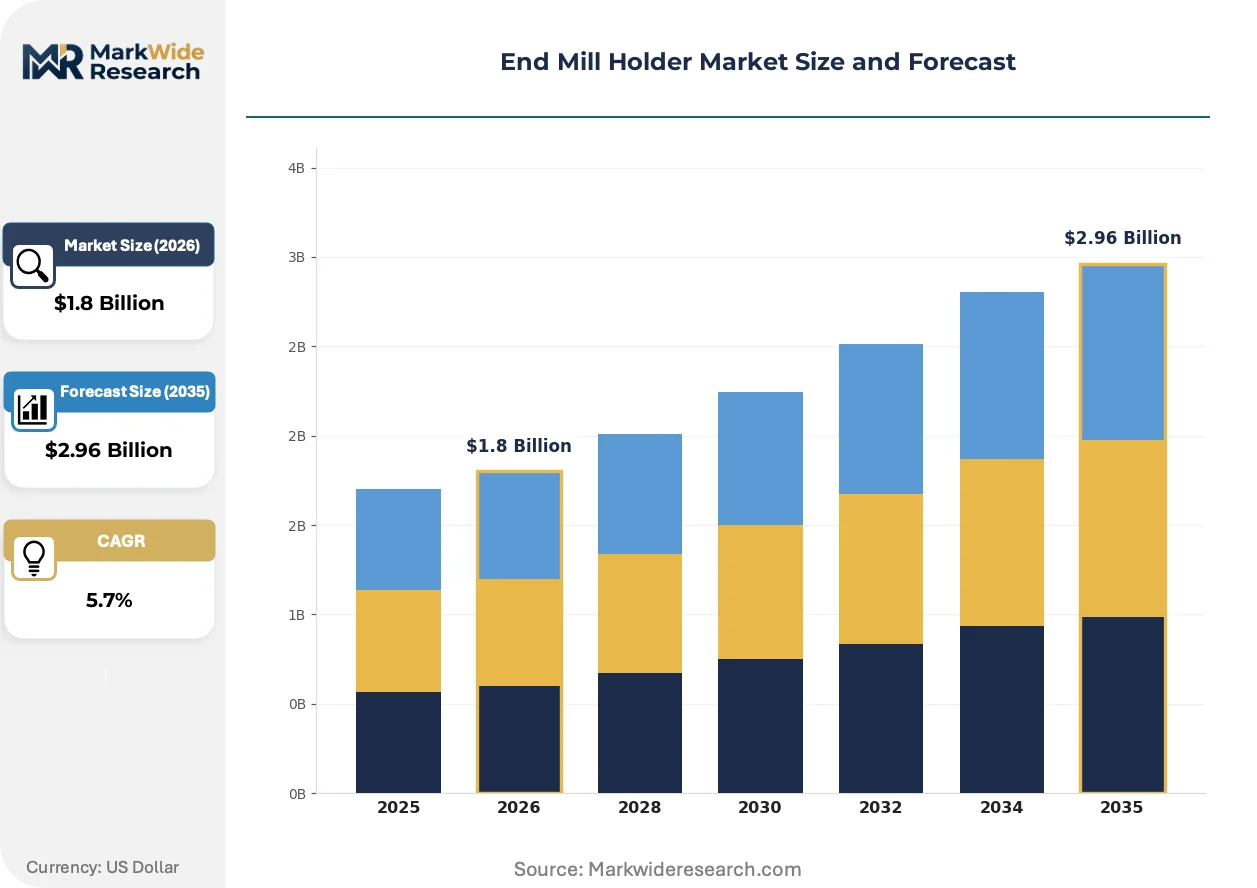
Market Dynamics
Shrink fit and hydraulic holder technologies are decomposing conventional collet systems in high-speed CNC applications as aerospace and automotive manufacturers prioritize micron-level concentricity tolerances over legacy mechanical clamping architectures.
Growth Catalysts
- AS9100 Certification Mandates:Tier-one aerospace suppliers in Germany and Japan face tightened procurement standards that favor precision-certified holder manufacturers over uncertified regional fabricators.
- East Asian Manufacturing Cluster Expansion:CNC machining density in Chinese and South Korean industrial corridors drives replacement cycles for conventional collet systems with thermal interference fit technologies.
- High-Speed Spindle Adoption:Spindle speeds exceeding 20,000 RPM in aerospace finishing operations create performance gaps that mechanical clamping cannot bridge.
Market Restraints
- Alloy Steel Input Volatility:Powder metallurgy feedstock costs fluctuate with nickel and cobalt spot markets, compressing margins for captive materials science divisions.
- European Regulatory Friction:REACH substance restrictions and RoHS compliance directives constrain surface coating chemistries and heat treatment processes used in holder manufacturing.
- Technical Limitation in Retrofit Compatibility:Shrink fit systems require specialized induction heating equipment that legacy machine shops cannot accommodate without capital redeployment.
Strategic Opportunities
- Underpenetrated Indian Aerospace Supply Base:CDSCO and BIS qualification pathways for precision tooling remain underdeveloped relative to Western certification density.
- Technology Convergence:Sensor-integrated smart holders combining vibration telemetry with hydraulic damping create predictive maintenance value propositions for automotive transfer lines.
- China's Import Substitution Programs:MIIT industrial equipment directives and GB standards establish parallel conformance requirements that favor domestic CNC ecosystem development.
Industry Challenges
- Balancing Technician Scarcity:Specialized spindle balancing expertise required for high-RPM applications concentrates in German and Japanese supplier networks.
- Dual Certification Burden:Suppliers pursuing both Western AS9100 and Chinese GB standard compliance face diverging documentation and statistical process control requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | End Mill Holder Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Holders, Collet Holders, Shrink Fit Holders, Hydraulic Holders Material: Steel, Aluminum, Carbon Fiber, Titanium Application: CNC Machining, Milling Operations, Metal Fabrication, Woodworking End User: Aerospace, Automotive, Manufacturing, Construction |
| Companies Covered | Sandvik AB, Kennametal Inc., Haimer GmbH, BIG KAISER Precision Tooling Inc., Guhring Inc., ISCAR Ltd., Seco Tools AB, Emuge-Franken, Nachi-Fujikoshi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
End Mill Holder Market Emerging Trajectories
Tooling interface architectures are fragmenting along performance-versus-cost fault lines as end-users segment procurement between premium precision systems and commoditized general fabrication equipment.
Shrink fit holder technology is decomposing mechanical clamping market share through thermal interference fits that eliminate collet runout at extreme spindle speeds. Aerospace finishing cells in Germany and Japan adopt these systems fastest where AS9100 traceability requirements intersect with micron-tolerance part specifications. The structural consequence compresses pricing power for conventional collet manufacturers while expanding margin pools for thermal-fit system specialists.
REACH and RoHS directives in Europe constrain legacy surface coating chemistries including hexavalent chromium conversion treatments and certain phosphate formulations. Holder manufacturers redirect toward environmentally compliant nitrocarburizing alternatives that meet ECHA substance restrictions without sacrificing wear resistance. German automotive supplier networks face the steepest compliance timelines given KBA oversight of production equipment environmental credentials.
Buyer consolidation among tier-one aerospace contractors compresses supplier qualification cycles and unbundles after-sales service from hardware procurement. Boeing and Lockheed Martin supplier standards now mandate traceable material certifications and statistical process control documentation that smaller fabricators cannot sustain. North American aerospace corridors exhibit the most pronounced consolidation effects as FAA qualification frameworks extend regulatory reach into tooling procurement decisions.
End Mill Holder Market Segmentation
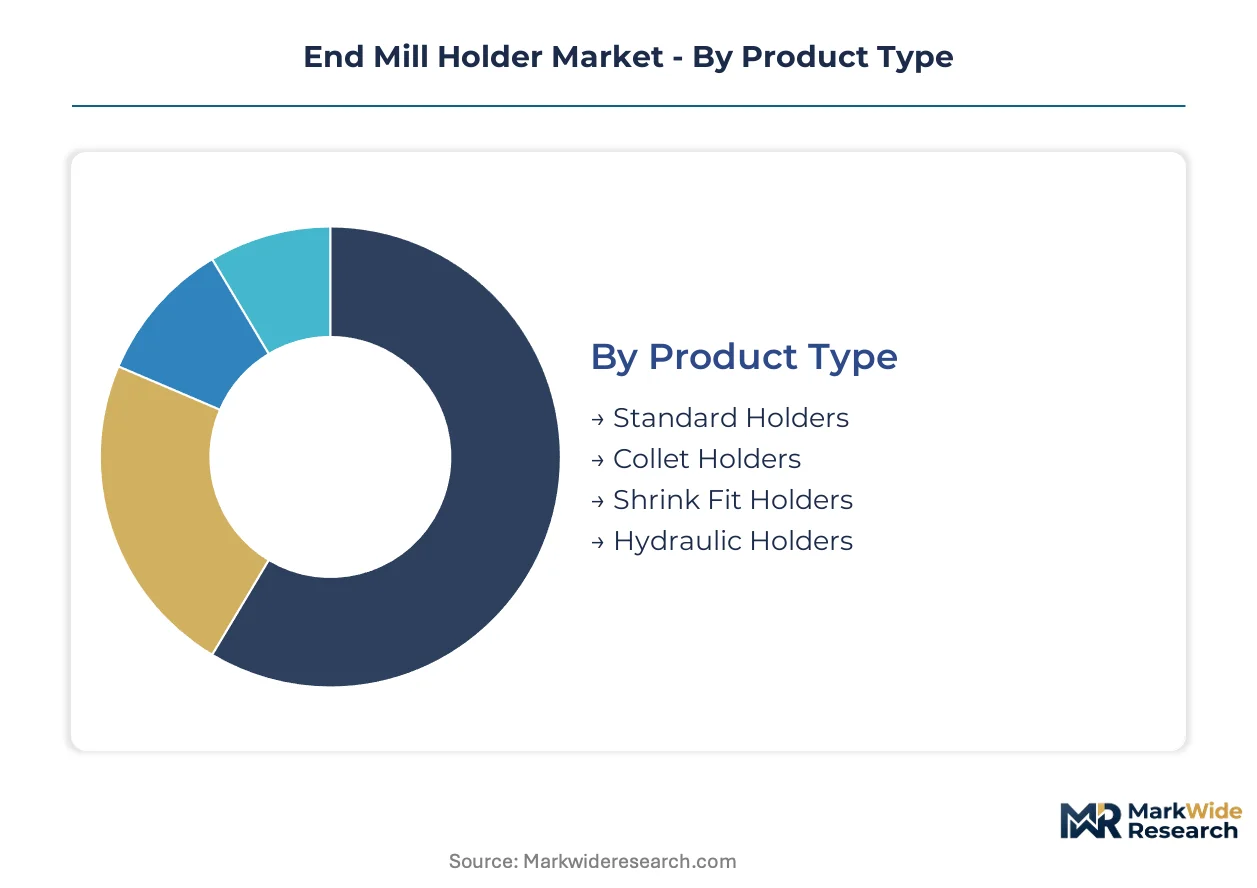
End mill holder procurement splits across performance tiers and regulatory compliance thresholds. Aerospace and automotive buyers segment purchases by spindle speed requirements and certification mandates rather than unit economics alone.
Product Type:
REACH substance restrictions and FAA qualification frameworks differentiate procurement eligibility across holder architectures.
- Shrink Fit Holders:Thermal interference fits eliminate mechanical runout through controlled induction heating cycles. Aerospace finishing cells in Germany and Japan prioritize these systems where AS9100 traceability intersects with spindle speeds exceeding 20,000 RPM.
- Hydraulic Holders:Internal damping chambers transmit clamping force through fluid pressure rather than mechanical collet compression. Automotive transfer lines in Stuttgart and Detroit specify these for vibration attenuation during high-volume production cycles.
- Collet Holders:Mechanical spring-collet architectures dominate general metal fabrication where capital constraints override performance optimization.
- Standard Holders:Basic tapered interfaces serve woodworking and light machining applications with minimal tolerance requirements.
Established volume favors collet holders; emerging adoption favors shrink fit systems.
Material:
Material selection concentrates in alloy systems where powder metallurgy capabilities determine supplier qualification status.
- Steel:Hardened alloy grades with HSK or BT taper geometries ground to micron-level concentricity form the baseline for aerospace-qualified production. German automotive networks source through Sandvik's captive materials science division for traceable heat treatment documentation.
- Titanium:Lightweight structural properties suit spindle applications where rotational inertia reduction improves acceleration response. Japanese precision manufacturers specify titanium holders for high-speed finishing operations in aerospace component cells.
- Aluminum:Lower mass and cost position these holders in woodworking and general fabrication where thermal stability requirements relax.
- Carbon Fiber:Emerging composite architectures target extreme weight reduction in specialized racing and aerospace prototyping applications.
Steel maintains procurement dominance; titanium claims the steepest expansion trajectory in certified precision supply chains.
Application:
Process-specific spindle dynamics and surface finish requirements fragment demand across machining modalities.
- CNC Machining:Computer-numerical control applications demand micron-level repeatability and automated tool change compatibility. East Asian manufacturing clusters in South Korea and China drive replacement cycles toward thermal-fit and hydraulic systems.
- Milling Operations:Material removal processes with variable cutting loads prioritize vibration damping and torque transmission stability. North American aerospace corridors specify holders qualified to Boeing and Lockheed Martin supplier standards.
- Metal Fabrication:Job shop environments with mixed part volumes favor conventional collet systems for flexibility across tool diameters.
- Woodworking:Lower spindle speeds and reduced precision tolerances accommodate standard holder architectures with minimal surface treatment requirements.
CNC machining commands premium positioning; metal fabrication sustains volume leadership through capital-constrained procurement.
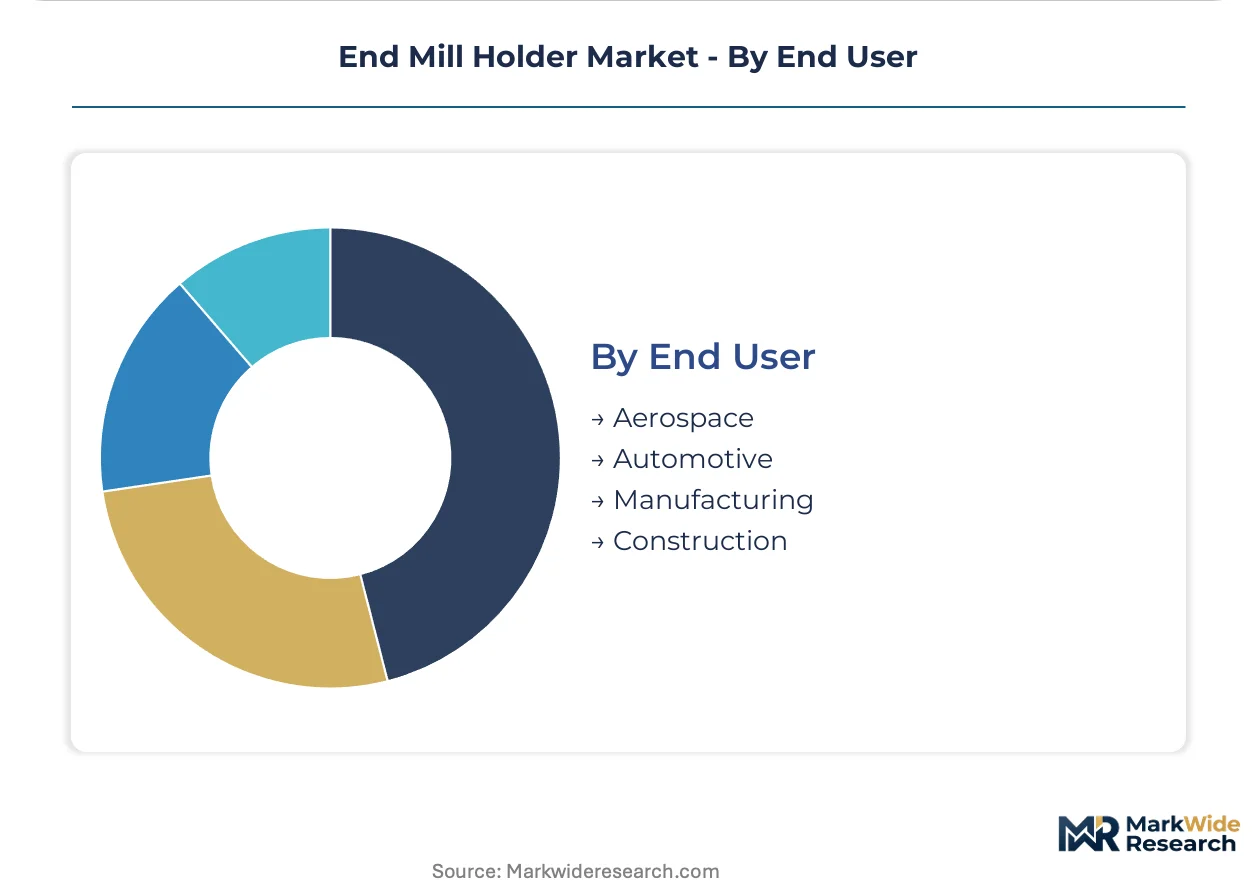
End User:
Industry-specific certification density and spindle technology adoption rates stratify demand by compliance burden.
- Aerospace:AS9100 and ISO 9001 qualification cycles bifurcate supply chains between certified precision manufacturers and uncertified regional fabricators. Tier-one suppliers in Germany and Japan face tightened procurement standards that mandate traceable material certifications.
- Automotive:High-volume transfer line operations prioritize quick tool change protocols and predictive maintenance integration. German supplier networks under KBA environmental oversight specify nitrocarburized surface treatments compliant with REACH directives.
- Manufacturing:General industrial machining spans performance tiers from precision aerospace subcontracting to commodity fabrication.
- Construction:Heavy equipment and structural metalworking applications tolerate lower precision specifications in favor of durability and cost efficiency.
Aerospace concentrates margin capture; automotive sustains volume scale through standardized procurement programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace manufacturers and automotive suppliers concentrate procurement power across four industrialized markets where certification density and spindle technology adoption create distinct competitive arenas.
Germany
AS9100-qualified tier-one suppliers in Stuttgart and Munich drive shrink fit holder adoption for aerospace finishing cells. KBA environmental oversight mandates REACH-compliant nitrocarburizing surface treatments for production equipment. The Baden-Württemberg automotive corridor specifies hydraulic holders for vibration-damped transfer line operations.
United States
Boeing and Lockheed Martin supplier standards mandate traceable material certifications for precision tooling procurement. FAA qualification frameworks extend regulatory reach into aerospace manufacturing equipment decisions. The Pacific Northwest and Texas aerospace clusters exhibit pronounced buyer consolidation among tier-one contractors.
Japan
METI industrial policy supports precision tooling ecosystem development alongside automotive and aerospace export manufacturing. JIS standards establish conformance baselines for domestic CNC equipment procurement. The Nagoya aerospace corridor and Osaka precision manufacturing belt prioritize micron-level concentricity tolerances in holder specifications.
China
MIIT industrial equipment directives and GB standards establish parallel conformance requirements for import substitution programs. The Yangtze River Delta and Pearl River Delta manufacturing clusters drive replacement cycles toward thermal-fit and hydraulic systems. Domestic CNC ecosystem development favors suppliers achieving dual Western and Chinese certification compliance.
South Korea
MFDS oversight of medical device manufacturing equipment creates adjacent demand for precision-certified holders. The Busan-Ulsan automotive and shipbuilding corridor specifies vibration-damped hydraulic systems for high-volume production environments. Seoul Capital Area electronics manufacturers adopt shrink fit technology for semiconductor equipment fabrication.
End Mill Holder Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with captive materials science capabilities alongside specialized precision tooling houses. Market structure exhibits tiered consolidation where AS9100-certified suppliers command premium positioning against uncertified regional fabricators. Three strategic archetypes dominate: vertically integrated materials-to-assembly conglomerates, balancing-technology specialists, and volume-focused generalist manufacturers. Competitive moves concentrate on certification-driven customer lock-in and geographic expansion through distributor partnerships.
Within the diversified conglomerate tier, Sandvik AB and Kennametal Inc. occupy positions anchored by captive powder metallurgy and heat treatment capabilities. Haimer GmbH exemplifies the specialist archetype through its German automotive supplier network positioning. These three entities represent the structural fault line between certified precision supply chains and price-competitive general fabrication markets.
| Leading Market Players |
|---|
| Sandvik AB |
| Kennametal Inc. |
| Haimer GmbH |
| BIG KAISER Precision Tooling Inc. |
| Guhring Inc. |
| ISCAR Ltd. |
| Seco Tools AB |
| Emuge-Franken |
| Nachi-Fujikoshi |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day powder metallurgy feedstock lead times in German and Japanese supply corridors concentrate pricing power among captive materials science divisions while compressing margin flexibility for tier-two fabricators. AS9100 certification density shapes procurement premiums across aerospace corridors, with traceable heat treatment documentation commanding substantial uplifts over uncertified regional alternatives.
Pricing Analysis
Cost-plus contracts indexed to nickel and cobalt spot markets dominate raw material procurement between Sandvik AB's materials division and tier-one aerospace suppliers. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and spindle speed capability, with AS9100-qualified thermal-fit systems capturing substantial premiums. Cost compression in standard collet tiers intensifies because Chinese import substitution programs flood general fabrication channels. Job shop metal fabricators exhibit highest price sensitivity; German automotive supplier networks show least sensitivity given KBA-mandated environmental compliance requirements.
Supply Chain Analysis
Strategic stockpiling of powder metallurgy feedstock characterizes tier-one supplier behavior, while just-in-time inventory protocols dominate general fabrication channels vulnerable to nickel spot volatility. Manufacturing concentrates in Germany, Japan, and China, with Baden-Württemberg and Nagoya corridors anchoring precision output. Alloy steel billets, cobalt binder powders, and nitrocarburizing surface treatments constitute critical input dependencies. Single-source vulnerability concentrates in Sandvik's captive tungsten carbide supply. Distribution runs through authorized distributor networks with Boeing and Lockheed Martin supplier qualification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The end mill holder market functions as a defensive-moat story where AS9100 certification entrenchment creates prohibitive switching costs for tier-one aerospace procurement officers.
For Market Incumbents: Shield market position by deepening backward integration into powder metallurgy feedstock production and accelerating dual-certification investments for Chinese GB standard compliance. Hydraulic holder technology faces substitution risk from sensor-integrated smart holder architectures; preemptive R&D in vibration telemetry integration represents the critical defensive lever. For New Entrants and Emerging Players: Aftermarket balancing service underperformance by established German suppliers creates immediate white-space opportunity in Indian aerospace supply base qualification support. CDSCO and BIS certification pathway advisory services offer the most penetrable entry vector. Partner with Mumbai and Bangalore precision manufacturing clusters on joint-qualification programs rather than hardware manufacturing. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because certification density concentrates margin capture in aerospace and automotive supplier networks with decade-long qualification cycles. Target mid-tier precision tooling houses with existing AS9100 documentation and latent capacity for GB standard expansion. Watch for MIIT industrial equipment directive acceleration as inflection signal indicating Chinese domestic ecosystem maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Simultaneous AS9100 and GB standard compliance unlocks Boeing and COMAC supplier eligibility. |
| Backward Integration into Powder Metallurgy | Captive tungsten carbide supply insulates Sandvik AB from cobalt spot market volatility. |
| Smart Holder Technology Development | Sensor-integrated vibration telemetry creates predictive maintenance value for Stuttgart automotive transfer lines. |
| Indian Aerospace Qualification Partnership | CDSCO and BIS pathway advisory services penetrate underdeveloped certification infrastructure in Bangalore clusters. |
| Nitrocarburizing Process Transition | REACH-compliant surface treatments satisfy KBA environmental oversight for German automotive supplier networks. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with CNC machining cell managers, aerospace procurement officers, automotive supplier quality directors, and precision tooling distributor principals; and secondary validation through SEC 10-K filings, customs trade databases, FAA supplier qualification registries, and JIS standard documentation. Bottom-up and top-down triangulation reconciled unit shipment estimates with aggregate market value assessments.
Across the projection horizon, the analytical framework modeled demand by product architecture, material grade, spindle speed tier, end-use industry, and regional certification density. CAGRs derived from regression analysis against CNC machine tool installation rates and aerospace production backlogs. Forecast inputs incorporated REACH substance restriction timelines and MIIT import substitution program acceleration curves.
Forecasts assume regulatory continuity in ECHA, FAA, and MIIT regimes; material policy shifts would require re-modeling. Alloy steel input cost volatility, dual certification documentation divergence, and Chinese domestic CNC ecosystem maturation pace constitute primary forecast risks. Revision becomes warranted when shrink fit holder penetration in East Asian manufacturing clusters crosses threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Pneumatic Marking Machines Market
Tools
Tool Storage Market
Tools
Assembly Fastening Tool Market
Tools
Rivet Busters Market
Tools
Scroll Saws Market
Tools
Global Cordless Power Tools Market
Tools
Pipe Alignment Clamps Market
Tools
Air Drills Market
Tools
Horizontal Milling Machine Market
Tools
Powder Compacting Pressers Market
Tools
Mechanical Hand Tools Market
Tools
Portable Boring Machines Market
Tools
Global Electric Portable Drill Market
Tools
Water Pump Pliers Market
Tools
Global Protractor Market
Tools
Diamond Hole Saw Market