
 Sprayed Concrete Market | 2026-2036
Sprayed Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Sprayed Concrete Market Outlook
Digital twin integration for real-time application monitoring is reconfiguring quality assurance workflows in sprayed concrete operations. Sika leverages its additive chemistry portfolio to sustain specification-grade performance across wet-mix and fiber-reinforced systems. BASF SE anchors its position through advanced admixture R&D that controls rebound rates and accelerates set times in demanding underground environments.
Sprayed concrete, also termed shotcrete, comprises cement, aggregates, and water pneumatically projected at high velocity onto vertical or overhead surfaces, typically achieving compressive strengths of 25–50 MPa depending on mix design and accelerator dosage. Its primary purpose is structural support, waterproofing, and surface restoration in confined or geometrically complex spaces. Wet-mix technology dominates volume due to lower dust emissions and consistent hydration control, while fiber-reinforced formulations capture expanding margin pools as owners specify ductility for seismic and mining loads. Tunneling and underground construction absorb the largest application share, though slope stabilization grows fastest where climate-induced geohazard mitigation intensifies.
OSHA silica exposure limits and EPA fugitive dust standards tighten jobsite compliance requirements across the United States, while REACH registration and CE marking govern chemical admixture composition and structural performance claims throughout Europe. In China, GB standards issued by SAMR establish mandatory quality thresholds for infrastructure-grade shotcrete used in rail and hydropower tunnels. Stakeholders must weigh accelerator chemistry choices against emerging carbon-accounting frameworks that threaten to recertify conventional Portland-based formulations.
Market Dynamics
The EU Green Deal's carbon benchmarking requirements are forcing sprayed concrete producers to reformulate Portland-based systems, compressing margins for conventional accelerators while opening specification windows for low-emission alternatives.
Growth Catalysts
- Tunneling Megaprojects:China's rail and hydropower tunnel pipelines absorb shotcrete volumes at scale, with India following through Himalayan infrastructure corridors.
- REACH Registration Compliance:Chemical admixture producers advancing CE-marked formulations capture preferential positioning across European public procurement.
- Fiber-Reinforced Formulations:Synthetic and steel fiber integration addresses seismic load specifications in Japan's underground construction codes.
Market Restraints
- Alkali-Free Accelerator Cost Premium:Low-alkali chemistries required for corrosion-sensitive applications carry 15-25% input cost premiums over conventional sodium aluminate systems.
- Silica Supply Concentration:High-purity silica fume production clusters in Norway and China, exposing formulators to freight-driven volatility.
- Rebound Rate Limitations:Wet-mix systems still lose 5-15% material to rebound in overhead applications, creating waste accounting liabilities under emerging carbon frameworks.
Strategic Opportunities
- Indonesia's Underpenetrated Mining Sector:Nickel and copper expansion in Sulawesi and Papua creates demand for ground support shotcrete with limited local supply capacity.
- Digital Twin Convergence:Real-time nozzle positioning integrated with rheology sensors enables thickness verification without destructive testing.
- EU Taxonomy Alignment:Green bond eligibility for low-carbon construction materials creates financing advantages for specifiers choosing certified low-emission shotcrete.
Industry Challenges
- Nozzle Operator Skill Scarcity:Proper accelerator dosing and spray angle control require 2-3 years apprenticeship; aging workforces in Germany and Japan constrain output quality.
- CE Marking Timeline Compression:Accelerated conformity assessment demands for new admixture chemistries extend time-to-market by 8-14 months.
- Legacy Equipment Retrofit Costs:Wet-mix pumps with integrated fiber dosing require capital outlays that smaller tunneling contractors defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sprayed Concrete Market |
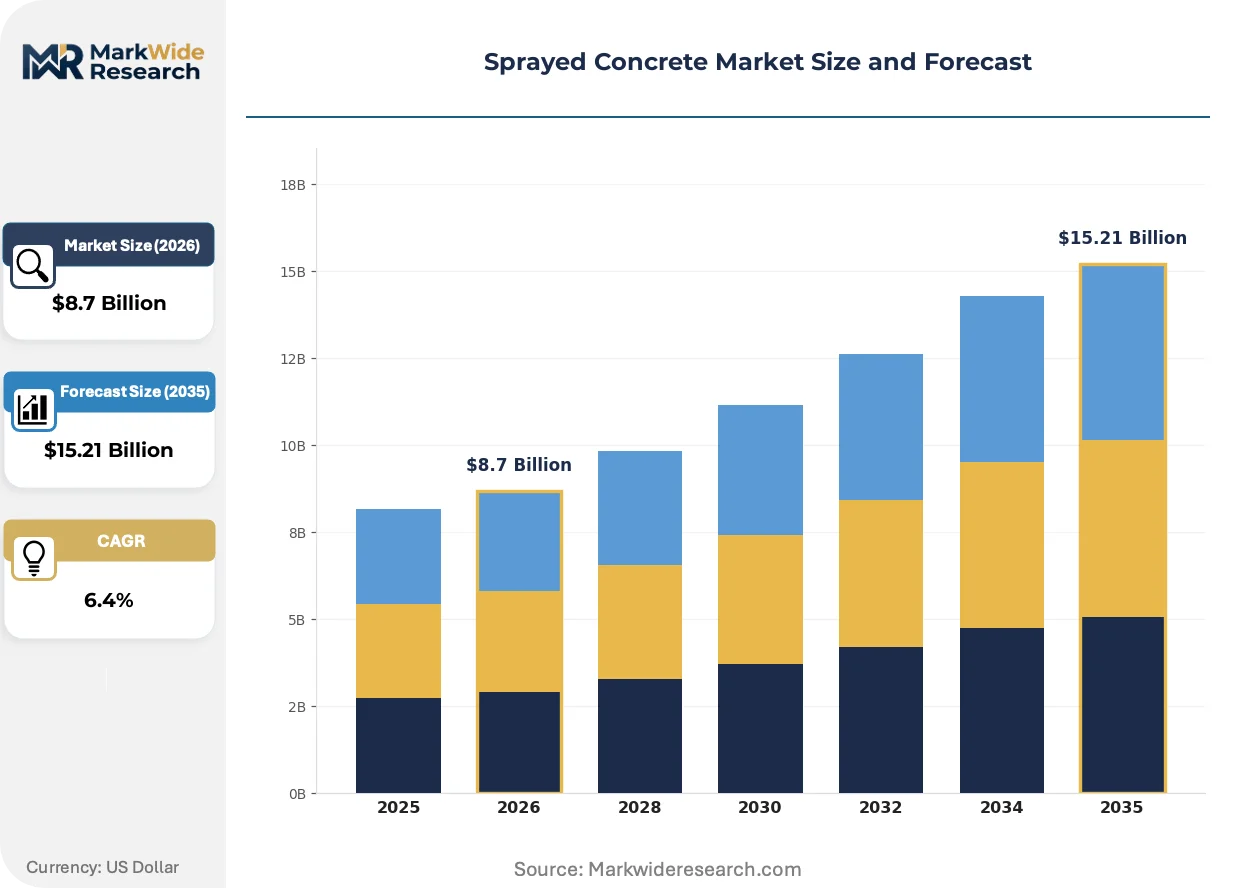
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Tunneling, Underground Construction, Slope Stabilization, Repair Works Technology: Wet Mix, Dry Mix, Shotcrete, Fiber-Reinforced End User: Construction, Mining, Infrastructure, Oil & Gas Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Sika, BASF SE, The Euclid Chemical Company, Cemex, LKAB Berg & Betong, Normet, Mapei, GCP Applied Technologies, Putzmeister, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sprayed Concrete Market Strategic Shifts
Shotcrete application workflows are digitizing rapidly, with sensor integration and predictive analytics compressing quality assurance cycles while regulatory carbon accounting penetrates specification criteria.
Alkali-free accelerator chemistry is rendering obsolete sodium aluminate formulations in corrosion-critical infrastructure. European rail tunnel contractors specify these systems for 50-year design life guarantees. The shift compresses the addressable market for conventional accelerators while elevating technical service requirements.
REACH Annex XIV restrictions on crystalline silica content in construction materials tighten admissible exposure thresholds. Formulators reformulate aggregate grading curves and binder systems to maintain pumpability. German and Austrian tunneling segments lead compliance adoption, with specification language migrating into Swiss and Nordic procurement templates.
Performance-based contractor selection is displacing unit-price bidding in Scandinavian underground projects. Owner-operators in Norway and Finland bundle shotcrete supply with guaranteed thickness and strength outcomes, transferring application risk to material suppliers. This compresses margins for equipment-only vendors while rewarding integrated system providers.
Sprayed Concrete Market Segmentation
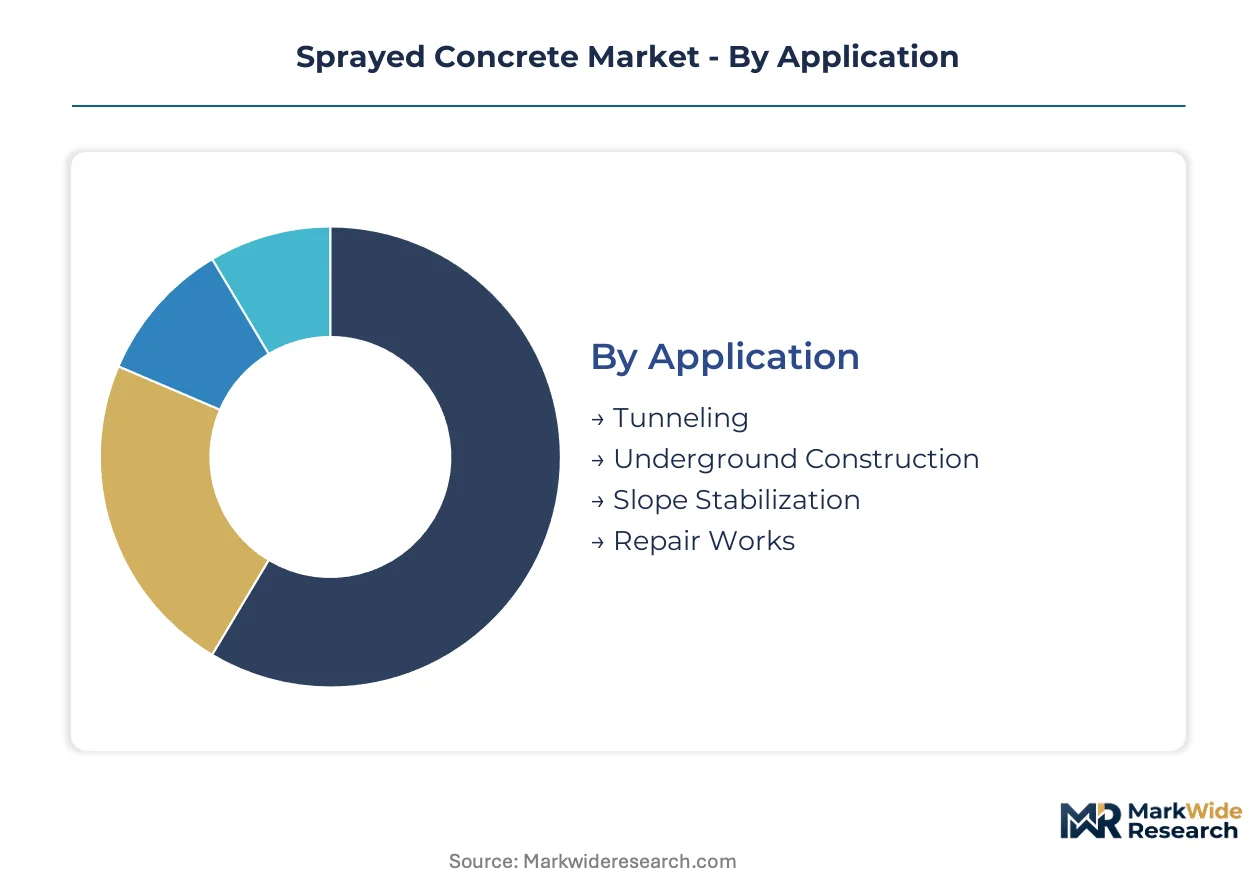
Sprayed concrete specifications diverge sharply across application environments, with tunneling contractors demanding accelerator-controlled set times while mining operators prioritize fiber-reinforced ductility. Technology choices determine equipment capital requirements and dust emission profiles. End-user procurement patterns split between project-based direct sourcing and distributor-mediated supply for maintenance applications.
Application:
Mature infrastructure corridors dominate volume, while emerging climate adaptation applications reshape specification priorities.
- Tunneling:Shotcrete provides primary ground support in rail and hydropower tunnels, with wet-mix systems specified for 25-50 MPa compressive strength targets. China's Sichuan-Tibet rail corridor and India's Himalayan road tunnels absorb substantial volumes as megaproject pipelines accelerate.
- Underground Construction:Metro stations, caverns, and utility tunnels require waterproofing layers and structural linings with controlled rebound rates. German urban rail expansions in Munich and Stuttgart specify alkali-free accelerators for 50-year design life guarantees in corrosion-sensitive environments.
- Slope Stabilization:Climate-induced landslide mitigation drives adoption in Japan's mountainous prefectures and Peru's Andean mining corridors.
- Repair Works:Bridge soffits, dam faces, and marine structures utilize low-alkali formulations for chloride-exposed concrete restoration.
Tunneling handles the majority of throughput; slope stabilization is the fastest mover on share.
Technology:
Cost tier separation between established wet-mix infrastructure and premium fiber-integrated systems defines competitive positioning.
- Wet Mix:Pre-batched concrete with controlled water-cement ratios delivers consistent hydration and reduced dust emissions versus dry-mix alternatives. European urban construction mandates specify wet-mix for EPA and REACH compliance in enclosed underground environments.
- Dry Mix:Aggregates and cement conveyed pneumatically with water added at the nozzle suit remote sites lacking batching infrastructure. Australian mining operations in Western Australia rely on dry-mix portability for exploration decline development.
- Shotcrete:Generic term encompassing both wet and dry pneumatic application methods; specification language varies by regional engineering standards.
- Fiber-Reinforced:Synthetic macro-fibers or steel fibers enhance post-crack ductility for seismic and dynamic load conditions. Japan's building code revisions for underground structures mandate fiber integration in high seismic zones.
Wet mix commands the volume base; fiber-reinforced formulations capture expanding margin pools.
End User:
Customer type determines specification authority, with owner-operators dictating performance standards and contractors optimizing for placement productivity.
- Construction:General contractors executing commercial and residential basements, swimming pools, and architectural features specify standard-grade wet-mix with conventional accelerators.
- Mining:Hard-rock and soft-ground operations demand rapid-setting ground support for cycle time compression. Indonesia's nickel belt expansion in Sulawesi creates demand for corrosion-resistant formulations in humid, saline conditions.
- Infrastructure:State-owned rail and highway authorities prescribe performance-based contractor selection with guaranteed thickness outcomes. Norway's Public Roads Administration bundles shotcrete supply with quality verification protocols.
- Oil & Gas:Offshore platform repairs and subsea infrastructure utilize specialized low-rebound formulations for splash zone applications.
Infrastructure clients anchor specification-grade demand; mining represents the steepest expansion trajectory.
Distribution Channel:
Supply concentration in admixture chemistry creates channel leverage for integrated system providers versus equipment-only vendors.
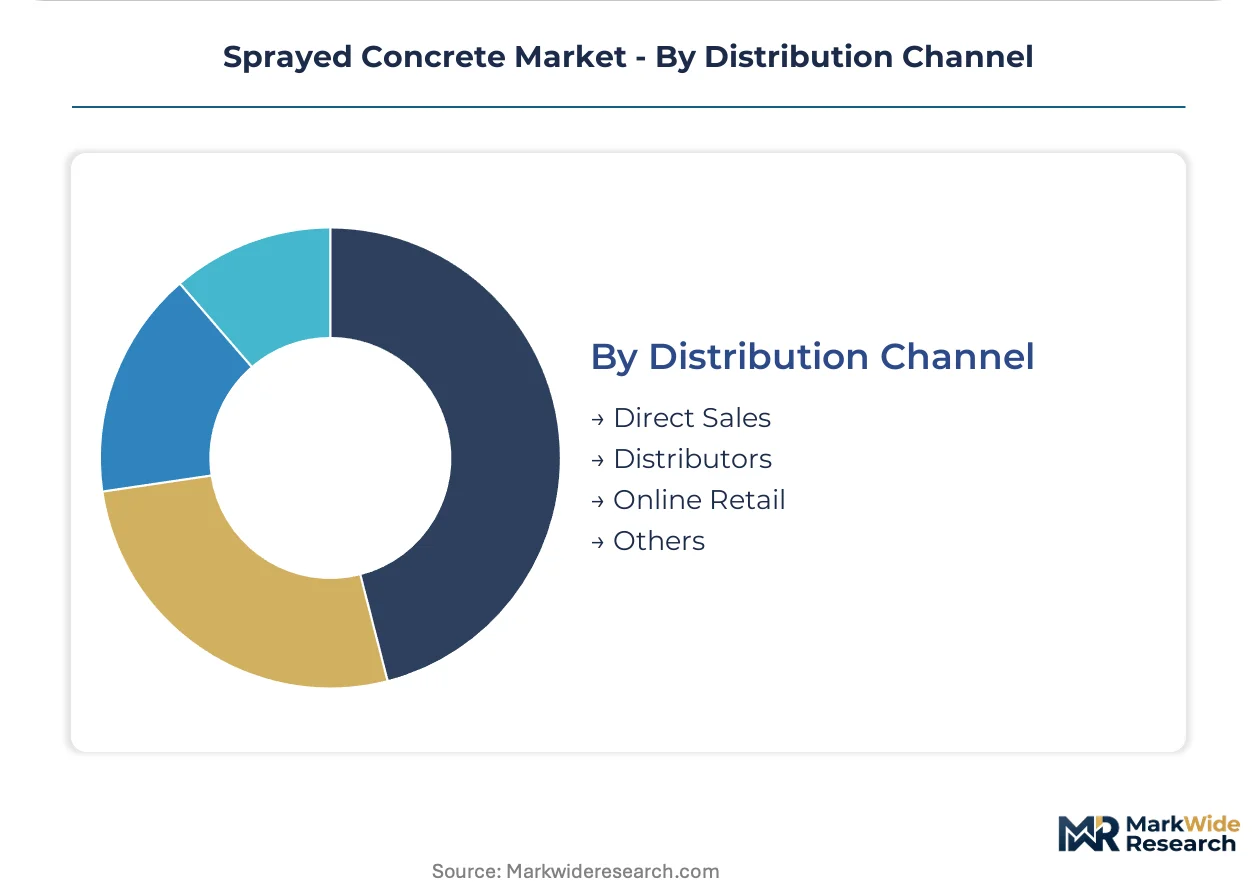
- Direct Sales:Large tunneling contractors and mining houses negotiate frame contracts with admixture producers for guaranteed accelerator supply and technical service support.
- Distributors:Regional construction supply networks handle bagged cement, pre-blended dry mixes, and smaller accelerator volumes for repair contractors.
- Online Retail:Equipment components, nozzles, and consumables migrate to digital procurement platforms for standardized SKU fulfillment.
- Others:Equipment leasing arrangements and application subcontracting bundle material supply with placement services.
Direct sales channels handle project-scale volume; distributor networks serve fragmented repair and maintenance demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German admixture producers export alkali-free accelerator systems to tunneling contractors across Scandinavia and the Alpine corridor, while Chinese shotcrete volumes flow inland toward Sichuan-Tibet rail megaprojects.
China
SAMR's GB standards mandate quality thresholds for rail and hydropower tunnel shotcrete, compressing informal supply. The Sichuan-Tibet rail corridor and Yangtze River hydropower cascade absorb wet-mix volumes at scale. Chengdu and Chongqing anchor formulation R&D clusters serving western infrastructure expansion.
Germany
Munich and Stuttgart urban rail expansions specify alkali-free accelerators for 50-year corrosion guarantees under EU Green Deal carbon benchmarks. CE marking governs admixture composition claims. The Rhine-Ruhr industrial corridor concentrates equipment manufacturing and technical service capabilities for European export.
India
Himalayan road tunnels and metro construction in Delhi-NCR and Mumbai drive wet-mix adoption. The country's national construction regulator enforces structural performance standards for underground infrastructure. Gujarat and Maharashtra host batching plant clusters supplying western and southern project corridors.
Japan
Meti oversees building code revisions mandating fiber-reinforced shotcrete in high-seismic zones. Kanto and Kansai underground rail expansions specify ductility-grade formulations. Osaka-based technical institutes collaborate with contractors on nozzle automation for aging workforce replacement.
Indonesia
Nickel and copper expansion in Sulawesi and Papua creates demand for corrosion-resistant ground support in humid, saline conditions. Limited local supply capacity opens import dependence for specification-grade systems. Jakarta-based distributors mediate frame contracts with international admixture producers.
Sprayed Concrete Market Competitive Environment
On the supply side, the industry is consolidating around integrated system providers that bundle admixture chemistry with application equipment and technical service. Three archetypes dominate: multinational chemical conglomerates with construction divisions, specialized underground equipment manufacturers with captive admixture supply, and regional batching operators serving fragmented repair demand. Competitive moves concentrate on portfolio diversification into low-emission formulations and strategic partnerships for digital twin integration.
Within the multinational chemical tier, Sika and BASF SE exemplify integrated positioning across wet-mix and fiber-reinforced systems. Sika leverages its additive chemistry portfolio to sustain specification-grade performance, while BASF SE anchors its position through advanced admixture R&D. Among equipment-specialist players, Normet occupies a position linking machinery supply with technical service capabilities for mining and tunneling applications.
| Leading Market Players |
|---|
| Sika |
| BASF SE |
| The Euclid Chemical Company |
| Cemex |
| LKAB Berg & Betong |
| Normet |
| Mapei |
| GCP Applied Technologies |
| Putzmeister |
| Others |
Value Chain & Pricing Dynamics
Silica supply concentration in Norway and China determines both pricing tier spreads and supply chain shape, as freight-driven volatility in high-purity silica fume cascades through accelerator cost structures and forces formulators into long-term offtake commitments or regional sourcing pivots.
Pricing Analysis
Wet-mix versus fiber-reinforced versus dry-mix technology generations command distinct pricing bands, with fiber-reinforced formulations capturing premium positioning due to seismic certification requirements in Japan's building codes. Three-tier pricing structure across specification-grade alkali-free accelerators, standard sodium aluminate systems, and economy dry-mix alternatives reflects certification level and volume scale differentiation. Pricing pressure stems from EU Green Deal carbon benchmarking as conventional Portland-based formulations face recertification costs. Mining contractors in Indonesia exhibit highest price sensitivity due to project finance constraints, while German rail authorities prioritize 50-year design life guarantees over unit cost.
Supply Chain Analysis
REACH Annex XIV crystalline silica restrictions function as de facto export controls on formulation chemistry, limiting admixture flows into European procurement channels. Supply concentrates in Germany for alkali-free accelerator R&D, China for wet-mix volume production, and Norway for high-purity silica fume extraction. Raw material dependencies span Portland cement clinker, synthetic macro-fibers, and alkali-free accelerator precursors. Single-source vulnerability in silica fume exposes formulators to freight-driven input cost spikes. Distribution runs through direct frame contracts between multinational admixture producers and tunneling contractors, with regional distributors handling fragmented repair demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sprayed concrete specification workflows are consolidating around integrated system providers, as digital twin convergence and performance-based contracting create platform economics where bundled chemistry-equipment-service offerings displace point-product vendors.
For Market Incumbents: Entrench specification authority through captive supply of alkali-free accelerator chemistry and integrated fiber dosing equipment, defending against emerging low-emission formulation specialists by locking in 50-year design life guarantees with German and Scandinavian rail authorities. Deepen backward integration into silica fume sourcing to mitigate Norwegian supply concentration risk. For New Entrants and Emerging Players: Establish a beachhead in Indonesia's nickel belt mining sector, where Sulawesi and Papua ground support demand outruns local supply capacity and corrosion-resistant formulation expertise commands premium positioning. Target direct frame contracts with Australian dry-mix contractors seeking alkali-free accelerator alternatives for remote site portability. For Investors and Strategic Acquirers: Regional batching operators with captive admixture blending capabilities and established technical service relationships represent the most defensible acquisition archetype, as performance-based contracting transfers application risk to material suppliers. Long-term viability hinges on EU Taxonomy alignment for green bond eligibility. The signal to watch is CE marking timeline compression for new accelerator chemistries, which extends time-to-market and favors incumbent integrated providers.| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Low-emission shotcrete formulations qualify for EU Taxonomy green bond financing advantages. |
| Backward Integration | Captive silica fume sourcing mitigates Norwegian supply concentration and freight volatility exposure. |
| Long-term Supply Agreement | Frame contracts with Chinese rail contractors secure volume commitments for Sichuan-Tibet corridor demand. |
| Joint Venture | Digital twin partnerships with Osaka-based automation institutes address Japan's nozzle operator skill scarcity. |
| Capacity Expansion | Alkali-free accelerator production scale-up in Germany serves Scandinavian and Alpine corridor specification demand. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with tunneling project managers, admixture R&D directors, mining procurement leads, and equipment service technicians; and secondary validation through customs trade data, CE marking registries, SEC filings of listed construction chemical producers, and infrastructure project development databases. Bottom-up volume estimates from megaproject pipelines triangulated against top-down market sizing from chemical admixture production disclosures.
Forecast inputs encompassed technology generation adoption curves, regulatory compliance timeline assumptions, and carbon accounting framework penetration rates across the projection horizon. Segmentation dimensions modeled include application environment, mix technology, fiber integration level, and regional specification authority. CAGRs were derived from elasticity-adjusted demand projections tied to tunneling investment cycles and mining capital expenditure patterns.
Stress conditions across silica supply disruption scenarios, REACH enforcement intensity variations, and Indonesian mining project approval delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU Green Deal implementation pacing and Chinese infrastructure stimulus continuity. Material shifts in carbon border adjustment mechanisms or SAMR quality threshold enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Cladding Market
Building Materials
Zinc Polycarboxylate Cement Market
Building Materials
Fireproof Cladding Market
Building Materials
Cement Tiles Market
Building Materials
ASEAN Dry Mix Mortar Market
Building Materials
Lightweight Cellular Concrete Market
Building Materials
Europe Cement Market
Building Materials
US Commercial Paving Slabs Market
Building Materials
Europe Exterior Sheathing Market
Building Materials
Roofing and Tile Underlayment Market
Building Materials
Fiber Cement Market
Building Materials
Concrete Market
Building Materials
Steel Slag Market
Building Materials
Cement Market
Building Materials
Spain Architectural Coatings Market
Building Materials
Solar Control Window Film Market