
 Stone Adhesive Market | 2026-2036
Stone Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Stone Adhesive Market Analysis
Buyer concentration among large-scale commercial contractors is decoupling from traditional masonry supply chains as heritage restoration and high-performance facade projects fragment procurement across specialized applicators. Sika AG leverages its European distribution density to sustain specification-grade positioning among restoration architects. Mapei S.p.A. anchors Mediterranean project pipelines through localized technical service teams. Henkel AG & Co. KGaA competes on construction adhesive cross-selling into stone bonding workflows.
Stone adhesives are formulated polymer systems—typically epoxy, polyurethane, or acrylic resins with mineral fillers and silane coupling agents—engineered to bond natural and engineered stone substrates under structural load and environmental exposure. These formulations cure through moisture-triggered or two-part catalytic reactions to achieve tensile adhesion strengths exceeding substrate cohesion in granite and marble applications. Epoxy formulations dominate structural anchoring and countertop fabrication where load-bearing performance commands premium positioning, while polyurethane adhesives capture fastest growth in exterior cladding and expansion-joint sealing as building envelope durability standards tighten. Acrylic segments occupy maintenance and repair niches where rapid cure and ambient temperature application offset lower ultimate strength.
EPA VOC regulations under the National Volatile Organic Compound Emission Standards for Consumer and Commercial Products constrain solvent-based formulation availability in the United States, while REACH Annex XVII restrictions on isocyanates and ECHA classification of certain epoxy hardeners reshape European product portfolios toward water-dispersible and low-monomer alternatives. Contractors and specifiers must monitor evolving harmonized product standards under the Construction Products Regulation and corresponding EN 12004 performance classifications to maintain market access across jurisdictions. Stakeholders should track formulation substitution timelines as regulatory thresholds descend and bio-based resin platforms mature.
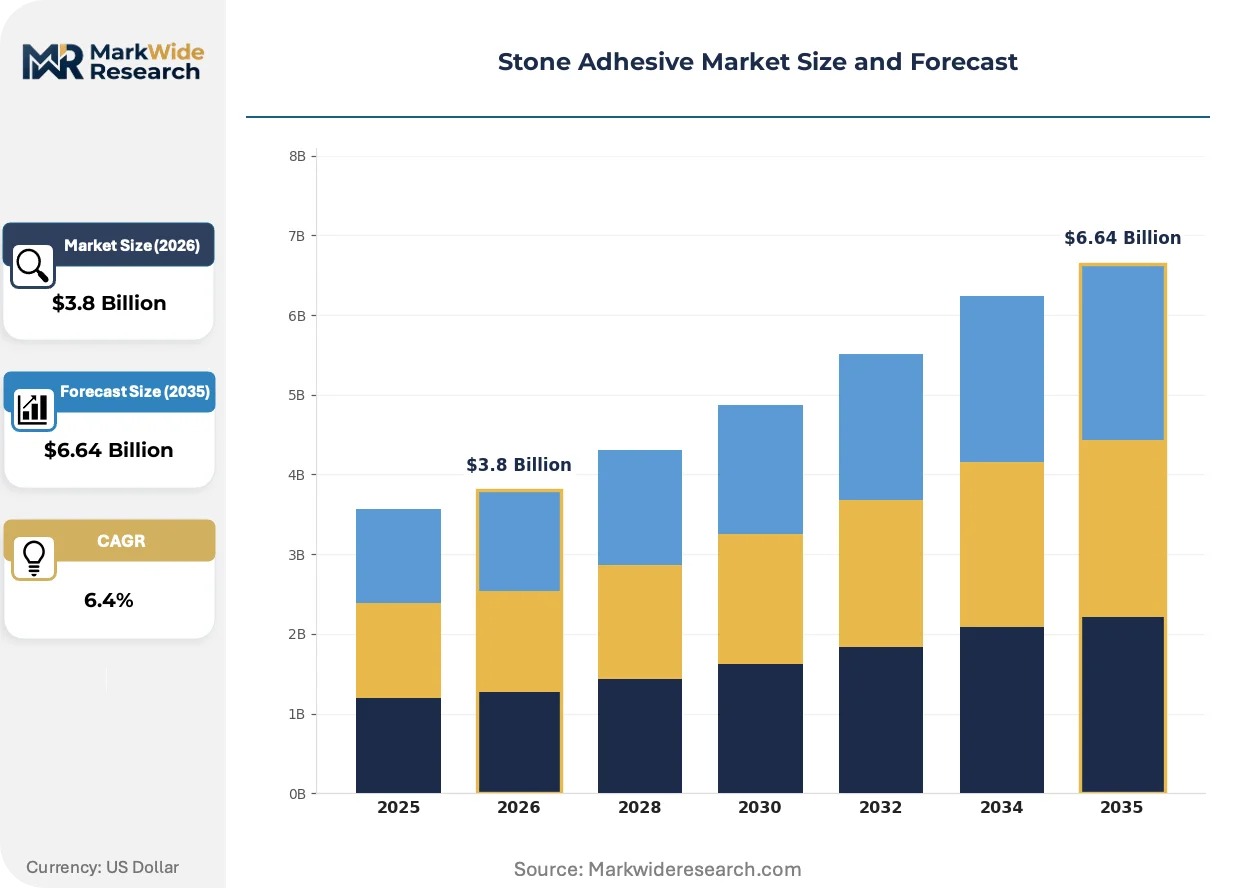
Market Dynamics
Facade retrofit cycles across mature construction markets are compressing specification timelines, forcing formulators to reconcile high-performance epoxy systems with tightening VOC thresholds under EPA and REACH frameworks.
Growth Catalysts
- Heritage Restoration Mandates:Government-funded preservation programs in Italy and Germany are specifying structural stone anchoring systems for cathedral and civic building renovations. Epoxy formulations with documented load-bearing performance dominate these tenders.
- REACH Annex XVII Isocyanate Restrictions:The ECHA classification of certain polyurethane hardeners is accelerating water-dispersible adhesive development. Formulators investing in low-monomer alternatives capture specification-grade positioning ahead of compliance deadlines.
- Cladding Retrofit Intensity:Commercial envelope durability standards in the United States are driving replacement cycles for failing mechanical fasteners. Adhesive-based stone anchoring displaces traditional pin-and-wire systems in high-rise applications.
Market Restraints
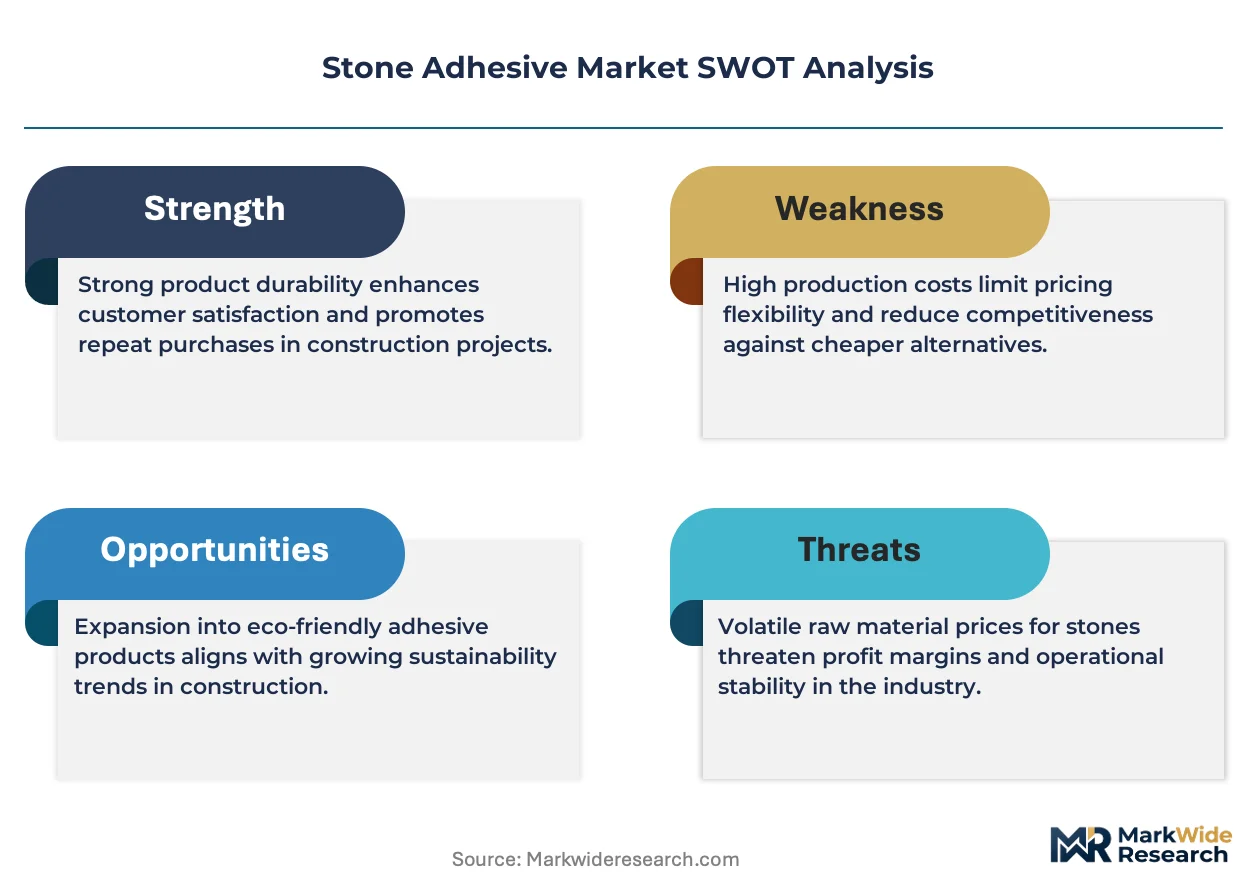
- Bisphenol A Feedstock Volatility:Epoxy resin production depends on petrochemical derivatives subject to refinery output fluctuations. Price instability compresses margin structures for mid-tier formulators lacking long-term supply contracts.
- Specialized Applicator Concentration:Structural stone bonding requires certified installation crews concentrated in Germany, Italy, and select US metropolitan markets. Geographic scarcity of qualified labor constrains project scaling in secondary regions.
- Ceramic Tile Substitution:Large-format porcelain slabs with printed stone aesthetics capture budget-sensitive commercial flooring and wall cladding. Lower material and installation costs displace natural stone in new construction segments.
Strategic Opportunities
- India Heritage Infrastructure:ASI-protected monument restoration and new temple construction create specification pathways for high-performance stone adhesives. Localized technical service capabilities remain underdeveloped relative to project pipeline growth.
- Bio-Based Epoxy Platforms:Lignin-derived and plant-oil epoxy resins are achieving performance parity in non-structural applications. Early movers in sustainable formulation secure green procurement preferences from public sector clients.
- Direct-to-Applicator Digital Channels:Specialized masonry contractors in fragmented European markets are bypassing traditional distributor tiers. E-procurement platforms with embedded technical documentation reduce specification friction for restoration specialists.
Industry Challenges
- EN 12004 Certification Timelines:Harmonized performance testing under the Construction Products Regulation requires multi-year validation cycles. Smaller formulators face capital constraints for sustained testing investment.
- Silane Coupling Agent Integration:Moisture-triggered adhesion chemistry demands precise ambient condition control during application. Field failure rates escalate when applicators lack substrate-specific training protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stone Adhesive Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylic, Silicone Application: Construction, Repairs, Artistic Projects, Landscaping End User: Contractors, DIY Enthusiasts, Architects, Engineers Distribution Channel: Retail, Online, Wholesale, Direct Sales |
| Companies Covered | Sika AG, Mapei S.p.A., Henkel AG & Co. KGaA, Laticrete International, Inc., Tenax S.p.A., Arkema Group, BASF SE, H.B. Fuller Company, ARDEX Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stone Adhesive Market Emerging Trajectories
Formulation chemistry is converging with digital specification tools and circular material mandates, compressing traditional development cycles while opening new performance categories.
Hybrid epoxy-acrylic systems are unifying rapid cure characteristics with structural load capacity. Restoration contractors in Milan and Munich are specifying these intermediates for heritage projects requiring same-day return-to-service. The technology is compressing the historical trade-off between installation speed and ultimate bond strength, enabling single-crew completion of complex anchoring sequences.
EPA National VOC Emission Standards are eliminating solvent-based stone adhesive formulations from US commercial distribution. Water-dispersible epoxy and polyurethane systems now dominate specification catalogs, with California Air Resources Board thresholds acting as de facto national benchmarks. Exterior cladding applications face the steepest compliance gradient, driving accelerated R&D investment in zero-VOC curing agents.
Building envelope commissioning protocols are elevating adhesive documentation requirements above traditional material specifications. Restoration architects in Boston and Chicago now mandate pull-test certificates and environmental exposure data as standard submittal packages. Digital product passports with embedded performance traceability are displacing paper-based warranty documentation in high-value commercial tenders.
Stone Adhesive Market Segmentation
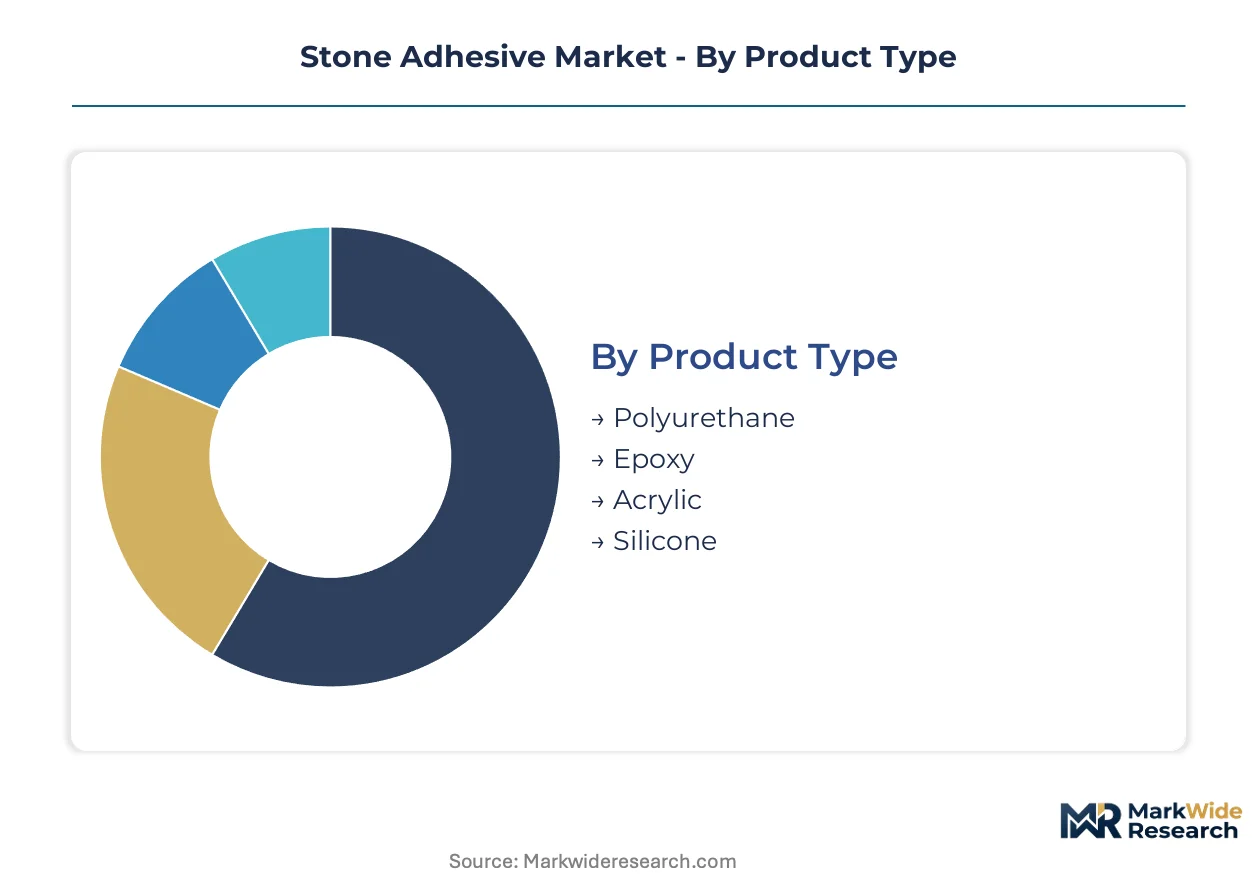
Stone adhesive procurement splits across performance tiers and project workflows, with specification-grade epoxies commanding premium positioning in heritage restoration while commodity polyurethanes capture volume in cladding retrofits. Understanding these segment boundaries helps suppliers align formulation investment with margin architecture.
Product Type:
Upgrade cycles from solvent-based to water-dispersible systems are fragmenting the competitive map, with regulatory deadlines forcing portfolio repositioning across all chemistry platforms.
- Epoxy:Two-part catalytic systems with bisphenol-A derived resins and amine hardeners achieve tensile adhesion strengths exceeding substrate cohesion in granite and marble structural anchoring. Heritage restoration mandates in Germany and Italy specify these formulations for cathedral and civic building renovations where load-bearing documentation is mandatory.
- Polyurethane:Moisture-cured isocyanate-terminated prepolymers with mineral fillers dominate exterior cladding and expansion-joint sealing as building envelope durability standards tighten. REACH Annex XVII restrictions on isocyanate hardeners are accelerating water-dispersible alternatives ahead of compliance deadlines.
- Acrylic:Rapid-cure emulsion systems with ambient temperature application occupy maintenance and repair niches where installation speed offsets lower ultimate strength.
- Silicone:Neutral-cure oxime and alkoxy formulations provide UV-stable flexible bonding for expansion joints and weathersealing in natural stone facades.
Epoxy sits at the top of the volume ranking, with polyurethane climbing the fastest as cladding retrofit intensity accelerates across mature construction markets.
Application:
Project scale and specification authority determine adhesive selection, with commercial envelope work fragmenting procurement across specialized applicators while residential repair concentrates through retail channels.
- Construction:Structural stone anchoring in high-rise facades and commercial interiors demands certified installation crews and pull-test documentation. Boston and Chicago restoration architects now mandate environmental exposure data as standard submittal packages.
- Repairs:Maintenance bonding of delaminated stone elements and crack injection in heritage substrates requires rapid-cure formulations compatible with ambient moisture conditions.
- Artistic Projects:Sculptural assembly and monument restoration in ASI-protected Indian sites creates specification pathways for high-performance systems with documented reversibility.
- Landscaping:Exterior hardscape installation of pavers, retaining walls, and water features drives volume demand for weather-resistant bonding in ground-contact applications.
Construction commands the largest revenue share, with repairs expanding most quickly as facade retrofit cycles compress across mature markets.
End User:
Technical competency and procurement authority vary sharply across user types, with certified contractors capturing specification-grade workflows while DIY channels concentrate commoditized repair volumes.
- Contractors:Specialized masonry and restoration firms in Germany, Italy, and select US metropolitan markets control structural stone bonding projects requiring EN 12004 certification and substrate-specific training protocols.
- DIY Enthusiasts:Residential repair and small-scale landscaping projects drive retail channel volume for pre-mixed acrylic and silicone formulations with simplified application instructions.
- Architects:Specification authority in commercial facade and heritage restoration projects creates pathway control for premium epoxy systems with embedded performance traceability.
- Engineers:Structural engineering review of stone anchoring systems in high-rise applications demands load-bearing calculation support and pull-test certification from adhesive suppliers.
Contractors dominate specification-grade revenue, with architects gaining influence fastest as digital product passports displace paper-based warranty documentation.
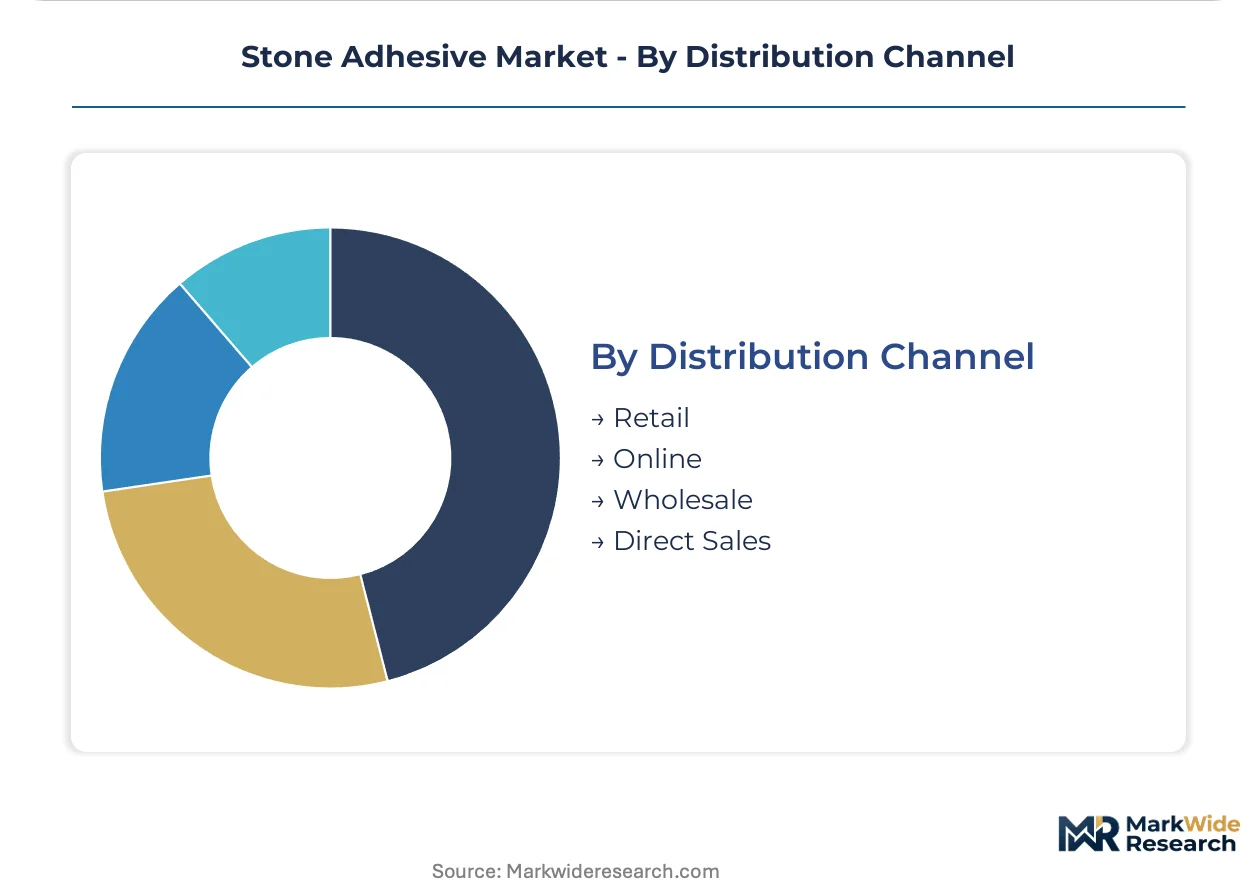
Distribution Channel:
Channel strategy must reconcile technical service intensity with geographic coverage, as specialized applicators bypass traditional tiers while retail expansion captures commoditized volume.
- Retail:Big-box and specialty building material stores serve DIY enthusiasts and small contractors with pre-packaged consumer-grade formulations and limited technical support.
- Online:E-procurement platforms with embedded technical documentation are reducing specification friction for restoration specialists in fragmented European markets.
- Wholesale:Regional distributors maintain inventory positions for mid-tier contractors while facing margin compression from direct-to-applicator digital channels.
- Direct Sales:Manufacturer technical service teams engage restoration architects and certified applicators for heritage projects requiring project-specific formulation customization.
Wholesale retains the deepest penetration, with online gaining share fastest as specialized contractors consolidate procurement through digital platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified restoration masons cluster in Germany, Italy, and the United States, anchoring specification-grade project pipelines for structural stone anchoring systems. Their technical competency constrains geographic expansion of high-performance adhesive workflows.
Germany
Heritage restoration mandates for cathedral and civic building renovations specify epoxy formulations with documented load-bearing performance. REACH Annex XVII restrictions on isocyanate hardeners accelerate water-dispersible adhesive development among formulators. Munich restoration architects specify hybrid epoxy-acrylic systems for same-day return-to-service projects.
Italy
Government-funded preservation programs drive structural stone anchoring tenders for historic monuments. Localized technical service teams maintain project pipeline control across Mediterranean restoration workflows. Milan contractors specify rapid-cure intermediates for complex heritage anchoring sequences.
United States
Commercial envelope durability standards drive replacement cycles for failing mechanical fasteners in high-rise facades. EPA National VOC Emission Standards eliminate solvent-based formulations from commercial distribution. Boston and Chicago restoration architects mandate pull-test certificates and environmental exposure data as standard submittal packages.
China
Evolving GB standards tighten VOC thresholds and reshape formulation requirements for construction adhesives. Cladding retrofit intensity accelerates across mature coastal construction markets. Technical service capabilities remain underdeveloped relative to project pipeline growth in heritage infrastructure segments.
India
ASI-protected monument restoration and new temple construction create specification pathways for high-performance stone adhesives. The Archaeological Survey of India mandates documented reversibility for structural interventions at protected sites. Mumbai and Delhi project pipelines outpace localized technical service infrastructure development.
Stone Adhesive Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated structure where cross-selling construction adhesives meets dedicated stone bonding expertise. The vendor base organizes around three archetypes: diversified chemical conglomerates with construction adhesive portfolios, pure-play construction chemical specialists, and regional formulation houses serving localized restoration markets. Consolidation pressure concentrates among mid-tier formulators lacking long-term supply contracts for petrochemical feedstocks. Competitive moves center on geographic expansion of technical service teams and portfolio diversification into water-dispersible alternatives.
Among Swiss and German diversified chemical groups, Sika AG and Henkel AG & Co. KGaA represent the conglomerate archetype with construction adhesive cross-selling capabilities. Italian pure-play specialists Mapei S.p.A. exemplify the focused technical service model anchoring Mediterranean restoration pipelines. These three companies occupy positions across the premium specification tier where heritage project mandates demand documented performance traceability.
| Leading Market Players |
|---|
| Sika AG |
| Mapei S.p.A. |
| Henkel AG & Co. KGaA |
| Laticrete International, Inc. |
| Tenax S.p.A. |
| Arkema Group |
| BASF SE |
| H.B. Fuller Company |
| ARDEX Group |
| Others |
Supply Flow & Price Mechanics
Heritage restoration mandates across Germany and Italy are compressing procurement timelines for certified epoxy formulations, forcing supply networks to prioritize technical service density over geographic breadth and compressing margins for distributors lacking direct applicator relationships.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity-grade polyurethane adhesives while premium epoxy segments retain structural margin protection through EN 12004 certification requirements. Pricing stratifies across specification-grade, performance-standard, and economy tiers based on load-bearing documentation and silane coupling agent content. Cost compression in water-dispersible formulations is intensifying as REACH compliance deadlines approach, with DIY retail channels exhibiting highest price sensitivity and heritage restoration contractors least responsive to incremental cost shifts.
Supply Chain Analysis
Certified applicator scarcity in Germany, Italy, and the United States constrains formulation plant location decisions despite feedstock proximity advantages. Bisphenol-A derived resins, amine hardeners, and silane coupling agents anchor raw material sourcing to petrochemical corridors in Germany, Belgium, and the US Gulf Coast. Single-source vulnerability concentrates in isocyanate-terminated prepolymer supply from select European producers. Distribution runs through manufacturer technical service teams for specification-grade projects and regional distributors for mid-tier construction volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with EPA National VOC Emission Standards and REACH Annex XVII restrictions successively eliminating solvent-based alternatives and mandating formulation upgrades that command premium positioning.
For Market Incumbents: Acquire certified applicator networks in underserved metropolitan markets to lock in specification-grade project pipelines. Consolidate backward integration into bisphenol-A resin supply to buffer feedstock volatility eroding mid-tier competitor margins. Counter ceramic tile substitution threats by embedding performance documentation into digital product passports that architects now mandate. For New Entrants and Emerging Players: ASI-protected monument restoration contractors in India represent an underserved buyer archetype with rapid project pipeline expansion and limited localized technical service coverage. Capture this white-space through partnerships with European heritage specialists transferring application protocols. Penetrate via direct-to-applicator digital channels bypassing established wholesale tiers that dominate mature markets. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play construction chemical specialists possessing EN 12004 certification infrastructure and Mediterranean project relationships. Long-term viability hinges on water-dispersible platform maturity and bio-based resin substitution timelines. Watch ECHA classification updates on epoxy hardeners as inflection signals for portfolio repositioning toward low-monomer alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Dispersible Platform Development | REACH Annex XVII compliance secures European market access ahead of isocyanate restrictions. |
| Certified Applicator Network Expansion | Technical service density in heritage corridors captures specification authority from restoration architects. |
| Bio-Based Epoxy Resin Investment | Lignin-derived formulations unlock green procurement preferences from public sector clients. |
| Digital Product Passport Deployment | Embedded performance traceability satisfies Boston and Chicago commissioning protocol requirements. |
| Direct-to-Applicator E-Procurement Launch | Bypassing wholesale tiers reduces specification friction for fragmented European restoration specialists. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with restoration architects, certified masonry contractors, formulation R&D directors, and construction adhesive procurement managers with secondary validation from EPA VOC emission filings, ECHA restriction proposals, EN standard documentation, and customs trade data. Bottom-up project pipeline estimates across Germany, Italy, the United States, China, and India triangulated against top-down construction spending forecasts.
Segment-weighted modeling applied chemistry-specific growth assumptions across epoxy, polyurethane, acrylic, and silicone platforms, with application-layer disaggregation for construction, repairs, artistic projects, and landscaping workflows. CAGRs derived from regression analysis of historic specification-grade penetration rates and regulatory compliance-driven substitution curves. Input variables included cladding retrofit cycle intensity, heritage preservation funding allocations, and certified labor availability indices.
Underlying measurement precision varies by segment; specification-grade epoxy volumes in heritage corridors carry tighter precision than fragmented DIY retail estimates. Forecasts assume continued regulatory descent in VOC thresholds and stable petrochemical feedstock availability. Material deviation in ECHA classification timelines, bisphenol-A supply disruptions, or ceramic tile substitution acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Pozzolana Cement Market
Building Materials
Fiber Cement Market
Building Materials
Asia-Pacific Aluminum Door and Window Market
Building Materials
Asia-Pacific Dry-Mix Mortar Market
Building Materials
East Africa Cement Market
Building Materials
Cladding Market
Building Materials
Building and Construction Plastics Market
Building Materials
Bolt (Fastener) Market
Building Materials
Concrete Reinforcing Fiber Market
Building Materials
Low-E Construction Glass Market
Building Materials
China Architectural Coatings Market
Building Materials
United Kingdom White Cement Market
Building Materials
Ductile Iron Pipe Market
Building Materials
Concrete Admixtures Market
Building Materials
Blind Bolts Market
Building Materials
Industrial Concrete Flooring Market