
 Japan Cross Laminated Timber (CLT) Market | 2026-2036
Japan Cross Laminated Timber (CLT) Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Cross Laminated Timber (CLT) Market Intelligence
Hokkaido's sawmill consolidation is decoupling from legacy plywood supply chains as regional softwood processors redirect log flows into engineered timber formats. Sumitomo Forestry Co., Ltd. leverages captive forest holdings and integrated milling assets to dominate CLT feedstock security across northern Japan. Meiken Lamwood Corporation specializes in precision lamination technology for seismic-grade panels, anchoring its position in high-specification commercial projects. Obayashi Corporation competes through design-build contracts that specify in-house engineered wood procurement, tightening contractor control over material sourcing.
Cross Laminated Timber consists of three to seven orthogonally bonded layers of dimensional lumber, pressed under controlled temperature and pressure with structural adhesives meeting JIS A 1460 formaldehyde emission standards, primarily serving as load-bearing wall and floor systems in mid-rise buildings. CLT Panels command the deepest fabrication expertise among product formats, with margin pools concentrating in fire-rated and acoustic-dampened specifications for commercial and educational applications. Residential uptake spreads fastest among custom home builders seeking carbon footprint reductions, though structural lumber retains volume leadership in single-family construction where code familiarity lowers engineering costs.
METI's Green Growth Strategy and PMDA-aligned building material certifications shape product approval pathways, while JIS standards govern dimensional tolerances and adhesive bonding protocols that determine market access. Local prefectural governments in timber-producing regions supplement national frameworks with procurement preferences for domestically sourced engineered wood in public buildings. Stakeholders must track evolving seismic design codes and cross-laminate adhesive chemistry restrictions as these forces determine which production configurations retain compliance advantage.
Market Dynamics
METI's building code amendments for fire-resistant wood structures are compressing engineering review timelines and redirecting mid-rise construction flows toward engineered timber systems, fundamentally altering how Japanese developers specify structural materials.
Growth Catalysts
- Prefectural procurement mandates:Timber-producing prefectures now require domestic engineered wood in public buildings, creating guaranteed offtake for regional CLT mills.
- Seismic design code evolution:Updated performance-based seismic standards recognize CLT's ductility, expanding permissible applications in multi-story construction.
- Carbon accounting integration:Corporate sustainability frameworks now capture embodied carbon in building materials, elevating wood-based systems over steel and concrete alternatives.
Market Restraints
- Adhesive chemistry constraints:JIS A 1460 formaldehyde emission standards limit available bonding agents, constraining panel thickness and fire-rating combinations.
- Hokkaido supply concentration:Domestic softwood feedstock clusters overwhelmingly in northern prefectures, exposing downstream fabricators to regional logistics bottlenecks.
- Structural lumber substitution:Conventional dimension lumber retains code familiarity and lower engineering costs in single-family construction, capping CLT penetration.
Strategic Opportunities
- Educational facility retrofits:Aging school infrastructure replacement programs create demand for rapid-assembly, low-carbon structural systems.
- Hybrid steel-timber systems:Composite construction methods combining CLT floor plates with steel moment frames unlock high-rise applications previously blocked by height restrictions.
- Prefabricated modular integration:Offsite construction specialists are specifying CLT as primary structural elements in factory-built volumetric units.
Industry Challenges
- Fire engineer certification scarcity:Qualified professionals capable of documenting CLT char-layer performance in performance-based designs remain concentrated in Tokyo and Osaka consulting firms.
- Cross-laminate adhesive qualification timelines:New structural adhesive formulations require 18-24 month JIS approval cycles, delaying product line extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Cross Laminated Timber (CLT) Market |
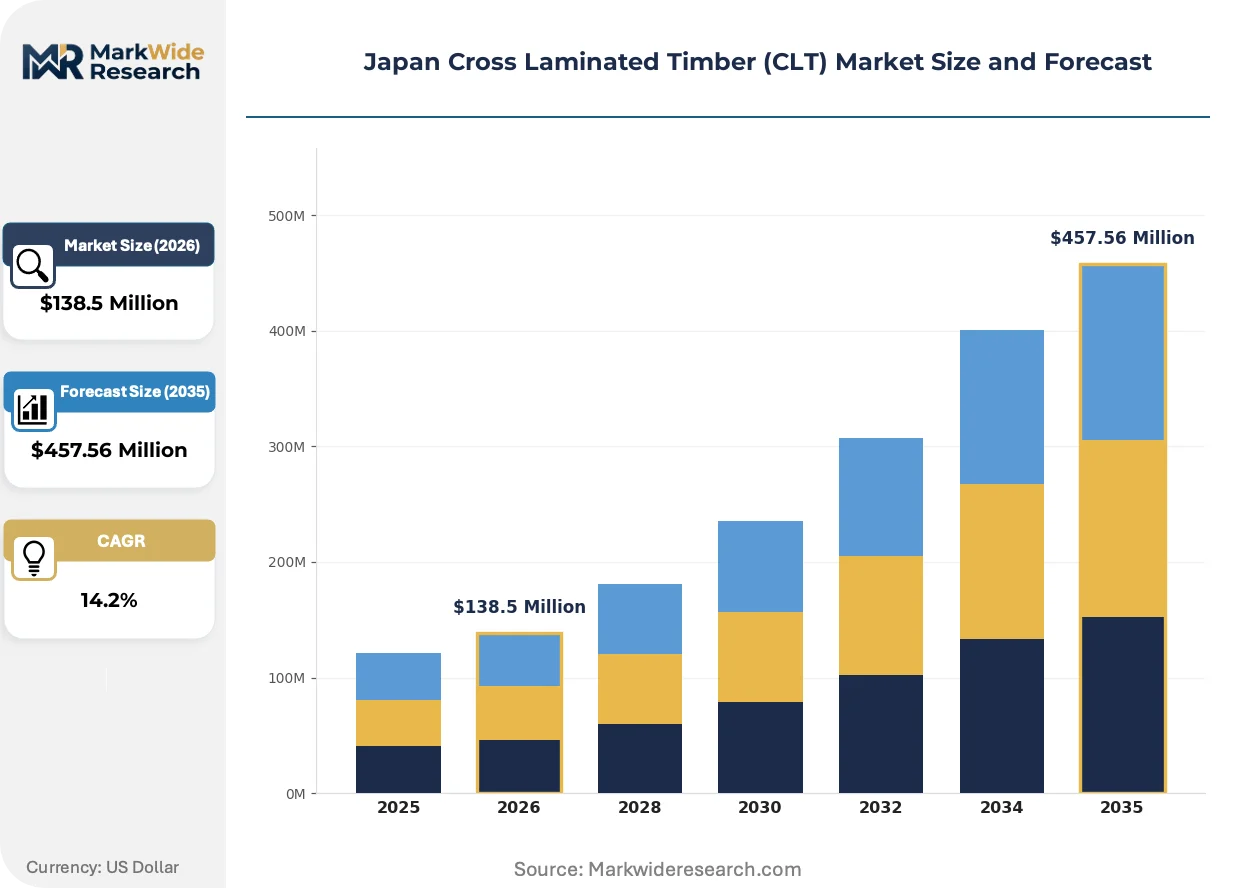
| Market Size in 2026 | $138.5 Million |
| Market Size in 2035 | $457.56 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glulam, CLT Panels, LVL, Structural Lumber Application: Residential, Commercial, Industrial, Educational End User: Builders, Contractors, Architects, Developers Distribution Channel: Direct Sales, Distributors, Retailers, Online |
| Companies Covered | Sumitomo Forestry Co., Ltd., Shinohara Shoten Co. Ltd., Meiken Lamwood Corporation, Itochu Kenzai Corporation, Obayashi Corporation, Middle East Co. Ltd., Takenaka Corporation, Mitsui Fudosan, Yamasa Mokuzai Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Cross Laminated Timber (CLT) Market Strategic Shifts & Innovations
Japanese CLT fabrication is pivoting from commodity panel production toward specification-grade systems, with adhesive chemistry, lamination precision, and fire-performance engineering becoming primary competitive differentiators rather than scale economics alone.
Mass-customized CLT fabrication systems are expanding into mid-rise commercial and institutional verticals. Automated CNC cutting and precision lamination technology from specialized equipment vendors enables project-specific panel dimensions without manual rework. Custom home builders and boutique commercial developers are adopting these capabilities fastest, compressing traditional structural steel procurement cycles by specifying pre-cut timber systems.
METI's Green Growth Strategy implementation is tightening building material certification pathways. PMDA-aligned third-party verification requirements now extend to structural adhesives and fire-retardant treatments, elevating compliance costs for smaller fabricators. Commercial and educational project specifications increasingly mandate certified supply chains, concentrating specification authority among integrated producers with captive testing facilities.
Developer procurement patterns are rotating toward design-build contractors with in-house engineered wood expertise. General contractors capable of self-performing structural engineering and material sourcing are capturing premium margins previously distributed to external timber consultants. This consolidation is most visible in Tohoku and Hokkaido prefectures where regional contractors have invested in CLT-specific fabrication partnerships.
Japan Cross Laminated Timber (CLT) Market Segmentation
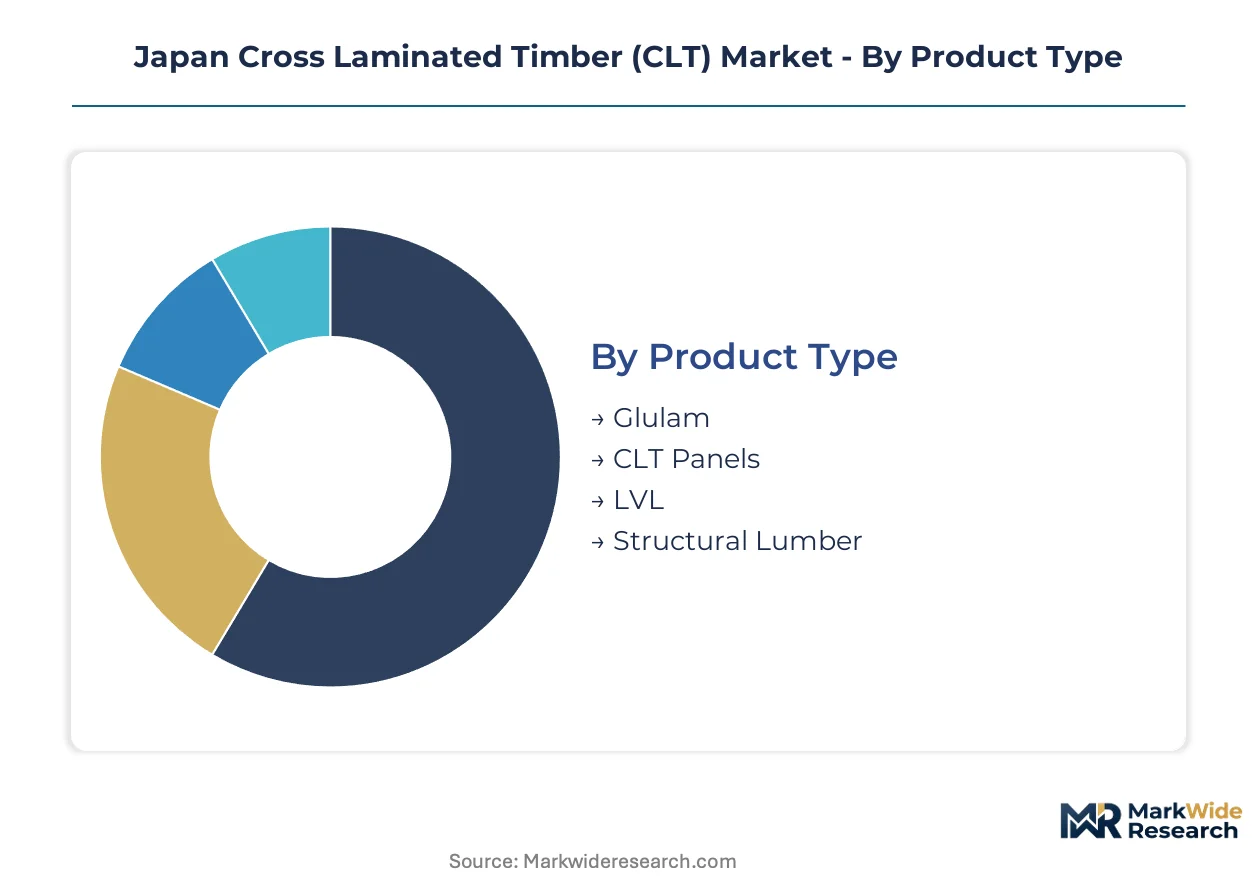
Segmentation in Japan's CLT market reveals how regulatory pathways and procurement hierarchies allocate margin pools unevenly across product formats and customer types. Certification requirements under JIS standards and METI's Green Growth Strategy create tiered market access that favors integrated producers with captive testing capabilities.
Product Type:
JIS A 1460 formaldehyde emission standards and PMDA-aligned structural certifications impose distinct compliance burdens across engineered timber formats, with fire-rated specifications demanding extended approval timelines.
- CLT Panels:Three to seven orthogonally bonded softwood layers pressed under controlled temperature and pressure serve as primary load-bearing wall and floor systems. Demand concentrates in Hokkaido and Tohoku commercial projects where seismic-grade specifications and fire-rated performance command premium positioning.
- Glulam:Longitudinally laminated dimensional lumber bonded with structural adhesives provides beam and column applications with superior span capabilities. Prefectural procurement mandates for public buildings in timber-producing regions accelerate specification of certified glulam systems over conventional steel alternatives.
- LVL:Laminated veneer lumber offers consistent mechanical properties through rotary-peeled veneer layup, serving rim board and header applications in residential mid-rise construction.
- Structural Lumber:Conventional dimension lumber retains code familiarity and lower engineering verification costs in single-family construction across Japan's custom home builder segment.
Structural lumber sits at the top of the volume ranking, with CLT Panels climbing the fastest.
Application:
Cost tier differentiation separates specification-grade commercial systems from commodity residential formats, with engineering intensity and fire-performance requirements determining margin architecture.
- Commercial:Mid-rise office and retail structures specify CLT for carbon accounting compliance and accelerated construction schedules. Hybrid steel-timber moment frame systems unlock height restrictions previously blocking engineered timber in urban cores.
- Educational:Aging school infrastructure replacement programs create concentrated demand for rapid-assembly, low-carbon structural systems with acoustic dampening specifications.
- Residential:Custom home builders seeking embodied carbon reductions drive fastest uptake, though structural lumber retains volume leadership in single-family construction.
- Industrial:Warehouse and logistics facilities specify CLT for roof and floor plates where long spans and fire resistance align with operational requirements.
Residential commands the greatest absolute volume, with Educational applications expanding most quickly under prefectural replacement programs.
End User:
Customer type determines procurement control points, with design-build contractors capturing margin previously distributed to external consultants through in-house engineered wood expertise.
- Developers:Corporate sustainability frameworks now capture embodied carbon in building materials, elevating wood-based system specifications in mid-rise project pipelines.
- Builders:Regional construction firms in Hokkaido and Tohoku have invested in CLT-specific fabrication partnerships, tightening material sourcing control.
- Contractors:General contractors capable of self-performing structural engineering capture premium margins through integrated procurement.
- Architects:Performance-based seismic design documentation requirements concentrate specification authority among firms with fire engineer certification access.
Builders represent the deepest volume base, with Developers gaining share fastest through sustainability-integrated project mandates.
Distribution Channel:
Supply concentration in northern prefectures shapes logistics economics, with direct mill relationships favored for specification-grade volumes and distributor networks handling commodity flows.
- Direct Sales:Integrated producers with captive forest holdings and milling assets in Hokkaido secure feedstock security through mill-direct relationships with large developers.
- Distributors:Regional softwood processors redirecting log flows from legacy plywood into engineered timber formats rely on distributor networks for downstream market access.
- Retailers:Custom home builder segments source dimension lumber and basic CLT formats through established building material retail channels.
- Online:Emerging digital procurement platforms serve boutique commercial developers and remote architectural practices with specification documentation and certified supply chain verification.
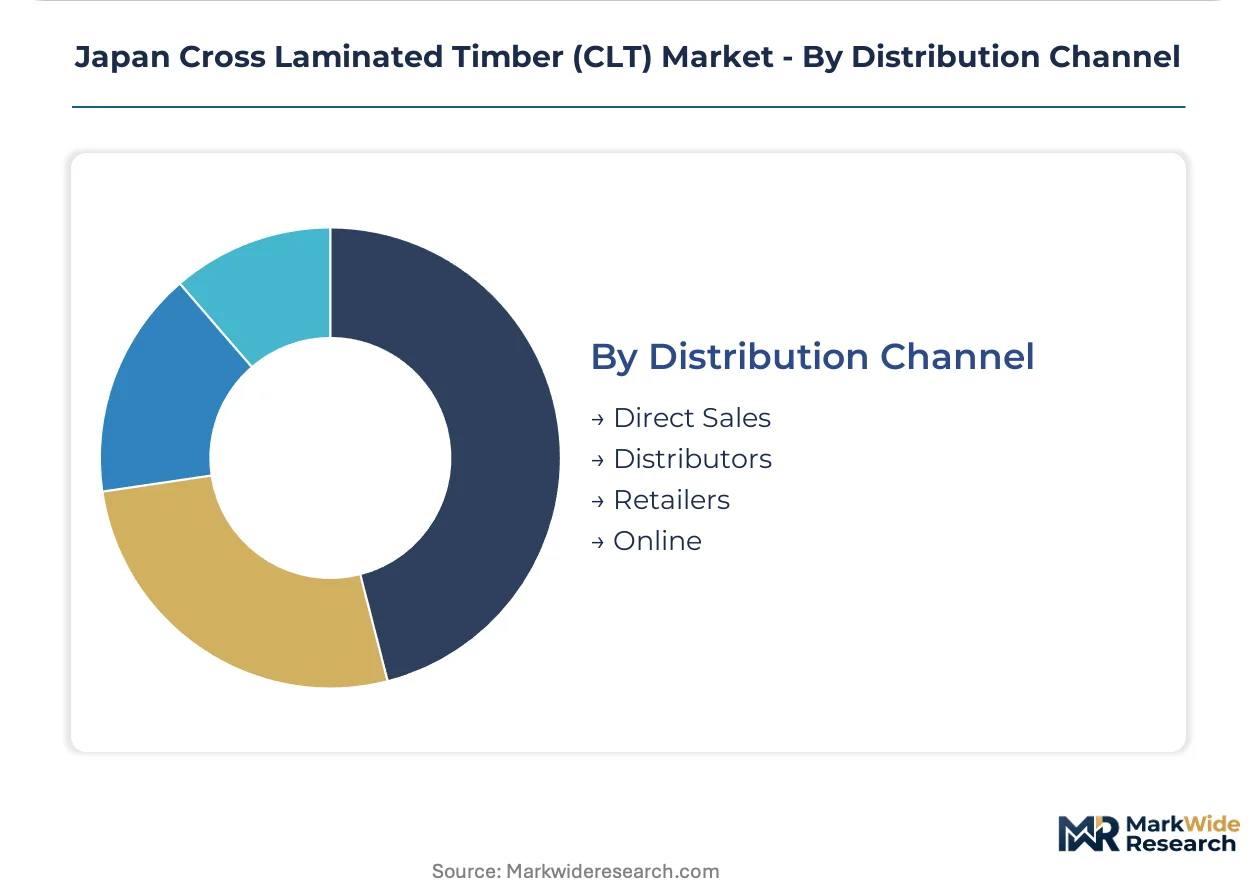
Direct Sales anchors the highest-value transactions, with Distributor channels handling the greatest transaction volume across Japan's fragmented construction base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's engineered timber sector matured a decade earlier than Japan's, yet both markets now converge on hybrid construction systems. Japan's domestic softwood concentration in northern prefectures creates logistics patterns distinct from European distributed feedstock models. METI's regulatory acceleration is compressing development timelines that stretched across multiple election cycles in other advanced economies.
Hokkaido
Regional sawmill consolidation redirects log flows from legacy plywood into CLT formats. METI's timber utilization promotion policies accelerate permit approvals for fire-resistant wood structures. Sapporo and Asahikawa clusters host integrated producers with captive forest holdings and milling assets securing feedstock security.
Tohoku
Post-disaster reconstruction programs and aging school infrastructure replacement drive specification-grade demand. Prefectural procurement mandates require domestic engineered wood in public buildings, creating guaranteed offtake. Sendai and Fukushima fabrication partnerships tighten contractor control over material sourcing.
Kanto/Tokyo
Mid-rise commercial development and corporate sustainability frameworks elevate wood-based systems over steel alternatives. Seismic design code evolution recognizes CLT's ductility, expanding permissible applications. Tokyo and Yokohama consulting firms concentrate fire engineer certification scarcity for performance-based design documentation.
Kansai/Osaka
Design-build contractors with in-house engineered wood expertise capture premium margins through integrated procurement. Carbon accounting integration in building materials selection displaces conventional structural specifications. Osaka and Kyoto clusters favor hybrid steel-timber moment frame systems unlocking height restrictions.
Kyushu
Emerging demand from educational facility retrofits and boutique commercial developers accelerates custom fabrication adoption. JIS A 1460 formaldehyde emission standards constrain adhesive chemistry options for regional processors. Fukuoka fabrication capacity expands through automated CNC cutting technology enabling project-specific panel dimensions.
Japan Cross Laminated Timber (CLT) Market Key Industry Players
Hokkaido-based producers anchor the feedstock-secure tier; Tokyo-Osaka specialists hold the specification-grade and design-build integration positions. The market structures around three distinct layers: integrated forest-to-fabrication operators, precision lamination technology specialists, and general contractors with captive engineered wood procurement. Strategic archetypes include captive resource holders, seismic-grade panel fabricators, and vertically integrated construction groups. Competitive moves concentrate on regional fabrication partnerships and in-house structural engineering capabilities.
Among Hokkaido-based forest holders, Sumitomo Forestry Co., Ltd. exemplifies the captive resource archetype through integrated milling assets. Meiken Lamwood Corporation represents the precision technology tier, specializing in lamination systems for high-specification applications. Obayashi Corporation anchors the contractor-integrated position, competing through design-build contracts that tighten material sourcing control. These three patterns illustrate how feedstock security, fabrication expertise, and procurement integration define competitive positioning.
| Leading Market Players |
|---|
| Sumitomo Forestry Co., Ltd. |
| Shinohara Shoten Co. Ltd. |
| Meiken Lamwood Corporation |
| Itochu Kenzai Corporation |
| Obayashi Corporation |
| Middle East Co. Ltd. |
| Takenaka Corporation |
| Mitsui Fudosan |
| Yamasa Mokuzai Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Design-build contractors with captive engineered wood procurement dominate high-value transactions, anchoring a project-based pricing model where fire-rated specifications and seismic-grade certifications command substantial premiums over commodity panel formats. METI's building code amendments compress engineering review timelines, intensifying competition among integrated producers to capture margin through specification-grade product lines.
Pricing Analysis
Capacity additions in Hokkaido and Tohoku are reshaping price floors as regional sawmill consolidation redirects softwood log flows from legacy plywood into engineered timber formats. Three-tier pricing structure across premium fire-rated, standard structural, and economy residential grades differentiates offerings, with certification level under JIS A 1460 and lamination precision serving as primary value drivers. Cost compression in standard-grade residential panels is intensifying because structural lumber retains code familiarity and lower engineering verification costs in single-family construction. Custom home builders exhibit highest price sensitivity, while commercial developers pursuing carbon accounting compliance demonstrate lowest sensitivity to premium positioning.
Supply Chain Analysis
Freight economics from northern prefectures to urban construction centers constrain downstream fabricators, elevating logistics costs as a decisive factor in mill site selection and procurement control. Domestic softwood feedstock concentrates overwhelmingly in Hokkaido and Tohoku, with adhesive chemistry formulations and precision lamination equipment representing critical imported dependencies. Single-source vulnerability in fire engineer certification access—concentrated in Tokyo and Osaka consulting firms—creates documentation bottlenecks for performance-based seismic designs. Distribution runs through direct mill relationships for specification-grade commercial volumes, while regional distributor networks handle fragmented residential flows across Japan's custom home builder base.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's CLT market operates as a stable compounder, with METI's regulatory acceleration providing predictable demand expansion through timber utilization promotion policies and building code evolution.
For Market Incumbents: Acquire captive forest holdings and integrated milling assets in Hokkaido to secure feedstock security against regional logistics bottlenecks. Invest in in-house fire engineer certification capabilities to capture premium margins from performance-based design documentation, defending against general contractors with captive engineered wood expertise. Prioritize JIS A 1460 adhesive qualification pipelines to accelerate product line extensions ahead of 18-24 month approval cycles. For New Entrants and Emerging Players: Automated CNC cutting and mass-customized fabrication systems offer a technology-first wedge into boutique commercial developers and educational facility retrofit segments. Kyushu presents the most penetrable geography, with emerging demand from school infrastructure replacement programs and limited regional fabrication capacity. Pursue partnerships with prefectural procurement programs requiring domestic engineered wood in public buildings as the primary go-to-market angle. For Investors and Strategic Acquirers: General contractors with design-build integration capabilities are the most active acquirer in this space, consolidating specification authority previously distributed to external timber consultants. The five-to-ten year viability window favors integrated forest-to-fabrication operators with captive testing facilities and PMDA-aligned certification pathways. Monitor cross-laminate adhesive chemistry restrictions as the critical inflection signal determining which production configurations retain compliance advantage.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forest Holdings | Secures softwood feedstock security against Hokkaido supply concentration risks. |
| Fire Engineer Certification Investment | Captures premium margins from Tokyo and Osaka performance-based design documentation scarcity. |
| Prefectural Procurement Partnership | Locks in guaranteed offtake from Tohoku and Hokkaido public building mandates. |
| Automated CNC Fabrication Deployment | Enables mass-customized panel dimensions for boutique commercial developer segments. |
| JIS Adhesive Qualification Pipeline | Accelerates product line extensions ahead of METI's tightening certification pathways. |
Research Approach
Bottom-up residential and commercial construction modeling reconciled against top-down softwood processing capacity tracking forms the analytical core of this study. Primary interviews with CLT fabricators, design-build contractors, structural engineers, and prefectural procurement officers combined with secondary validation from METI timber utilization reports, JIS standards documentation, and building permit databases. Customs records of structural adhesive imports and forestry agency log flow statistics anchored supply-side triangulation.
Historical trendline analysis of engineered timber adoption rates across Japanese prefectures informed projection parameters. Segmentation dimensions modeled include product format, application vertical, end-user procurement control point, and regional supply cluster. CAGRs were derived through regression analysis of permit approval velocities and construction cost indices. Forecast inputs incorporated METI Green Growth Strategy implementation timelines and seismic design code evolution trajectories.
The model holds under stable regulatory enforcement of timber utilization promotion policies; deviation in adhesive chemistry restrictions or fire engineer certification access would shift construction flow specifications. Forecasts reflect documented assumptions about prefectural procurement mandate continuity and softwood supply chain resilience. Stakeholders should weight assumptions against their own operating context and regional feedstock access.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
GRC Conduit Fittings Market
Building & Construction Materials
North America Decks Market
Building & Construction Materials
Fiberglass Light Poles Market
Building & Construction Materials
Door and Window Hardware Market
Building & Construction Materials
Germany Construction Chemicals Market
Building & Construction Materials
Corrugated Steel Panels Market
Building & Construction Materials
South Korea Aluminum Door and Window Market
Building & Construction Materials
Global Sandwich Panels Market
Building & Construction Materials
APAC Commercial Glazing System Market
Building & Construction Materials
Sandwich Panel System Market
Building & Construction Materials
Urethane Concrete Sealer Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
UPVC Doors and Windows Market
Building & Construction Materials
Insulated Concrete Form (ICF) Market
Building & Construction Materials
India Manufacturing Market
Building & Construction Materials
Plastic Fencing Market