
 Brick Adhesive Market | 2026-2036
Brick Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Brick Adhesive Market Analytics
Buyer concentration among large construction companies is restructuring procurement patterns across the brick adhesive value chain. Henkel AG & Co. KGaA leverages its European distribution infrastructure to sustain specification-grade relationships with major contractors. Sika AG anchors its position through specialized mortar systems for high-performance facade bonding. BASF SE competes on formulation chemistry tailored to regional climate variability.
Brick adhesive comprises polymer-modified cementitious or resin-based compounds engineered to bond clay, concrete, or stone masonry units to substrates with tensile adhesion strength typically exceeding 1.0 MPa after cure. The primary commercial purpose centers on structural and aesthetic integration of brick veneer, pavers, and cladding across load-bearing and non-load-bearing assemblies. Thin-set mortar formulations dominate volume due to their versatility across interior and exterior applications, while epoxy adhesives command premium positioning in industrial flooring and heavy-traffic installations where chemical resistance parameters exceed standard requirements. Mastic adhesives occupy the DIY and light-commercial segment where speed of application outweighs extended durability specifications.
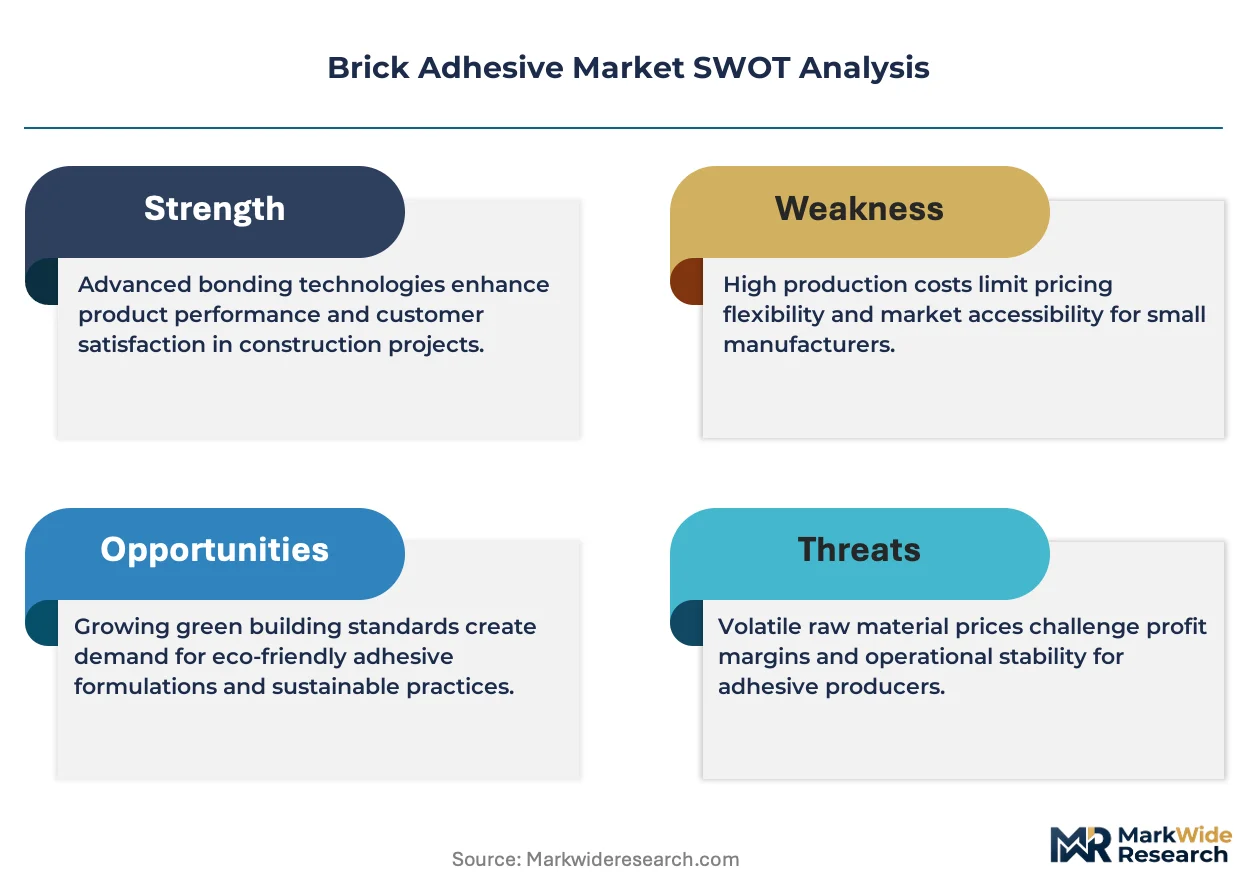
REACH regulations in Europe mandate disclosure of hazardous substance content and restrict specific phthalate plasticizers in construction adhesives, directly elevating R&D expenditure on bio-based alternatives. EPA guidelines in the United States govern volatile organic compound emissions from architectural coatings and adhesives, shaping product availability across state-level markets. ISO 13007 classification standards for ceramic tile adhesives provide the technical baseline that specifiers reference when qualifying brick adhesive products for commercial projects. Stakeholders must monitor evolving low-carbon building codes and embodied carbon disclosure requirements that will increasingly filter adhesive selection criteria in public procurement frameworks.
Market Dynamics
REACH compliance on volatile organic compounds is forcing wholesale reformulation across European supply chains, compressing legacy product margins while elevating bio-based chemistry investments.
Growth Catalysts
- Facade restoration demand:Aging masonry stock across Germany, France, and Italy is generating specification-grade procurement volumes for polymer-modified systems.
- Low-carbon building codes:Embodied carbon disclosure requirements in public procurement frameworks are filtering adhesive selection toward lower-carbon formulations.
- Epoxy technology maturation:Industrial flooring contractors are specifying high-performance resin systems where chemical resistance parameters exceed standard cementitious offerings.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin and polyurethane precursor costs fluctuate with crude oil indices, compressing formulation margins unpredictably.
- Specialized applicator scarcity:Thin-set mortar installation requires certified tradespeople, creating bottleneck capacity in high-volume construction corridors.
- Cement substitution threat:Mechanical anchoring systems and rainscreen cladding are displacing adhesive-dependent veneer in certain commercial specifications.
Strategic Opportunities
- Bio-based polymer R&D:Bio-sourced polyurethane precursors and lignin-modified cementitious binders open premium positioning against petrochemical incumbents.
- DIY channel digitization:E-commerce platforms and mobile-optimized technical documentation are capturing mastic adhesive demand from homeowner renovators.
- Industrial flooring convergence:Hybrid epoxy-cement systems are penetrating food processing and pharmaceutical cleanroom specifications previously served by pure resin chemistry.
Industry Challenges
- ISO 13007 certification timelines:Extended third-party testing protocols delay new product commercialization by 12-18 months.
- Reformulation complexity:Phthalate-free plasticizer alternatives in REACH-compliant systems demand compatibility testing across substrate portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brick Adhesive Market |
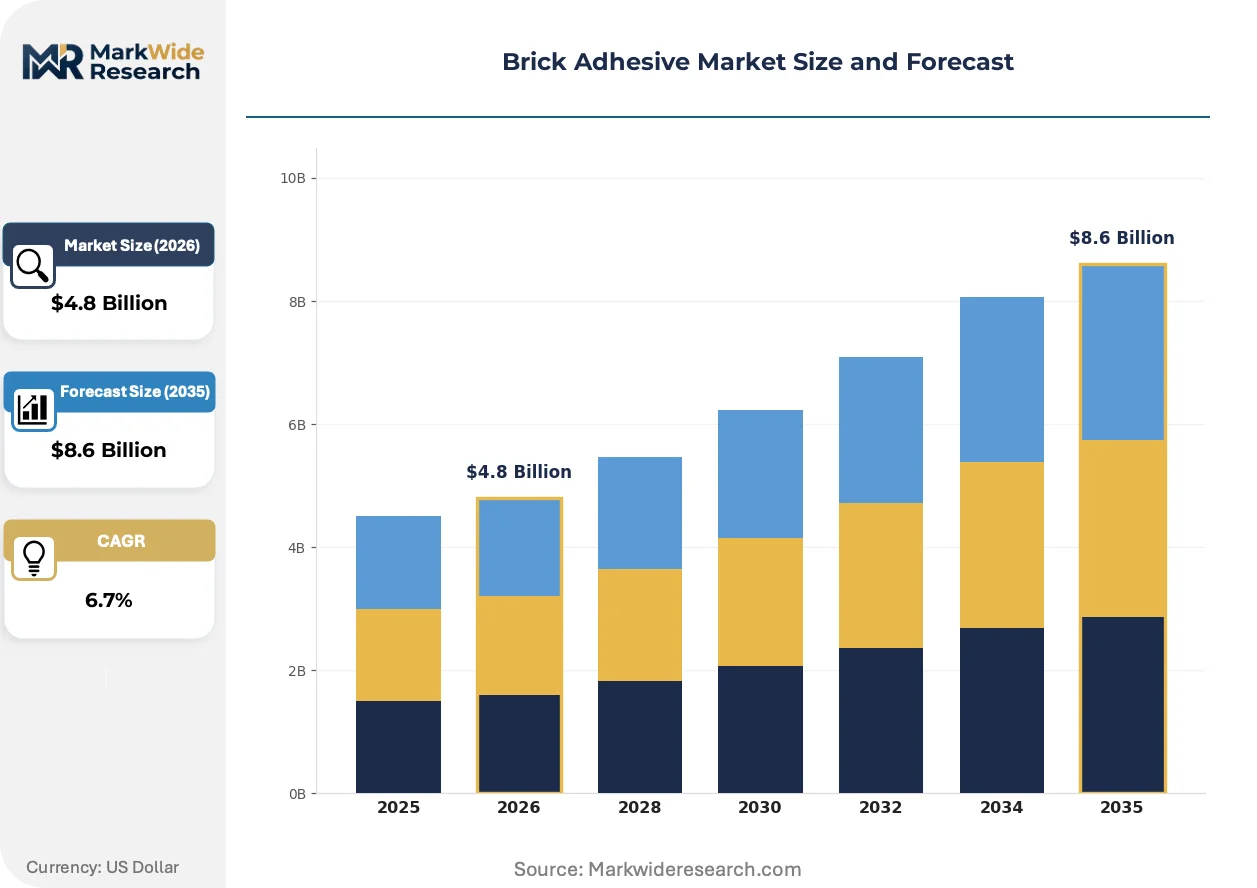
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin-set Mortar, Mastic Adhesives, Epoxy Adhesives, Uncoupling Membrane Application: Interior Installation, Exterior Installation, Facade Bonding, Flooring End User: Contractors, DIY Enthusiasts, Construction Companies, Retailers Distribution Channel: Online Retail, Direct Sales, Specialty Stores, Wholesale |
| Companies Covered | Henkel AG & Co. KGaA, Sika AG, 3M Company, H.B. Fuller Company, Bostik, Dow Chemical Company, Huntsman Corporation, Mapei Corporation, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brick Adhesive Market Evolving Landscape
Formulation chemistry is pivoting toward bio-based feedstocks while digital specification tools compress buyer decision cycles across commercial construction procurement.
Hybrid epoxy-cement systems are overtaking pure epoxy formulations in heavy-traffic industrial flooring. Facility managers in automotive assembly plants specify these systems for intermediate chemical resistance at reduced installed cost. The technology is overtaking premium resin-only positioning across mid-tier performance specifications.
REACH Annex XVII restrictions on phthalate plasticizers are eliminating legacy formulation pathways. ECHA substance evaluation timelines are accelerating R&D spend on bio-sourced alternatives. German and French specification bodies are updating approved product lists to exclude non-compliant chemistry.
Specification-grade buyers now demand embodied carbon data alongside technical performance sheets. Large contractors in Italy and the Netherlands are bundling adhesive selection into whole-building LCA submissions. Digital product passports are displacing static technical datasheets in public tender documentation.
Brick Adhesive Market Segmentation
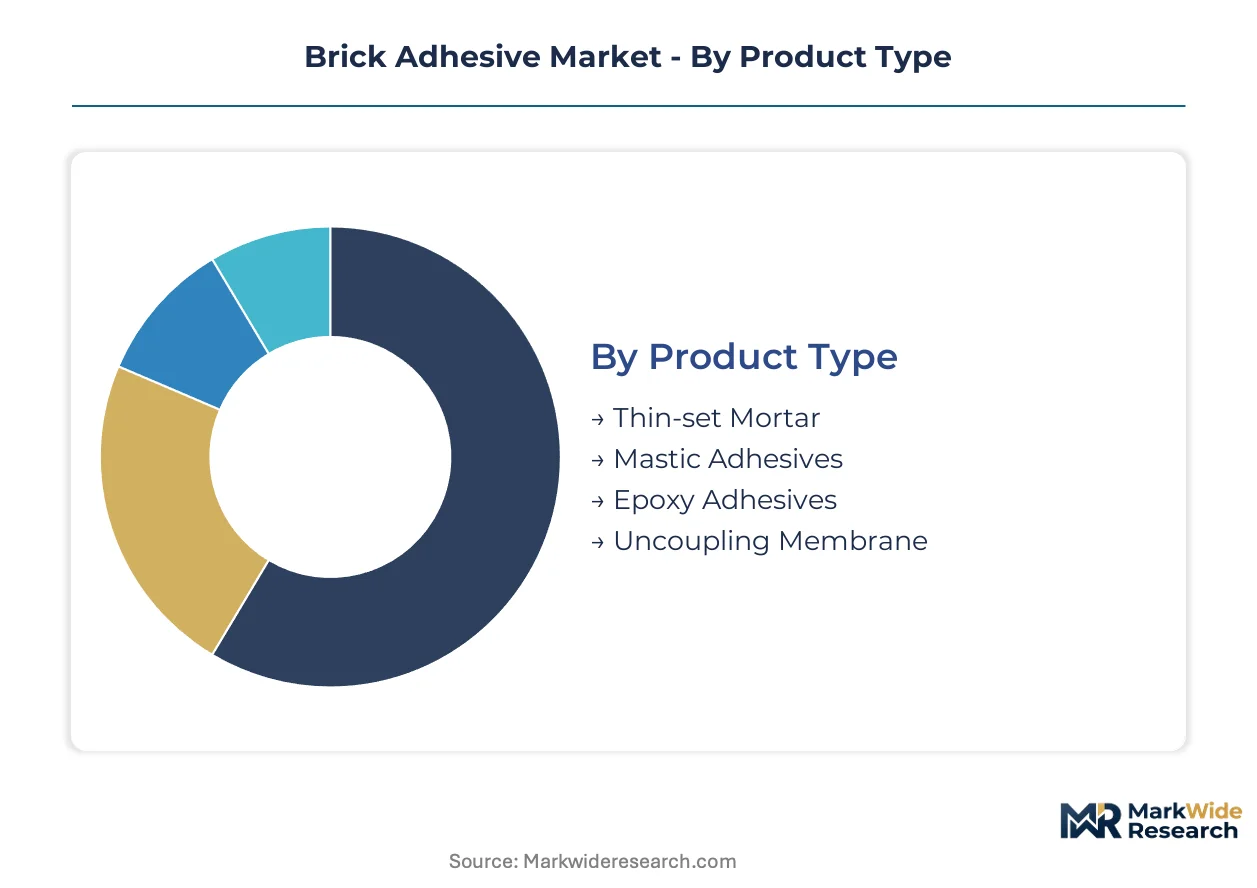
Segmentation in the brick adhesive market reveals how formulation chemistry, installation environment, and buyer procurement power reshape competitive positioning. Distinct technical requirements across product categories create divergent margin structures and channel strategies that suppliers must navigate simultaneously.
Product Type:
Supply concentration in thin-set mortar manufacturing dominates volume production, while epoxy adhesive specialists command premium positioning through proprietary resin chemistry.
- Thin-set Mortar:Polymer-modified cementitious compounds incorporating Portland cement, graded sand, and synthetic latex polymers deliver tensile adhesion exceeding 1.0 MPa after cure. Demand concentrates in Germany, France, and Italy where facade restoration contractors specify polymer-modified systems for aging masonry stock under REACH-compliant procurement frameworks.
- Mastic Adhesives:Pre-mixed organic formulations based on acrylic or urethane resins enable rapid application without water mixing. DIY renovators in suburban markets drive volume through home improvement retailers, prioritizing speed over extended durability specifications in light-commercial and residential interior applications.
- Epoxy Adhesives:Two-component thermosetting resin systems provide chemical resistance parameters exceeding standard cementitious offerings. Industrial flooring contractors in automotive assembly plants specify these for heavy-traffic installations.
- Uncoupling Membrane:Polypropylene composite sheets with integrated adhesive layers isolate substrate movement from finished surfaces. Specialized flooring distributors stock these for high-value commercial tile projects.
Today's leader: Thin-set Mortar. Tomorrow's challenger: Epoxy Adhesives.
Application:
Cost tier differentiation separates specification-grade facade bonding from economy-focused interior installations, with exterior applications commanding formulation premiums for weather resistance.
- Interior Installation:Standard-grade thin-set and mastic formulations serve residential and light-commercial wall and floor applications where climate exposure remains minimal.
- Exterior Installation:Freeze-thaw resistant polymer-modified mortars with enhanced bond strength address cladding and veneer applications across variable European climates.
- Facade Bonding:Structural adhesive systems engineered for clay, concrete, and stone masonry units integrate aesthetic and load-bearing functions. German, French, and Italian specification bodies concentrate procurement-grade volumes here, with embodied carbon disclosure requirements now filtering adhesive selection in public tender documentation.
- Flooring:High-compressive-strength formulations support paver and tile installations in commercial and industrial environments. Hybrid epoxy-cement systems are gaining share fastest in food processing and pharmaceutical cleanroom specifications previously served by pure resin chemistry.
Facade bonding commands specification premiums; flooring applications are expanding most quickly through hybrid technology adoption.
End User:
Customer type fragmentation splits the market between certified-trade dependency and homeowner convenience purchasing, with construction companies consolidating procurement leverage.
- Contractors:Certified tradespeople execute thin-set mortar installation requiring technical training, creating bottleneck capacity in high-volume construction corridors across Germany and Italy.
- DIY Enthusiasts:Homeowner renovators purchase mastic adhesives through e-commerce platforms and mobile-optimized technical documentation, capturing convenience-driven demand.
- Construction Companies:Large contractors bundle adhesive selection into whole-building LCA submissions, demanding embodied carbon data alongside technical performance sheets in Italy and the Netherlands.
- Retailers:Home improvement chains and specialty distributors stock multiple product tiers, serving as gatekeepers between manufacturers and fragmented end-user bases.
Construction companies consolidate procurement power; DIY enthusiasts are gaining channel influence through digital platform migration.
Distribution Channel:
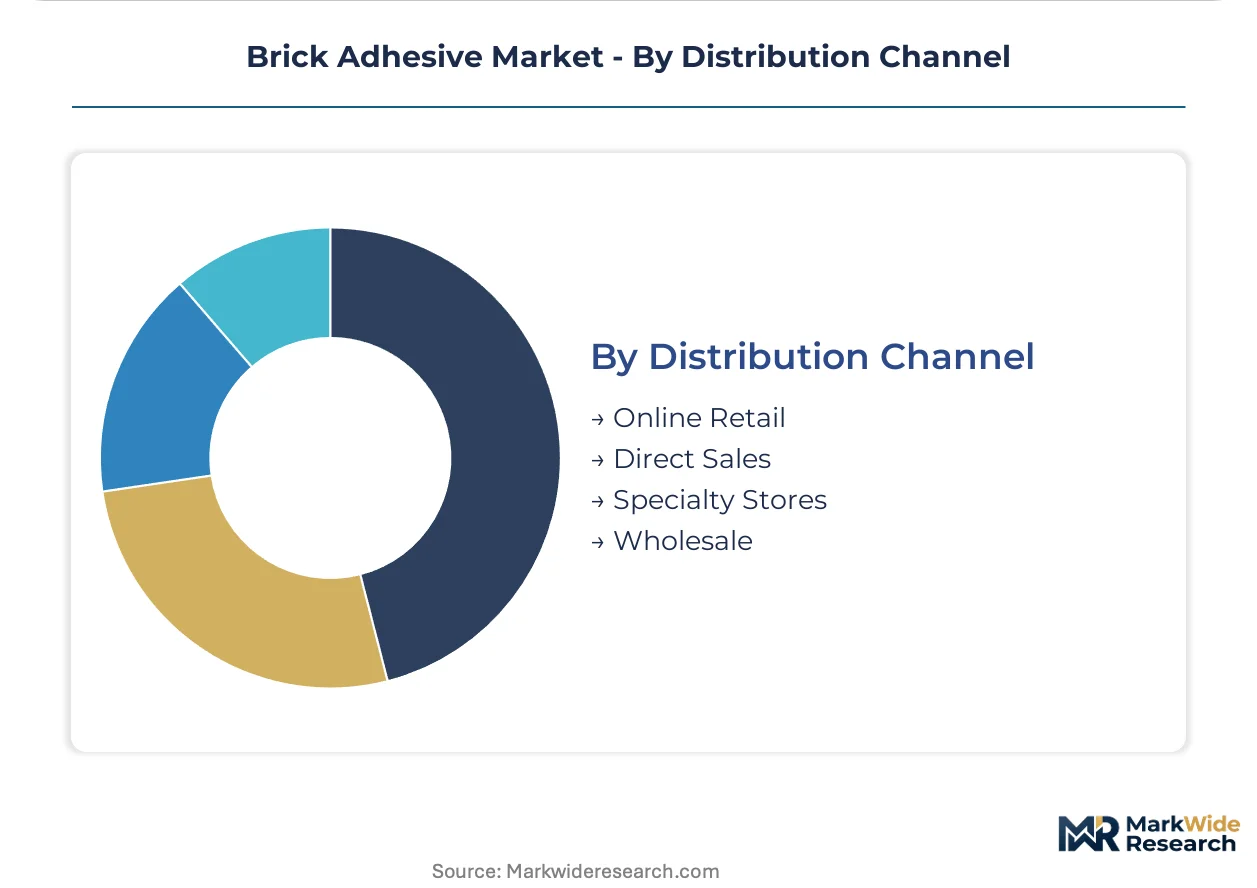
Volume concentration in wholesale and direct sales channels serves professional contractors, while online retail captures fragmented homeowner demand with lower service intensity.
- Online Retail:E-commerce platforms deliver mastic adhesives and technical documentation to DIY renovators, compressing traditional distributor margins.
- Direct Sales:Manufacturers maintain specification-grade relationships with major contractors through dedicated technical service teams and project-specific formulation support.
- Specialty Stores:Tile and flooring distributors stock certified products with ISO 13007 documentation, serving professional installers requiring immediate material availability.
- Wholesale:Construction supply houses move bulk thin-set mortar volumes to contractor fleets, leveraging established logistics networks across regional construction corridors.
Wholesale anchors professional volume; online retail shows the steepest expansion trajectory in homeowner segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates specification-grade procurement volumes while the United States drives hybrid epoxy-cement technology adoption for industrial flooring. France and Italy anchor facade restoration demand across aging masonry corridors. Construction activity in the Netherlands accelerates embodied carbon disclosure requirements for adhesive selection.
Germany
Facade restoration contractors across North Rhine-Westphalia and Bavaria specify polymer-modified thin-set mortar for aging masonry stock. REACH Annex XVII restrictions on phthalate plasticizers eliminate legacy formulations from approved product lists. The Frankfurt-Rhine-Main corridor concentrates technical service teams serving major construction company procurement offices.
United States
Industrial flooring contractors in automotive assembly plants specify hybrid epoxy-cement systems for intermediate chemical resistance. EPA guidelines on volatile organic compound emissions shape product availability across state-level markets. The Detroit metro cluster anchors heavy-traffic installation demand from manufacturing facility managers.
France
Specification bodies in Île-de-France update approved product lists to exclude non-compliant chemistry under ECHA substance evaluation timelines. Low-carbon building codes filter adhesive selection in public procurement frameworks. The Lyon-Saint-Étienne corridor concentrates facade bonding specialists serving heritage restoration projects.
Italy
Large contractors in Lombardy bundle adhesive selection into whole-building LCA submissions demanding embodied carbon data. Aging masonry stock across northern industrial cities generates specification-grade procurement volumes. The Milan metro area anchors certified tradespeople capacity for thin-set mortar installation.
Netherlands
Public tender documentation in Randstad cities mandates digital product passports displacing static technical datasheets. Embodied carbon disclosure requirements filter adhesive selection in government-funded construction. The Amsterdam-Rotterdam corridor concentrates e-commerce platform distribution capturing DIY renovator demand.
Brick Adhesive Market Competitive Landscape
German producers anchor one tier; Swiss specialists hold premium positioning through proprietary mortar systems. The vendor base splits between diversified chemical conglomerates with European distribution infrastructure and focused adhesive formulators serving regional climate variability. Three archetypes dominate: specification-grade relationship builders, industrial flooring resin specialists, and bio-based chemistry innovators. Capacity expansion and portfolio diversification toward lower-carbon formulations represent the dominant competitive vectors.
Among Germany-based chemical conglomerates, Henkel AG & Co. KGaA and BASF SE occupy positions spanning specification-grade procurement channels and formulation chemistry development. Sika AG, a Swiss AG-structured specialist, exemplifies the focused mortar system archetype. These three entities represent the competitive core around which mid-cap regional formulators and bio-based startups organize their market entry strategies.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Sika AG |
| 3M Company |
| H.B. Fuller Company |
| Bostik |
| Dow Chemical Company |
| Huntsman Corporation |
| Mapei Corporation |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between ISO 13007-compliant specification products and uncertified commodity alternatives manifests in parallel supply chain configurations. Premium formulations route through dedicated technical service teams serving major contractors, while economy-grade thin-set mortar flows through wholesale construction supply houses competing on volume throughput.
Pricing Analysis
Capacity additions in Germany and France are reshaping price floors for polymer-modified thin-set mortar as regional producers expand specification-grade output. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant systems with phthalate-free plasticizers from legacy formulations facing margin compression. Pricing pressure stems from petrochemical feedstock volatility in epoxy resin precursors, with DIY enthusiasts exhibiting highest price sensitivity and facade restoration contractors demonstrating lowest sensitivity due to performance guarantees.
Supply Chain Analysis
Certified applicator scarcity in the Milan and Frankfurt-Rhine-Main corridors constrains formulation plant staffing and technical service team deployment across German and Italian manufacturing hubs. Raw material sourcing draws from Saudi Arabian petrochemical complexes for epoxy precursors, Norwegian lignin suppliers for bio-based binder development, and domestic European sources for Portland cement. Single-source vulnerability concentrates in specialized phthalate-free plasticizer supply from Swiss chemical specialists. Distribution runs through construction supply houses and specialty flooring distributors serving contractor fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The brick adhesive market functions as a stable compounder anchored by sustained facade restoration demand across aging European masonry stock. Infrastructure maintenance cycles and regulatory compliance mandates generate predictable replacement volumes.
For Market Incumbents: Anchor specification-grade relationships through backward integration into bio-based polymer precursor production, securing supply certainty for REACH-compliant formulations. Invest in ISO 13007 certification capacity to compress 12-18 month commercialization timelines threatening product pipeline velocity. Cement substitution from mechanical anchoring systems and rainscreen cladding demands accelerated R&D on hybrid epoxy-cement systems preserving adhesive-dependent specifications. For New Entrants and Emerging Players: The mid-tier price-point gap between Sika AG-level premium positioning and commodity thin-set mortar creates white-space opportunity for regional bio-based specialists. Target Netherlands and Italian public procurement frameworks where embodied carbon disclosure requirements filter adhesive selection toward lower-carbon formulations underserved by petrochemical incumbents. Deploy e-commerce platforms with mobile-optimized technical documentation to capture DIY renovator demand migrating from traditional distributor channels. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap regional formulators lack capital to fund REACH-compliant reformulation and bio-based chemistry R&D simultaneously. Five-to-ten year viability favors acquisition targets possessing existing ISO 13007 certification infrastructure and established relationships with German or French specification bodies. Watch ECHA substance evaluation timelines accelerating R&D spend on bio-sourced alternatives as inflection indicator for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Precursors | Captive supply of lignin-modified binders secures REACH-compliant formulation pathways against petrochemical volatility. |
| ISO 13007 Certification Expansion | Compressed third-party testing timelines accelerate new product commercialization for specification-grade procurement channels. |
| Hybrid Epoxy-Cement System Development | Food processing and pharmaceutical cleanroom specifications previously served by pure resin chemistry open mid-tier penetration. |
| Digital Product Passport Deployment | Netherlands and Italy public tender documentation mandates displace static technical datasheets in contractor procurement. |
| DIY Channel E-Commerce Buildout | Mobile-optimized technical documentation captures homeowner renovator demand compressing traditional distributor margins. |
Research Methodology
Direct dialogue with facade restoration contractors, industrial flooring specialists, construction company procurement directors, and ECHA regulatory affairs leads grounded qualitative assessment in operational realities. Secondary validation drew from REACH Annex XVII substance restriction databases, ISO 13007 certification registries, European construction trade association reports, and customs data tracking epoxy resin precursor imports. Bottom-up project pipeline analysis across German, French, and Italian restoration corridors triangulated against top-down formulation chemistry production estimates.
Bottom-up volume modeling segmented demand across thin-set mortar, mastic adhesive, epoxy adhesive, and uncoupling membrane categories, further disaggregated by interior installation, exterior installation, facade bonding, and flooring applications. End-user splits among contractors, DIY enthusiasts, construction companies, and retailers captured procurement power concentration effects. CAGRs derived from elasticity-adjusted demand curves incorporating petrochemical feedstock price indices and certified tradespeople capacity constraints across the analysis window.
Caveats apply where ECHA substance evaluation timeline acceleration, sudden petrochemical feedstock price dislocation, or cement substitution technology breakthroughs could materially shift the outlook. Forecasts reflect assumptions about regulatory compliance cost pass-through rates and bio-based formulation performance parity timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
India Dry Mix Mortar Market
Building Materials
Acoustic Damping Tiles Market
Building Materials
Refractory Cement Market
Building Materials
Latin America Aluminum Door and Window Market
Building Materials
Stone Adhesive Market
Building Materials
Basalt Rock Market
Building Materials
Steel Slag Market
Building Materials
Concrete Blocks and Bricks Market
Building Materials
Granite Market
Building Materials
Exterior Doors Market
Building Materials
Earthen Plasters Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market
Building Materials
Global Corrugated Steel Sheets Market
Building Materials
Global Glass Fiber Reinforced Concrete Market