
 Acoustic Damping Tiles Market | 2026-2036
Acoustic Damping Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Acoustic Damping Tiles Market Analysis
Software-defined acoustic tuning is decoupling hardware sales from static performance claims, forcing manufacturers to bundle digital calibration services with physical tile installations. Saint-Gobain leverages its building materials distribution network to anchor premium mineral fiber tile sales across European commercial projects. Rockwool International sustains R&D intensity in fire-rated acoustic solutions that differentiate its portfolio from commodity foam competitors. Knauf Insulation competes on manufacturing scale, operating some of the largest mineral wool production lines serving continental European contractors.
Acoustic damping tiles are engineered panels designed to absorb sound energy through porous or resonant structures, typically rated by Noise Reduction Coefficient values ranging from 0.35 to 0.95 depending on material density and surface geometry. Their primary commercial purpose is controlling reverberation in built environments where speech intelligibility, worker concentration, or audio fidelity matters. Mineral fiber tiles occupy the highest margin pool in commercial suspended ceiling applications where fire safety ratings and acoustic performance converge. Foam tiles represent the fastest-growing category in residential and entertainment venues where lighter weight and lower installed cost outweigh durability concerns. Vinyl tiles dominate industrial facilities requiring wash-down resistance and chemical compatibility beyond standard porous absorbers.
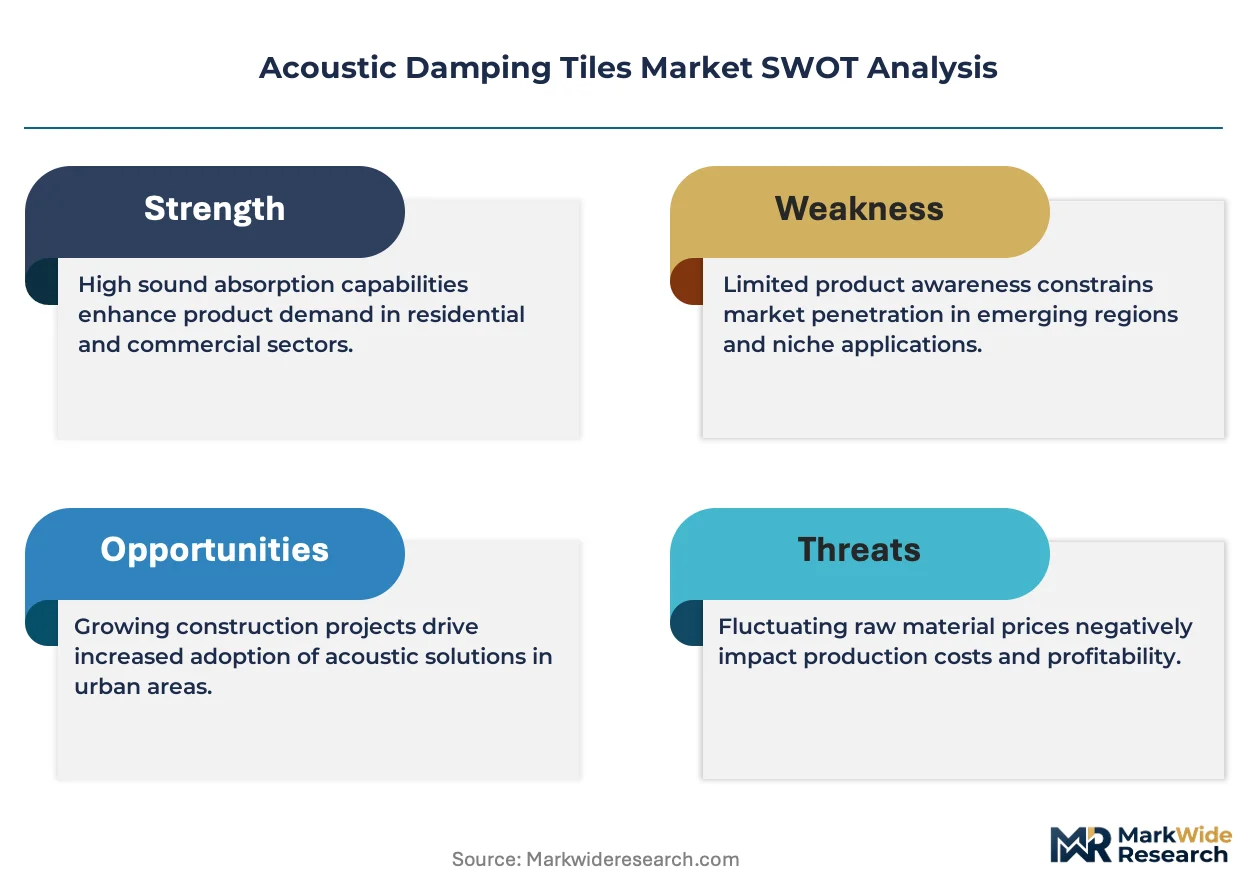
The EPA regulates volatile organic compound emissions from building materials under indoor air quality guidelines, while OSHA enforces permissible noise exposure limits that drive industrial facility retrofit demand. REACH compliance in Europe restricts certain flame retardants and binders used in foam tile manufacturing, redirecting formulation investment toward mineral fiber alternatives. Stakeholders must monitor evolving green building certification schemes and their acoustic performance credits, as these standards increasingly determine specification authority in competitive bidding environments.
Market Dynamics
Software-defined acoustic tuning is decoupling hardware sales from static performance claims, forcing manufacturers to bundle digital calibration services with physical tile installations. This structural shift reconfigures margin capture toward recurring service revenue and away from one-time product sales.
Growth Catalysts
- EU Green Deal building performance standards:Commercial office developers in Germany and France specify higher-grade mineral fiber tiles to meet mandatory energy efficiency and indoor environmental quality benchmarks.
- Workplace acoustic comfort prioritization:Facility managers across the United States, Germany, and Japan drive suspended ceiling retrofits to address employee productivity and retention concerns.
- Fire-rated acoustic solution R&D:Mineral wool manufacturers advance non-combustible formulations that satisfy stricter building code enforcement in high-occupancy structures.
Market Restraints
- Mineral fiber raw material volatility:Slag wool and basalt supply concentration in Eastern European smelter operations exposes producers to energy cost spikes and logistics disruption.
- REACH compliance friction:European chemical restrictions on legacy flame retardants and formaldehyde-based binders force foam tile reformulation, extending product development cycles.
- Lightweight foam substitution:Lower-density polyurethane and melamine alternatives capture residential and entertainment venue demand where durability requirements remain minimal.
Strategic Opportunities
- Underpenetrated healthcare acoustics:Hospital patient room and corridor retrofits in Japan present untapped demand for infection-control-compatible sound-absorbing surfaces.
- Industrial wash-down specification:Vinyl-faced tile penetration into food processing and pharmaceutical manufacturing facilities expands addressable market beyond standard porous absorbers.
- Digital-physical bundling:Acoustic sensor integration with ceiling tiles enables real-time reverberation monitoring, creating subscription revenue streams for building automation integrators.
Industry Challenges
- Acoustic engineer talent scarcity:Specialized expertise in room acoustics modeling and software-defined tuning configuration remains concentrated among legacy consulting firms, constraining installer scaling.
- Multi-certification timeline compression:Simultaneous pursuit of LEED, WELL, and national fire safety ratings extends specification-to-installation intervals, straining working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acoustic Damping Tiles Market |
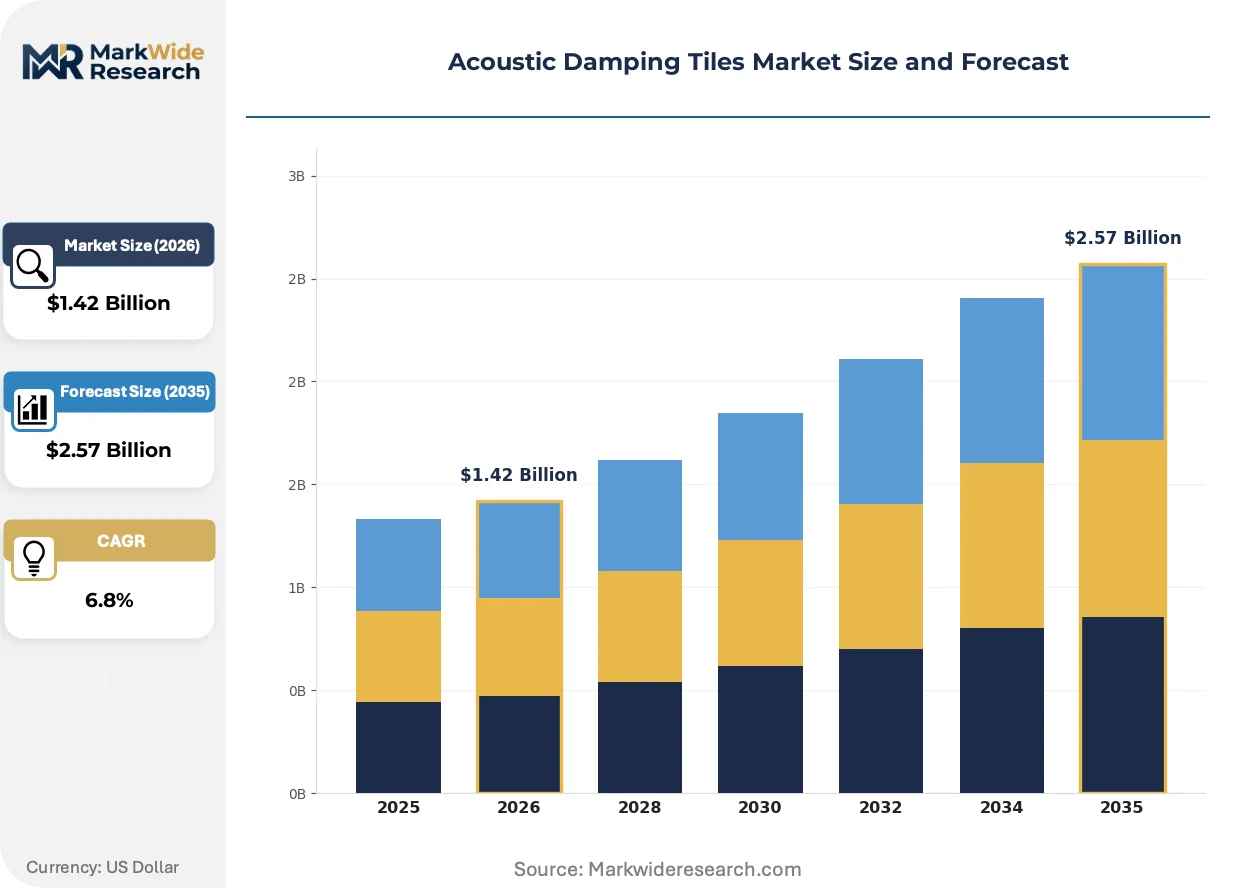
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Tiles, Vinyl Tiles, Mineral Fiber Tiles, Wood Tiles Application: Commercial Spaces, Residential Areas, Industrial Facilities, Entertainment Venues End User: Architects, Interior Designers, Contractors, Facility Managers Installation Type: Suspended Ceiling, Wall-Mounted, Floor-Mounted, Integrated Systems |
| Companies Covered | 3M, Autex Industries, Rockwool International, Auralex Acoustics, Armstrong World Industries, USG Corporation, Acoustical Surfaces, Saint-Gobain, Knauf Insulation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acoustic Damping Tiles Market Emerging Trajectories
Material science advances and embedded sensor integration are redefining how acoustic performance is specified, measured, and monetized across commercial construction. Three convergent developments are compressing traditional hardware margins while opening service-based revenue architectures.
Microperforated metal tiles paired with tuned backing cavities are overtaking conventional mineral fiber in premium conference room and broadcast studio applications. Corporate AV integrators specify these systems for predictable broadband absorption without particulate shedding concerns. The shift is compressing commodity ceiling tile margins while elevating engineered system pricing power.
REACH restrictions on halogenated flame retardants are redirecting European foam tile formulation toward mineral fiber alternatives and bio-based binders. Manufacturers face eighteen-month requalification timelines for modified chemistries under ECHA notification requirements. German and French specification authorities now prioritize pre-certified low-emission products in public procurement frameworks.
Building owners increasingly demand post-installation acoustic verification rather than manufacturer NRC claims alone. Third-party commissioning agents capture specification influence previously held by distributor sales teams. This behavior shift concentrates most visibly in United States Class A office developments pursuing WELL Building Standard certification.
Acoustic Damping Tiles Market Segmentation
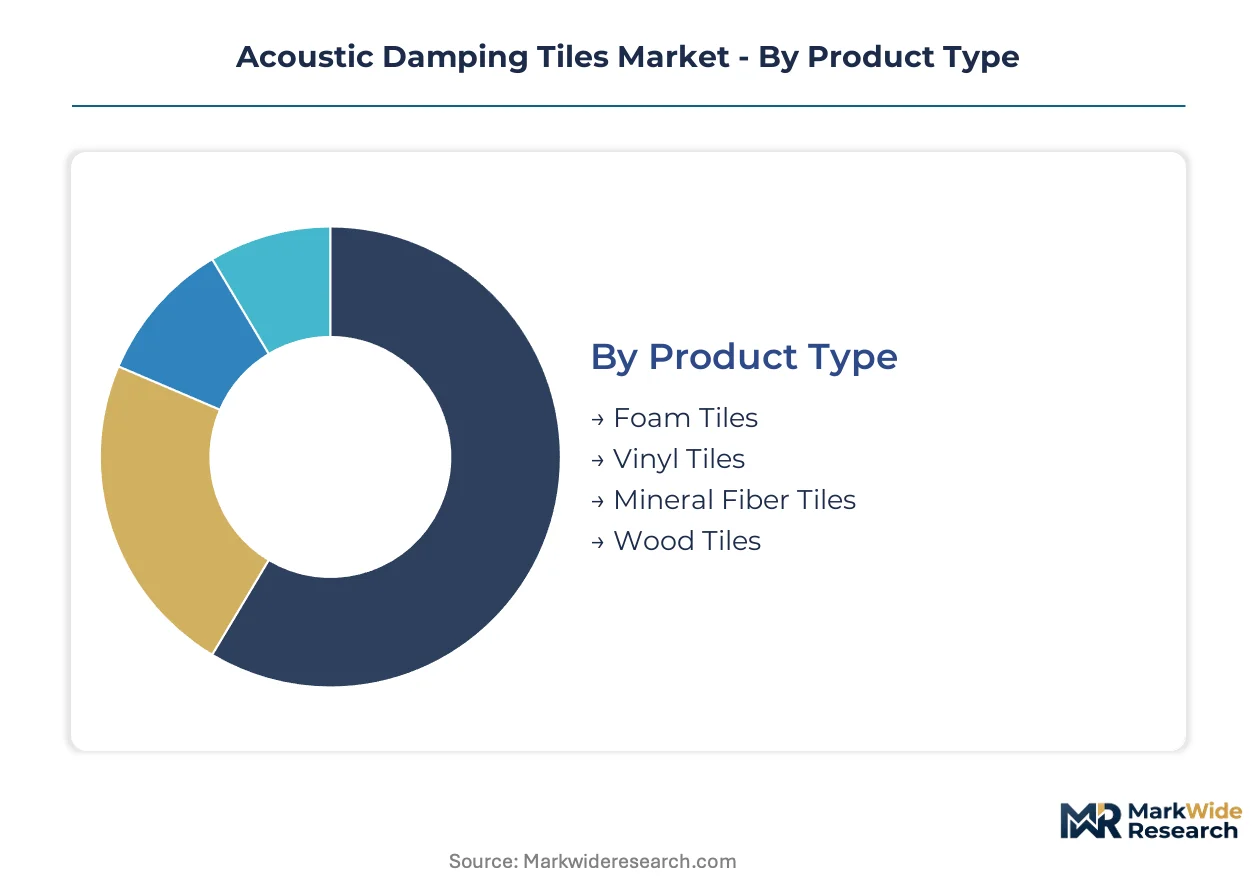
Specification authority in acoustic damping tiles fragments across four distinct decision-making hierarchies. Product chemistry determines fire safety compliance ceilings. Installation geometry constrains retrofit feasibility. End-user professional identity shapes whether performance claims or installed cost carries final weight.
Product Type:
Material density and combustion behavior separate premium specification from commodity substitution in commercial bidding.
- Mineral Fiber Tiles:Non-combustible slag wool and basalt formulations achieve NRC ratings of 0.85–0.95 while satisfying EU Green Deal fire safety mandates. German and French commercial office developers specify these for suspended ceiling retrofits where regulatory compliance eliminates foam alternatives.
- Foam Tiles:Open-cell polyurethane and melamine structures deliver NRC 0.70–0.85 at 60% lower installed weight than mineral fiber. Residential and entertainment venue demand in Japan and the United States favors these where durability requirements remain minimal and ceiling load capacity restricts heavier materials.
- Vinyl Tiles:Wash-down resistant PVC facings protect porous cores in pharmaceutical manufacturing and food processing environments requiring chemical compatibility.
- Wood Tiles:Microperforated hardwood veneers over tuned cavities serve premium conference rooms and broadcast studios where aesthetic integration overrides cost sensitivity.
Volume sits with mineral fiber; growth tilts toward foam.
Application:
Acoustic performance requirements and retrofit economics diverge sharply across built environment categories.
- Commercial Spaces:Class A office developments in the United States pursue WELL Building Standard certification requiring post-installation reverberation verification. Facility managers specify integrated ceiling systems combining absorption with embedded sensors for real-time monitoring.
- Industrial Facilities:OSHA noise exposure limits mandate retrofitting of manufacturing floors where machinery-generated sound exceeds 85 decibels. Vinyl-faced tiles penetrate food processing plants requiring daily wash-down protocols incompatible with standard porous absorbers.
- Residential Areas:Home theater and open-plan living renovations drive demand for lightweight foam panels with adhesive mounting systems avoiding structural ceiling modifications.
- Entertainment Venues:Concert halls and recording studios prioritize predictable broadband absorption through microperforated metal and wood systems over commodity mineral fiber.
Commercial Spaces command the largest revenue pool; Industrial Facilities show the steepest expansion trajectory.
End User:
Professional training and liability exposure determine whether specification authority rests with design-phase consultants or construction-phase implementers.
- Architects:Early-stage design control enables premium product specification where acoustic modeling software integrates with building information management systems. German and French public procurement frameworks now require pre-certified low-emission documentation that architects must validate.
- Facility Managers:Post-occupancy retrofit decisions prioritize installed cost and disruption minimization over peak performance. Suspended ceiling replacements in aging United States office stock concentrate specification influence with this group.
- Interior Designers:Aesthetic integration requirements in hospitality and corporate headquarters settings drive wood and microperforated metal selections over standard white mineral fiber.
- Contractors:Procurement leverage concentrates with large continental European ceiling installation firms operating directly with mineral wool manufacturers.
Architects retain specification authority in new construction; Facility Managers dominate retrofit volume.
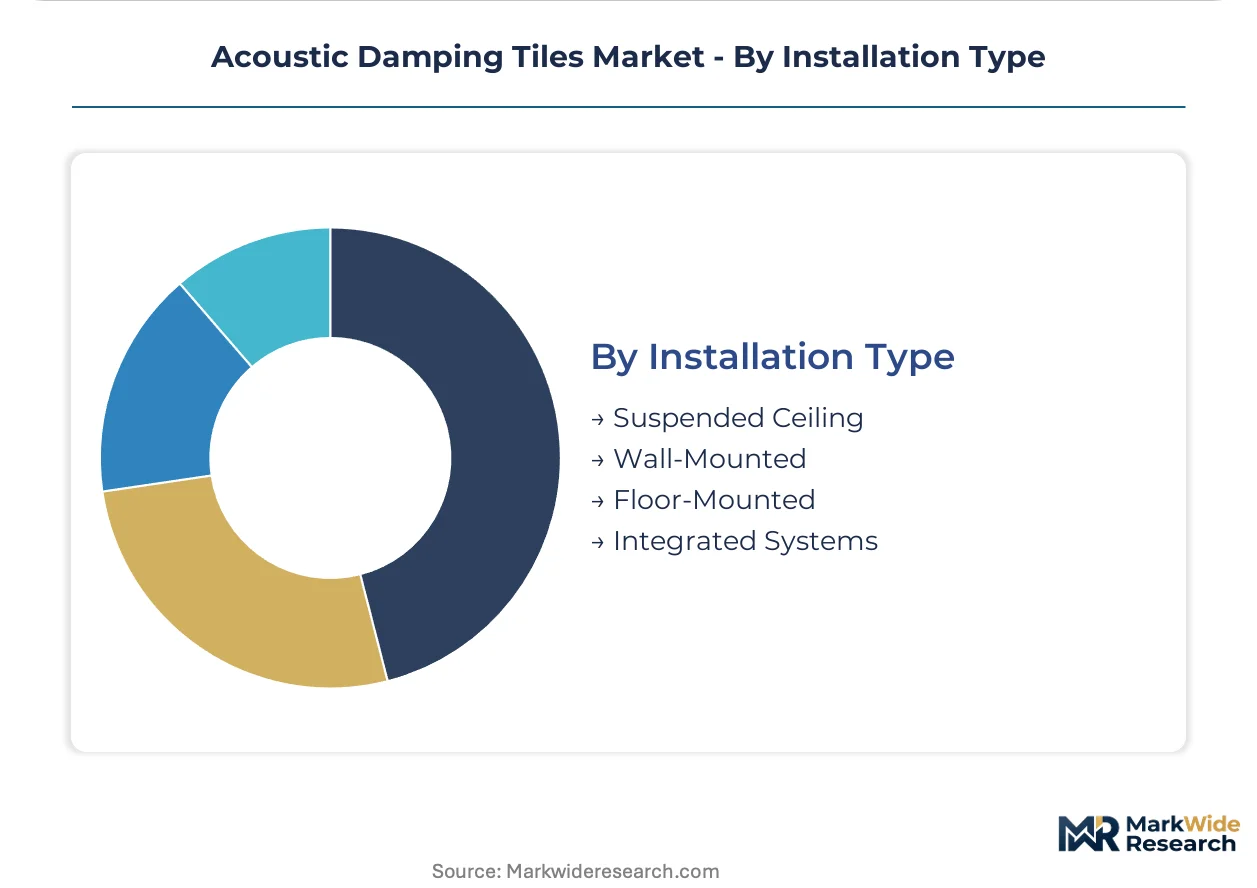
Installation Type:
Structural attachment geometry constrains material selection and labor cost allocation.
- Suspended Ceiling:T-bar grid systems accommodate standard 2×2 and 2×4 foot mineral fiber and vinyl tiles. This configuration dominates commercial office and healthcare retrofits where mechanical systems require continued access.
- Wall-Mounted:Fabric-wrapped and direct-adhered panels serve residential and entertainment applications where ceiling modification is structurally or economically prohibitive.
- Floor-Mounted:Freestanding acoustic partitions and baffles address open-plan offices and industrial environments lacking fixed ceiling infrastructure.
- Integrated Systems:Ceiling tiles embedding sensors, lighting, and HVAC diffusers command premium pricing in smart building developments pursuing building automation integration.
Suspended Ceiling maintains volume dominance; Integrated Systems capture the fastest share gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mineral fiber production concentrates in Eastern European smelter corridors, while specification authority and retrofit volume concentrate in mature commercial office markets across Western Europe, North America, and East Asia.
United States
Class A office developments in Manhattan, Chicago, and San Francisco drive suspended ceiling retrofits as facility managers pursue WELL Building Standard certification. OSHA enforces permissible noise exposure limits that mandate industrial facility upgrades. The Pacific Northwest corridor hosts acoustic engineering consultancies that influence specification patterns for integrated sensor-embedded ceiling systems.
Germany
Commercial office developers in Frankfurt, Munich, and Hamburg specify higher-grade mineral fiber tiles to satisfy EU Green Deal building performance standards. REACH compliance through ECHA restricts legacy flame retardants and formaldehyde-based binders, redirecting formulation investment toward mineral wool alternatives. The Rhine-Ruhr industrial cluster anchors mineral wool production capacity serving continental European contractors.
France
Public procurement frameworks in Paris, Lyon, and Marseille prioritize pre-certified low-emission acoustic products for new commercial construction. ANSM and CNIL oversight intersects with building material emissions monitoring in healthcare facility retrofits. The Île-de-France region concentrates specification authority among architects integrating acoustic modeling with building information management systems.
Japan
Hospital patient room and corridor retrofits in Tokyo, Osaka, and Nagoya present demand for infection-control-compatible sound-absorbing surfaces. METI building efficiency guidelines elevate acoustic comfort in workplace productivity calculations. The Kanto region hosts facility management firms that dominate post-occupancy retrofit decision-making for aging office stock.
China
Smart building developments in Shanghai, Beijing, and Shenzhen pilot integrated ceiling systems embedding sensors, lighting, and HVAC diffusers. MIIT standards and GB building codes increasingly reference acoustic performance metrics in commercial construction permits. The Yangtze River Delta concentrates manufacturing capacity for microperforated metal tiles serving premium conference room applications.
Acoustic Damping Tiles Market Vendor Landscape
Top-tier vendors anchor premium mineral fiber specification, while mid-scale fabricators compete on installed cost for residential and light commercial retrofits. The market structure reflects a tiered hierarchy where fire safety certification and distribution network depth separate premium positioning from commodity substitution. Three archetypes dominate: integrated building materials conglomerates with captive mineral wool capacity, specialized acoustic treatment firms focused on engineered systems, and regional contractors with direct procurement relationships. Capacity expansion and digital-physical bundling represent the dominant competitive moves reshaping margin capture.
Within the building materials conglomerate tier, Saint-Gobain and Rockwool International exemplify European-origin players leveraging mineral fiber production scale and fire-rated formulation expertise. Knauf Insulation occupies a position among German-based manufacturers operating large-scale mineral wool production lines. These three entities anchor the premium specification channel where EU Green Deal compliance and REACH-aligned low-emission certification determine bidding authority in commercial office developments across Germany, France, and adjacent markets.
| Leading Market Players |
|---|
| 3M |
| Autex Industries |
| Rockwool International |
| Auralex Acoustics |
| Armstrong World Industries |
| USG Corporation |
| Acoustical Surfaces |
| Saint-Gobain |
| Knauf Insulation |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between EU Green Deal-compliant mineral fiber and commodity foam alternatives splits pricing power across parallel supply channels. German and French specification authorities award bidding preference to pre-certified low-emission products, compressing margins for uncertified competitors while anchoring premium tier pricing to REACH-aligned formulation costs.
Pricing Analysis
Margin tightening in commodity foam traces to REACH-driven reformulation timelines and eighteen-month ECHA requalification cycles. Three-tier pricing structure across premium mineral fiber, standard vinyl, and economy foam segments reflects fire safety certification grade and after-sales digital calibration bundling. Cost-down pressure on foam accelerates as lightweight polyurethane substitution captures residential demand where durability requirements remain minimal. Facility managers in retrofit applications exhibit highest price sensitivity; architects in new commercial construction prioritize certification compliance over unit cost.
Supply Chain Analysis
EU domestic-content preferences under the Green Deal industrial plan redirect sourcing toward Rhine-Ruhr and Eastern European smelter corridors. Basalt and slag wool feedstock draws from German, Polish, and Czech metallurgical operations. Single-source vulnerability concentrates in Eastern European energy-intensive smelter capacity exposed to electricity cost volatility. Distribution runs through building materials conglomerates with captive mineral wool production serving continental European contractors directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into raw mineral wool capacity and embedded sensor technology represents the decisive competitive race, with backward control over basalt supply and forward bundling of digital calibration services separating premium positioning from commodity erosion.
For Market Incumbents: Lock in specification authority by deepening captive supply of REACH-compliant mineral fiber and embedding acoustic sensors for real-time reverberation monitoring. Acquire specialized acoustic engineering consultancies to overcome talent scarcity constraining installer scaling. Defend against foam substitution by emphasizing fire safety certification in public procurement frameworks.
For New Entrants and Emerging Players: Capture underpenetrated healthcare acoustics in Japanese hospital retrofits where infection-control-compatible surfaces remain undersupplied. Target industrial wash-down vinyl specifications in food processing and pharmaceutical manufacturing where chemical resistance requirements exclude standard porous absorbers. Lead with adhesive-mounted foam systems avoiding structural ceiling modifications in residential renovation channels.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by building materials conglomerates seeking REACH-compliant mineral fiber capacity and digital-physical bundling capabilities. Long-term viability hinges on regulatory certification depth rather than manufacturing scale alone. Watch EU Green Deal enforcement intensity and ECHA restriction list expansions as inflection indicators for mineral fiber demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Basalt Supply | Captive feedstock from Eastern European smelters insulates margin from energy cost volatility. |
| Digital Calibration Service Launch | Software-defined acoustic tuning converts one-time hardware sales into recurring subscription revenue streams. |
| REACH-Compliant Formulation Investment | ECHA-aligned low-emission certification unlocks bidding authority in German and French public procurement. |
| Healthcare-Specific Product Line | Infection-control-compatible surfaces address untapped demand in Japanese hospital retrofits. |
| Acoustic Engineering Talent Acquisition | Specialized room acoustics expertise overcomes installer scaling constraints constraining market expansion. |
Methodological Framework
Independent corroboration across primary interviews with ceiling system contractors, facility management directors, acoustic engineering consultants, and building materials procurement leads underwrites the qualitative findings. Secondary validation draws from ECHA restriction list updates, EU Green Deal implementation guidance, SEC filings of listed building materials conglomerates, and customs data on mineral wool trade flows. Bottom-up project pipeline assessment and top-down construction spend allocation triangulate market sizing.
Rate-of-change decomposition across product type, application, end-user professional identity, and installation geometry segments structures the analytical framework. Modeled dimensions include mineral fiber versus foam versus vinyl chemistry tiers, commercial versus industrial versus residential end-use, and suspended ceiling versus integrated system attachment geometry. CAGRs derive from segment-level volume trajectories weighted by pricing tier mix and regional regulatory enforcement intensity, with mineral fiber raw material cost pass-through and digital service attach rates as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH chemical restriction expansions, EU Green Deal building code enforcement timing, and energy cost volatility in Eastern European smelter operations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Shotcrete Market
Building Materials
Southeast Asia Concrete Admixtures Market
Building Materials
Construction Stone Market
Building Materials
United States Architectural Coatings Market
Building Materials
Granite Market
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
Global Drywall and Building Plaster Market
Building Materials
Concrete Blocks and Bricks Market
Building Materials
Ireland Cement Market
Building Materials
North America Cement Market
Building Materials
North America Construction Aggregates Market
Building Materials
Building and Construction Sheets Market
Building Materials
Indonesia Dry Mix Mortar Market
Building Materials
Latin America Facade Market
Building Materials
Rapid Strength Concrete Market
Building Materials
Europe Concrete Admixtures Market