
 Europe Acrylic Resin Dispersion Based Primers in Construction Market | 2026-2036
Europe Acrylic Resin Dispersion Based Primers in Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Acrylic Resin Dispersion Based Primers in Construction Market Foresight
Low-VOC specification tiers is rotating demand toward premium water-based acrylic primers across European construction supply chains. BASF SE leverages its Ludwigshafen dispersion capacity to anchor supply security for large-scale commercial projects. Henkel AG & Co. KGaA differentiates through specialized adhesion promoters for difficult substrates like aged concrete and gypsum. Arkema competes on bio-based acrylic monomer integration, responding to specifier requests for renewable content documentation.
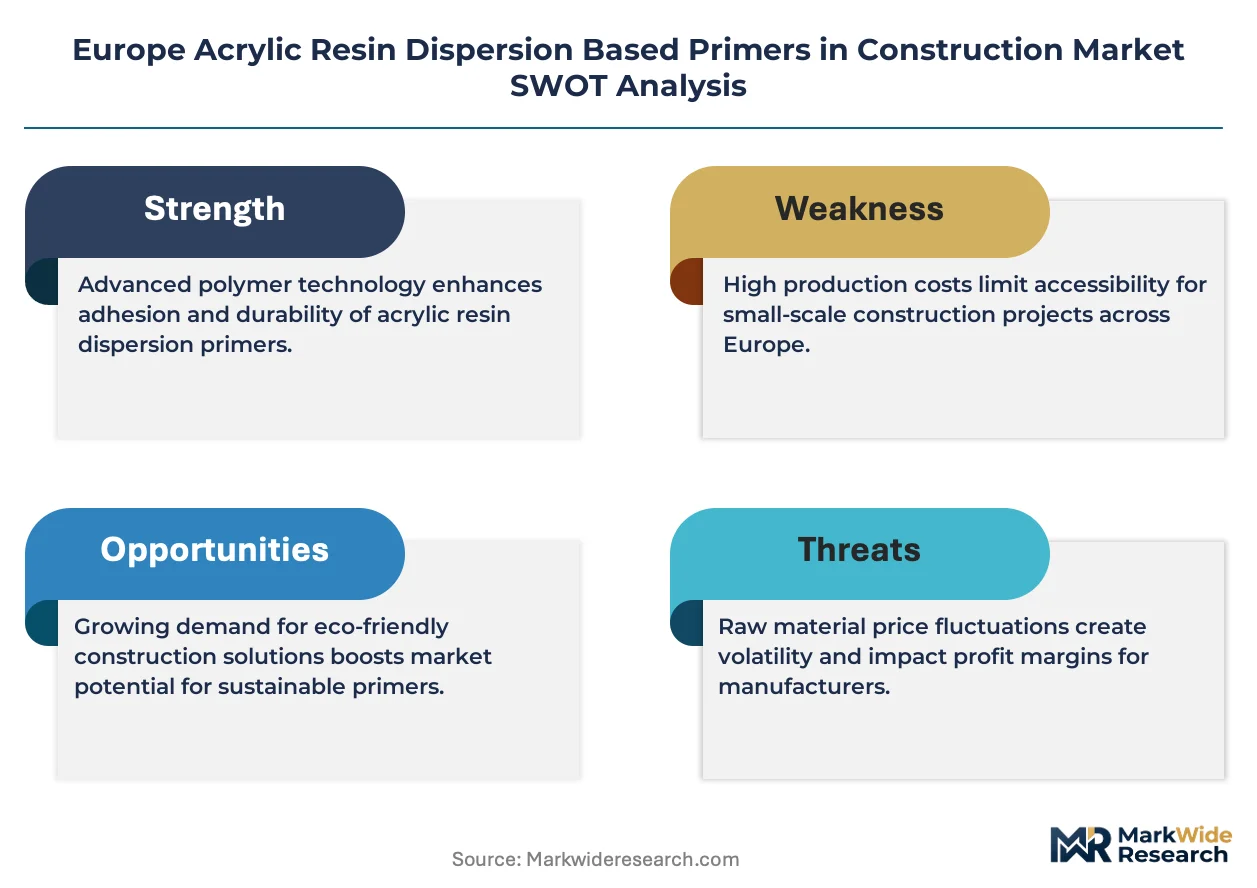
Europe acrylic resin dispersion based primers in construction are aqueous polymer emulsions containing 40-60% solids by weight, formulated with styrene-acrylic or pure acrylic copolymers that penetrate porous substrates to consolidate surfaces and improve topcoat bonding. Their primary purpose is sealing absorbent construction materials while providing uniform surface tension for subsequent decorative or protective coatings. Exterior primers lead volume distribution due to weathering protection requirements across Nordic and Atlantic climate zones, though eco-friendly primers represent the fastest-expanding margin pool as green building certification penetration deepens. Specialty primers for contaminated or fire-damaged substrates occupy a concentrated premium niche where technical specification overrides price sensitivity.
REACH registration requirements and the EU F-Gas Regulation constrain solvent-based formulation pathways, while CE marking under the Construction Products Regulation mandates declared performance values for primer breathability and crack-bridging capacity. ECHA's ongoing restriction proposals for residual formaldehyde in interior coatings are forcing reformulation timelines among dispersion suppliers serving the residential segment. Stakeholders must monitor how the EU Green Deal's embodied carbon reporting rules for construction products will alter procurement criteria for primer systems in publicly tendered infrastructure work.
Market Dynamics
EU Green Deal VOC thresholds are compressing formulation pathways toward water-based acrylic dispersions, eliminating solvent-bearing alternatives from commercial specification lists across member states.
Growth Catalysts
- Residential renovation intensity:Germany, France, and UK homeowners are prioritizing moisture-resistant interior finishes, accelerating primer consumption in single-family refurbishment projects.
- REACH registration pathways:Chemical compliance frameworks now favor aqueous polymer emulsions over solvent systems, redirecting R&D investment toward near-zero emission formulations.
- Heritage structure mandates:Berlin and Munich building codes now require breathable primer systems for commercial refurbishment, creating specification lock-in for compliant suppliers.
Market Restraints
- Styrene-acrylic monomer volatility:Petrochemical feedstock cost swings compress margin stability for dispersion manufacturers serving price-sensitive residential segments.
- Supply concentration in Ludwigshafen corridor:German production clusters create geographic risk exposure for large-scale commercial projects requiring just-in-time delivery.
- Performance ceiling on aged concrete:Standard acrylic dispersions exhibit adhesion failure rates above acceptable thresholds on contaminated substrates without specialized promoters.
Strategic Opportunities
- Eastern European construction acceleration:Poland and Romania infrastructure tenders are adopting EU-compliant primer specifications, opening white space for REACH-registered suppliers.
- Bio-based monomer integration:Specifier requests for renewable content documentation are creating premium positioning for acrylic producers with certified bio-carbon feedstocks.
- Digital specification platforms:Construction product databases are displacing traditional distributor relationships, enabling direct technical engagement with architect and engineer specifiers.
Industry Challenges
- Formaldehyde restriction timelines:ECHA's ongoing proposals for residual limits in interior coatings are forcing compressed reformulation cycles without guaranteed regulatory finality.
- Embodied carbon reporting readiness:EU Green Deal construction product rules will require primer suppliers to deploy lifecycle assessment infrastructure ahead of public tender mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Acrylic Resin Dispersion Based Primers in Construction Market |
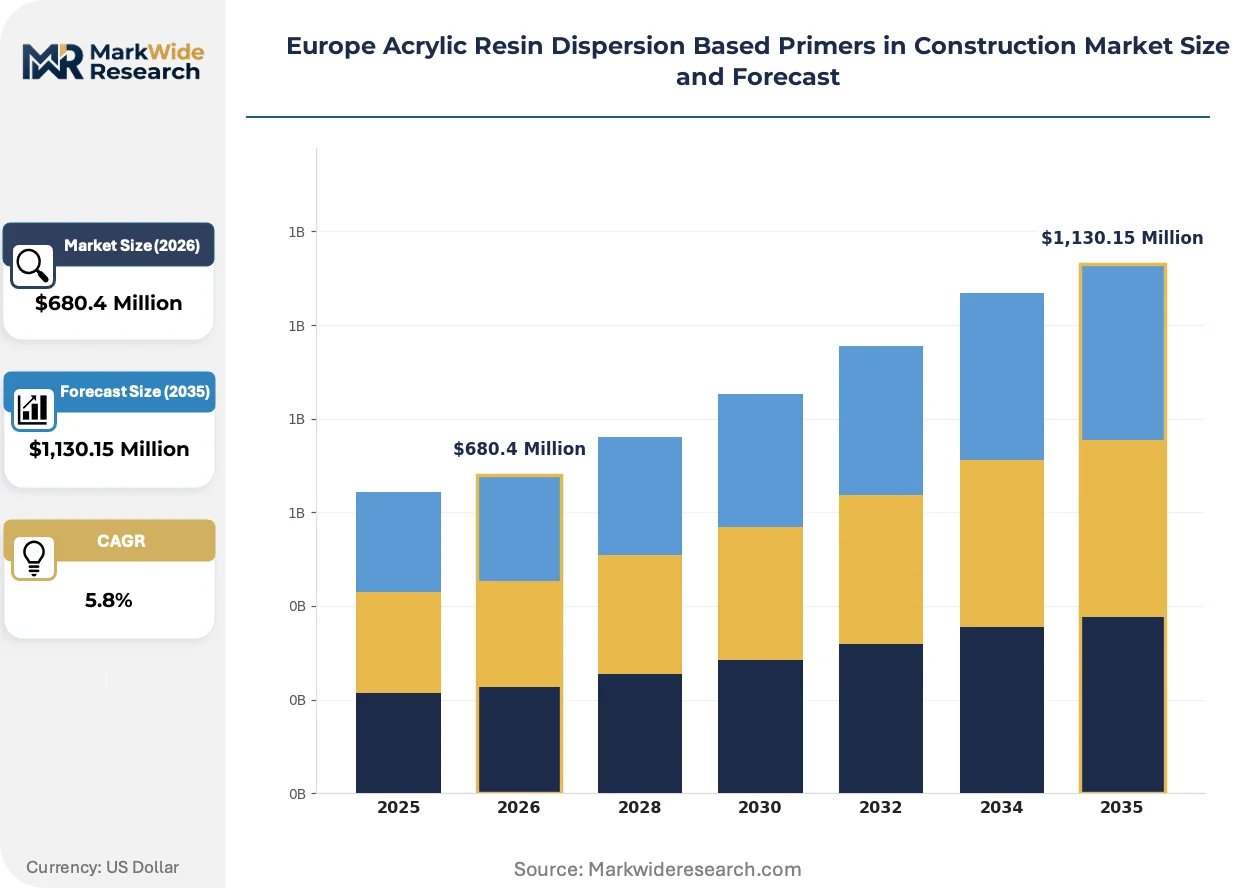
| Market Size in 2026 | $680.4 Million |
| Market Size in 2035 | $1,130.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
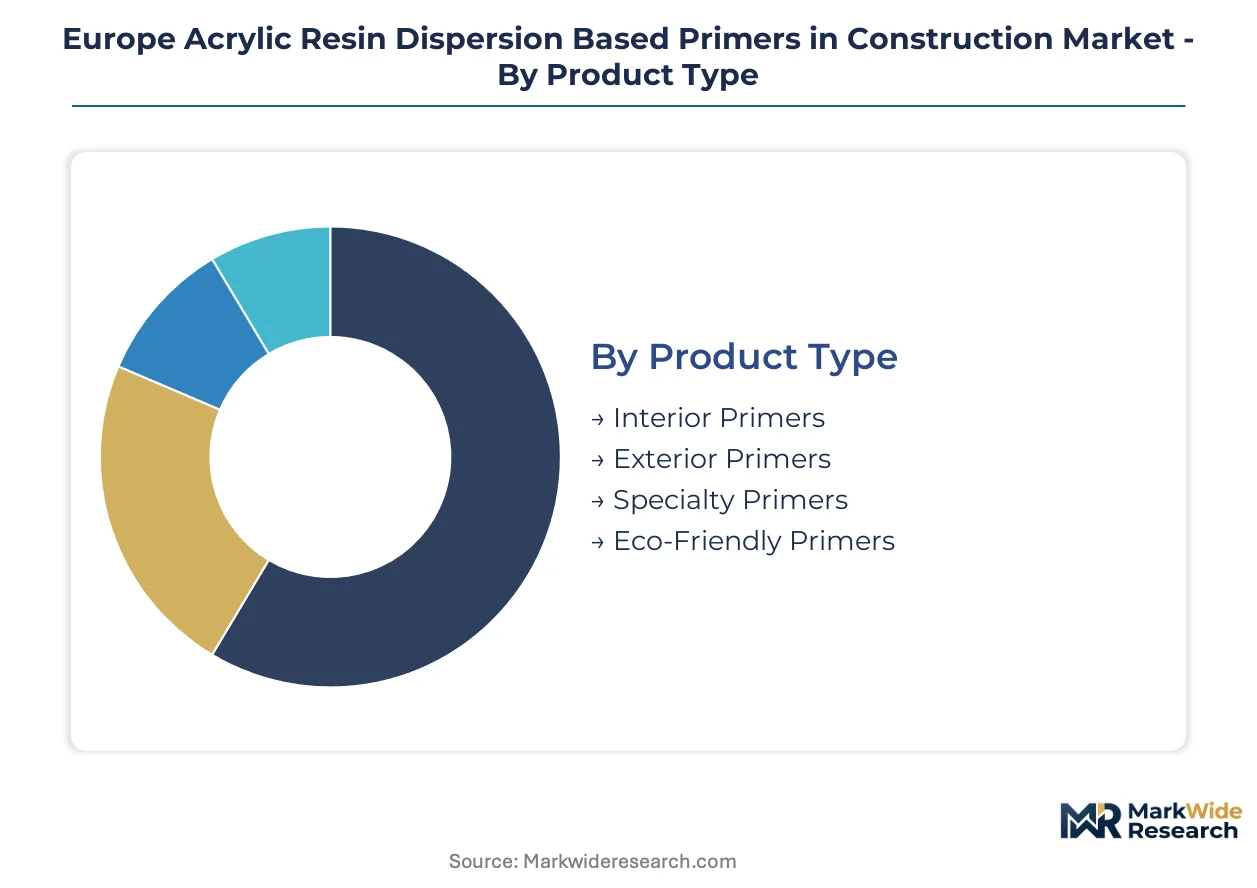
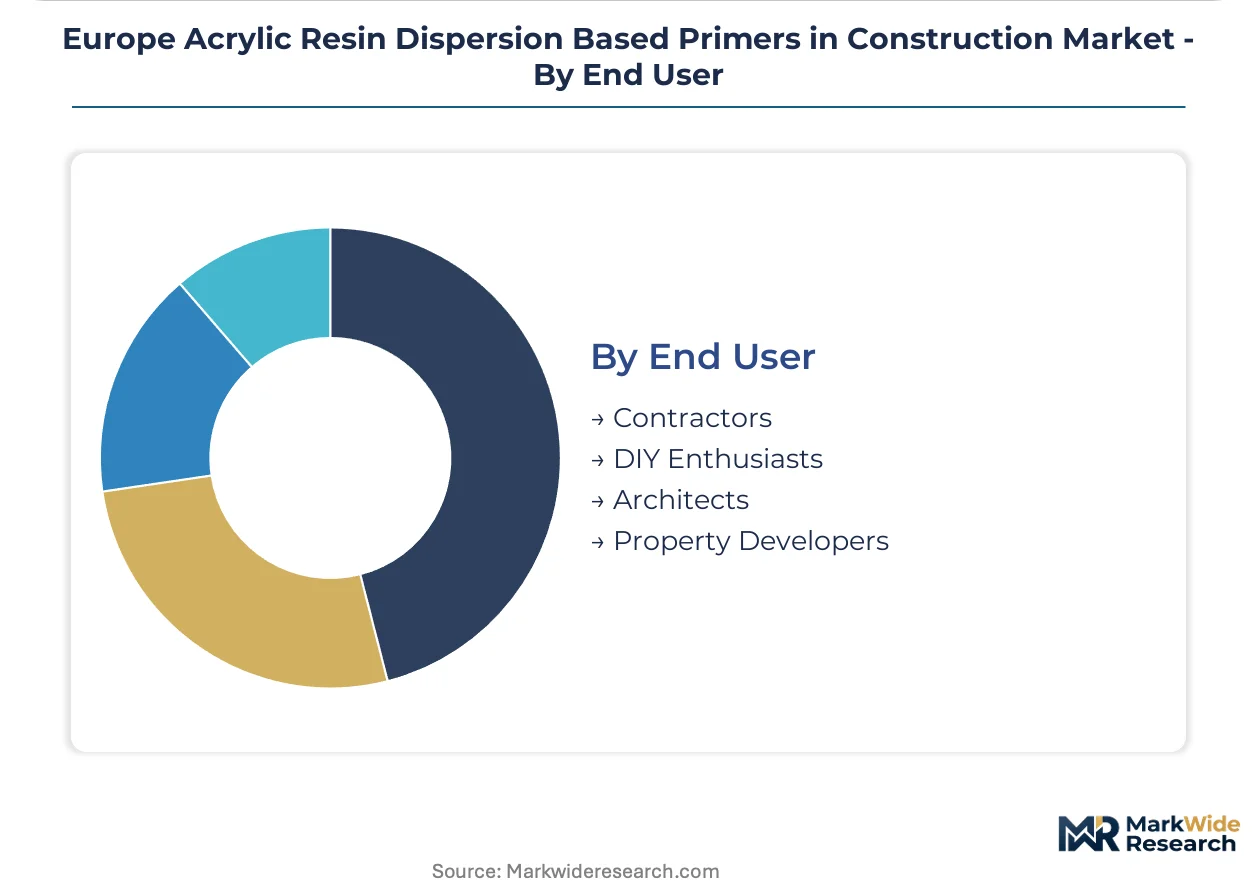
| Segmentation | Product Type: Interior Primers, Exterior Primers, Specialty Primers, Eco-Friendly Primers Application: Residential, Commercial, Industrial, Infrastructure Technology: Water-Based, Solvent-Based, Hybrid, UV-Curable End User: Contractors, DIY Enthusiasts, Architects, Property Developers |
| Companies Covered | AKZO NOBEL N.V., Henkel AG & Co. KGaA, Nippon Paint Holdings Co., Ltd., Jotun, BASF SE, Dow, Solvay, Kansai, Arkema, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Acrylic Resin Dispersion Based Primers in Construction Market Shifts & Advancements
Acrylic resin dispersion technology is pivoting toward substrate-specific functionality as generic sealing performance becomes commoditized across European supply chains.
Hybrid styrene-acrylic copolymers with silane crosslinking functionality are fragmenting the traditional exterior primer category. Façade restoration contractors in Nordic climate zones are specifying these systems for freeze-thaw durability. The technology is fragmenting volume concentration away from pure acrylic formulations toward segmented performance tiers.
EU F-Gas Regulation constraints on solvent-based pathways are eliminating residual formulation options for interior commercial applications. Industrial coating operations serving retail fit-out sectors are converting aqueous dispersion lines ahead of enforcement windows. Heritage rehabilitation specialists face the steepest adaptation curves given breathability requirements that conflict with fast-curing solvent alternatives.
Architect specification behavior is rotating toward certified environmental product declarations as gatekeeping criteria. Large commercial developers in France and the Netherlands are unbundling primer procurement from painting contractor packages to enforce direct compliance verification. This pattern concentrates most visibly in publicly tendered infrastructure where EU Green Deal procurement rules mandate documented low-VOC performance.
Europe Acrylic Resin Dispersion Based Primers in Construction Market Segmentation
Acrylic resin dispersion primers fragment across multiple technical and commercial dimensions, each carrying distinct margin profiles and regulatory exposure. Understanding these segment boundaries clarifies where formulation investment yields competitive advantage versus commodity trap risk.
Product Type:
Substitution pressure from bio-based alternatives and mineral silicate systems varies sharply across primer categories, with exterior formulations facing the most intense displacement threat from evolving masonry coating technologies.
- Interior Primers:Low-VOC water-based styrene-acrylic emulsions formulated for gypsum, plaster, and drywall sealing. German and French residential renovation contractors specify these for moisture-blocking base coats in single-family refurbishment, driven by ECHA formaldehyde restriction timelines compressing acceptable emission thresholds.
- Exterior Primers:Weathering-resistant pure acrylic or hybrid copolymer systems with silane crosslinking for façade durability. Nordic climate zone restoration projects in Sweden and Denmark concentrate demand for freeze-thaw resistant grades, though mineral silicate competitors are capturing share in heritage masonry applications.
- Specialty Primers:High-adhesion formulations with tailored promoters for fire-damaged, contaminated, or aged concrete substrates.
- Eco-Friendly Primers:Bio-based acrylic monomer systems with certified renewable content documentation for green building certification compliance.
Exterior primers anchor the volume base while eco-friendly primers gain share at the steepest rate.
Application:
Cost tier stratification separates specification-grade commercial projects from price-sensitive residential rollouts, with infrastructure tenders imposing the most demanding compliance documentation burdens.
- Residential:Standard water-based primers for interior wall preparation in new construction and renovation. UK and German homeowners prioritize moisture-resistant finishes, accelerating consumption in single-family refurbishment where DIY application rates remain elevated.
- Commercial:Breathable primer systems mandated by Berlin and Munich building codes for heritage structure rehabilitation. Large French and Dutch developers unbundle primer procurement from painting contractor packages to enforce direct low-VOC verification.
- Industrial:Heavy-duty corrosion-inhibiting primers for manufacturing facility maintenance.
- Infrastructure:CE-marked systems with declared performance values for publicly tendered bridge, tunnel, and transit projects.
Commercial applications command premium pricing while residential renovation delivers the deepest volume penetration.
Technology:
Supply concentration in German dispersion manufacturing clusters creates geographic risk exposure that technology choice can either amplify or mitigate through formulation flexibility.
- Water-Based:Aqueous acrylic emulsions with 40-60% solids content, now the default pathway under EU Green Deal VOC thresholds. REACH registration requirements and F-Gas Regulation constraints have eliminated solvent alternatives from commercial specification lists.
- Solvent-Based:Declining residual category confined to niche fast-curing applications where breathability requirements conflict with aqueous system drying times.
- Hybrid:Styrene-acrylic copolymers with silane functionality bridging water-based environmental compliance with solvent-grade performance.
- UV-Curable:Emerging industrial coating line technology for retail fit-out sectors converting ahead of enforcement windows.
Water-based systems dominate current procurement while hybrid formulations expand most quickly among specification-sensitive contractors.
End User:
Digital specification platforms are displacing traditional distributor relationships, altering how each user category accesses technical product data and compliance documentation.
- Contractors:Professional applicators purchasing through construction supply distributors for multi-unit residential and commercial projects. Polish and Romanian infrastructure tender adoption of EU-compliant specifications is opening new geographic white space for REACH-registered suppliers.
- DIY Enthusiasts:Retail channel consumers selecting convenience-formatted primer products for interior home improvement.
- Architects:Specification gatekeepers rotating toward certified environmental product declarations as procurement criteria. Direct technical engagement through construction product databases is replacing legacy distributor relationships.
- Property Developers:Large commercial portfolio managers unbundling primer procurement to enforce lifecycle assessment readiness ahead of EU Green Deal embodied carbon reporting mandates.
Contractors drive immediate volume throughput while architects control long-term specification lock-in trajectories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European acrylic primer trade flows reflect a net export position concentrated in German chemical manufacturing clusters, with import dependency concentrated in Eastern European construction markets lacking domestic dispersion capacity.
Germany
Heritage rehabilitation mandates in Berlin and Munich building codes are concentrating demand for breathable primer systems. REACH registration requirements favor domestic aqueous polymer emulsion producers over imported solvent-bearing alternatives. The Ludwigshafen chemical corridor anchors dispersion supply security for large-scale commercial projects requiring just-in-time delivery.
France
Large commercial developers in Paris and Lyon are unbundling primer procurement from painting contractor packages to enforce direct low-VOC verification. EU Green Deal procurement rules mandate documented environmental product declarations for publicly tendered infrastructure work. The Île-de-France region concentrates specification-grade demand for green building certification compliance.
United Kingdom
Homeowners in London and Southeast England are prioritizing moisture-resistant interior finishes, accelerating primer consumption in single-family refurbishment where DIY application rates remain elevated. ECHA formaldehyde restriction timelines are compressing acceptable emission thresholds for residential coatings. Manchester and Birmingham commercial corridors drive specification-grade volume for retail fit-out sectors.
Poland
Infrastructure tenders in Warsaw and Kraków are adopting EU-compliant primer specifications, opening white space for REACH-registered suppliers without domestic production. Construction acceleration in Eastern European markets is outpacing local dispersion manufacturing capacity. Polish contractors rely on German and Benelux supply chains for aqueous acrylic emulsion systems.
Netherlands
Architect specification behavior in Rotterdam and Amsterdam is rotating toward certified environmental product declarations as gatekeeping criteria. The Randstad urban cluster concentrates demand for green building certification penetration in commercial development. Dutch procurement patterns exemplify early adoption of EU Green Deal embodied carbon reporting readiness requirements.
Europe Acrylic Resin Dispersion Based Primers in Construction Market Competitive Landscape
Concentration sits with integrated chemical conglomerates controlling upstream monomer supply and downstream dispersion formulation. Three tiers structure competitive positioning: multinational coating chemical suppliers with captive resin production, regional specialty formulators serving niche substrate applications, and construction chemical distributors private-labeling commodity primers. M&A activity targets bio-based acrylic technology assets, while capacity expansion concentrates in German Rhine corridor clusters to serve just-in-time commercial project logistics.
Within the integrated chemical supplier tier, BASF SE and Arkema exemplify archetypes anchoring competitive dynamics through upstream dispersion capacity and bio-based monomer development respectively. Henkel AG & Co. KGaA occupies a position representing specialty adhesion promoter differentiation for difficult substrates. These three entities illustrate how REACH registration compliance and Ludwigshafen production gravity combine to structure market access barriers for non-European competitors.
| Leading Market Players |
|---|
| AKZO NOBEL N.V. |
| Henkel AG & Co. KGaA |
| Nippon Paint Holdings Co., Ltd. |
| Jotun |
| BASF SE |
| Dow |
| Solvay |
| Kansai |
| Arkema |
| Others |
Supply & Pricing Matrix
Capacity utilization at Ludwigshafen dispersion plants shapes both supply concentration and price floors for European acrylic primer markets. REACH registration compliance costs create fixed barriers that protect incumbent pricing power while compressing margin flexibility for smaller formulators serving price-sensitive residential segments.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the European construction primer market. Price differentiation separates CE-marked breathable systems for heritage rehabilitation from standard interior grades, with certification level and volume scale as primary tiering mechanisms. Cost compression in residential-grade styrene-acrylic emulsions is intensifying because petrochemical feedstock volatility compresses formulation margins. DIY enthusiasts exhibit highest price sensitivity, while heritage restoration contractors demonstrate lowest sensitivity given technical specification mandates.
Supply Chain Analysis
Just-in-time delivery preferences dominate large-scale commercial projects in Germany and France, though strategic stockpiling persists among Polish contractors managing German supply chain lead times. Raw material dependencies center on styrene and acrylic acid monomers from Ludwigshafen and Antwerp petrochemical clusters, with methyl methacrylate feedstocks drawing from Rotterdam refining capacity. Single-source vulnerability concentrates in German dispersion manufacturing, where BASF SE and Arkema control upstream polymer emulsion capacity. Distribution runs through construction chemical distributors and direct specification channels to architect and engineer gatekeepers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and specification support engagements expand faster than hardware volumes in European acrylic primer markets. Recurring specification lock-in through certified environmental product declarations offers superior lifetime value capture than transactional primer sales alone.
For Market Incumbents: Fortify backward integration into bio-based acrylic monomer production to preempt Arkema's renewable content positioning. Expand REACH-registered aqueous dispersion capacity in the Benelux corridor to mitigate geographic concentration risk from Ludwigshafen supply clusters. Mineral silicate primer substitution in Nordic heritage masonry applications threatens pure acrylic exterior formulations. For New Entrants and Emerging Players: Lead with digital specification platform partnerships targeting architect and engineer gatekeepers in Poland and Romania. Eastern European infrastructure tenders adopting EU-compliant primer specifications offer the most penetrable white space without domestic dispersion competition. Direct technical engagement through construction product databases displaces legacy distributor relationships in these markets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty primer formulators with certified adhesion promoter technology for contaminated substrates. Long-term viability favors targets with documented lifecycle assessment infrastructure ahead of EU Green Deal embodied carbon reporting mandates. Watch ECHA formaldehyde restriction finalization as inflection indicator for residential segment reformulation spending.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Monomers | Secures renewable content certification for EU Green Deal procurement compliance. |
| REACH Registration Expansion | Unlocks specification access for publicly tendered infrastructure across Eastern Europe. |
| Digital Specification Platform Partnerships | Displaces distributor intermediaries for direct architect and engineer engagement. |
| Lifecycle Assessment Infrastructure Deployment | Prepares for embodied carbon reporting mandates in Dutch and French tenders. |
| Hybrid Silane-Acrylic Capacity Addition | Captures freeze-thaw durability demand from Nordic façade restoration contractors. |
Research Methodology
Cross-validation between primary interviews with plant managers at German dispersion facilities and secondary trade data from Cefic and customs records anchors the qualitative findings. Technical R&D directors at coating formulators, procurement leads at downstream construction OEMs, and distribution channel partners across France, Germany, and Poland provided field-level input. SEC 10-K filings and declared performance values under CE marking supplemented bottom-up and top-down triangulation across product type and application segments.
Sensitivity analysis around styrene-acrylic monomer cost trajectories and EU Green Deal enforcement timelines informs the analytical framework across the projection horizon. Segmentation dimensions modeled include primer category, application end-use, technology pathway, and regional regulatory cluster. CAGRs derive from volume-demand buildups by construction activity intensity and specification-grade adoption curves, with heritage rehabilitation mandates and formaldehyde restriction timelines as industry-specific forecast inputs.
Forecasts assume regulatory continuity in REACH, EU Green Deal, and F-Gas Regulation regimes; material policy shifts would require re-modeling. Styrene feedstock price volatility and Eastern European infrastructure tender acceleration represent specific risk factors. Revision becomes warranted when bio-based acrylic monomer cost parity crosses thresholds for mass-market penetration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
North America Construction Aggregates Market
Building Materials
Calcium Aluminate Cement Market
Building Materials
Europe Aluminum Door and Window Market
Building Materials
Foam Concrete Market
Building Materials
ASEAN Dry Mix Mortar Market
Building Materials
Roofing and Tile Underlayment Market
Building Materials
Portland Cement Market
Building Materials
Europe Fireproof Cladding Market
Building Materials
Global Fiber Cement Siding Market
Building Materials
Germany Aluminum Door and Window Market
Building Materials
Refractory Cement Market
Building Materials
Commonwealth of Independent States (CIS) Building and Construction Sheets Market
Building Materials
Singapore Architectural Coatings Market
Building Materials
Gravity Retaining Wall Market
Building Materials
Fire Resistant Mortar Market
Building Materials
Stone Adhesive Market