
 Stone Coated Steel Roofing Market | 2026-2036
Stone Coated Steel Roofing Market Size, Share, and Industry Trends Forecast 2026-2036
Stone Coated Steel Roofing Market Outlook
Residential re-roofing is rebalancing toward premium weather-resistant systems as homeowners replace aging asphalt roofs with longer-life alternatives. DECRA Roofing Systems leverages its proprietary interlocking panel design to dominate coastal markets with strict wind codes. Tilcor Roofing Systems anchors its position through backward integration into stone granule sourcing, controlling raw material quality across production batches. Boral Roofing competes on brand strength in the commercial segment, where specifiers prioritize warranty depth and installer certification networks.
Stone coated steel roofing consists of galvanized or galvalume steel substrate coated with acrylic resin and embedded mineral granules, achieving Class A fire ratings and impact resistance to hailstones while mimicking clay or slate aesthetics. The product type dimension shows shingles leading volume due to familiar installation methods, while panels capture margin pools through faster commercial deployment and reduced labor hours. Application segmentation reveals residential retrofit outpacing new construction as housing stock ages and insurance incentives reward resilient roofing upgrades.
ASTM International standards govern impact resistance and corrosion testing protocols, while the International Code Council publishes wind uplift requirements adopted across hurricane-prone jurisdictions. The EPA's ENERGY STAR program and various state-level cool roof mandates shape product development priorities by rewarding solar reflectance thresholds. Stakeholders must monitor evolving insurance industry risk models that increasingly tie premium discounts to verified storm-resistance certifications rather than nominal material claims.
Market Dynamics
Residential re-roofing cycles are compressing replacement timelines as insurance carriers withdraw coverage from aging asphalt shingle roofs in hurricane corridors, forcing homeowners toward Class A fire-rated alternatives before natural end-of-life.
Growth Catalysts
- Florida's wind uplift standards:The state's building code amendments mandate enhanced fastening patterns for high-velocity hurricane zones, disqualifying traditional three-tab shingles and redirecting volume toward interlocking steel systems.
- Cool roof mandates:California's Title 24 energy codes establish minimum solar reflectance thresholds for residential re-roofing permits, creating compliance-driven substitution toward granule-coated metal substrates.
- Hail belt concentration:Front Range Colorado and Texas Panhandle homeowners face repeated total-loss roof claims, concentrating demand for impact-resistant stone coated steel as insurers mandate material upgrades for policy renewal.
Market Restraints
- Zinc-aluminum alloy volatility:Galvalume substrate pricing tracks London Metal Exchange aluminum and zinc futures, compressing manufacturer margins when base metal inventories tighten.
- Granule supply concentration:Three domestic quarries control premium ceramic-coated stone sourcing for roofing granules, creating single-source vulnerability for coating consistency.
- Clay tile aesthetic substitution:Synthetic composite shingles achieve comparable visual mimicry at lower installed cost, threatening price-sensitive residential segments.
Strategic Opportunities
- Midwestern underpenetration:Ohio, Michigan, and Illinois housing stock remains dominated by asphalt, presenting first-mover expansion potential as hail severity increases.
- Solar-integrated reroofing:Building-integrated photovoltaics converge with standing seam steel substrates, enabling single-installation weatherproofing and energy generation.
- Installer certification networks:Factory-authorized contractor programs create channel control and capture margin pools currently lost to unqualified roofing crews.
Industry Challenges
- Specialized fastening expertise:Proper interlocking panel installation requires training in torque-limited screw guns and expansion joint placement, creating labor bottlenecks in remote markets.
- UL 2218 certification timelines:Class 4 impact rating testing protocols extend product launch cycles by eight to fourteen months for new granule formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stone Coated Steel Roofing Market |
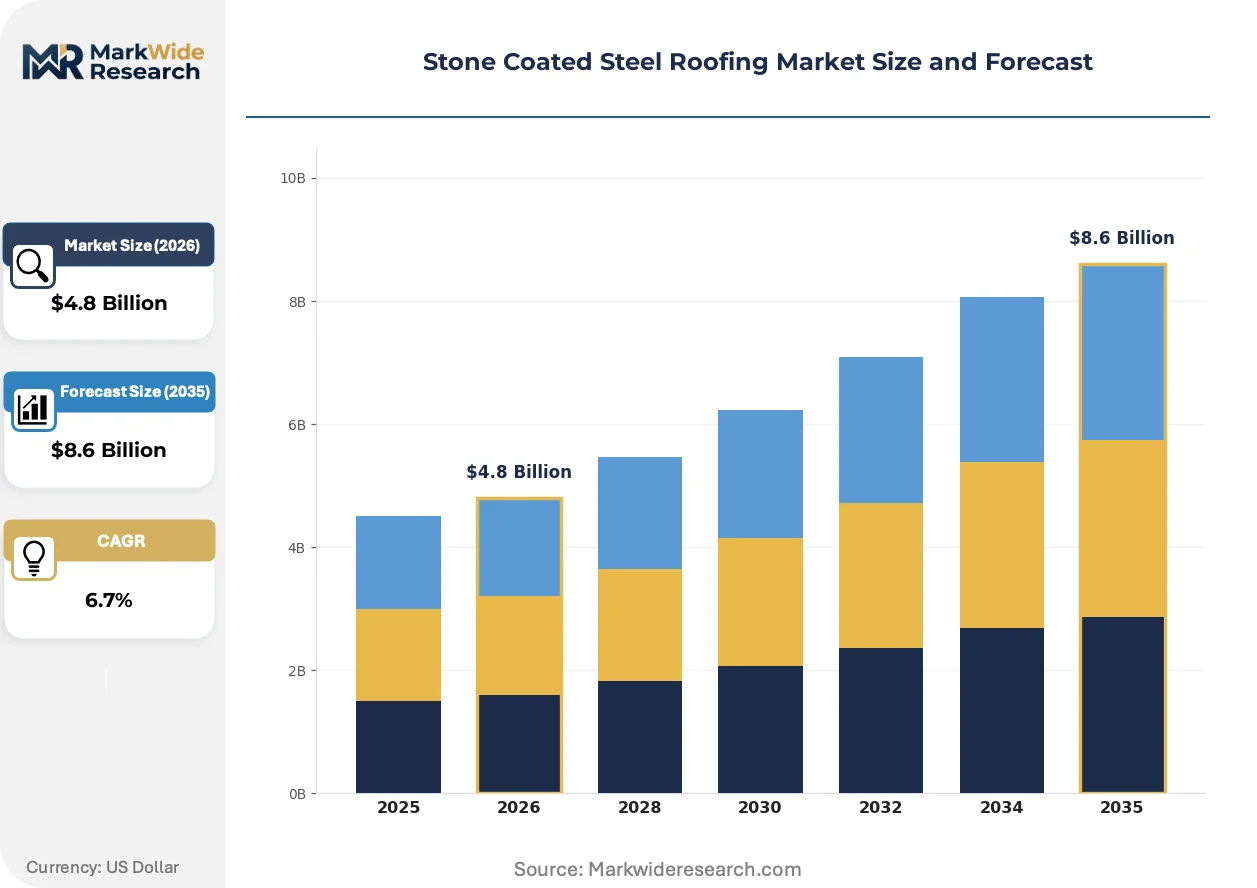
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shingles, Tiles, Sheets, Panels Application: Residential, Commercial, Industrial, Agricultural Installation Method: New Construction, Retrofit, Repair, DIY Finish Type: Matte, Glossy, Textured, Smooth |
| Companies Covered | DECRA Roofing Systems, Boral Roofing, Tilcor Roofing Systems, Roser Co., Ltd., Ross Roof Group, Quarrix, Hartman Roofing, Gerard Roofing, Westlake Royal Roofing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stone Coated Steel Roofing Market Strategic Shifts
Material science advances and code harmonization are compressing product development cycles while expanding addressable applications beyond traditional residential retrofit.
Cool pigment technology is integrating infrared-reflective ceramic granules into standard stone coating formulations. Commercial re-roofing specifiers in Texas and Arizona are specifying these substrates for warehouse and retail envelope retrofits. The technology is integrating energy compliance into aesthetic requirements previously treated as separate purchase criteria.
The EPA's ENERGY STAR Roof Products program revised its solar reflectance testing protocols in 2023, tightening measurement tolerances for aged material performance. Manufacturers must now submit three-year weathered samples rather than factory-fresh panels, extending certification costs and disqualifying marginal formulations. Residential retrofit distributors in California and Florida are prioritizing warehouse inventory toward pre-certified product lines to avoid permitting delays.
Insurance-driven material specification is concentrating buying authority into carrier-preferred contractor networks. Homeowners in coastal counties now receive policy renewal notices listing approved roofing materials and certified installers, bypassing traditional architect and general contractor influence. This channel consolidation is most visible in Louisiana, Mississippi, and Alabama, where state insurance pools dominate wind coverage availability.
Stone Coated Steel Roofing Market Segmentation
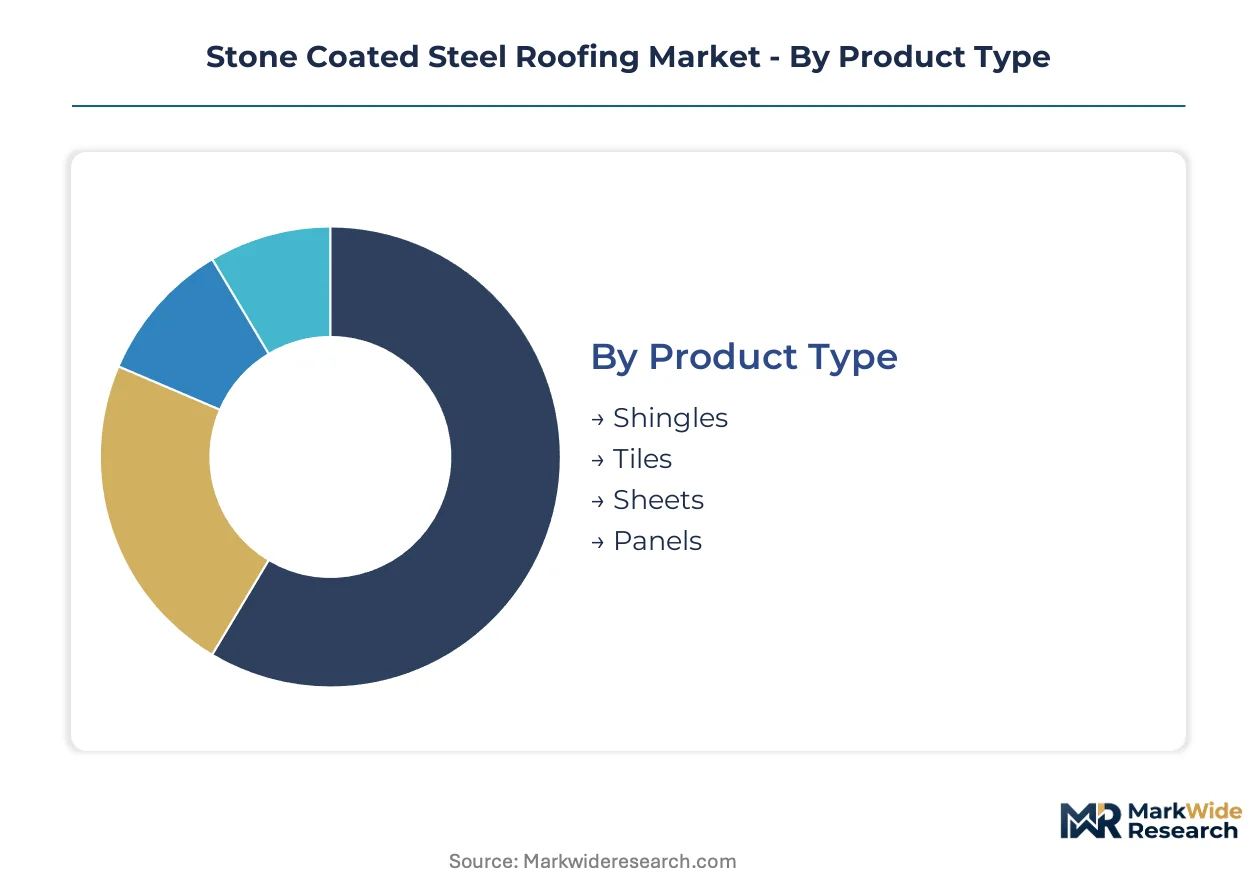
Stone coated steel roofing segments diverge sharply on certification burdens, with wind uplift ratings and fire classifications determining which products qualify for insurance discounts and code compliance. Understanding these segment boundaries reveals where margin pools concentrate versus where volume flows.
Product Type:
UL 2218 impact ratings and Florida Product Approval codes segment the product landscape, with interlocking systems facing stricter fastening scrutiny than overlapping profiles.
- Shingles:Galvalume steel substrate cut into overlapping rectangular profiles mimicking asphalt dimensional shingles. Demand clusters in residential retrofit across Florida's high-velocity hurricane zones where homeowners seek familiar aesthetics with Class 4 impact certification.
- Tiles:Press-formed profiles replicating clay barrel or flat tile configurations with mechanical fastening through pre-punched nailing flanges. Coastal California municipalities specify these for Title 24 cool roof compliance combined with seismic load resistance.
- Sheets:Continuous roll-formed panels with concealed clip fastening systems. Agricultural outbuildings in Texas and Oklahoma specify these for rapid coverage of large roof planes.
- Panels:Modular interlocking units with tongue-and-groove vertical seams. Commercial re-roofing in hurricane corridors favors these for reduced labor hours and factory-controlled quality.
Leading the category by volume: Shingles. Growing fastest: Panels.
Application:
Insurance underwriting criteria and building code amendments split demand across end-use categories, with residential retrofit commanding premium pricing through carrier-mandated material upgrades.
- Residential:Single-family and multi-family re-roofing dominates volume as aging asphalt stock reaches replacement age. Hail belt homeowners in Colorado and Texas face non-renewal notices unless upgrading to Class 4 rated systems.
- Commercial:Retail, office, and warehouse envelope retrofits specify stone coated steel for accelerated depreciation schedules and energy compliance. Texas power purchase agreements increasingly tie commercial solar installations to cool roof substrates.
- Industrial:Manufacturing facilities and distribution centers prioritize corrosion-resistant galvalume substrates for chemical exposure environments.
- Agricultural:Barns, equipment shelters, and processing facilities value the material's rodent resistance and structural load capacity for hay storage.
Residential commands the largest revenue pool. Commercial retrofit shows the steepest expansion trajectory as ESG disclosure requirements tighten.
Installation Method:
Labor availability and permit complexity separate installation channels, with factory certification requirements blocking unqualified crews from insurance-preferred contractor networks.
- New Construction:Specified during framing phase with integrated flashing and ventilation design. Production homebuilders in Florida and California negotiate volume pricing through national purchasing agreements.
- Retrofit:Tear-off replacement of existing roofing dominates current volume as housing stock ages. Insurance carriers in Louisiana and Mississippi now pre-approve retrofit materials through managed repair programs.
- Repair:Storm damage restoration and isolated panel replacement. Hail events in the Front Range generate concentrated repair demand with expedited permitting.
- DIY:Limited to accessory structures and rural properties without mortgage insurance requirements. Big-box retailers stock shingle profiles for this channel with simplified fastening instructions.
Retrofit installation leads by project count. New construction offers the most stable pricing through contract manufacturing arrangements.
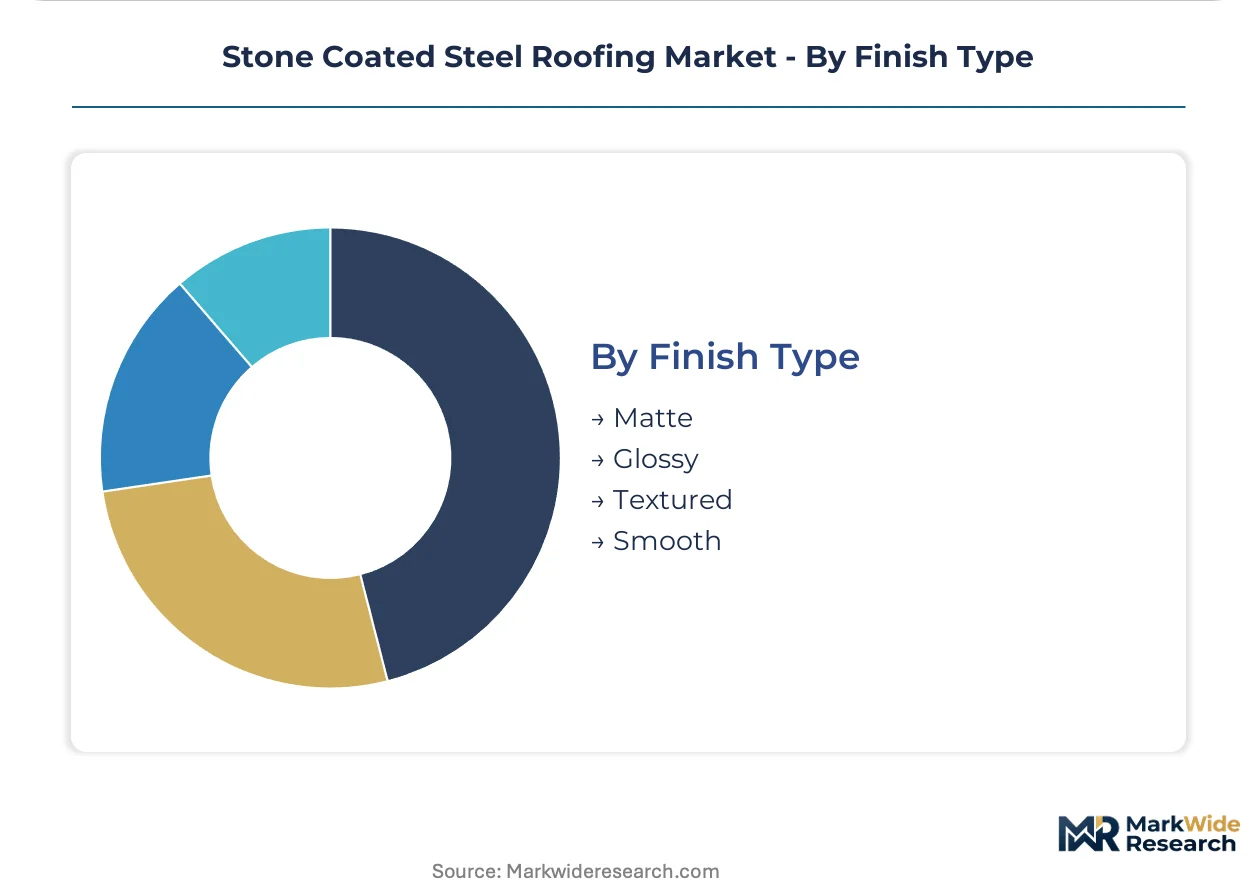
Finish Type:
Solar reflectance testing protocols and aesthetic matching requirements divide finish specifications, with infrared-reflective ceramics commanding price premiums in code-mandated markets.
- Matte:Low-sheen acrylic resin coating with standard ceramic granule embedment. Traditional residential applications in the Southeast favor this finish for clay tile authenticity.
- Glossy:Higher resin content creating reflective surface properties. Commercial specifiers in Arizona and Nevada specify these for enhanced solar reflectance index performance.
- Textured:Multi-layer granule application creating dimensional depth mimicking natural slate. Premium residential segments in the Northeast select this for historic district compatibility.
- Smooth:Uniform granule distribution with sealed surface. Industrial applications prefer this for debris shedding and simplified maintenance protocols.
Matte finishes dominate current volume. Textured profiles gain share fastest as historic preservation incentives expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in Florida's hurricane corridors concentrate stone coated steel roofing demand through tax-advantaged redevelopment incentives. Federal and state programs reward resilient construction in designated distressed areas.
United States
Florida's high-velocity hurricane zones and Texas hail corridors drive replacement demand as insurers mandate Class 4 impact-rated materials for policy renewal. The EPA's ENERGY STAR program and state-level cool roof mandates in California shape product specifications. Miami-Dade County and Houston metropolitan clusters concentrate installer certification networks and distribution warehousing.
Canada
Alberta's extreme temperature cycling and Ontario's ice dam exposure accelerate metal roofing substitution for asphalt in residential retrofit. The National Building Code of Canada and provincial energy efficiency programs establish thermal performance thresholds. Calgary and Toronto sub-markets anchor distribution infrastructure for prairie and Great Lakes construction corridors.
Australia
Bushfire-prone regions in New South Wales and Victoria mandate non-combustible roofing materials under the Australian Building Codes Board standards. Hail belt concentrations around Brisbane drive impact-resistant specification. Sydney and Melbourne metropolitan areas concentrate roofing contractor networks and building material distribution.
New Zealand
Seismic building code requirements and coastal corrosion exposure favor steel roofing over concrete tile in Wellington and Auckland construction markets. The Ministry of Business, Innovation and Employment enforces weathertightness standards for residential envelope systems. Canterbury reconstruction activity sustains demand for resilient roofing materials.
United Kingdom
Heritage conservation area requirements and Part L energy efficiency regulations drive premium roofing substitution in southeast England renovation markets. Historic England guidelines influence material aesthetics for listed building consent. London commuter belt and Home Counties clusters concentrate high-value residential retrofit activity.
Stone Coated Steel Roofing Market Competitive Environment
Top-tier vendors anchor premium-tier certification networks, while mid-scale fabricators compete on regional availability and installer relationships. The vendor base stratifies across proprietary interlocking system developers, backward-integrated granule processors, and brand-licensed distribution specialists. Three archetypes dominate: coastal code specialists controlling wind-uplift certification, integrated manufacturers with captive raw material supply, and brand aggregators leveraging warranty depth for commercial specification. Capacity expansion and factory-authorized contractor programs represent the dominant competitive moves.
Among established system developers, DECRA Roofing Systems, Tilcor Roofing Systems, and Boral Roofing occupy positions spanning proprietary fastening technology, upstream granule sourcing control, and commercial segment brand strength respectively. These entities exemplify the tiered structure where coastal code compliance, raw material integration, and specifier relationships determine competitive positioning.
| Leading Market Players |
|---|
| DECRA Roofing Systems |
| Boral Roofing |
| Tilcor Roofing Systems |
| Roser Co., Ltd. |
| Ross Roof Group |
| Quarrix |
| Hartman Roofing |
| Gerard Roofing |
| Westlake Royal Roofing |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap fabricators with multi-generational ownership structures dominate regional supply clusters, translating patient capital into inventory buffers that stabilize pricing through commodity cycles while insulating against private-equity rollup volatility.
Pricing Analysis
Lead-time-driven pricing creates premium capture for certified stock held in Miami-Dade and Houston distribution centers, while spot inventory in secondary markets trades at discounts due to permitting uncertainty. Three-tier pricing structure across premium, standard, and economy levels separates Florida Product Approval holders from regional fabricators and unbranded imports. Pricing pressure stems from zinc-aluminum alloy volatility on the London Metal Exchange, compressing margins when base metal inventories tighten. Residential retrofit buyers in hail belt counties show lowest price sensitivity due to insurance non-renewal pressure, while agricultural specifiers in Texas and Oklahoma remain most cost-conscious.
Supply Chain Analysis
Galvalume steel substrate supply rests on integrated mills in the United States, South Korea, and Japan, with specialty coating lines concentrated in domestic facilities near coastal demand clusters. Ceramic-coated stone granules draw from three domestic quarries, while acrylic resin formulations source from petrochemical complexes along the Gulf Coast. Single-source vulnerability for premium granule consistency creates supply chain risk when quarry output fluctuates. Distribution runs through factory-authorized contractor networks that bypass traditional roofing supply houses, capturing margin pools previously lost to channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where Florida's wind uplift standards and California's Title 24 codes create a barrier-to-entry moat that rewards certified incumbents while filtering out marginal competitors.
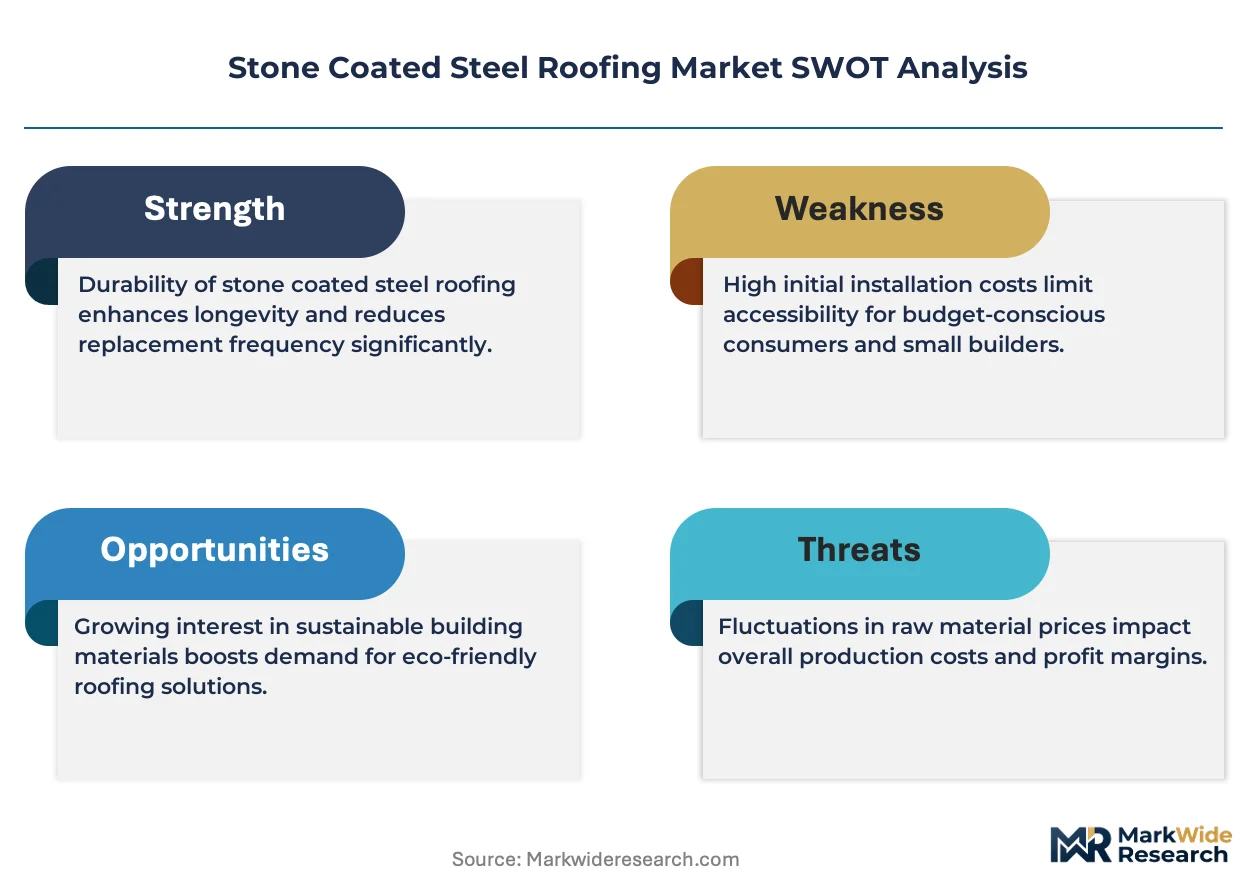
For Market Incumbents: Hedge against zinc-aluminum alloy volatility through long-term offtake agreements with domestic mills, while expanding captive granule processing capacity to reduce single-source quarry dependency. Synthetic composite shingles threaten price-sensitive residential segments, making installer certification network density the priority lever for channel control. For New Entrants and Emerging Players: Begin with underpenetrated Midwestern states where Ohio, Michigan, and Illinois housing stock remains asphalt-dominated despite rising hail severity. Agricultural outbuildings in Texas and Oklahoma offer the most penetrable volume segment due to lower code scrutiny and rodent-resistance purchasing criteria. Factory-authorized contractor recruitment programs provide the essential go-to-market angle for bypassing established distribution relationships. For Investors and Strategic Acquirers: UL 2218 certification timeline compression is the leading indicator that technical regulatory capacity is becoming the scarcest asset in the vendor base. Long-term viability favors backward-integrated manufacturers with captive granule supply and established Florida Product Approval portfolios. Watch for state insurance pool preferred contractor list expansions as the signal that carrier-driven channel consolidation is accelerating.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Granule Processing | Captive supply of ceramic-coated stone reduces dependency on three domestic quarries controlling premium sourcing. |
| Factory-Authorized Contractor Network Expansion | Channel control captures margin pools lost to unqualified crews while satisfying insurance-preferred contractor requirements. |
| Cool Pigment Technology Integration | Infrared-reflective ceramic granules meet California Title 24 and Texas commercial solar-PPA cool roof mandates. |
| Florida Product Approval Portfolio Deepening | High-velocity hurricane zone compliance qualifies products for insurance-mandated retrofit specifications. |
| Midwestern Distribution Infrastructure Buildout | First-mover positioning in Ohio, Michigan, and Illinois as hail severity accelerates asphalt substitution cycles. |
Study Parameters
Multi-period observation of residential re-roofing permit volumes, insurance non-renewal notice filings, and state code amendment trajectories anchored the trend analysis, supplemented by interviews with roofing contractor operations managers, building material distribution executives, municipal code enforcement officers, and insurance carrier risk modeling specialists. Secondary validation drew from ICC code adoption tracking, EPA ENERGY STAR certification databases, Florida Product Approval listings, and ASTM International standard revision records. Bottom-up project pipeline aggregation triangulated against top-down construction spending forecasts.
Input-output matrices modeled demand drivers across product type, application, installation method, and finish specifications, with volume and value outputs reconciled through cross-segment elasticity checks. CAGRs were derived from regression-based trend extrapolation moderated by regulatory adoption curve assumptions. Forecast inputs included housing stock age profiles, insurance industry risk model evolution, and state energy code amendment calendars.
Underlying measurement precision varies by segment; residential retrofit volumes carry tighter precision than agricultural applications due to more consistent permitting documentation. Forecasts reflect documented assumptions about code adoption timelines and carrier underwriting criteria evolution. Metal price volatility, quarry output disruption, and synthetic composite substitution acceleration warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Iron and Steel Slag Market
Building Materials
Europe Fireproof Cladding Market
Building Materials
Steel Products Market
Building Materials
Fiber Cement Market
Building Materials
Roof Cover Boards Market
Building Materials
Global Drywall and Building Plaster Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
Concrete and Cement Market
Building Materials
South Africa White Cement Market
Building Materials
Natural Stone Market
Building Materials
Asia-Pacific Aluminum Door and Window Market
Building Materials
China Architectural Coatings Market
Building Materials
Asia-Pacific Shotcrete Market
Building Materials
Asia-Pacific White Cement Market
Building Materials
Africa Aluminum Door and Window Market
Building Materials
Exterior Doors Market