
 LAMEA Engineered Stone Market | 2026-2036
LAMEA Engineered Stone Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Engineered Stone Market Insights
Luxury hospitality developers is reorganizing procurement priorities across the LAMEA engineered stone channel, shifting volume toward large-format slabs with extended warranty terms. Caesarstone Ltd. leverages its Israeli manufacturing base to supply Gulf project pipelines with consistent lead times. Cosentino S.A. anchors its LAMEA position through direct distribution hubs in São Paulo and Dubai. VICOSTONE competes on technical quartz purity grades that meet emerging silica-content thresholds.
Engineered stone comprises crushed natural minerals bound with polymer resins under vacuum vibration compression, yielding slabs with controlled porosity below 0.05 percent and flexural strength exceeding 25 MPa for high-traffic surfacing applications. Quartz dominates product type value generation due to its stain resistance and color consistency, while solid surface segments capture renovation-driven replacement cycles where seamless integration matters. The hospitality end user commands premium margin pools across countertop and wall cladding applications, whereas residential flooring segments operate on thinner spreads through distributor channels.
Brazil's ANVISA silica monitoring protocols and South Africa's NRCS occupational exposure standards are tightening resin-content disclosures and pushing manufacturers toward alternative binder chemistries. Saudi Arabia's SFDA building material certifications now require imported engineered stone to demonstrate thermal shock resistance under Gulf climate conditions. Stakeholders must track how these evolving compliance layers reshape supplier qualification costs and regional sourcing decisions.
Market Dynamics
Silica exposure regulations across Brazil and South Africa are compressing resin-content tolerances and forcing reformulation investments that reshape competitive cost structures in the LAMEA engineered stone channel.
Growth Catalysts
- ANVISA Silica Monitoring Protocols:Brazil's pharmaceutical regulator mandates workplace exposure documentation that accelerates low-resin product certification timelines for domestic manufacturers.
- Luxury Hospitality Specification Upgrades:Developers in Dubai and Riyadh are mandating extended warranty terms and large-format slab dimensions for premium countertop installations.
- São Paulo Residential Tower Construction:Brazil's most populous state concentrates demand for premium surfacing volumes across high-rise residential developments.
Market Restraints
- Petrochemical Resin Volatility:Unsaturated polyester and epoxy resin feedstock costs fluctuate with crude oil derivatives, compressing margin predictability for slab producers.
- Quartz Supply Concentration:High-purity silica sand deposits cluster in specific Brazilian mining jurisdictions, creating geographic dependency risk for quality-grade raw material.
- Solid Surface Substitution Threat:Acrylic-based solid surface materials capture renovation-driven replacement cycles where seamless thermoforming integration matters more than hardness.
Strategic Opportunities
- Alternative Binder Chemistry Development:Bio-based resin formulations and geopolymer binders offer pathways to preempt tightening silica-content thresholds in South African NRCS standards.
- SFDA Thermal Shock Certification:Saudi Arabia's food and drug authority now requires imported engineered stone to demonstrate Gulf climate resilience, creating qualification barriers for non-compliant exporters.
- Direct Distribution Hub Expansion:São Paulo and Dubai logistics centers enable project-scale slab fulfillment with reduced lead time variability for hospitality developers.
Industry Challenges
- Occupational Health Compliance Talent Scarcity:Industrial hygienists with engineered stone-specific silica monitoring expertise remain concentrated in São Paulo and Johannesburg, limiting facility expansion in secondary Brazilian states.
- Low-Resin Formulation R&D Capex Burden:Vacuum vibration compression equipment modifications and binder chemistry pilot programs require capital deployment ahead of regulatory mandate certainty.
- Cross-Border Certification Timeline Compression:Simultaneous ANVISA, NRCS, and SFDA approval processes create documentation bottlenecks for multi-territory project bids.
Report Scope
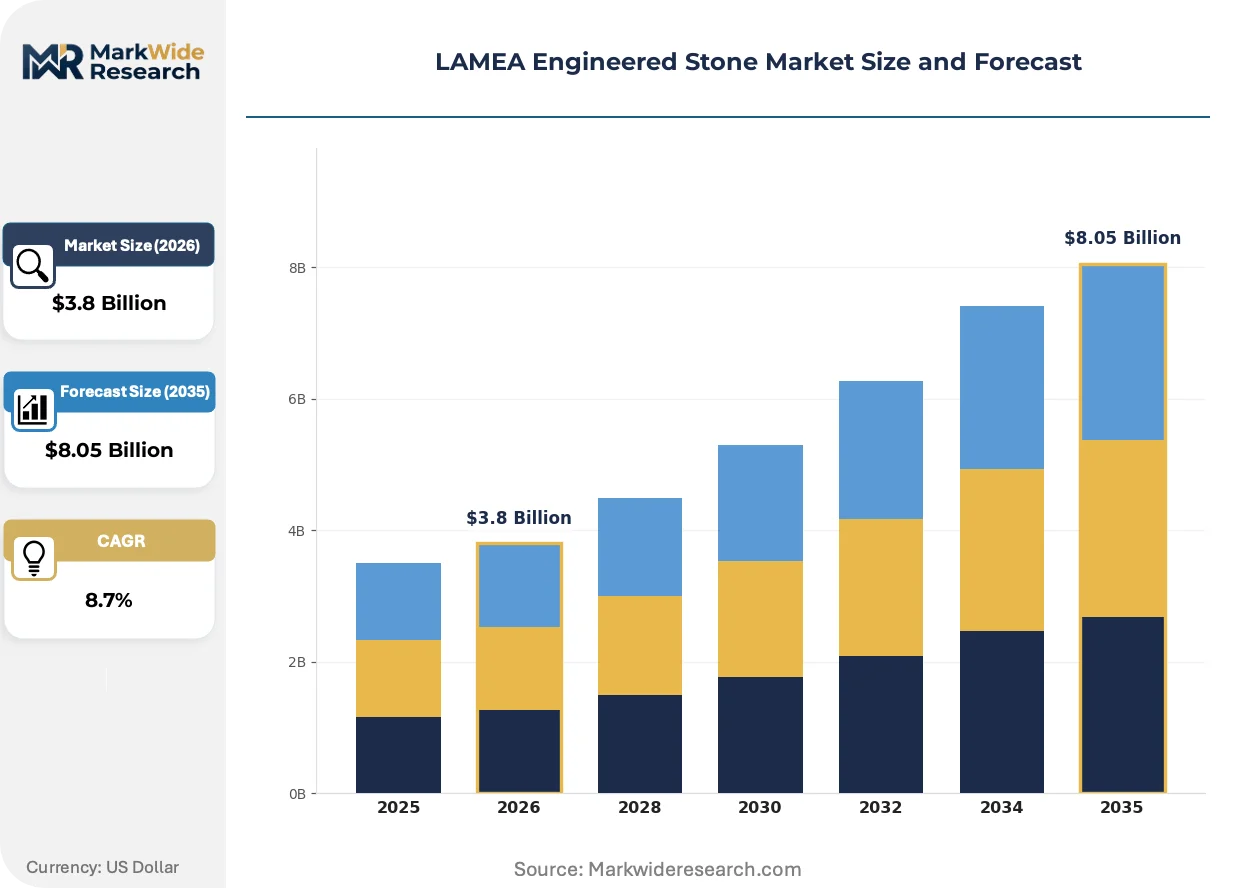
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Engineered Stone Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quartz, Marble, Granite, Solid Surface Application: Countertops, Flooring, Wall Cladding, Sinks End User: Residential, Commercial, Hospitality, Healthcare Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Cosentino S.A., Caesarstone Ltd., LX Hausys, VICOSTONE, Technistone s.r.o, Belenco, Stone Italiana S.P.A., Quartzforms, A.St.A. WORLD-WIDE, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Engineered Stone Market Trends and Innovations
Formulation chemistry and procurement architecture are converging to redefine competitive advantage in LAMEA engineered stone, with regulatory compliance and project-scale logistics now inseparable from product specification.
Ultra-thin large-format slab technology is miniaturizing material thickness below 12mm while preserving flexural strength above 25 MPa through optimized particle packing algorithms. Hospitality developers in Dubai specify these profiles for vertical wall cladding applications where weight reduction enables structural cost savings. The technology is miniaturizing installation labor requirements and expanding addressable surface area per quarry-equivalent raw material extraction.
South Africa's NRCS occupational exposure standards and Brazil's ANVISA silica monitoring protocols are tightening in parallel, creating a dual-jurisdiction compliance floor that favors manufacturers with integrated industrial hygiene documentation systems. Resin-content disclosure requirements now extend to imported slab certifications, raising supplier qualification costs for distributors serving both markets. Low-resin quartz formulations with polymer content below 7 percent capture preferential specification status in healthcare and food-service end uses.
Project-direct procurement models are consolidating volume commitments from luxury hospitality developers in Riyadh and Dubai, bypassing traditional distributor markups for developments exceeding 500 units. General contractors now negotiate slab supply agreements directly with manufacturers, compressing specification cycles from 16 weeks to 8 weeks for flagship properties. This channel compression is most visible in Gulf Cooperation Council hospitality developments where developer balance sheet strength enables upfront material financing.
LAMEA Engineered Stone Market Segmentation
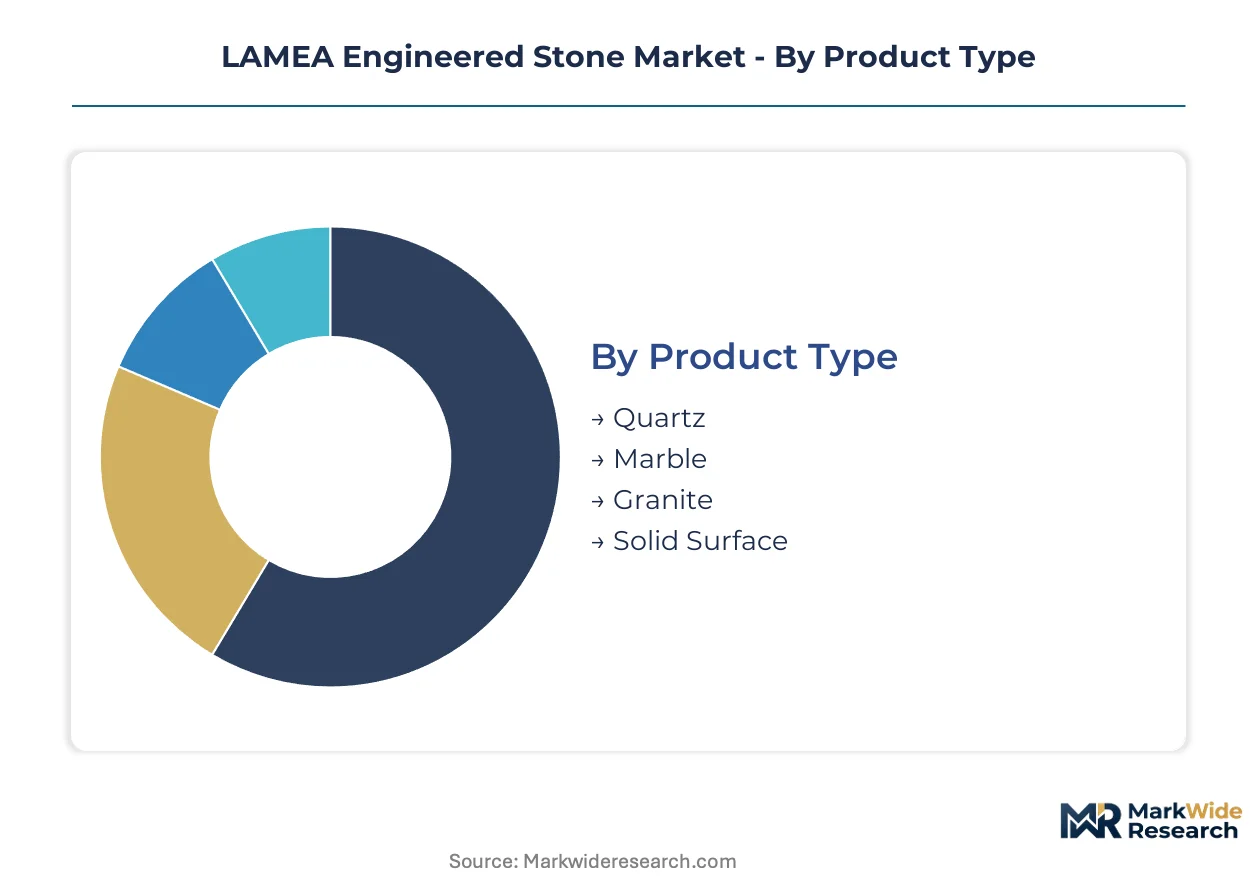
Engineered stone demand across Latin America, Middle East, and Africa fragments along material chemistry, installation application, and procurement channel dimensions. Each segmentation axis carries distinct margin profiles and regulatory exposure that reshape supplier positioning.
Product Type:
Quartz and solid surface formulations dominate export-led shipments to Gulf hospitality projects, while marble and granite variants serve price-sensitive domestic renovation cycles in Brazil and South Africa.
- Quartz:Crushed silica sand bound with unsaturated polyester resin under vacuum vibration compression yields slabs with sub-0.05 percent porosity. Dubai and Riyadh luxury developers specify quartz for large-format countertop installations requiring extended warranty coverage and thermal shock resistance under Gulf climate conditions.
- Solid Surface:Acrylic-based thermoformable material enables seamless integration across curved reception desks and healthcare casework. São Paulo residential renovation contractors favor solid surface for replacement cycles where installation speed matters more than surface hardness.
- Marble:Engineered marble combines calcium carbonate filler with resin binders for cost-competitive flooring in Brazilian mid-rise residential towers.
- Granite:Resin-enhanced granite slabs target South African commercial flooring segments where abrasion resistance trumps color consistency requirements.
Quartz holds the largest share; momentum sits with solid surface as healthcare and food-service end uses accelerate low-resin specification adoption.
Application:
Countertop and wall cladding installations command premium pricing through project-direct procurement, while flooring and sink applications flow through distributor networks with compressed margins.
- Countertops:Horizontal surfacing in kitchens and bathrooms represents the highest value-per-square-meter application. Hospitality developers in Dubai negotiate direct manufacturer agreements for developments exceeding 500 units, compressing specification cycles from 16 weeks to 8 weeks.
- Wall Cladding:Ultra-thin large-format slabs below 12mm thickness enable vertical installations with reduced structural load. Riyadh luxury hotel projects specify these profiles for lobby and elevator bank finishes where weight reduction drives material cost savings.
- Flooring:High-traffic commercial installations in São Paulo retail centers absorb volume through distributor channels operating on thinner spreads.
- Sinks:Integrated basin fabrication targets residential replacement markets in South African urban centers.
Countertops generate the highest absolute margin; wall cladding is expanding most quickly as Gulf hospitality construction accelerates large-format specification.
End User:
Residential demand concentrates in São Paulo state high-rise construction, while hospitality and healthcare segments drive premium product mix across Middle East import markets.
- Residential:Brazil's São Paulo state absorbs premium countertop volumes through high-rise tower developments. ANVISA silica monitoring protocols push developers toward low-resin quartz certifications for multi-unit projects.
- Hospitality:Luxury hotel developers in Dubai and Riyadh mandate large-format slabs with extended warranty terms. SFDA thermal shock certification requirements now filter supplier qualification for imported material.
- Commercial:Office and retail fit-outs in Johannesburg and Cape Town operate through distributor channels with standardized specification.
- Healthcare:South African NRCS occupational exposure standards favor low-resin formulations for hospital renovation projects where indoor air quality protocols apply.
Residential holds the largest share; hospitality carries the steepest expansion trajectory as Gulf project pipelines mature.
Distribution Channel:
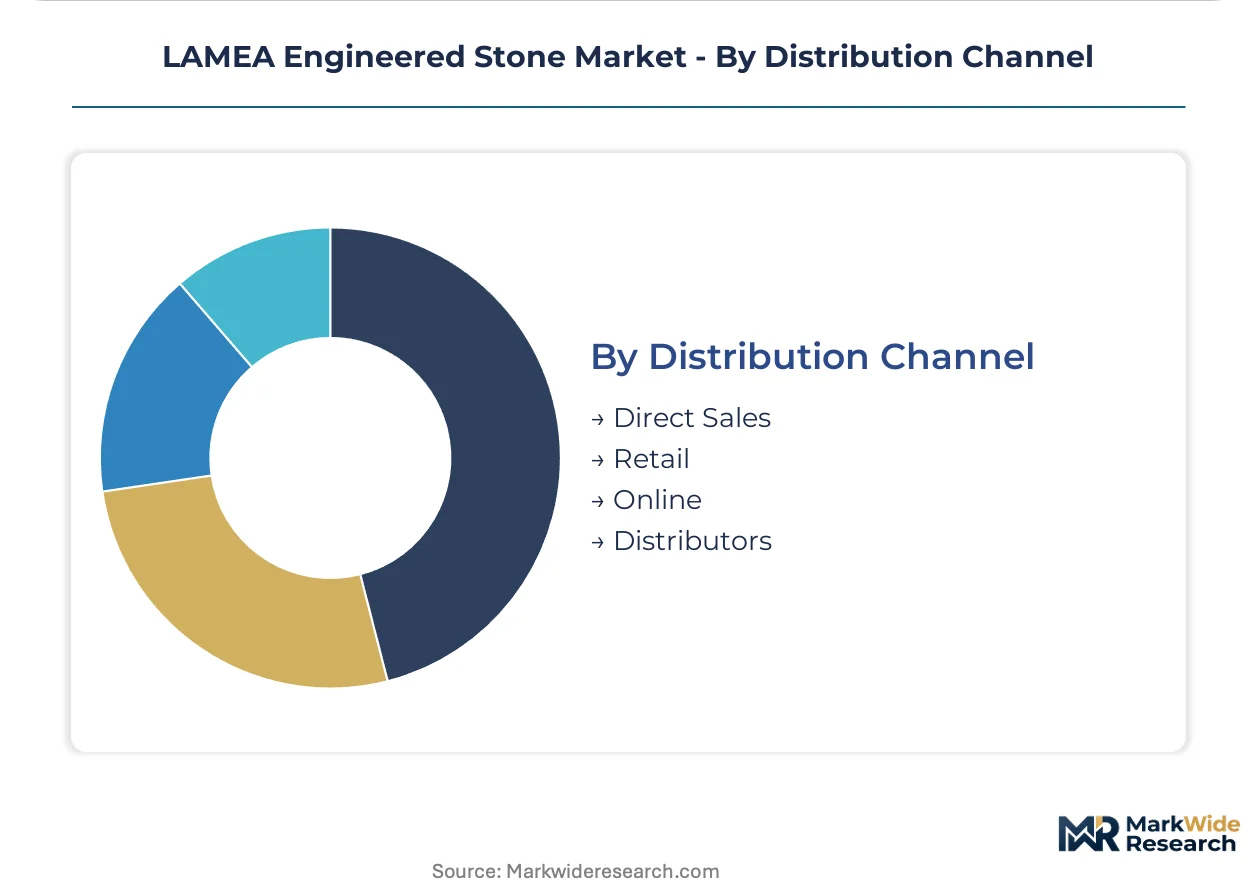
Direct sales models capture volume from large-scale hospitality developers, while retail and distributor channels serve fragmented residential renovation demand.
- Direct Sales:Manufacturer-to-contractor agreements bypass traditional markups for project-scale slab fulfillment. Dubai and São Paulo logistics centers enable reduced lead time variability for developments with upfront material financing.
- Distributors:Regional inventory positioning serves secondary Brazilian states and South African provinces where project scale does not justify direct procurement.
- Retail:Showroom-based selection supports residential renovation decisions in urban centers with established surfacing trade infrastructure.
- Online:Digital specification tools gain traction for standard colorway selection in repeat commercial fit-out programs.
Direct sales commands the highest value concentration; distributor networks retain volume dominance across geographically dispersed markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quartz slab manufacturing concentrates in Brazilian mining jurisdictions and Israeli coastal plants, with Gulf logistics hubs mediating access to Dubai and Riyadh project pipelines. ANVISA silica protocols and South Africa's NRCS standards now filter supplier qualification across four distinct national markets.
Brazil
São Paulo state absorbs premium countertop volumes through high-rise residential tower construction. ANVISA mandates workplace exposure documentation that accelerates low-resin product certification timelines for domestic manufacturers. Minas Gerais mining jurisdictions supply high-purity silica sand to engineered stone plants clustered around São Paulo's industrial periphery.
Saudi Arabia
Riyadh luxury hospitality developers mandate large-format slabs with extended warranty terms for flagship properties. SFDA building material certifications require imported engineered stone to demonstrate thermal shock resistance under Gulf climate conditions. Eastern Province petrochemical complexes supply unsaturated polyester resin feedstock to regional slab producers.
United Arab Emirates
Dubai's hospitality construction pipeline drives specification upgrades for quartz surfaces across countertop and wall cladding applications. MOHAP indoor air quality protocols intersect with SFDA import requirements to create dual compliance thresholds for hotel fit-out materials. Jebel Ali logistics hubs enable reduced lead times for project-scale slab fulfillment.
South Africa
Johannesburg and Cape Town commercial flooring segments absorb volume through distributor channels with standardized specification. NRCS occupational exposure standards enforce silica limits that favor low-resin formulations in healthcare renovation projects. Gauteng province concentrates industrial hygienist expertise for engineered stone-specific compliance documentation.
Israel
Coastal manufacturing facilities supply Gulf project pipelines with consistent lead times for quartz slab exports. Israeli producers leverage geographic proximity to Dubai and Riyadh developers to compress specification cycles. Central district plants serve as alternative sourcing nodes when Brazilian supply faces ANVISA certification delays.
LAMEA Engineered Stone Market Competitive Landscape
Concentration sits with vertically integrated quartz specialists and regional distribution architects. The vendor base separates into three strategic tiers: resin-formulation innovators, project-direct logistics operators, and price-competitive solid surface fabricators. M&A activity targets captive quartz mining access, while capacity expansion concentrates in Brazilian and Israeli coastal zones with Gulf-facing export infrastructure.
Among Israeli and Spanish producers, Caesarstone Ltd. and Cosentino S.A. exemplify the logistics-integrated archetype with direct distribution presence in São Paulo and Dubai. VICOSTONE occupies a position within the technical-purity tier, representing manufacturers competing on silica-content thresholds. These three companies anchor the competitive structure through distinct geographic and specification vectors rather than overlapping market positions.
| Leading Market Players |
|---|
| Cosentino S.A. |
| Caesarstone Ltd. |
| LX Hausys |
| VICOSTONE |
| Technistone s.r.o |
| Belenco |
| Stone Italiana S.P.A. |
| Quartzforms |
| A.St.A. WORLD-WIDE |
| Others |
Pricing and Supply Chain Analysis
Low-resin formulation substitution is compressing raw material procurement geography toward Minas Gerais silica deposits and Israeli coastal manufacturing zones, simultaneously elevating certification-premium slabs above commodity-grade pricing bands across Gulf hospitality specifications.
Pricing Analysis
ANVISA silica monitoring protocols dictate the pricing tier structure across Brazilian domestic supply, separating low-resin certified slabs from standard formulations. Price differentiation rests on resin-content disclosure grade and thermal shock certification level under SFDA import requirements. Cost compression in economy-tier solid surface segments is intensifying because petrochemical resin feedstock volatility feeds through unsaturated polyester input costs. Residential renovation contractors in São Paulo secondary markets exhibit highest price sensitivity, while Dubai luxury hospitality developers absorb premium markups for extended warranty coverage.
Supply Chain Analysis
Jebel Ali port transit underwrites Gulf-facing logistics economics for quartz slab imports from Brazilian and Israeli production nodes. Geographic supply concentrates in Minas Gerais mining jurisdictions, Israel's central district coastal plants, and São Paulo industrial periphery fabrication clusters. Raw material dependencies draw from high-purity silica sand deposits, unsaturated polyester resin from Eastern Province petrochemical complexes, and epoxy binder chemistries. Single-source vulnerability sits with concentrated industrial hygienist expertise for ANVISA compliance documentation. Distribution runs through project-direct manufacturer agreements for hospitality developments exceeding 500 units, supplemented by São Paulo and Dubai hub inventory positioning for fragmented residential demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LAMEA engineered stone market is recovering from regulatory-induced formulation transition costs, with hospitality construction cyclicality in Dubai and Riyadh driving volume normalization ahead of residential tower completions in São Paulo state.
For Market Incumbents: Consolidate captive silica mining access in Minas Gerais through lease extensions or joint venture structures with existing quarry operators. Deepen backward integration into low-resin binder chemistry R&D to preempt NRCS occupational exposure threshold tightening in South African healthcare specifications. Channel control through São Paulo and Dubai logistics hub expansion defends margin position against distributor disintermediation threats from project-direct procurement models. For New Entrants and Emerging Players: Differentiate on ultra-thin large-format slab technology below 12mm thickness for vertical wall cladding applications where weight reduction commands structural cost savings. Target South African healthcare renovation segments where NRCS low-resin formulation preferences create specification white space against incumbent quartz purity positioning. Go-to-market leverage through direct contractor relationships in Johannesburg and Cape Town commercial flooring channels bypasses established distributor gatekeeping. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Israeli coastal manufacturers holding Gulf-facing export infrastructure and SFDA thermal shock certification portfolios. Long-term viability across a 5-10 year window hinges on regulatory compliance scalability rather than volume scale alone. Acquisition screening should prioritize integrated industrial hygiene documentation systems capable of simultaneous ANVISA, NRCS, and SFDA approval navigation. The signal to monitor is cross-border certification timeline compression for multi-territory project bids.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Binder Chemistry Development | Bio-based resin formulations preempt tightening silica-content thresholds in South African NRCS standards. |
| Direct Distribution Hub Expansion | São Paulo and Dubai logistics centers reduce lead time variability for project-scale slab fulfillment. |
| Ultra-Thin Large-Format Slab Scale-Up | Sub-12mm thickness profiles enable vertical wall cladding weight savings for Riyadh luxury hotel specifications. |
| Integrated Compliance Documentation Systems | ANVISA, NRCS, and SFDA parallel approval capabilities filter supplier qualification for multi-territory bids. |
| Captive Silica Mining Access Consolidation | Minas Gerais quarry control secures high-purity raw material supply against geographic concentration risk. |
Research Methodology
Cross-validation between primary interviews with plant managers, procurement leads at Gulf hospitality developers, distribution channel partners, and technical R&D directors anchors the qualitative findings. Secondary validation draws from ANVISA regulatory filings, SFDA building material certification databases, Brazilian customs and trade data, and SEC 10-K disclosures from publicly listed engineered stone manufacturers. Bottom-up volume modeling across product type, application, end user, and distribution channel segments triangulates against top-down macroeconomic indicators for the LAMEA region.
Sensitivity analysis around resin-content threshold scenarios and petrochemical feedstock price volatility informs the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry grade, installation application, end-user industry, and procurement channel structure. CAGRs were derived from regression-based trend extrapolation calibrated to construction pipeline data and regulatory implementation timelines. Industry-specific forecast inputs incorporate hospitality development permit flows in Dubai and Riyadh, plus São Paulo state high-rise residential tower completion schedules.
Material uncertainties — ANVISA silica monitoring protocol enforcement intensity, NRCS occupational exposure standard revision timing, and SFDA thermal shock certification scope expansion — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory compliance cost pass-through rates and hospitality developer balance sheet capacity for upfront material financing. Practitioners should keep alternative scenarios live as cross-border certification timeline compression and alternative binder chemistry commercialization trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Global Builders Joinery and Carpentry of Wood Market
Building Materials
US Facade Market
Building Materials
Thermoplastic Composite Exterior Clips and Brackets Market
Building Materials
Sanded Grout Market
Building Materials
Malaysia Architectural Coatings Market
Building Materials
Foam Concrete Market
Building Materials
Asia-Pacific Kinetic Tiles Market
Building Materials
Europe Fireproof Cladding Market
Building Materials
US Cement Tiles Market
Building Materials
GCC Concealed Cistern Market
Building Materials
Cribbing Blocks Market
Building Materials
Construction Coatings Market
Building Materials
India Aluminum Door and Window Market
Building Materials
Exterior Doors Market
Building Materials
China Architectural Coatings Market
Building Materials
North America Dry-Mix Mortar Market