
 Middle East and Africa Floor Coatings Market | 2026-2036
Middle East and Africa Floor Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Floor Coatings Market Outlook
Water-based polyurethane dispersion chemistry is reconfiguring how manufacturers balance VOC compliance with abrasion resistance in high-traffic installations. Akzo Nobel NV leverages its European R&D base to transfer low-emission formulations into Middle Eastern distribution networks. Jotun anchors its position through marine-grade coating expertise adapted to aggressive chemical environments in Saudi petrochemical facilities. Sika AG extends its construction chemicals footprint by integrating floor systems with waterproofing and joint-sealing portfolios across African infrastructure projects.
Middle East and Africa floor coatings comprise resin-based protective layers applied to concrete, wood, or metal substrates, typically formulated at two to six millimeters dry-film thickness to resist mechanical wear, chemical spillage, and thermal cycling in industrial settings. Epoxy formulations dominate commercial and industrial specification due to their hardness and cost efficiency, while polyaspartic technology captures premium maintenance-provider segments demanding rapid return-to-service intervals. Water-based technology gains share among builders and contractors facing tightening VOC limits in UAE and South African metropolitan jurisdictions, though solvent-based systems retain volume in heavy-duty automotive and manufacturing floors where chemical resistance thresholds remain stringent.
SASO in Saudi Arabia and SABS in South Africa enforce divergent compliance pathways that fragment formulation strategies for suppliers operating across both markets. The EU Green Deal's extraterritorial influence through CE-marked import requirements shapes product development priorities for European-originated multinationals serving North African trade corridors. Stakeholders must monitor how diverging national building codes and carbon-border adjustment mechanisms reshape regional supply chain configurations and local manufacturing investments.
Market Dynamics
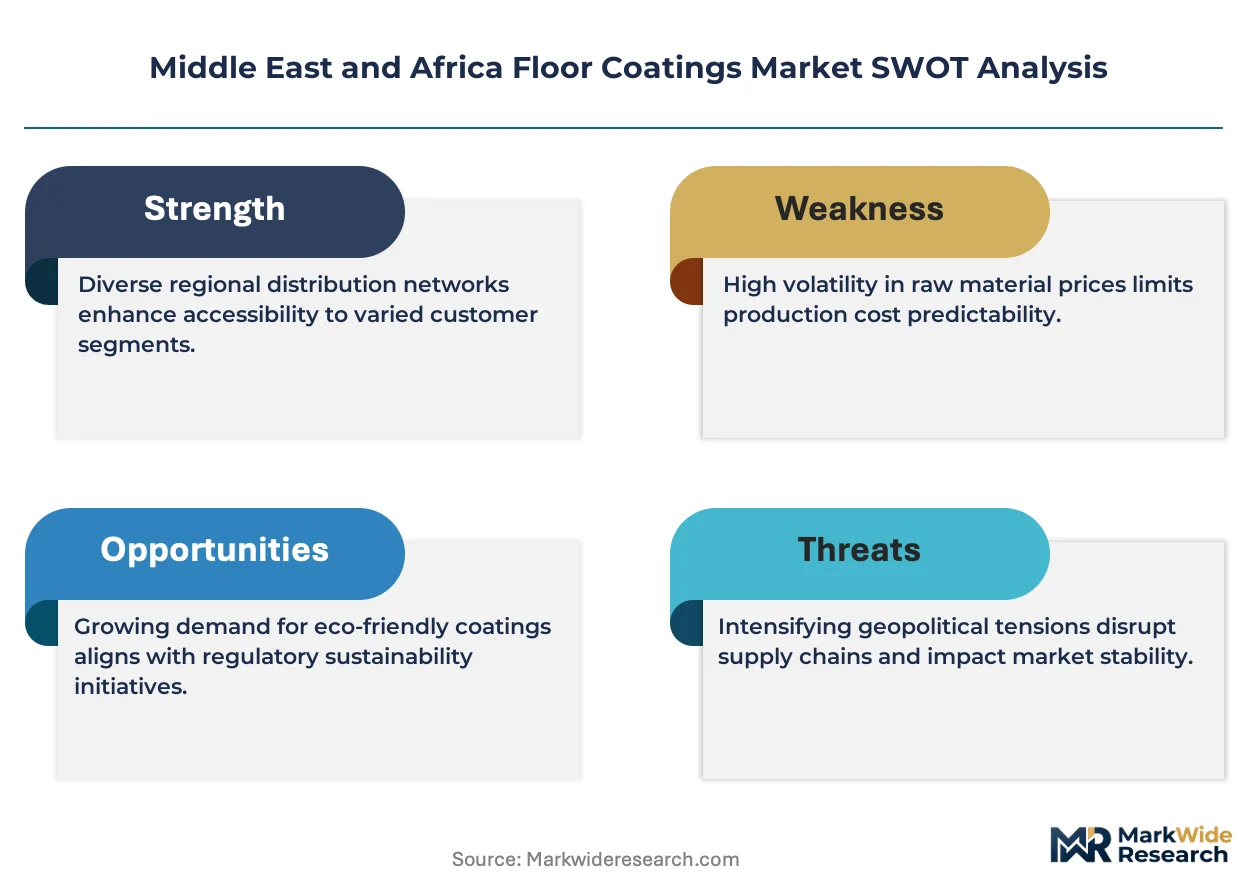
SASO building efficiency mandates and SABS durability standards are fragmenting formulation strategies, forcing suppliers to maintain parallel compliance pathways across Gulf and Southern African markets. This regulatory divergence concentrates investment in regional manufacturing capacity.
Growth Catalysts
- Epoxy formulation hardness:Industrial facility construction across Gulf Cooperation Council nations specifies high-performance epoxy systems for mechanical wear resistance in manufacturing floors.
- SASO mandates:Saudi Arabia's building efficiency regulations tighten product compliance thresholds, accelerating specification of certified coating systems in commercial construction.
- Polyaspartic rapid return-to-service:Maintenance providers in premium segments demand shortened installation windows, driving uptake of fast-curing technology in logistics corridors.
Market Restraints
- Solvent-based input volatility:Petrochemical feedstock price swings compress margins for manufacturers supplying heavy-duty automotive floors where chemical resistance thresholds remain stringent.
- European supply concentration:CE-marked import requirements from EU-originated multinationals limit local formulation flexibility in North African trade corridors.
- Water-based performance ceiling:VOC-compliant aqueous systems face technical limitations in thermal cycling resistance compared to solvent-borne alternatives in petrochemical environments.
Strategic Opportunities
- Nigerian infrastructure gap:Underpenetrated West African construction markets present white space for integrated floor-waterproofing-joint sealing system portfolios.
- UAE logistics corridor expansion:Dubai's Jebel Ali Free Zone growth drives specification demand for solvent-resistant industrial systems in warehousing applications.
- Carbon-border adjustment positioning:EU Green Deal extraterritorial mechanisms create competitive advantage for suppliers with verified low-emission formulations entering North African markets.
Industry Challenges
- Applicator certification timelines:Divergent national building codes require specialized training programs, extending workforce readiness periods in multi-country operations.
- Legacy substrate integration:Existing concrete floors demand extensive surface preparation protocols, complicating retrofit project execution and cost estimation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Floor Coatings Market |
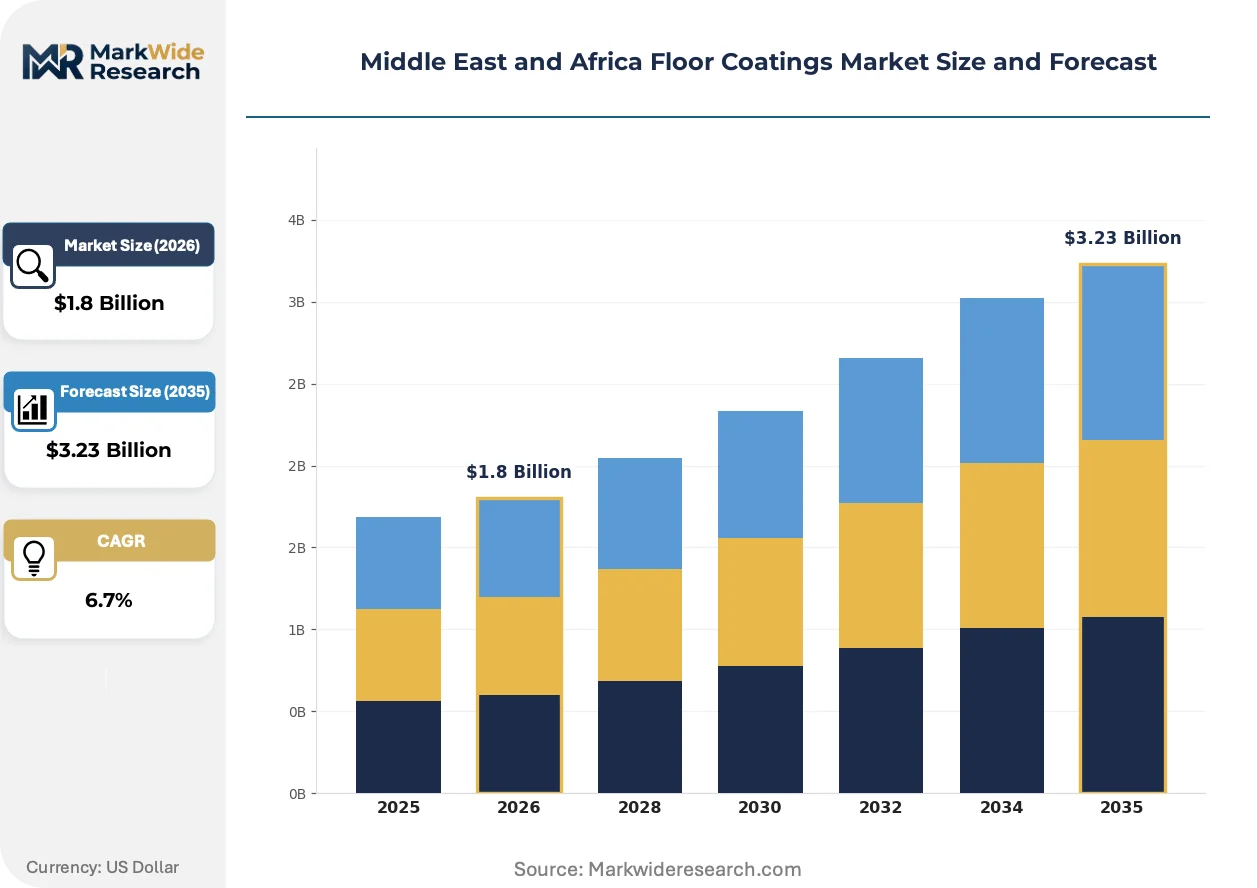
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Polyurethane, Polyaspartic Application: Residential, Commercial, Industrial, Automotive Technology: Water-Based, Solvent-Based, UV-Curable, Powder Coating End User: Builders, Contractors, DIY Users, Maintenance Providers |
| Companies Covered | Akzo Nobel NV, Jotun, PPG Industries Inc., Sika AG, Asian Paints, The Sherwin-Williams Company, BASF SE, Jazeera Paints, National Paints Factories Co. Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Floor Coatings Market Strategic Shifts
Water-based polyurethane dispersion chemistry is reconfiguring manufacturer calculations around VOC compliance and abrasion resistance trade-offs. Formulation priorities now center on aqueous systems that match solvent-borne performance in high-traffic installations.
Polyaspartic technology is collapsing the traditional cure-time barrier that separated premium maintenance contracts from standard industrial specifications. Facility managers in Saudi petrochemical complexes now specify rapid return-to-service systems that enable 24-hour operational continuity. This compression is eliminating the historical price-performance gap between fast-cure and conventional epoxy alternatives.
SASO efficiency mandates and SABS durability standards are diverging compliance pathways that fragment regional formulation strategies. Suppliers operating across both markets must maintain parallel certification tracks, raising fixed compliance costs. European-originated multinationals serving North African corridors face additional CE-marked import requirements that reshape local manufacturing investment priorities.
Maintenance providers are unbundling after-sales service contracts from initial material supply, creating discrete revenue streams for specialized applicator networks. This disintermediation concentrates specification influence with certified installation crews rather than distributor sales channels. The shift is most visible in South Africa's metropolitan jurisdictions where SABS-certified contractors capture premium project margins through performance-guaranteed application protocols.
Middle East and Africa Floor Coatings Market Segmentation
Floor coatings in the Middle East and Africa fragment across four intersecting dimensions that determine specification logic. Product chemistry dictates performance ceilings in Saudi petrochemical corridors. Application context shapes compliance requirements under SASO and SABS frameworks.
Product Type:
Mature epoxy formulations coexist with emerging polyaspartic alternatives across divergent price-performance tiers.
- Epoxy:Two-part thermosetting systems built from bisphenol-A and amine hardeners deliver compressive strength exceeding 10,000 psi. GCC manufacturing floors specify these for mechanical wear resistance under heavy forklift traffic in Jebel Ali warehousing clusters. Saudi Arabia's SASO efficiency mandates accelerate certified epoxy specification in commercial construction.
- Polyurethane:Aliphatic and aromatic isocyanate-cured films provide superior UV stability and flexibility for exterior concrete decks. South African SABS durability standards tighten compliance thresholds for polyurethane gloss retention in Cape Town coastal installations. Water-based dispersion chemistry now matches solvent-borne abrasion resistance in high-traffic retail environments.
- Acrylic:Thermoplastic emulsions offer rapid drying and re-coat windows for light-duty residential garages across UAE villa developments.
- Polyaspartic:Polyurea-derived rapid-cure technology collapses return-to-service intervals to four hours, capturing premium maintenance contracts in Saudi petrochemical complexes.
Epoxy retains volume leadership; polyaspartic holds the steepest expansion curve.
Application:
Cost tiers separate specification authority between owner-operators and facility managers.
- Industrial:Heavy-duty systems at 4-6 mm dry-film thickness resist thermal cycling and chemical spillage in Saudi Aramco processing facilities. Solvent-resistant formulations dominate despite tightening VOC limits.
- Commercial:Decorative flake and metallic systems balance aesthetics with slip resistance in Dubai retail and hospitality fit-outs. Water-based technology gains share under UAE municipal emission controls.
- Automotive:Chemical-resistant epoxy and polyurethane hybrids withstand brake fluid and lubricant exposure in Johannesburg assembly plants and Casablanca repair bays.
- Residential:DIY-friendly water-based acrylics and single-part epoxies penetrate Gulf Cooperation Council villa garage segments through hardware retail channels.
Industrial applications command the highest system value per square meter; commercial flooring expands most quickly under metropolitan construction booms.
Technology:
Customer type determines whether compliance or performance dominates formulation selection.
- Solvent-Based:High-solids epoxy and polyurethane systems retain specification in heavy-duty automotive and petrochemical floors where chemical resistance thresholds remain non-negotiable. Feedstock price volatility compresses manufacturer margins.
- Water-Based:Aqueous polyurethane dispersions and epoxy emulsions satisfy SASO and SABS VOC limits in Riyadh and Johannesburg metropolitan jurisdictions. Technical limitations in thermal cycling resistance constrain penetration in process environments.
- UV-Curable:Acrylate oligomer systems enable instant cure for thin-film wood and vinyl flooring applications in high-end UAE commercial interiors.
- Powder Coating:Thermoset epoxy and hybrid powders serve conductive and anti-static requirements in electronics manufacturing facilities across Morocco and Tunisia.
Solvent-based technology retains volume leadership; water-based formulations climb the fastest under regulatory pressure.
End User:
Supply concentration varies across specification influence nodes.
- Builders:Large-scale contractors in UAE logistics corridor developments specify integrated floor-waterproofing systems from Sika and similar construction chemical portfolios.
- Maintenance Providers:Specialized applicator networks unbundle after-sales service contracts, capturing premium margins through SABS-certified performance guarantees in South African metropolitan markets.
- Contractors:Mid-tier installation firms face extended certification timelines under divergent national building codes across multi-country operations.
- DIY Users:Retail-channel purchasers in Gulf Cooperation Council residential markets drive volume for water-based acrylic and single-part epoxy convenience formulations.
Builders retain volume leadership; maintenance providers hold the steepest expansion curve as service unbundling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE exports solvent-resistant industrial floor systems to Saudi petrochemical buyers through integrated logistics corridors, while South African distributors serve SADC infrastructure projects under divergent compliance frameworks.
United Arab Emirates
Dubai's Jebel Ali Free Zone expansion and Abu Dhabi's KIZAD industrial city drive specification of high-performance epoxy systems in warehousing clusters. MOHAP oversees VOC emission protocols for commercial construction in metropolitan jurisdictions. Ras Al Khaimah's ceramics manufacturing belt demands chemical-resistant polyurethane hybrids for heavy-duty process floors.
Saudi Arabia
SASO building efficiency mandates accelerate certified coating specification across Riyadh's commercial construction boom and Dammam's industrial corridor. The Saudi Building Code enforces durability thresholds for public infrastructure projects. NEOM's northwest development zone specifies rapid-cure polyaspartic systems to compress installation windows in mega-project timelines.
South Africa
SABS durability standards tighten compliance for polyurethane gloss retention in Cape Town coastal installations and Johannesburg automotive assembly plants. The National Building Regulations govern substrate preparation protocols in retrofit markets. Durban's container terminal expansion specifies solvent-resistant epoxy systems for heavy forklift traffic zones.
Nigeria
Lagos port modernization and Abuja federal capital construction create white space for integrated floor-waterproofing system portfolios. The country's national standards body enforces import quality certification for construction chemical products. Kano's textile manufacturing belt presents underpenetrated demand for industrial-grade epoxy formulations in process environments.
Egypt
Suez Canal Economic Zone industrialization and Cairo metropolitan commercial construction specify imported CE-marked coating systems. The Egyptian Organization for Standardization and Quality regulates building material compliance thresholds. Alexandria's petrochemical complex demands thermal cycling-resistant formulations for aggressive process floor environments.
Middle East and Africa Floor Coatings Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented national compliance environments. Construction chemical conglomerates leverage integrated waterproofing-joint sealing portfolios to capture specification authority in large-scale infrastructure tenders. Specialist coating manufacturers anchor positions through marine-grade expertise and rapid-cure technology platforms. Dominant competitive moves include regional manufacturing investments to bypass import certification barriers and applicator certification program expansion to secure maintenance contract flows.
Within the European-originated multinational tier, Akzo Nobel NV and Sika AG exemplify archetypes leveraging R&D transfer and construction chemical integration respectively. Jotun occupies a position representing marine-grade expertise adapted to aggressive industrial environments. These three entities anchor competitive positioning through divergent technology platforms and distribution network configurations across Gulf and African markets.
| Leading Market Players |
|---|
| Akzo Nobel NV |
| Jotun |
| PPG Industries Inc. |
| Sika AG |
| Asian Paints |
| The Sherwin-Williams Company |
| BASF SE |
| Jazeera Paints |
| National Paints Factories Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Jebel Ali's warehousing cluster concentration shapes downstream pricing power across Gulf logistics corridors, as UAE-based distributors leverage solvent-resistant epoxy inventory positions to command premium placement in Saudi petrochemical procurement cycles. This geographic supply anchoring compresses margin flexibility for European-originated multinationals facing CE-marked import compliance costs.
Pricing Analysis
Current-generation water-based polyurethane dispersions, prior-generation solvent-borne epoxies, and next-generation polyaspartic rapid-cure systems occupy divergent price-performance tiers. Three-tier pricing structure across premium polyaspartic, standard epoxy, and economy acrylic levels reflects certification grade under SASO and SABS frameworks alongside volume scale. Cost compression in solvent-borne tiers is intensifying because petrochemical feedstock volatility feeds raw material instability. Maintenance providers demonstrate lowest price sensitivity due to performance-guaranteed application protocols, while DIY residential purchasers in Gulf Cooperation Council markets exhibit highest elasticity.
Supply Chain Analysis
Contract manufacturing concentration rests with European-originated multinationals operating transfer-production arrangements, regional toll manufacturers in UAE and Saudi Arabia, and specialized applicator networks performing field blending. Geographic supply concentration centers on Germany, the Netherlands, and Belgium for resin intermediates; UAE and Saudi Arabia for regional formulation; and South Africa for SADC distribution. Raw material dependencies draw from bisphenol-A, isocyanate precursors, and amine hardeners. Single-source vulnerability in European resin intermediate supply creates structural exposure. Distribution runs through construction chemical distributors, certified applicator networks, and hardware retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward maintenance providers unbundling after-sales service contracts, as this consolidation of specification influence fragments traditional distributor channel control across metropolitan jurisdictions.
For Market Incumbents: Entrench position through backward integration into regional resin formulation capacity in Saudi Arabia and UAE free zones, bypassing CE-marked import friction. Secure applicator certification program expansion to lock maintenance contract flows against emerging water-based technology specialists. Anchor channel control through integrated floor-waterproofing-joint sealing portfolio bundling in large-scale infrastructure tenders. For New Entrants and Emerging Players: Pursue white-space penetration in Nigerian industrial corridors and Kano textile manufacturing belts where integrated system portfolios remain underdeveloped. Target West African logistics infrastructure as the most penetrable geography given fragmented incumbent presence. Execute go-to-market through partnership with UAE-based distributors possessing established Saudi petrochemical buyer relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors construction chemical conglomerates with verified low-emission formulation platforms and regional manufacturing footprints. Long-term viability hinges on carbon-border adjustment readiness and SASO-SABS dual certification capability. Acquisition target archetype: regional specialists possessing applicator network control in underpenetrated African markets. Signal to watch: divergence in national building code harmonization efforts across Gulf and Southern African jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Manufacturing Capacity Expansion | UAE and Saudi Arabia facilities bypass CE-marked import barriers and compress logistics costs for Gulf petrochemical buyers. |
| Applicator Certification Program Investment | SABS-certified contractor networks capture premium margins through performance-guaranteed protocols in South African metropolitan markets. |
| Water-Based Formulation Platform Development | Aqueous polyurethane dispersions satisfy tightening SASO and SABS VOC limits while matching solvent-borne abrasion resistance. |
| Integrated System Portfolio Bundling | Floor-waterproofing-joint sealing combinations secure specification authority in UAE logistics corridor infrastructure tenders. |
| Carbon-Border Adjustment Readiness Program | Verified low-emission formulations create competitive positioning for EU Green Deal extraterritorial mechanism exposure in North African trade corridors. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs and trade data, SASO and SABS regulatory filings, construction chemical industry association reports, and SEC disclosures from multinational coating suppliers. Primary interviews engaged plant managers at Saudi petrochemical facilities, procurement leads at UAE logistics developers, distribution channel partners across Gulf Cooperation Council markets, and technical R&D directors at European formulation centers. Bottom-up project pipeline assessment triangulates against top-down macroeconomic overlay to validate volume and value estimates.
Forecast inputs incorporate resin chemistry segmentation, application thickness requirements, technology generation transitions, and end-user procurement pattern shifts across the projection horizon. Modeled dimensions span product chemistry tier, application environment severity, compliance technology type, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand projection against capacity expansion timelines. Industry-specific inputs include SASO building efficiency mandate implementation pace and SABS durability standard revision cycles.
Macroeconomic conditions sit as an overlay; deviation in Gulf Cooperation Council construction spending, South African infrastructure budget allocation, or petrochemical feedstock pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization and technology substitution elasticities. Quarterly review of SASO certification issuance rates, SABS standard revision announcements, and Jebel Ali Free Zone warehousing occupancy indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Paint Buckets Market
Paints & Coatings
Middle-East Paints and Coatings Additives Market
Paints & Coatings
Automotive OEM Coatings Market
Paints & Coatings
Food Grade Epoxy Paint Market
Paints & Coatings
Asia-Pacific Paint Spray Guns Market
Paints & Coatings
Europe Paints and Coatings Market
Paints & Coatings
UAE Architectural Paints and Coatings Market
Paints & Coatings
Middle-East Paints and Coatings Market
Paints & Coatings
Global Texture Paint Market
Paints & Coatings
Furniture Wood Coatings Market
Paints & Coatings
Middle East and Africa Paints and Coatings Market
Paints & Coatings
India Paints and Coatings Market
Paints & Coatings
Solar Paint Market
Paints & Coatings
Asia-Pacific Paints and Coatings Additives Market
Paints & Coatings
Sri Lanka Paints and Coatings Market
Paints & Coatings
Canvas Primer Market