
 Acrylic Protective Coating Market | 2026-2036
Acrylic Protective Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Protective Coating Market Analysis
ISO 12944 corrosion-protection certification is rotating supplier eligibility across marine and industrial projects. PPG Industries leverages captive resin production to control formulation costs across North American shipyards. AkzoNobel anchors its position through water-based R&D pipelines aligned with EU VOC directives. Jotun dominates Nordic offshore infrastructure through specialized high-solids systems.
Acrylic protective coatings are thermoplastic or thermosetting films formed from acrylic polymer resins, typically applied at dry-film thicknesses of 50–200 microns to shield substrates from moisture, UV degradation, and chemical attack. Water-based acrylics now lead volume growth as environmental compliance hardens, while solvent-based systems retain margin pools in heavy-industrial segments where performance specifications remain stringent. Marine and construction applications command premium pricing due to extreme-service requirements and recoat complexity.
EPA VOC regulations in the United States, REACH in Europe, and China's MEE emission standards collectively restrict solvent-borne formulations while accelerating compliant alternative development. Product registration with these frameworks now determines market access more than raw technical performance alone. Stakeholders must track regulatory harmonization gaps between jurisdictions to anticipate formulation investment cycles and avoid stranded capacity in non-compliant chemistries.
Market Dynamics
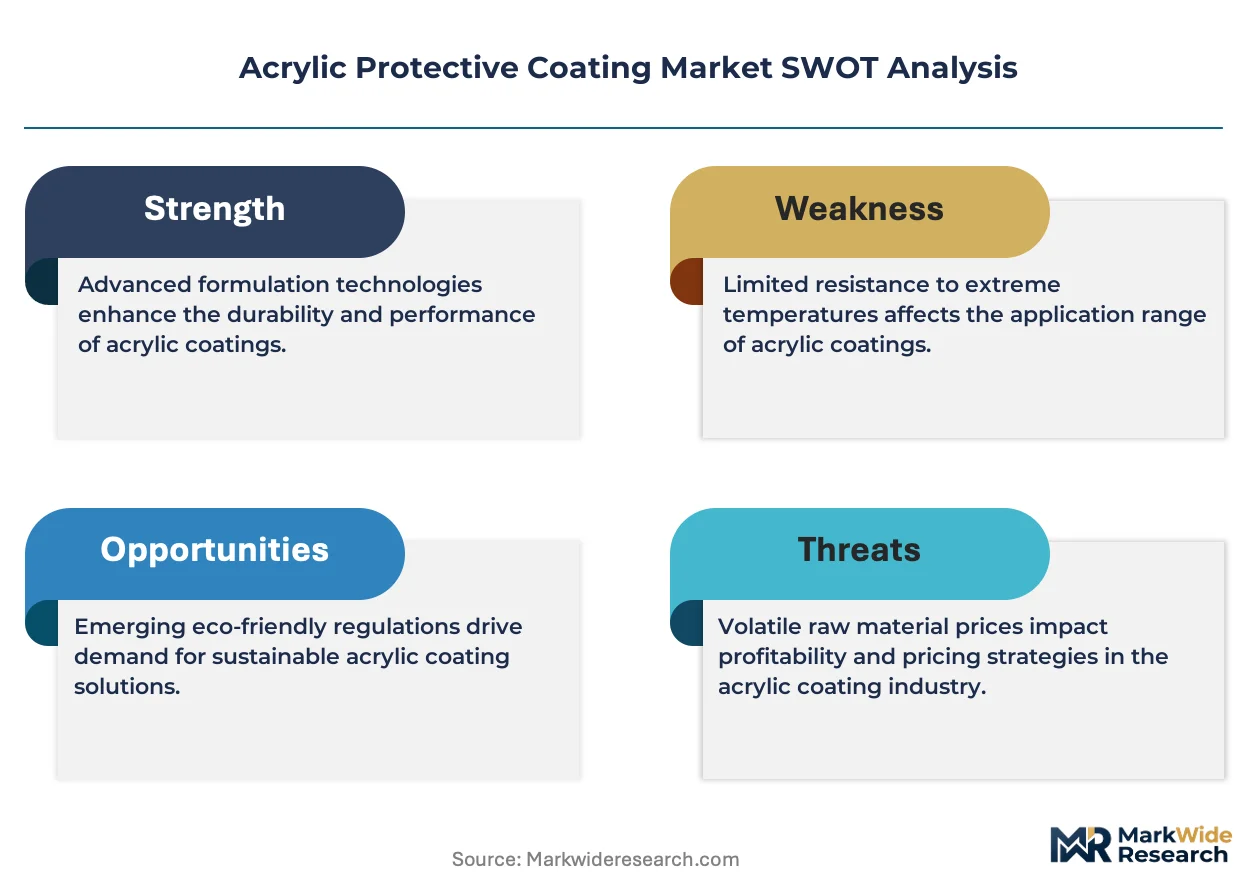
Water-based formulation chemistry is compressing solvent-borne capacity while tightening margin structures across the Acrylic Protective Coating Market. EPA VOC limits and REACH substance restrictions now determine supplier eligibility before performance metrics enter procurement discussions.
Growth Catalysts
- Infrastructure Resilience Mandates:China's MEE emission standards and Germany's tightened building codes are accelerating specification upgrades across marine and industrial maintenance cycles.
- REACH Compliance Windows:European coating formulators are capturing replacement demand as solvent-borne registrations expire, redirecting R&D spend toward compliant acrylic resin architectures.
- Offshore Wind Installation Surge:Nordic and North Sea corrosion-protection specifications are expanding addressable demand for high-solids acrylic systems in salt-exposure environments.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic monomer costs fluctuate with propylene pricing, compressing formulation margins during upstream supply disruptions.
- Specialty Additive Concentration:UV stabilizer and biocide supply concentrates among German and Swiss chemical producers, creating single-source exposure for compliant coating manufacturers.
- Epoxy-Polyurethane Substitution:Heavy-industrial segments in US Gulf Coast petrochemical clusters retain solvent-borne epoxy systems where acrylics face performance ceiling constraints.
Strategic Opportunities
- Indian Industrial Corridor Expansion:BIS certification alignment and PLI scheme incentives are opening specification pathways for water-based acrylic suppliers in steel and cement plant maintenance.
- Digital Color-Matching Platforms:Construction contractors are adopting spectrophotometer-integrated procurement systems that favor standardized acrylic SKU portfolios over custom solvent blends.
- Photovoltaic Backsheet Integration:Convergence of fluoropolymer and acrylic coating technologies is creating new module-protection applications in solar manufacturing supply chains.
Industry Challenges
- ISO 12944 Certification Bottlenecks:Third-party corrosion-testing laboratory capacity constraints are extending product qualification timelines for marine coating approvals.
- Legacy Equipment Compatibility:Water-based acrylic viscosity profiles require spray-gun and drying-oven reconfiguration at contractor facilities, slowing adoption in fragmented construction segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Protective Coating Market |
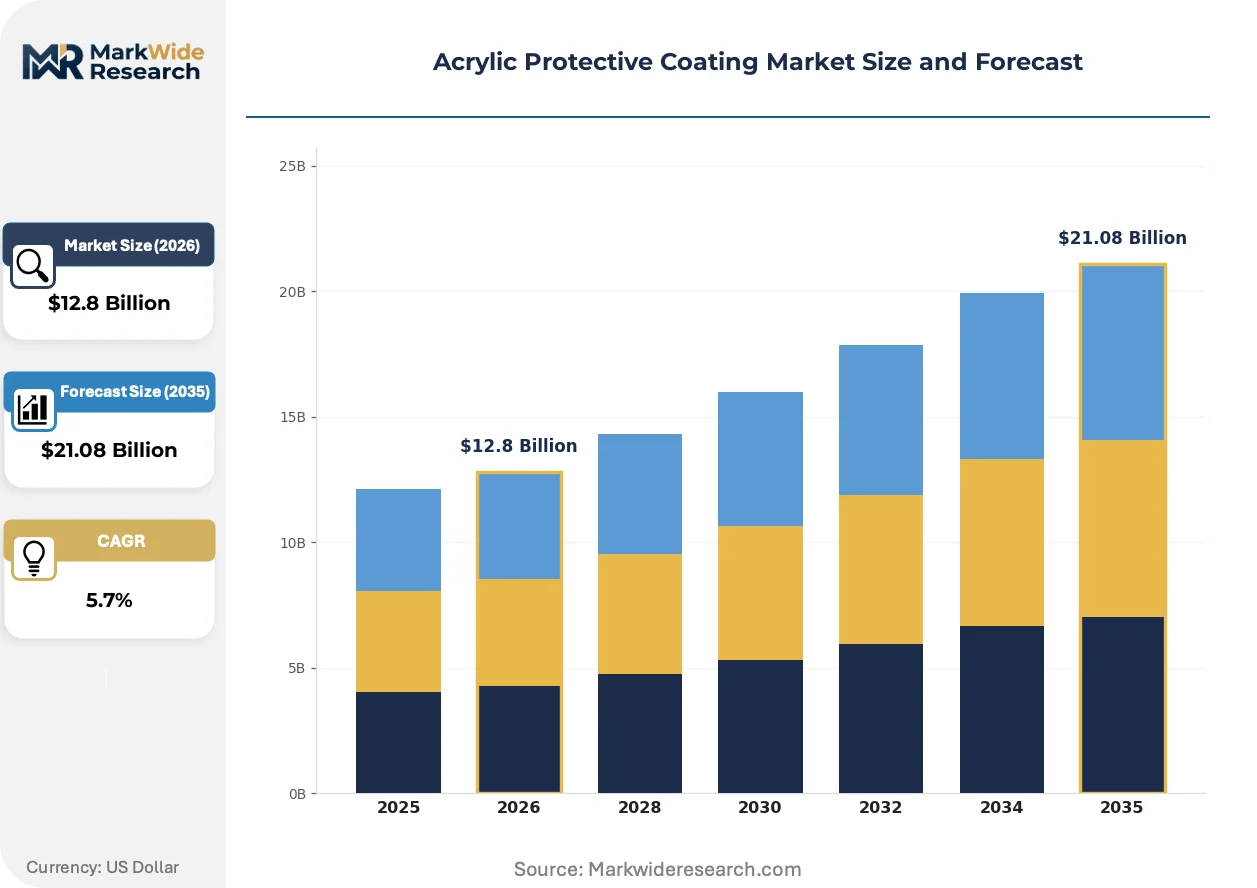
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-based, Water-based, Powder Coatings, UV-cured Application: Automotive, Aerospace, Marine, Construction End User: Manufacturers, Contractors, DIY Users, Maintenance Services Technology: Spray Coating, Brush Coating, Roller Application, Electrodeposition |
| Companies Covered | PPG Industries, Sherwin-Williams, AkzoNobel, BASF, Nippon Paint, Sika, Jotun, RPM International, Kansai Paint, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Protective Coating Market Emerging Trajectories
Formulation architecture is pivoting toward bio-based resin feedstocks and self-healing polymer networks as environmental compliance hardens and lifecycle-cost scrutiny intensifies across asset owners.
Nano-silica reinforcement technology is miniaturizing particle dispersion within acrylic matrices to enhance scratch resistance without sacrificing optical clarity. Automotive refinish shops in Germany and Japan are adopting these systems for premium vehicle protection. The technology is miniaturizing performance differentiation between mid-tier and premium coating tiers, compressing price stratification.
REACH substance restriction proposals targeting microplastic release are forcing reformulation of textured architectural coatings across EU member states. Manufacturers are accelerating bio-based binder development to preempt regulatory disqualification. Decorative exterior applications in France and the Netherlands face the steepest compliance timelines.
Asset owners are unbundling coating application from material supply, issuing separate procurement contracts for specification compliance and labor execution. Industrial maintenance divisions in US chemical processing and German automotive manufacturing are driving this bifurcation. This pattern concentrates specification authority with engineering consultancies while commodifying contractor margins.
Acrylic Protective Coating Market Segmentation
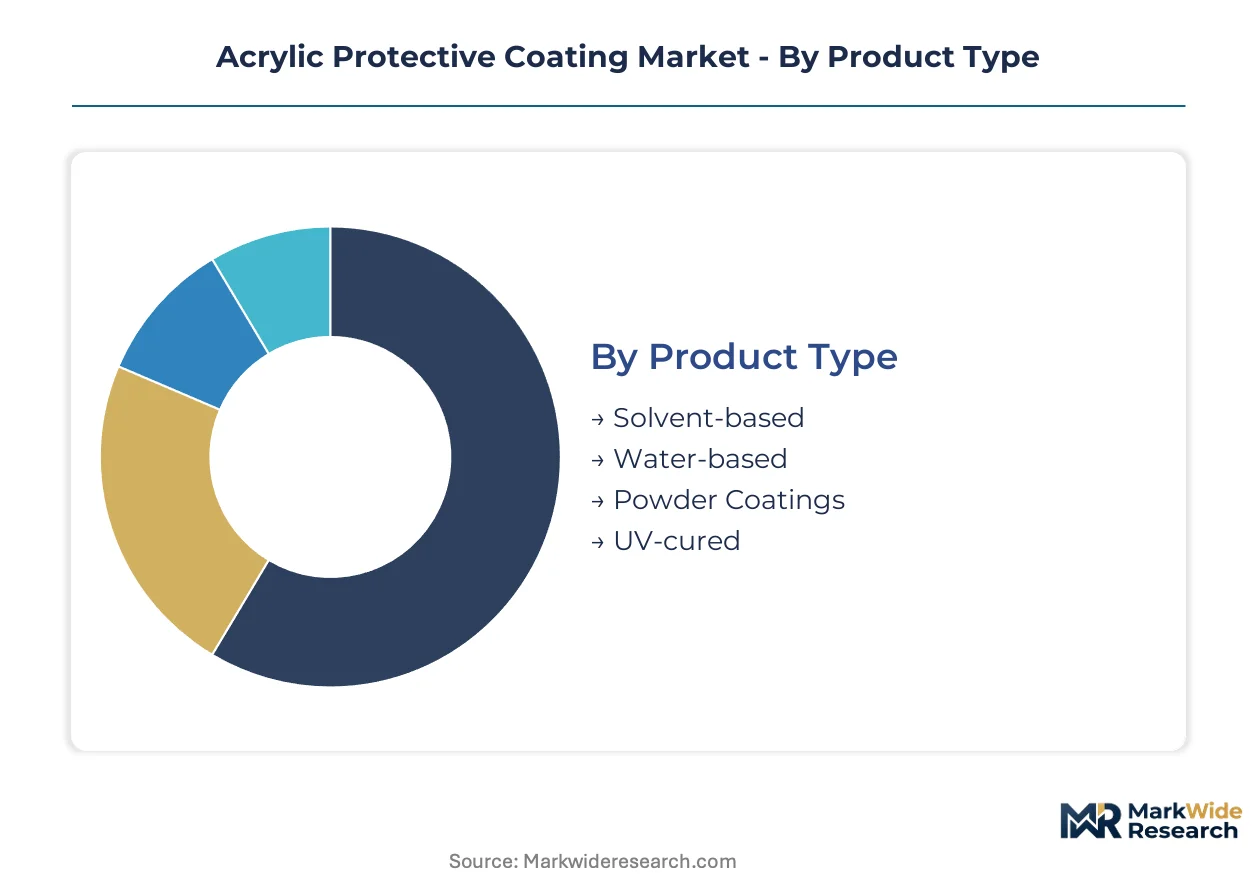
Acrylic protective coating procurement channels diverge sharply by formulation chemistry and end-use complexity. Specification authority concentrates with engineering consultancies in industrial maintenance, while retail distribution dominates consumer-facing construction segments.
Product Type:
Channel economics favor water-based formulations in regulated markets, while solvent-borne systems retain contractor loyalty in heavy-industrial clusters.
- Water-based:Emulsion polymer architectures with 30-50% solids content meet EPA VOC limits and REACH substance restrictions. Demand concentrates in German automotive refinishing and Chinese infrastructure projects where MEE emission standards enforce compliance. Formulators capture specification upgrades as solvent-borne registrations expire.
- Solvent-based:Thermoplastic acrylic solutions in aromatic or aliphatic hydrocarbon carriers deliver 200+ micron single-coat builds. US Gulf Coast petrochemical maintenance and Nordic offshore platforms specify these systems where recoat windows are compressed and substrate temperatures fluctuate.
- Powder Coatings:Thermoset acrylic-epoxy hybrids applied via electrostatic spray to metal substrates in appliance and architectural aluminum segments.
- UV-cured:Acrylate oligomer formulations polymerized under 200-400 nm irradiation for electronics and furniture finishing.
Solvent-based dominates installed base. Water-based is where expansion concentrates.
Application:
Cost tier stratification separates specification-grade marine systems from commodity construction finishes.
- Marine:High-solids acrylic-urethane hybrids certified to ISO 12944 C5-M corrosivity categories for salt-exposure environments. Nordic offshore wind installations and Singapore shipyards specify these for 15-year maintenance cycles. Salt-fog testing protocols extend qualification timelines.
- Construction:Water-based acrylic elastomers for concrete, stucco, and masonry protection. Indian industrial corridor projects and German building envelope retrofits drive volume. BIS certification and tightened energy codes redirect procurement toward compliant formulations.
- Automotive:Basecoat-clearcoat acrylic systems for OEM and refinish segments with color-matching precision requirements.
- Aerospace:Chromate-free pretreatment-compatible topcoats for airframe exteriors subject to UV and hydraulic fluid exposure.
Construction commands volume scale. Marine captures margin premium.
End User:
Customer type determines whether procurement flows through distributor networks or direct specification channels.
- Maintenance Services:Industrial asset owners unbundle material supply from labor execution, issuing separate contracts for specification compliance. US chemical processing and German automotive manufacturing divisions concentrate authority with engineering consultancies.
- Contractors:Fragmented construction applicators purchase through building-material distributors, with digital color-matching platforms favoring standardized SKU portfolios.
- Manufacturers:OEM coating operations with captive application lines and volume purchasing leverage.
- DIY Users:Retail hardware channel consumers selecting pre-tinted architectural coatings.
Maintenance services control specification value. Contractors represent volume throughput.
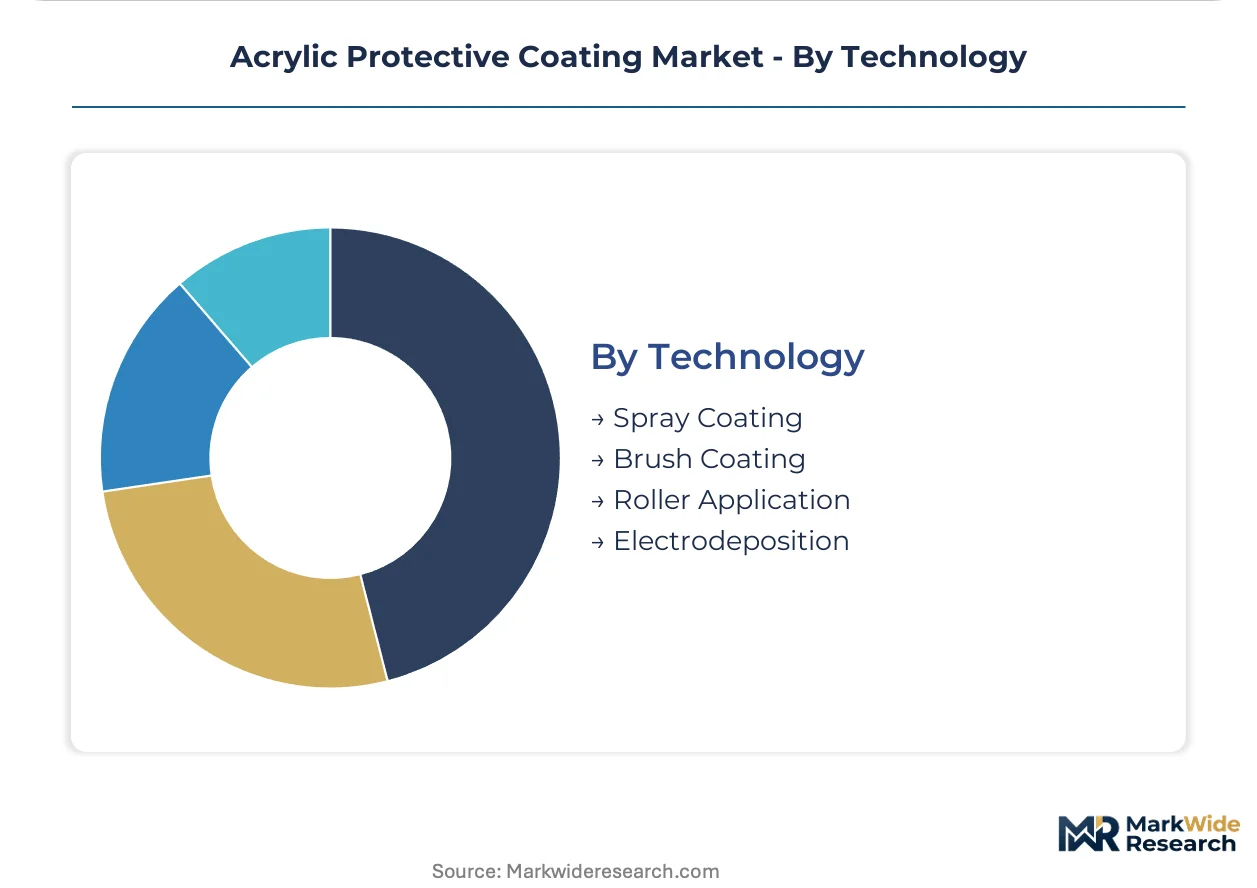
Technology:
Application method maturity curves separate automated OEM lines from field-applied maintenance systems.
- Spray Coating:Airless and HVLP systems dominate marine and industrial maintenance, with water-based viscosity profiles requiring gun and oven reconfiguration at contractor facilities.
- Electrodeposition:Automotive OEM primer application with 95%+ transfer efficiency and uniform edge coverage on complex stampings.
- Brush Coating:Touch-up and small-area repair in field maintenance applications.
- Roller Application:Large-surface architectural and flooring segments with texture requirements.
Spray coating anchors field-installed volume. Electrodeposition defines OEM precision standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government infrastructure stimulus packages and tightening emission standards are redirecting procurement toward compliant acrylic formulations across industrialized economies. National regulators in major manufacturing centers are accelerating specification upgrades that favor water-based systems. Construction resilience mandates and marine maintenance cycles are concentrating demand in specific geographic clusters.
China
Steel plant maintenance and offshore wind installation are expanding specification-grade coating demand. The Ministry of Ecology and Environment (MEE) emission standards enforce water-based formulation compliance across industrial facilities. The Yangtze River Delta manufacturing corridor concentrates procurement for marine and infrastructure projects.
Germany
Automotive refinishing and building envelope retrofits drive premium water-based acrylic volume. REACH substance restrictions rotate supplier eligibility as solvent-borne registrations expire. The Ruhr industrial basin and Bavarian automotive clusters anchor specification authority with engineering consultancies.
United States
Gulf Coast petrochemical maintenance and shipyard corrosion protection sustain solvent-borne demand alongside water-based transitions. EPA VOC limits determine supplier eligibility before performance metrics enter procurement. Houston and Philadelphia marine terminals specify high-solids systems for salt-exposure environments.
India
Steel and cement plant maintenance cycles are expanding addressable demand for compliant coatings. BIS certification alignment and PLI scheme incentives open specification pathways for water-based suppliers. The Delhi-Mumbai Industrial Corridor and Gujarat chemical clusters concentrate project activity.
Singapore
Shipyard repair and offshore platform maintenance command premium pricing for certified marine systems. The national environmental regulator enforces emission standards that accelerate water-based formulation adoption. Jurong Port and Sembcorp Marine facilities specify ISO 12944 C5-M certified coatings.
Acrylic Protective Coating Market Vendor Landscape
Player mix skews toward diversified chemical conglomerates with captive resin production and specialized coating formulators with certification depth. Market structure concentrates specification authority among firms with ISO 12944 laboratory accreditation and REACH-registered portfolios. Two strategic archetypes dominate: integrated resin-to-coating manufacturers controlling formulation costs, and application-technology specialists capturing marine and industrial maintenance premiums. Competitive moves center on backward integration into acrylic monomer supply and geographic expansion into Indian and Southeast Asian industrial corridors.
Among North American diversified manufacturers, PPG Industries and Sherwin-Williams occupy positions anchored by captive resin production and distributor network density. AkzoNobel represents the European formulation specialist archetype with water-based R&D pipelines aligned to EU VOC directives. These three firms exemplify how regulatory compliance capabilities and supply chain control separate specification-grade suppliers from commodity competitors.
| Leading Market Players |
|---|
| PPG Industries |
| Sherwin-Williams |
| AkzoNobel |
| BASF |
| Nippon Paint |
| Sika |
| Jotun |
| RPM International |
| Kansai Paint |
| Others |
Supply Flow & Price Mechanics
Ninety-day acrylic monomer inventory cycles in European coating plants compress margin buffers when propylene feedstock costs spike, concentrating pricing power with German and Swiss resin producers who control specialty additive supply. Water-based formulation transitions under REACH and EPA VOC limits are forcing buyers to absorb requalification costs while solvent-borne capacity rationalization tightens mid-tier supply.
Pricing Analysis
Certification level creates the primary spread across acrylic protective coating tiers, with ISO 12944 C5-M marine systems commanding substantial premiums over architectural water-based emulsions. Three-tier pricing structure separates specification-grade marine coatings from industrial maintenance systems and commodity construction finishes. Cost compression in water-based segments is intensifying because captive resin producers leverage backward integration to undercut independent formulators. Contractor purchasers through building-material distributors exhibit highest price sensitivity, while engineering consultancies specifying industrial maintenance cycles prioritize performance compliance over unit cost.
Supply Chain Analysis
Germany, China, and the United States anchor acrylic resin and specialty additive production, with BASF and Dow facilities along the Rhine and Yangtze river corridors feeding downstream formulation networks. Acrylic monomer supply draws from propylene crackers concentrated in Gulf Coast petrochemical clusters, while UV stabilizer and biocide production rests on Swiss and German fine chemical specialists. Single-source vulnerability in compliant additive supply creates qualification bottlenecks when REACH substance restrictions rotate approved supplier lists. Distribution runs through building-material distributors serving fragmented construction contractors, with direct specification channels dominating industrial maintenance procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 12944 laboratory accreditation and REACH-registered portfolios constitute scarce capabilities that separate specification-grade suppliers from commodity competitors, with fewer than twelve firms globally holding full certification depth across marine and industrial segments.
For Market Incumbents: Fortify specification authority by deepening captive resin production in North American and European production hubs, while accelerating water-based R&D pipelines to preempt solvent-borne registration expirations under REACH. Epoxy-polyurethane substitution in US Gulf Coast petrochemical maintenance and feedstock volatility in propylene derivatives represent immediate threats to margin stability. For New Entrants and Emerging Players: Differentiate on BIS certification alignment and PLI scheme positioning within Indian industrial corridor expansion, where steel and cement plant maintenance cycles are redirecting procurement toward compliant water-based suppliers. Photovoltaic backsheet integration offers a penetrable white-space target, with solar module manufacturers seeking fluoropolymer-acrylic hybrid protection systems. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core coating divisions lacking ISO 12944 depth or REACH compliance infrastructure. Long-term viability hinges on regulatory certification moats rather than scale alone, with water-based formulation expertise and captive resin supply representing durable value anchors. Watch for MEE enforcement acceleration in Chinese steel and offshore wind sectors as inflection indicator for specification-grade demand migration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Supply | Captive propylene derivative production insulates PPG and Sherwin-Williams from feedstock volatility compressing independent formulator margins. |
| ISO 12944 Laboratory Accreditation Investment | Third-party corrosion-testing capacity constraints extend qualification timelines, favoring incumbents with in-house certification infrastructure. |
| Water-Based Formulation R&D Pipeline Expansion | AkzoNobel's REACH-aligned development accelerates specification capture as solvent-borne registrations expire across EU member states. |
| Indian Industrial Corridor Geographic Expansion | BIS certification and PLI scheme incentives open specification pathways for compliant suppliers in Delhi-Mumbai and Gujarat chemical clusters. |
| Photovoltaic Backsheet Technology Partnership | Fluoropolymer-acrylic hybrid convergence creates module-protection applications in solar manufacturing supply chains seeking lifecycle cost reduction. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with coating formulators, plant engineers at downstream OEMs, distribution channel partners, and technical R&D directors; and secondary validation through customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and regulatory registration databases. Bottom-up volume modeling triangulated against top-down value estimates derived from procurement pattern analysis across marine, construction, and industrial maintenance segments.
Across the analysis window, forecasts employed a segmented analytical framework spanning formulation chemistry, application complexity, end-user procurement channel, and regional regulatory cluster. CAGRs were derived from trend extrapolation of specification upgrade cycles, infrastructure maintenance intervals, and compliance-driven formulation substitution patterns. Key inputs included propylene derivative pricing trajectories, REACH substance restriction timelines, and offshore wind installation forecasts for Nordic and North Sea markets.
The analysis sits within stated boundaries; outcomes outside sustained enforcement of EPA VOC limits, REACH registration windows, and MEE emission standards would require recalibration. Forecasts reflect documented assumptions regarding regulatory harmonization gaps between jurisdictions and petrochemical feedstock supply continuity. Recalibration cycles align with material shifts in emission standard enforcement intensity, ISO certification protocol revisions, and acrylic monomer capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Vacuum Coating Machine Market
Coatings
Italy Automotive OEM Coatings Market
Coatings
Coating Binders Market
Coatings
Anti Soiling Coating Market
Coatings
Electrical Insulation Coatings Market
Coatings
Polymer Modified Cementitious Coatings Market
Coatings
Topcoat Market
Coatings
Extrusion Coating Market
Coatings
Transportation Coating Market
Coatings
Electron Beam Curable Coating Market
Coatings
Wood Sealer Market
Coatings
Self-Healing Coatings Market
Coatings
Global Inorganic Antimicrobial Coatings Market
Coatings
Anti-Adhesion Coatings Market
Coatings
South America Thermal Spray Market
Coatings
CVD Coating Technology Market