
 Concrete Floor Coatings Market | 2026-2036
Concrete Floor Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Floor Coatings Market Analysis
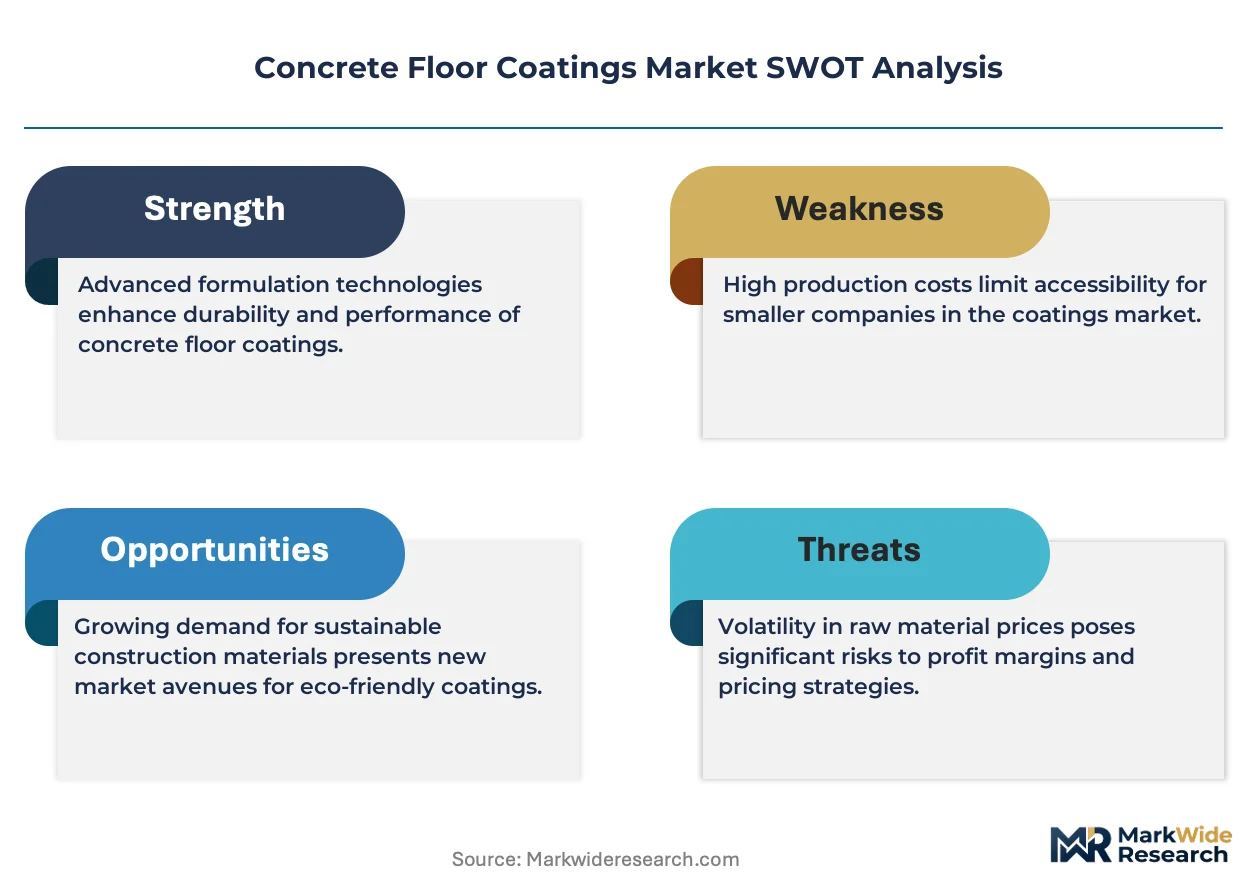
ISO 9001 certification is redrawing competitive boundaries by filtering out suppliers unable to demonstrate consistent quality management systems. PPG Industries sustains broad geographic coverage through its diversified industrial coatings portfolio. Sika AG specializes in construction chemical integration, leveraging its adhesive and sealing expertise to cross-sell flooring systems. Akzo Nobel navigates sustainability pressures through waterborne technology leadership in protective coatings.
Concrete floor coatings constitute polymer-based protective layers applied to cured concrete substrates, typically formulated with epoxy resins, polyurethane binders, or polyaspartic aliphatic polyureas at film thicknesses ranging from 4 to 125 mils depending on traffic load and chemical exposure requirements. These systems seal porous concrete surfaces, prevent dusting, resist abrasion from wheeled equipment, and provide defined aesthetic finishes for industrial and commercial environments. Epoxy formulations dominate the product type landscape due to their cost-performance balance in heavy-traffic applications, while polyaspartic coatings are gaining traction in fast-cure warehouse installations where operational downtime carries steep opportunity costs. The end user structure tilts toward industrial segments—manufacturing plants and distribution centers—where coating replacement cycles tie directly to facility lease renewals and equipment upgrade timelines.
EPA VOC regulations constrain solvent-based formulation options across the United States, compelling reformulation investments and raw material substitution programs. OSHA slip-resistance standards influence texture additive selection and surface profile specifications in commercial and automotive applications. The California Air Resources Board imposes the nation's most stringent emission limits, creating a regulatory laboratory that prefigures national compliance trajectories. Stakeholders must track state-level regulatory divergence while building formulation flexibility that accommodates both current EPA thresholds and anticipated tightening of volatile organic compound limits in high-growth construction corridors.
Market Dynamics
EPA VOC emission limits are forcing wholesale reformulation of solvent-based epoxy systems, compressing product development cycles and redrawing supplier qualification criteria across industrial procurement channels.
Growth Catalysts
- Warehouse automation intensity:Distribution centers deploying autonomous mobile robots require abrasion-resistant coatings with defined surface energy profiles to ensure sensor accuracy and tire longevity.
- REACH chemical restrictions:European manufacturers accelerating substitution of bisphenol-A epoxies with bio-based alternatives ahead of 2025 SVHC candidate list updates.
- Sun Belt industrial construction:Texas, Florida, and Arizona account for disproportionate square footage expansion in manufacturing and logistics facilities driving coating specification volume.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin pricing tracks propylene and benzene derivatives, exposing coating margins to upstream commodity swings without short-term pass-through mechanisms.
- Applicator certification concentration:Factory-trained installation networks cluster in metropolitan corridors, leaving rural industrial projects with limited qualified contractor availability and extended lead times.
- Cementitious overlay substitution:Polished concrete systems with densifier treatments capture budget-conscious commercial segments where coating performance specifications are discretionary.
Strategic Opportunities
- Data center construction surge:Hyperscale facilities in Northern Virginia and Dallas-Fort Worth specify static-dissipative flooring for server hall environments, opening specialized conductivity-grade formulation demand.
- Fast-cure polyaspartic convergence:Combination of aliphatic polyurea chemistry with LED-curable primers enables 4-hour return-to-service protocols in 24/7 logistics operations.
- California CARB alignment:Waterborne coating portfolios developed for SCAQMD Rule 1113 compliance position suppliers for anticipated federal EPA adoption of similar VOC thresholds.
Industry Challenges
- Moisture vapor transmission remediation:Existing slab conditions with elevated relative humidity require calcium chloride testing and mitigation systems before coating adhesion warranties activate, extending project timelines.
- ISO 9001 audit preparation:Mid-tier applicators face documentation gaps in batch traceability and environmental management systems necessary for Tier 1 manufacturing facility qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Floor Coatings Market |
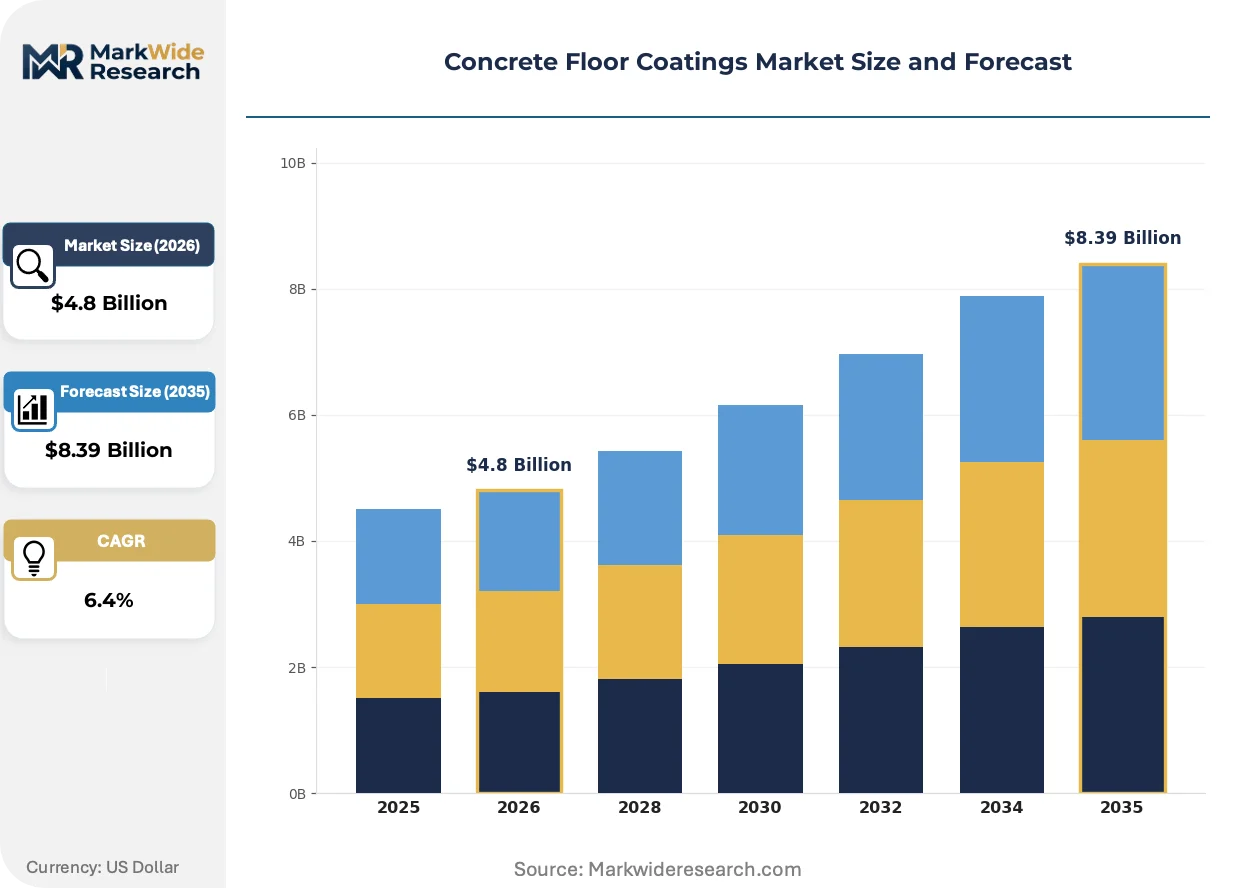
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Polyaspartic End User: Industrial, Commercial, Residential, Automotive Application: Interior, Exterior, Garage, Warehouse Form: Liquid, Solid, Spray, Paste |
| Companies Covered | The Sherwin-Williams Company, PPG Industries, Inc., BASF SE, RPM International Inc., Sika AG, Henkel AG & Co. KGaA, Akzo Nobel N.V., Jotun Group, Laticrete International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Floor Coatings Market Emerging Trajectories
Formulation chemistry and application methodology are converging to compress installation windows while extending service life expectations in high-wear industrial environments.
Polyaspartic aliphatic polyurea technology is miniaturizing cure schedules from 24-hour epoxies to 2-hour full builds without sacrificing film thickness or chemical resistance. Cold-storage facilities and just-in-time distribution hubs are specifying these systems to eliminate multi-day operational shutdowns. The technology is miniaturizing the traditional coating installation from a capital project to a maintenance-window procedure, compressing contractor crew size requirements and reducing facility revenue loss.
EPA NESHAP subpart HHHH standards for hazardous air pollutants from surface coating operations are tightening monitoring and recordkeeping obligations for major source facilities. Automotive and aerospace manufacturing plants must demonstrate continuous compliance through stack testing and material balance accounting. Metal fabrication and assembly operations in Ohio, Michigan, and Indiana are consolidating coating activities into fewer permitted facilities to achieve synthetic minor source status.
Integrated flooring system procurement is consolidating specification authority from general contractors to facility engineering departments with lifecycle cost modeling capabilities. Industrial end-users in food and beverage processing are negotiating direct relationships with coating manufacturers for multi-site maintenance contracts, bypassing traditional distributor networks. This concentration is most pronounced in the Upper Midwest where dairy processing and meatpacking facilities operate coating replacement cycles synchronized with sanitation shutdown schedules.
Concrete Floor Coatings Market Segmentation
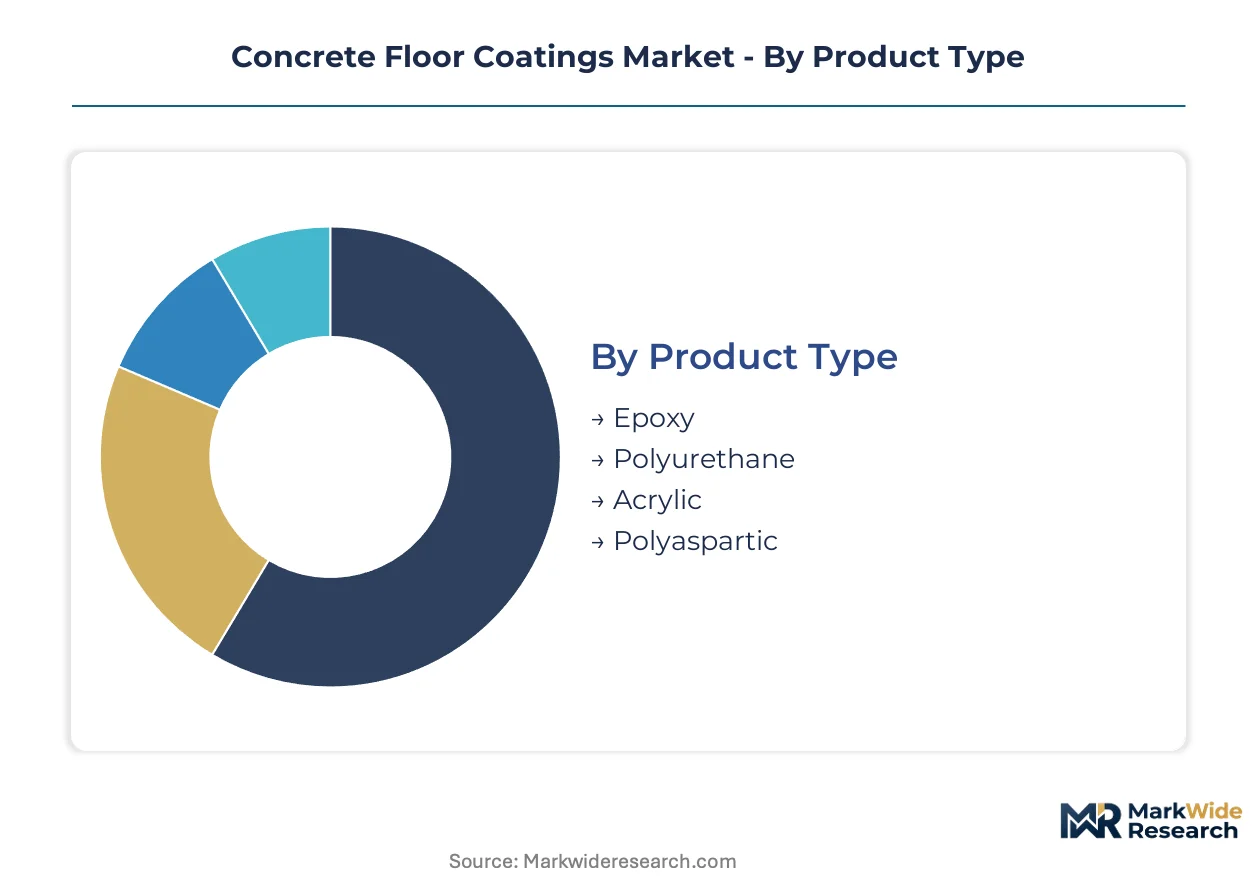
Segmentation in concrete floor coatings reveals distinct procurement channels and specification authorities. Industrial buyers prioritize performance warranties and applicator certification networks. Commercial and residential segments route through distributor and retail channels with shorter decision cycles.
Product Type:
Channel mix varies sharply across chemistries: epoxies flow through industrial distributors and direct manufacturer relationships, while polyaspartics concentrate in specialized applicator networks with factory certification requirements.
- Epoxy:Thermosetting polymer systems formulated from bisphenol-A or bisphenol-F resins with amine hardeners, delivering 8-20 mil builds with superior chemical resistance. Manufacturing plants and distribution centers in Texas and Florida specify these for heavy forklift traffic zones where abrasion resistance trumps cure speed. By volume, epoxy leads. By growth pace, polyaspartic is climbing the fastest.
- Polyurethane:Aliphatic or aromatic isocyanate-based systems offering UV stability and flexible film properties for thermal cycling environments. Food processing facilities in the Upper Midwest favor urethane topcoats for thermal shock resistance during sanitation cycles.
- Acrylic:Waterborne or solvent-based thermoplastic resins providing decorative finishes with moderate durability for light commercial traffic. Retail showrooms and office lobbies select these for color retention and rapid recoatability.
- Polyaspartic:Aliphatic polyurea technology enabling 2-hour full cure schedules without sacrificing film build. 24/7 logistics hubs in Dallas-Fort Worth and Northern Virginia specify these to eliminate operational shutdown windows.
Cost tier separation runs from economy-grade waterborne acrylics through premium polyaspartic systems with 10-year performance warranties.
End User:
Application methodology and crew certification requirements diverge across customer types, with industrial accounts demanding factory-trained installation networks unavailable to smaller commercial buyers.
- Industrial:Manufacturing plants, warehouses, and distribution centers requiring 10-125 mil systems with defined slip resistance and chemical containment properties. Sun Belt logistics construction drives specification volume in Texas, Arizona, and Florida.
- Commercial:Retail, healthcare, and institutional facilities balancing aesthetic requirements with moderate traffic loads. These buyers route through regional distributor networks with shorter lead times than industrial direct channels.
- Residential:Garage floors and basement applications where DIY kits and local contractor bids compete. Home improvement retailers capture this segment through epoxy and polyaspartic kit formulations.
- Automotive:Service bays, showrooms, and manufacturing facilities requiring oil-resistant finishes with static control options. OSHA slip-resistance standards influence texture specification in these environments.
Industrial commands the highest specification authority and longest replacement cycles tied to facility leases. Automotive exhibits the steepest expansion trajectory from electric vehicle manufacturing facility construction.
Application:
Volume concentration aligns with construction activity geography, while margin structure favors specialized environments with performance warranty requirements.
- Interior:Manufacturing floors, commercial kitchens, and cleanroom environments where vapor emission control and chemical resistance dominate specification. EPA VOC regulations constrain solvent-based options in enclosed spaces.
- Exterior:Loading docks, walkways, and parking structures requiring UV-stable aliphatic chemistries with thermal expansion accommodation. These applications specify thicker builds to withstand freeze-thaw cycling.
- Garage:Residential and light commercial vehicle storage with moderate chemical exposure from oils and road salts. DIY epoxy kits and professional polyaspartic applications split this volume.
- Warehouse:High-bay storage and automated distribution centers demanding defined surface energy for robotic navigation and abrasion resistance for tire traffic. Northern Virginia and Dallas-Fort Worth data center corridors drive specialized static-dissipative specifications.
Warehouse applications generate the highest square footage per project. Interior specifications command premium pricing from confined-space application constraints and ventilation requirements.
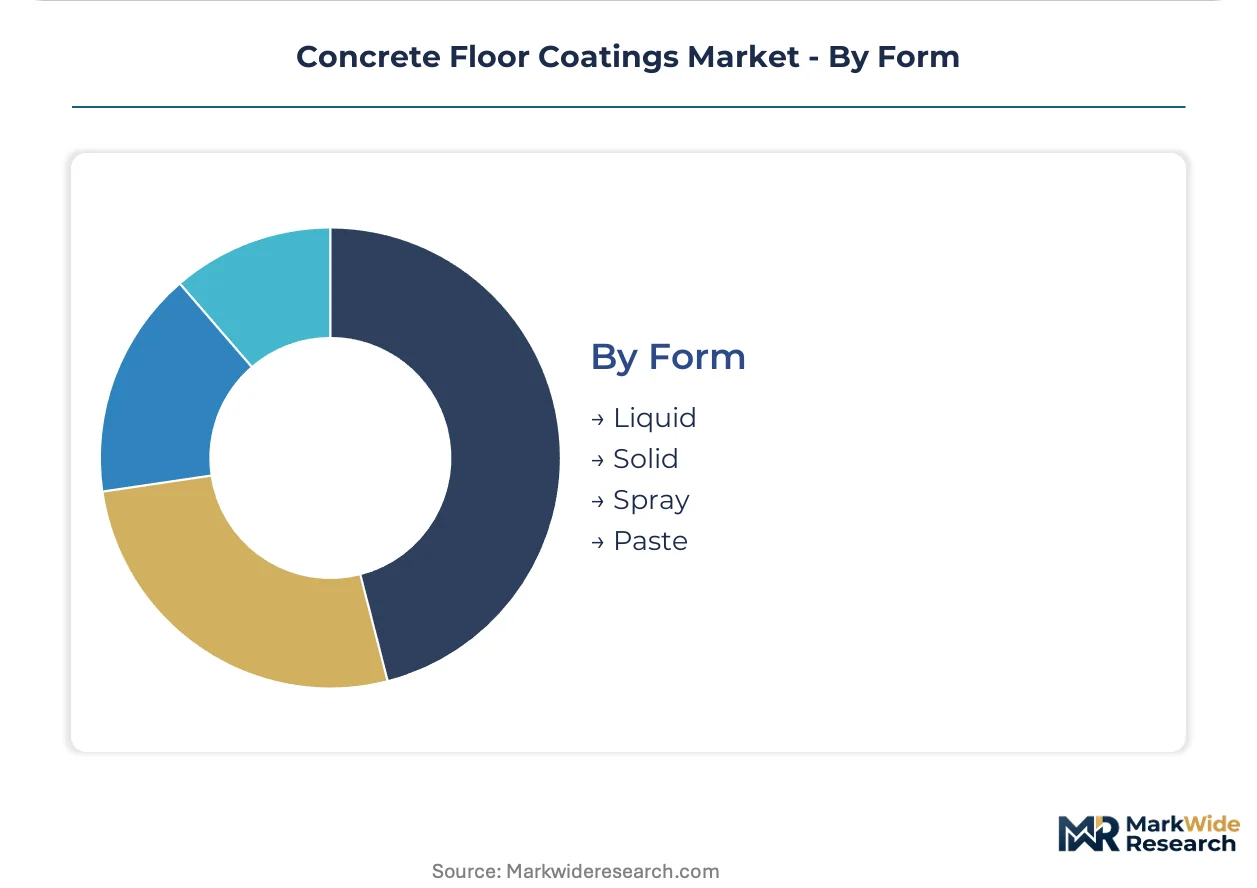
Form:
Supply chain configuration determines availability: liquid systems dominate industrial channels with drum and tote packaging, while spray and paste formats concentrate in repair and specialty contractor networks.
- Liquid:Self-leveling and roller-applied systems in 1-gallon to 55-gallon containers, representing the standard industrial procurement format. These flow through manufacturer-direct and distributor channels with established logistics infrastructure.
- Solid:Flake and chip broadcast media for decorative and slip-resistant finishes, typically packaged in bags for integration with liquid resin systems. Custom color matching drives specification in commercial aesthetic applications.
- Spray:Plural-component equipment-applied systems for rapid coverage of large surface areas. Factory-trained applicator networks control distribution of spray-grade polyaspartic equipment and formulations.
- Paste:Trowel-grade repair compounds and cove base formulations for patching and detail work. These support maintenance and remediation rather than new installation volume.
Liquid forms capture the largest shipment volume by unit and weight. Spray application is gaining share fastest from polyaspartic adoption in time-sensitive logistics environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial facility engineering departments concentrate procurement authority in the United States, Germany, and China, where warehouse automation and data center construction drive specification volume for high-performance coating systems.
United States
Texas, Florida, and Arizona account for disproportionate square footage expansion in manufacturing and logistics facilities. EPA NESHAP subpart HHHH standards for hazardous air pollutants tighten monitoring obligations for surface coating operations in automotive and aerospace plants. Dallas-Fort Worth and Northern Virginia data center corridors specify static-dissipative flooring for server hall environments.
Germany
Automotive manufacturing facilities in Bavaria and Baden-Württemberg demand chemical-resistant coatings for assembly line environments. REACH chemical restrictions accelerate substitution of bisphenol-A epoxies with bio-based alternatives ahead of SVHC candidate list updates. The Stuttgart and Munich industrial clusters drive premium formulation specifications tied to OEM facility standards.
China
E-commerce logistics hubs in the Yangtze River Delta and Pearl River Delta expand warehouse automation requiring abrasion-resistant coatings with defined surface energy profiles. The Ministry of Ecology and Environment enforces volatile organic compound emission standards that constrain solvent-based formulation options. Shenzhen and Shanghai distribution centers specify fast-cure systems to minimize operational downtime.
Japan
Food processing facilities in the Kansai and Chubu regions favor urethane topcoats for thermal shock resistance during sanitation cycles. METI industrial standards influence coating specification protocols in pharmaceutical and electronics manufacturing. The Osaka-Nagoya corridor maintains strict applicator certification requirements for cleanroom installations.
India
Cold chain infrastructure expansion in Maharashtra and Gujarat drives demand for thermal cycling-resistant flooring systems. BIS certification requirements filter supplier participation in government-funded industrial corridor projects. The Mumbai-Pune belt concentrates pharmaceutical manufacturing facilities with coating replacement cycles synchronized with equipment upgrade timelines.
Concrete Floor Coatings Market Vendor Landscape
Player mix skews toward diversified chemical conglomerates with construction chemical divisions, creating a tiered structure where ISO 9001 certification filters mid-tier suppliers from Tier 1 manufacturing facility qualification. Strategic archetypes include full-line coating manufacturers with direct specification relationships, construction chemical specialists leveraging adhesive expertise for cross-selling, and regional applicator networks with factory certification lock-in. Dominant competitive moves center on waterborne formulation investments to preempt regulatory tightening and direct procurement relationships with multi-site industrial end-users that bypass traditional distributor networks.
Within the diversified chemical conglomerate tier, The Sherwin-Williams Company, PPG Industries, and BASF SE exemplify scale-driven positions anchored in broad geographic coverage and integrated supply chains. RPM International and Sika AG occupy specialist positions, with the former representing industrial maintenance coating expertise and the latter exemplifying construction chemical integration strategies. Akzo Nobel and Jotun Group represent waterborne technology leadership archetypes developed for stringent emission compliance environments. These seven entities collectively illustrate the competitive spectrum from volume-driven commodity supply to premium performance warranty positioning.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| PPG Industries, Inc. |
| BASF SE |
| RPM International Inc. |
| Sika AG |
| Henkel AG & Co. KGaA |
| Akzo Nobel N.V. |
| Jotun Group |
| Laticrete International, Inc. |
| Others |
Supply Flow & Price Mechanics
Project-based coating contracts with epoxy resin indexation tie Texas and Florida warehouse developers to fixed-price installation schedules while locking in raw material cost visibility across 12-18 month build cycles. This structure transfers benzene derivative volatility risk from facility owners to applicator networks with bulk purchasing power.
Pricing Analysis
Cost-plus agreements with propylene and benzene indexation dominate industrial procurement in Sun Belt logistics corridors. Pricing stratifies across premium polyaspartic systems with 10-year warranties, standard epoxy builds for heavy traffic zones, and economy waterborne acrylics for light commercial use. Cost compression in mid-tier epoxy formulations is intensifying because cementitious overlay alternatives capture budget-conscious segments. Residential DIY buyers exhibit highest price sensitivity; data center engineering departments show least sensitivity due to uptime-driven specification authority.
Supply Chain Analysis
Just-in-time resin delivery dominates industrial coating projects, though strategic stockpiling of amine hardeners persists among certified applicator networks facing benzene supply disruptions. Raw material sourcing draws from Germany for bisphenol-A epoxy precursors, South Korea for aliphatic isocyanates, and China for titanium dioxide pigments. Single-source vulnerability concentrates in specialty amine curatives from Rotterdam chemical clusters. Distribution runs through manufacturer-direct channels for industrial accounts and regional distributor networks for commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where ISO 9001 certification creates switching costs that entrench qualified suppliers in multi-site manufacturing facility relationships.
For Market Incumbents: Fortify specification authority by deepening backward integration into epoxy resin production and expanding factory-trained applicator networks in Arizona and Florida. Polished concrete densifier systems threaten coating volume in commercial segments; counter with lifecycle cost modeling tools that demonstrate total ownership advantages. Priority lever: direct procurement relationships with food processing engineering departments in the Upper Midwest. For New Entrants and Emerging Players: Anchor in fast-cure polyaspartic technology gaps among rural industrial projects lacking qualified contractor coverage. Rural manufacturing corridors in Ohio and Michigan present the most penetrable geography. Go-to-market angle: mobile spray equipment fleets with 48-hour deployment guarantees bypassing metropolitan applicator bottlenecks. For Investors and Strategic Acquirers: Regional applicator networks with CARB-compliant waterborne portfolios and established data center credentials represent the highest-conviction acquisition archetype. Long-term viability hinges on regulatory entrenchment deepening through anticipated EPA VOC threshold tightening. Signal to watch: SCAQMD Rule 1113 adoption patterns prefiguring federal emission standards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resins | Captive supply of bisphenol-A precursors insulates margins from benzene derivative volatility. |
| Waterborne Formulation Portfolio Expansion | CARB-aligned products position suppliers for anticipated EPA VOC threshold adoption. |
| Factory Certification Network Expansion | Trained applicator density in Sun Belt corridors captures warehouse automation specification volume. |
| Direct Procurement Relationships | Bypassing distributor networks with multi-site industrial end-users concentrates specification authority. |
| Static-Dissipative Formulation Development | Specialized conductivity grades penetrate Northern Virginia and Dallas-Fort Worth data center corridors. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs trade data, and American Chemistry Council reports across coating manufacturers and raw material suppliers. Primary interviews engaged plant engineers at distribution centers, procurement leads at logistics real estate developers, technical directors at epoxy resin producers, and certified applicator network managers. Bottom-up project pipeline analysis triangulates against top-down construction spending data from regional building permits.
Segmentation dimensions modeled include coating chemistry type, film thickness specification, end-use industry vertical, application methodology, and regional regulatory cluster across the analysis window. CAGRs derive from installation volume projections tied to warehouse square footage expansion and coating replacement cycle analysis. Forecast inputs incorporate EPA NESHAP compliance cost modeling and polyaspartic cure schedule adoption curves in 24/7 logistics environments.
Decision-makers should treat outputs as directional under assumptions of sustained Sun Belt industrial construction and stable benzene derivative pricing; material deviation would warrant model refresh. Specific risk factors include cementitious overlay substitution acceleration and REACH SVHC list expansion affecting bisphenol-A epoxy formulations. Revision becomes warranted when warehouse automation deployment rates cross thresholds that alter surface energy specification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Italy Automotive OEM Coatings Market
Coatings
Energy Efficient Powder Coatings Market
Coatings
Global Polyurea Coating Market
Coatings
Topcoat Market
Coatings
US Antifouling Yacht Coatings Market
Coatings
Acrylic Surface Coating Market
Coatings
Vietnam Architectural Coatings Market
Coatings
Hard Coating Market
Coatings
Global Plastic Coatings Market
Coatings
France Automotive OEM Coatings Market
Coatings
Marking Coatings Market
Coatings
Flexible Waterproof Coating Market
Coatings
Spain Automotive OEM Coatings Market
Coatings
Europe Protective Coatings Market
Coatings
Global Graphite Coatings Market
Coatings
Conductive Polymer Coatings Market