
 2K Protective Coatings Market | 2026-2036
2K Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
2K Protective Coatings Market Intelligence
Buyer concentration among shipbuilders and offshore engineering contractors is rebalancing as smaller independent maintenance firms gain procurement share through digital coating specification platforms. BASF SE leverages its integrated resin supply chain to control raw material quality for epoxy formulations. Jotun A/S anchors its position through specialized marine application expertise and direct technical service teams at major port clusters. Akzo Nobel N.V. competes across multiple industrial end uses with standardized product platforms that reduce customer switching costs.
2K protective coatings are two-component systems combining a base resin with a hardener that chemically crosslink at ambient or elevated temperatures to form dense, adherent films with hardness ratings often exceeding 5H pencil hardness and salt spray resistance beyond 5,000 hours. These formulations serve primarily to prevent substrate corrosion, chemical attack, and mechanical abrasion in aggressive operating environments. Epoxy systems dominate heavy industrial maintenance due to superior chemical resistance and lower applied cost per mil, while polyurethane topcoats command premium positioning in aerospace and marine applications where UV stability and gloss retention determine recoating intervals. Water-based technologies are gaining formulation share as environmental compliance tightens, though solvent-based systems retain dominance in field-applied marine and infrastructure settings where ambient cure speed and substrate tolerance remain critical.
REACH registration requirements and the EU F-Gas Regulation constrain permissible solvent chemistries and hardener components, forcing reformulation investments that favor suppliers with captive resin synthesis capabilities. EPA NESHAP standards in the United States impose parallel VOC limits on industrial surface coating operations, creating cross-jurisdictional compliance complexity for multinational applicators. China's GB standards and MEE enforcement protocols add a third regulatory layer for suppliers serving Asia-Pacific shipyard clusters. Stakeholders must monitor evolving substance restriction timelines and pre-qualify alternative hardener chemistries before existing formulations face authorization withdrawal.
Market Dynamics
REACH authorization timelines and the EU F-Gas Regulation are forcing accelerated reformulation cycles across epoxy and polyurethane chemistries, compressing product development windows from 36 months to 18 months for suppliers without captive resin synthesis.
Growth Catalysts
- Offshore platform maintenance cycles:North Sea operators are advancing scheduled recoating programs to preempt corrosion-related downtime during winter weather windows.
- REACH substance restriction pre-qualification:ECHA's sunset date enforcement for isocyanate-based hardeners is pulling forward demand for compliant alternative formulations.
- Water-based epoxy curing advances:New catalyst packages achieving ambient cure below 10°C are opening field application in temperate climates previously reserved for solvent systems.
Market Restraints
- Epoxy resin supply concentration:Bisphenol A feedstock pricing volatility tied to Asian petrochemical capacity swings creates margin compression for European formulators.
- Solvent-based system lock-in:Marine applicators in Hamburg and Rotterdam port clusters face technical barriers to water-based conversion due to humidity-cure incompatibility with existing spray equipment.
- Polyaspartic substitution threat:Fast-cure polyurea systems are capturing share in secondary containment and flooring applications where return-to-service speed dominates specification.
Strategic Opportunities
- Digital coating specification platforms:Independent maintenance firms in Bremerhaven and Marseille are bypassing traditional distributor networks through AI-assisted product matching tools.
- EU Green Deal public procurement mandates:German federal infrastructure tenders now require VOC content documentation, creating preference windows for verified low-emission systems.
- UV-curable epoxy hybrid development:Convergence of cationic UV chemistry with moisture-tolerant hardeners targets wind turbine blade repair applications requiring rapid turnaround.
Industry Challenges
- Certified applicator pipeline constraints:SSPC and FROSIO qualification backlogs in Scandinavian shipyards are extending project mobilization timelines by 8-12 weeks.
- Legacy coating compatibility testing:Intercoat adhesion failures between existing epoxy primers and new low-VOC topcoats are forcing costly full-stripping protocols on North Sea assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2K Protective Coatings Market |
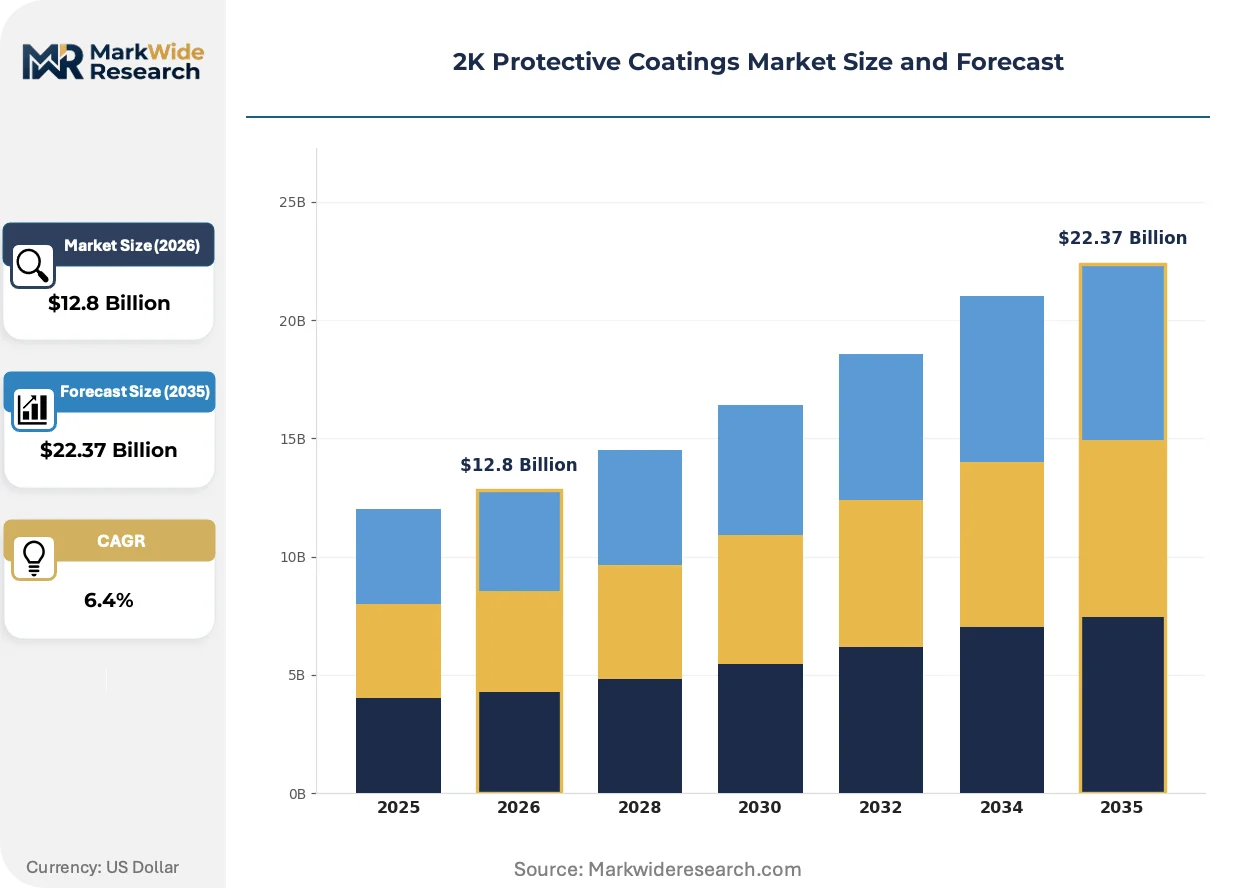
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Alkyd, Polyester, Silicone Application: Marine Vessels, Oil & Gas Facilities, Industrial Machinery, Infrastructure, Aerospace Components, Power Plants Technology: Solvent-Based, Water-Based, High-Solid, Powder Coatings, UV-Curable End User Industry: Construction Firms, Equipment Manufacturers, Shipbuilders, Power Generation Companies, Aviation Firms, Chemical Processing Units |
| Companies Covered | BASF SE, Jotun A/S, Akzo Nobel N.V., RPM International Inc., Hempel A/S, PPG Industries, Inc., Axalta Coating Systems, Sika AG, Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2K Protective Coatings Market Strategic Shifts & Innovations
Formulation chemistry, regulatory compliance architecture, and procurement digitization are converging to redefine competitive advantage in protective coatings specification and application.
Robotic spray application systems integrating real-time film thickness monitoring and automated path correction are automating quality consistency on offshore platform ballast tanks and wind turbine monopiles. Norwegian yard operators are deploying these units for 24-hour continuous coating operations in controlled environments. The technology is automating labor cost structures while compressing recoating intervals through precise mil-build control.
ECHA's 2023 restriction proposal for medium-chain chlorinated paraffins as flame-retardant additives is forcing polyurethane intumescent coating reformulations across marine and architectural segments. German formulators are accelerating phosphorous-nitrogen synergist testing to maintain certification under MED and EN 45545 standards. The regulatory pressure is most acute in cruise ship newbuild specifications, where fire performance ratings determine yard contract awards.
Specification authority is migrating from shipyard procurement departments to fleet technical managers using predictive corrosion modeling software. Mediterranean and Baltic operators are consolidating coating decisions across multiple vessel classes through centralized digital platforms. This concentration is visible in Hamburg and Copenhagen headquarters, where technical service relationships now outweigh price-based tendering for maintenance contract renewals.
2K Protective Coatings Market Segmentation
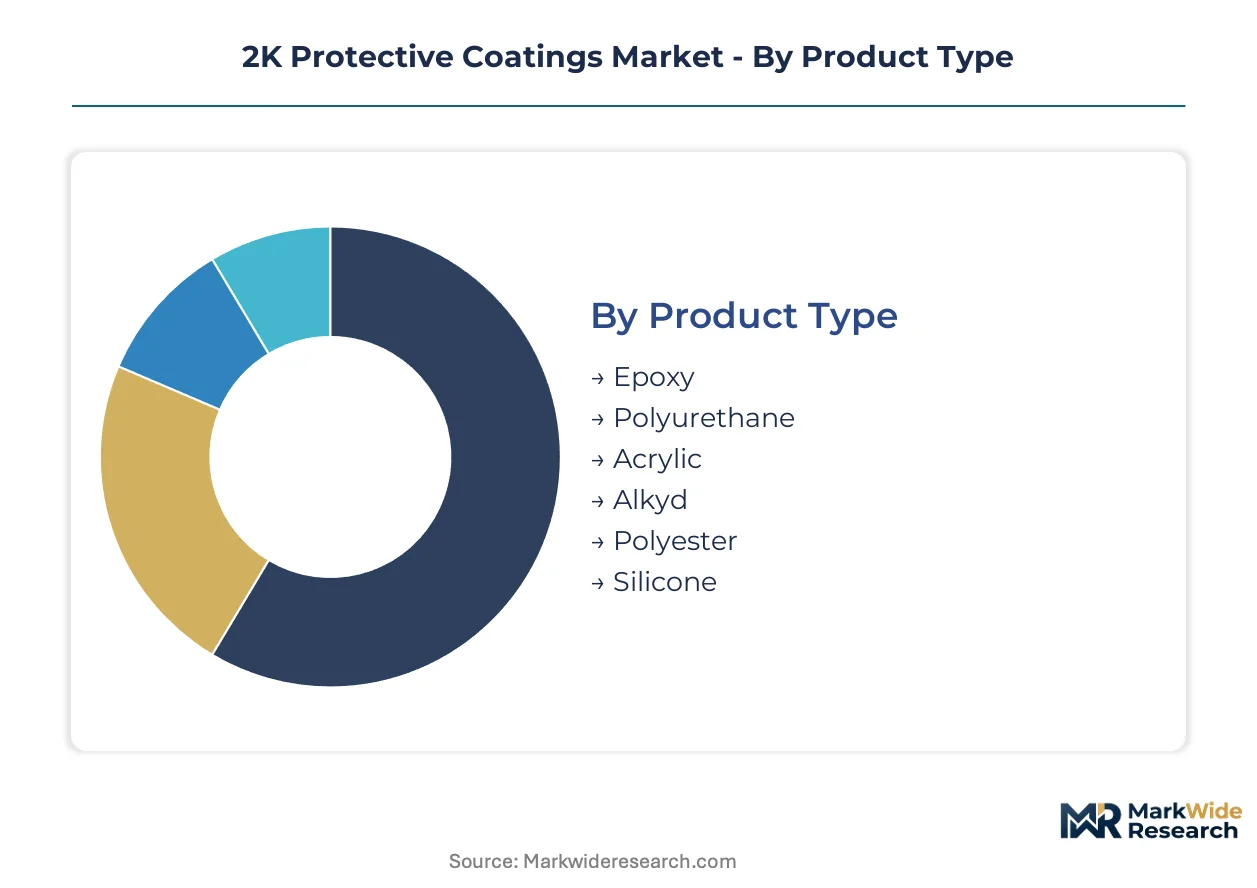
Segmentation in 2K protective coatings reveals how formulation chemistry, application environment, and procurement authority intersect to determine supplier positioning. Specification decisions cascade differently across marine newbuild programs versus offshore maintenance contracts, creating distinct competitive arenas within the same technical category.
Product Type:
Buyers select resin chemistry based on chemical exposure severity, UV stability requirements, and recoating interval economics rather than upfront material cost.
- Epoxy:Two-component amine-cured systems deliver dense crosslinked films with superior chemical resistance and adhesion to blasted steel substrates. Demand concentrates in North Sea offshore platform maintenance, where operators prioritize 15-year protection intervals against salt spray and process chemical exposure under REACH substance restriction timelines.
- Polyurethane:Aliphatic isocyanate-cured topcoats provide UV-stable gloss retention critical for aerospace exterior finishes and superyacht aesthetic requirements. German and Dutch marine applicators specify these systems despite ECHA isocyanate authorization pressures, as alternatives fail to match color stability under Mediterranean and Caribbean operating conditions.
- Acrylic:Modified acrylic-urethane hybrids serve architectural metal cladding where rapid dry-to-touch enables just-in-time construction sequencing.
- Alkyd:Traditional oil-modified polyester systems persist in heritage infrastructure maintenance where substrate compatibility with aged coatings overrides performance specifications.
- Polyester:Unsaturated polyester gelcoats dominate wind turbine nacelle exterior protection against particulate erosion.
- Silicone:High-temperature silicone-modified alkyd formulations protect exhaust stacks and flare systems in chemical processing facilities.
Epoxy leads on scale across industrial maintenance volumes; polyurethane leads on momentum as ECHA restriction timelines accelerate alternative hardener development.
Application:
Application environment dictates cure chemistry selection, with ambient temperature and humidity constraints filtering viable formulation options.
- Marine Vessels:Ballast tank, cargo hold, and topside coatings face simultaneous salt immersion, mechanical abrasion from cargo handling, and UV degradation. Hamburg and Rotterdam shipyards specify epoxy-polyurethane systems compliant with IMO PSPC performance standards for dedicated seawater ballast spaces.
- Oil & Gas Facilities:Offshore platform structural steel, process equipment, and subsea pipelines require cathodic disbondment resistance and thermal insulation compatibility. Norwegian operators in the North Sea are advancing recoating programs to preempt winter weather downtime windows.
- Industrial Machinery:Manufacturing equipment and material handling systems prioritize chemical resistance against lubricants, coolants, and cleaning agents.
- Infrastructure:Bridges, pipelines, and storage tanks in German federal projects now require VOC documentation under EU Green Deal procurement mandates.
- Aerospace Components:Aircraft exterior skins and engine nacelles demand polyurethane topcoats with gloss retention specifications exceeding commercial marine requirements.
- Power Plants:Boiler structures, cooling water systems, and flue gas desulfurization units combine high-temperature exposure with acidic condensation environments.
Oil & gas facilities lead on scale through North Sea maintenance cycle concentration; infrastructure leads on momentum through EU public procurement compliance windows.
Technology:
Environmental regulation stringency and application equipment legacy determine technology adoption trajectories across end-use segments.
- Solvent-Based:Traditional xylene and ketone-thinned systems retain dominance in field-applied marine and infrastructure settings where ambient cure speed below 5°C and substrate tolerance for surface preparation deficiencies remain critical. Hamburg port cluster applicators face technical barriers to conversion due to humidity-cure incompatibility with existing heated plural-component spray equipment.
- Water-Based:Epoxy dispersions and polyurethane dispersions are gaining formulation share as REACH VOC thresholds tighten, with new catalyst packages achieving ambient cure below 10°C opening temperate climate field applications previously reserved for solvent systems.
- High-Solid:Formulations above 80% volume solids reduce solvent emissions while maintaining application viscosity through reactive diluent chemistry.
- Powder Coatings:Thermoset epoxy and polyester powders serve factory-applied industrial components where oven cure infrastructure exists.
- UV-Curable:Cationic epoxy hybrids with moisture-tolerant hardeners target wind turbine blade repair applications requiring rapid turnaround and controlled film build.
Solvent-based systems lead on scale through marine and infrastructure lock-in; water-based technologies lead on momentum as ECHA enforcement compresses reformulation windows.
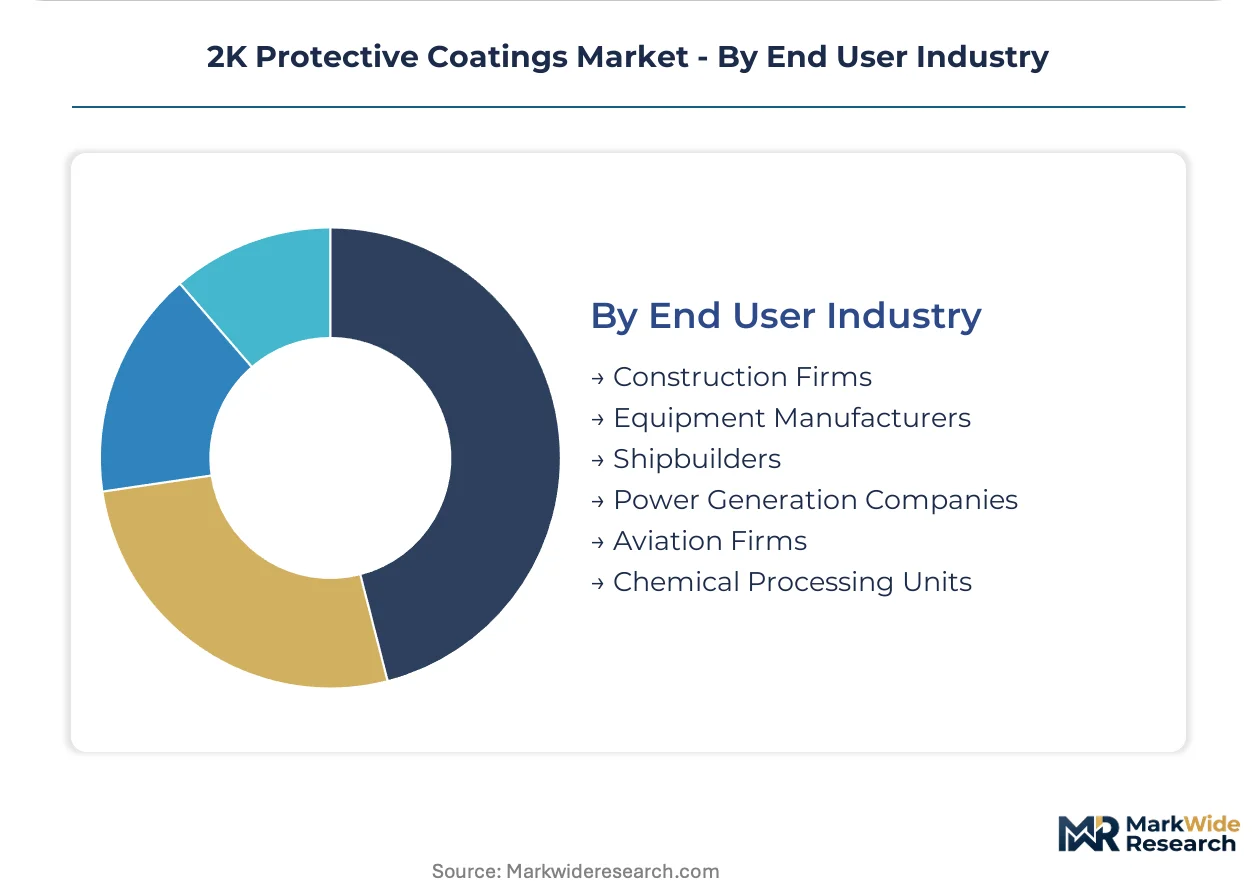
End User Industry:
Procurement authority concentration and technical specification capability vary sharply across end user categories, determining supplier relationship economics.
- Shipbuilders:Yard procurement departments traditionally controlled coating specification, but Mediterranean and Baltic fleet operators are consolidating decisions through centralized digital platforms with predictive corrosion modeling. Hamburg and Copenhagen headquarters now drive technical service relationships over price-based tendering.
- Construction Firms:German federal infrastructure tenders require VOC content documentation, creating preference windows for verified low-emission systems in bridge and storage tank contracts.
- Equipment Manufacturers:Factory-applied coating specifications emphasize film thickness uniformity and cure schedule compatibility with production line throughput.
- Power Generation Companies:Offshore wind developers specify coating systems for turbine monopiles and transition pieces with 25-year design life requirements.
- Aviation Firms:OEM and MRO coating specifications prioritize weight minimization, fluid resistance, and aerodynamic surface finish.
- Chemical Processing Units:Aggressive acid, alkali, and solvent exposure drives epoxy and vinyl ester system selection with specialized novolac modifications.
Shipbuilders lead on scale through newbuild and maintenance contract concentration; construction firms lead on momentum through EU Green Deal procurement mandate implementation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial maintenance intensity contrasts with China's shipyard capacity expansion, while US Gulf Coast offshore activity and Norwegian North Sea platform aging create divergent demand profiles across major coating markets.
Germany
Federal infrastructure tenders under EU Green Deal mandates now require VOC content documentation for bridge and storage tank contracts. ECHA enforcement of REACH substance restrictions accelerates reformulation investments among Hamburg and Bremerhaven applicators. The North Rhine-Westphalia chemical processing corridor drives epoxy system demand for flare stack and exhaust protection.
United States
EPA NESHAP standards impose parallel VOC limits on industrial surface coating operations across Gulf Coast refineries and offshore platform clusters. The Texas-Louisiana petrochemical corridor sustains heavy maintenance cycles for process equipment and pipeline infrastructure. Houston-area applicators face cross-jurisdictional compliance complexity when coordinating with multinational operators.
China
GB standards and MEE enforcement protocols regulate coating chemistries across Yangtze River Delta shipyard clusters. Shanghai and Ningbo yards expand procurement of high-performance corrosion protection systems for newbuild vessels. Domestic petrochemical capacity swings in Shandong Province create bisphenol A feedstock pricing volatility for regional formulators.
Norway
North Sea operators advance scheduled recoating programs to preempt corrosion-related downtime during winter weather windows. Norwegian yard operators deploy robotic spray application systems for 24-hour continuous coating operations in controlled environments. Stavanger and Bergen technical service teams consolidate specification authority through predictive corrosion modeling platforms.
Netherlands
Rotterdam port cluster applicators face technical barriers to water-based conversion due to humidity-cure incompatibility with existing heated plural-component spray equipment. The country's national environmental regulator enforces tightening VOC thresholds across marine and infrastructure settings. Amsterdam-Rijnmond industrial maintenance activity intensifies as REACH sunset dates approach for isocyanate-based hardeners.
2K Protective Coatings Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and application service vectors. The vendor base stratifies into three tiers: integrated resin producers controlling raw material quality, marine-focused technical service providers, and multi-industrial platform suppliers reducing customer switching costs. Consolidation pressures favor players with captive synthesis capabilities and direct port-cluster presence. Strategic moves concentrate on backward integration into resin supply and digital specification platform deployment.
Among European integrated chemical groups, BASF SE anchors the resin-synthesis tier through upstream control over epoxy formulation feedstocks. Jotun A/S and Hempel A/S occupy positions within the marine-specialist archetype, exemplifying technical service-intensive models built around direct presence at major port clusters. Akzo Nobel N.V. and PPG Industries, Inc. represent diversified coating platforms competing across multiple industrial end uses with standardized product ranges. These five entities collectively illustrate the competitive tension between vertical integration depth and application-specific expertise.
| Leading Market Players |
|---|
| BASF SE |
| Jotun A/S |
| Akzo Nobel N.V. |
| RPM International Inc. |
| Hempel A/S |
| PPG Industries, Inc. |
| Axalta Coating Systems |
| Sika AG |
| Sherwin-Williams Company |
| Others |
Cost & Logistics Intelligence
Captive resin synthesis capabilities anchor both supply security and pricing power for European formulators facing REACH substance restriction timelines. BASF SE's upstream control over bisphenol A epoxy feedstocks insulates margin structures from Asian petrochemical volatility that compresses independent compounders.
Pricing Analysis
Capacity additions in Shandong Province are reshaping price floors for bisphenol A feedstock, transmitting volatility to European epoxy formulators. Three-tier pricing structure across premium marine-certified, standard industrial, and economy maintenance tiers reflects certification grade and technical service bundling. Cost compression in standard-grade epoxy systems is intensifying because Hamburg port cluster applicators face equipment conversion barriers to water-based alternatives. Independent maintenance firms exhibit highest price sensitivity, while Norwegian offshore operators prioritize performance guarantees over unit cost.
Supply Chain Analysis
SSPC and FROSIO certification requirements gate qualified applicator availability, concentrating execution capacity around Stavanger, Hamburg, and Rotterdam port clusters. Raw material sourcing draws from German resin synthesis, Chinese bisphenol A feedstock, and Dutch specialty amine hardener production. Single-source vulnerability runs through Asian petrochemical capacity swings affecting epoxy precursor availability. Distribution runs through direct technical service teams at major port clusters rather than traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 2K protective coatings market functions as a stable compounder, with offshore platform maintenance cycles and regulatory reformulation mandates generating predictable replacement demand.
For Market Incumbents: Anticipate polyaspartic substitution threats in secondary containment by accelerating UV-curable epoxy hybrid development for wind turbine blade repair applications. Deepen backward integration into amine hardener synthesis before ECHA authorization timelines constrain supply. Prioritize digital specification platform deployment to defend technical service relationships against AI-assisted product matching tools. For New Entrants and Emerging Players: Independent maintenance firms in Bremerhaven and Marseille represent the most penetrable channel partner type, bypassing entrenched distributor relationships through procurement digitization. Target water-based epoxy catalyst packages achieving ambient cure below 10°C for temperate climate field applications previously reserved for solvent systems. Lead with VOC documentation compliance to capture EU Green Deal public procurement preference windows. For Investors and Strategic Acquirers: Roll-up economics work for marine-focused technical service providers because specification authority is migrating from shipyard procurement to fleet technical managers consolidating decisions across vessel classes. Five-to-ten year viability hinges on captive resin synthesis capabilities and direct port-cluster presence. Watch for ECHA enforcement acceleration on isocyanate-based hardeners as inflection indicator for alternative formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | BASF SE's captive bisphenol A supply insulates margins from Shandong Province feedstock volatility. |
| Digital Specification Platform Deployment | AI-assisted product matching tools enable independent maintenance firms to bypass traditional distributor networks. |
| Water-Based Catalyst Package Development | New ambient cure below 10°C opens temperate climate field applications previously reserved for solvent systems. |
| Robotic Spray Application Investment | Norwegian yard operators deploy 24-hour continuous coating operations with real-time film thickness monitoring. |
| UV-Curable Epoxy Hybrid Formulation | Convergence with moisture-tolerant hardeners targets wind turbine blade repair requiring rapid turnaround. |
Research Approach
Coverage spans Germany, Norway, Netherlands, United States, and China, with primary inputs from each region's major port clusters and industrial corridors. Primary interviews engaged coating formulators, shipyard procurement directors, offshore platform maintenance managers, SSPC-certified applicators, and ECHA regulatory affairs specialists. Secondary validation drew from REACH substance restriction timelines, EPA NESHAP compliance records, GB standards documentation, customs trade data, and SEC filings from listed coating manufacturers. Bottom-up demand modeling triangulated against top-down market sizing across resin chemistry segments.
Rate-of-change decomposition anchored the analytical framework across the projection horizon, separating volume growth from value mix shifts. Segmentation dimensions modeled include resin chemistry tier, application environment severity, cure technology type, and end-user procurement authority concentration. CAGRs derived from installed base corrosion modeling, maintenance cycle intervals, and regulatory reformulation pull-forward effects. Forecast inputs incorporated North Sea platform aging profiles, EU Green Deal procurement mandate implementation schedules, and ECHA authorization sunset dates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA enforcement acceleration, bisphenol A feedstock pricing volatility, and polyaspartic substitution rates in secondary containment. Forecasts reflect documented assumptions regarding maintenance cycle timing and regulatory pre-qualification behavior. A model refresh is warranted upon material change in REACH substance restriction timelines or MEE enforcement protocols in Yangtze River Delta shipyards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Thermal Barrier Coatings Market
Coatings
Global Low Friction Coatings Market
Coatings
Global Plastic Coatings Market
Coatings
Europe Super Hydrophobic Coatings Market
Coatings
Biopolymer Coatings Market
Coatings
Perfluoroalkoxy (PFA) Coatings Market
Coatings
Anti Soiling Coating Market
Coatings
Concrete Floor Coatings Market
Coatings
North America Polyimide Coating Market
Coatings
Camouflage Coatings Market
Coatings
Transparent Conductive Coatings Market
Coatings
Europe Waterborne Polyurethane Coatings Market
Coatings
Japan Marine Coatings Market
Coatings
Global Flat Glass Coatings Market
Coatings
Carpet Back Coatings Market
Coatings
Water Based Enamel Market