
 Biobased Propylene Glycol Market | 2026-2036
Biobased Propylene Glycol Market Size, Share, and Industry Trends Forecast 2026-2036
Biobased Propylene Glycol Market Outlook
Specialized biochemical engineering talent is collapsing across North American and European production hubs, constraining plant expansion timelines for biobased glycol operations. BASF SE leverages its Ludwigshafen integrated complex to sustain captive glycerol-to-propylene-glycol conversion at scale. Cargill, Incorporated anchors Midwestern US supply through its established biorefinery network and agricultural feedstock procurement. DuPont Tate & Lyle Bio Products Company, LLC differentiates via dedicated bio-based diol technology leadership and pharmaceutical-grade certification.
Biobased propylene glycol denotes a C3 diol synthesized from renewable feedstocks such as glycerol or plant-derived sugars via hydrogenolysis or fermentation pathways, typically achieving purity above 99.5% with a molecular weight of 76.09 g/mol and serving as a low-toxicity solvent, humectant, and carrier fluid across consumer and industrial formulations. Industrial grade dominates current volume flows into chemical manufacturing and anti-freeze compounding, while pharmaceutical grade commands concentrated margin pools due to USP and EP compliance burdens. Food grade applications within the food additive segment are expanding fastest as clean-label pressures displace synthetic alternatives in flavor and color extraction processes.
The EPA administers TSCA oversight for renewable chemical commercialization in the United States, while REACH registration requirements in Europe govern bio-based substance hazard communication and downstream user obligations. FDA food additive and GRAS determinations shape North American ingestible applications, with EMA and EFSA pharmaceutical guidelines influencing excipient qualification across Atlantic markets. Stakeholders must monitor feedstock cost volatility, certification timeline compression, and the evolving stringency of biobased content thresholds in public procurement frameworks.
Market Dynamics
REACH registration deadlines and the EU Green Deal's petrochemical substitution mandates are compressing certification timelines while concentrating production capacity in German industrial biotech clusters.
Growth Catalysts
- EU Green Deal mandates:Binding biobased content thresholds in public procurement frameworks accelerate displacement of synthetic glycols across member states.
- Clean-label food additive demand:Food and beverage manufacturers expand solvent and humectant applications to meet consumer preference for natural-derived formulations.
- Hydrogenolysis pathway maturation:Commercial-scale glycerol-to-propylene-glycol conversion achieves cost parity with petrochemical routes in integrated biorefinery settings.
Market Restraints
- Feedstock cost volatility:Crude glycerol prices fluctuate with biodiesel production cycles, compressing margin predictability for standalone producers.
- Specialized biochemical engineering scarcity:North American and European production hubs face collapsing talent pools, extending plant expansion timelines.
- Petroleum propylene glycol substitution threat:Established synthetic supply chains retain cost advantages in price-sensitive anti-freeze and industrial solvent segments.
Strategic Opportunities
- Pharmaceutical-grade certification expansion:USP and EP compliance burdens create concentrated margin pools for dedicated bio-based diol technology leaders.
- Midwestern US biorefinery network leverage:Agricultural feedstock procurement advantages position the region for captive supply integration into chemical manufacturing.
- Flavor and color extraction applications:Clean-label pressures in food processing open fastest-expanding volume channels for food grade biobased glycol displacement.
Industry Challenges
- Biochemical process engineering talent pipeline collapse:Universities produce insufficient graduates with hydrogenolysis and fermentation scale-up expertise.
- Multi-jurisdiction certification timeline compression:Simultaneous FDA GRAS, EFSA food additive, and REACH registration submissions strain regulatory affairs capacity.
- Legacy petrochemical equipment retrofit complexity:Existing propylene glycol plants require substantial capital reconfiguration to handle renewable feedstock variability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biobased Propylene Glycol Market |
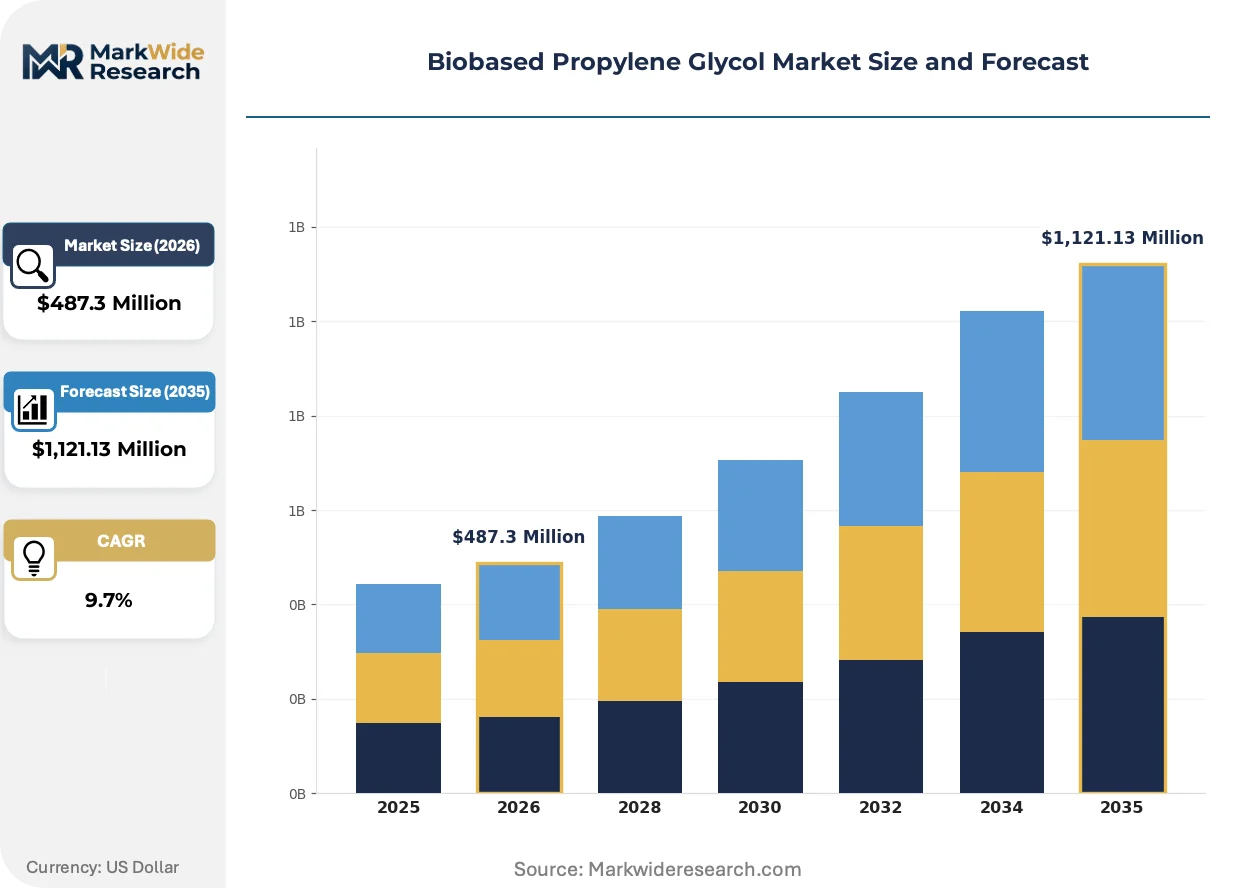
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,121.13 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Cosmetic Grade End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Chemical Manufacturing Distribution Channel: Online, Retail, Wholesalers, Direct Sales Application: Food Additive, Solvent, Humectant, Anti-freeze |
| Companies Covered | Archer Daniels Midland Company, BASF SE, Dow Chemical Company, Cargill, Incorporated, Huntsman Corporation, DuPont Tate & Lyle Bio Products Company, LLC, Global Bio-chem Technology Group Company Limited, LyondellBasell Industries N.V., UPM Biochemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biobased Propylene Glycol Market Strategic Shifts
Process intensification and regulatory stringency are bifurcating the competitive landscape between integrated biorefinery operators and standalone specialty chemical producers.
Continuous hydrogenolysis reactor designs are bifurcating the technology base between high-throughput fixed-bed systems and modular micro-reactor configurations. Pharmaceutical manufacturers adopt micro-reactor output for batch traceability, while chemical manufacturers favor fixed-bed scale. This technology split is bifurcating supplier qualification requirements and fragmenting equipment vendor relationships.
REACH registration requirements for bio-based substances are tightening hazard communication obligations and downstream user documentation burdens. ECHA's evolving guidance on renewable chemical classification forces reformulation disclosure across complex supply chains. Food grade and pharmaceutical grade segments face the steepest compliance cost escalation as safety data sheet requirements expand beyond petrochemical precedent.
Clean-label procurement specifications now mandate biobased content verification through third-party certification schemes. Food and beverage manufacturers audit supplier carbon-14 testing protocols, displacing traditional synthetic glycol contracts. Germany's industrial biotech clusters and US Midwest agricultural processing hubs concentrate this procurement pattern shift, with buyers consolidating supplier panels to reduce audit burden.
Biobased Propylene Glycol Market Segmentation
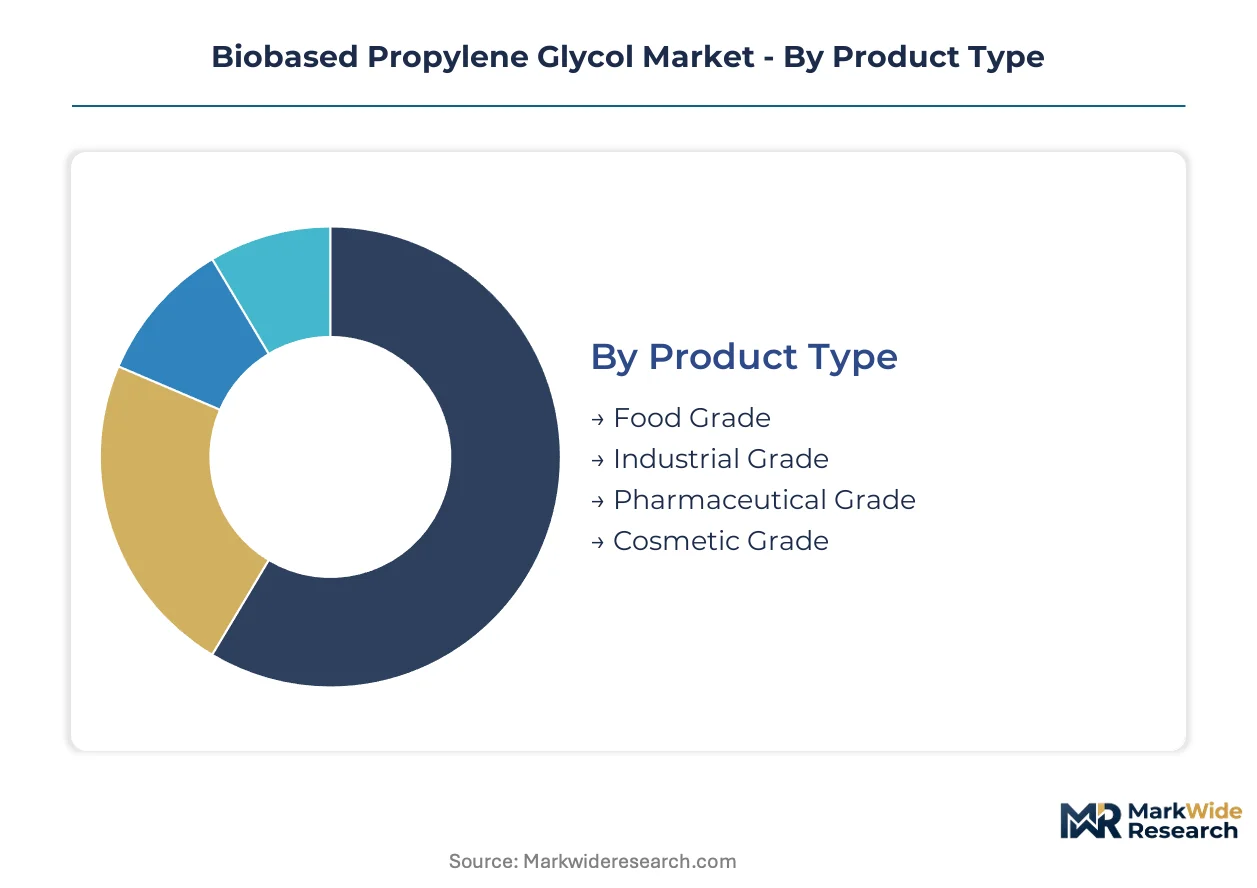
Regulatory grade requirements fragment the biobased propylene glycol market into distinct certification tiers, each commanding separate supply chains and margin structures. Product type differentiation determines access to pharmaceutical, food, and industrial end-use markets with non-overlapping compliance burdens.
Product Type:
REACH registration deadlines and FDA GRAS determinations create divergent certification timelines across purity grades, concentrating pharmaceutical and food grade production in integrated biorefinery settings with dedicated quality systems.
- Pharmaceutical Grade:USP and EP compliance mandates batch traceability and residual solvent controls exceeding 99.5% purity thresholds. Demand concentrates in parenteral formulation manufacturing across Germany and the United States, where EMA and FDA inspections enforce excipient qualification protocols that disqualify lower-tier suppliers.
- Food Grade:EFSA food additive approvals and carbon-14 verification requirements govern clean-label procurement specifications. Adoption expands most quickly in flavor extraction and natural color carrier applications as European and North American beverage manufacturers displace synthetic alternatives.
- Industrial Grade:Anti-freeze compounding and polyester resin manufacturing absorb volume flows without pharmaceutical or food contact restrictions.
- Cosmetic Grade:Personal care formulators specify intermediate purity for humectant and solvent functions in topical preparations.
Established volume favors Industrial Grade; emerging adoption favors Food Grade.
End Use Industry:
Customer procurement patterns split between bulk chemical manufacturers seeking cost-optimized supply and pharmaceutical sponsors requiring audit-ready documentation packages.
- Pharmaceuticals:Parenteral drug sponsors mandate excipient master files and supplier qualification audits that extend onboarding timelines. German and US formulation facilities dominate procurement concentration due to EMA and FDA inspection density.
- Food & Beverage:Clean-label commitments drive solvent and humectant substitution in flavor systems, with carbon footprint verification now standard in supplier selection criteria.
- Chemical Manufacturing:Polyester resin and unsaturated polymer producers specify industrial grade for cost-sensitive volume applications.
- Cosmetics:Personal care brands prioritize biobased content marketing claims over purity premiums in moisturizer and serum formulations.
Pharmaceuticals capture premium pricing; Food & Beverage climbs the fastest.
Distribution Channel:
Channel selection reflects order scale and technical service requirements, with pharmaceutical and food grade transactions favoring direct manufacturer relationships over intermediaries.
- Direct Sales:Pharmaceutical sponsors and multinational food manufacturers negotiate frame contracts with dedicated account management and regulatory documentation support. BASF SE and Cargill anchor this channel through captive production networks.
- Wholesalers:Regional chemical distributors aggregate industrial grade volume for anti-freeze compounders and small-batch resin manufacturers.
- Online:Specialty chemical marketplaces facilitate cosmetic grade and small-volume industrial procurement with limited technical support.
- Retail:Consumer-facing channels capture negligible share, limited to hobbyist and artisanal cosmetic formulators.
Direct Sales commands margin concentration; Wholesalers handle volume aggregation.
Application:
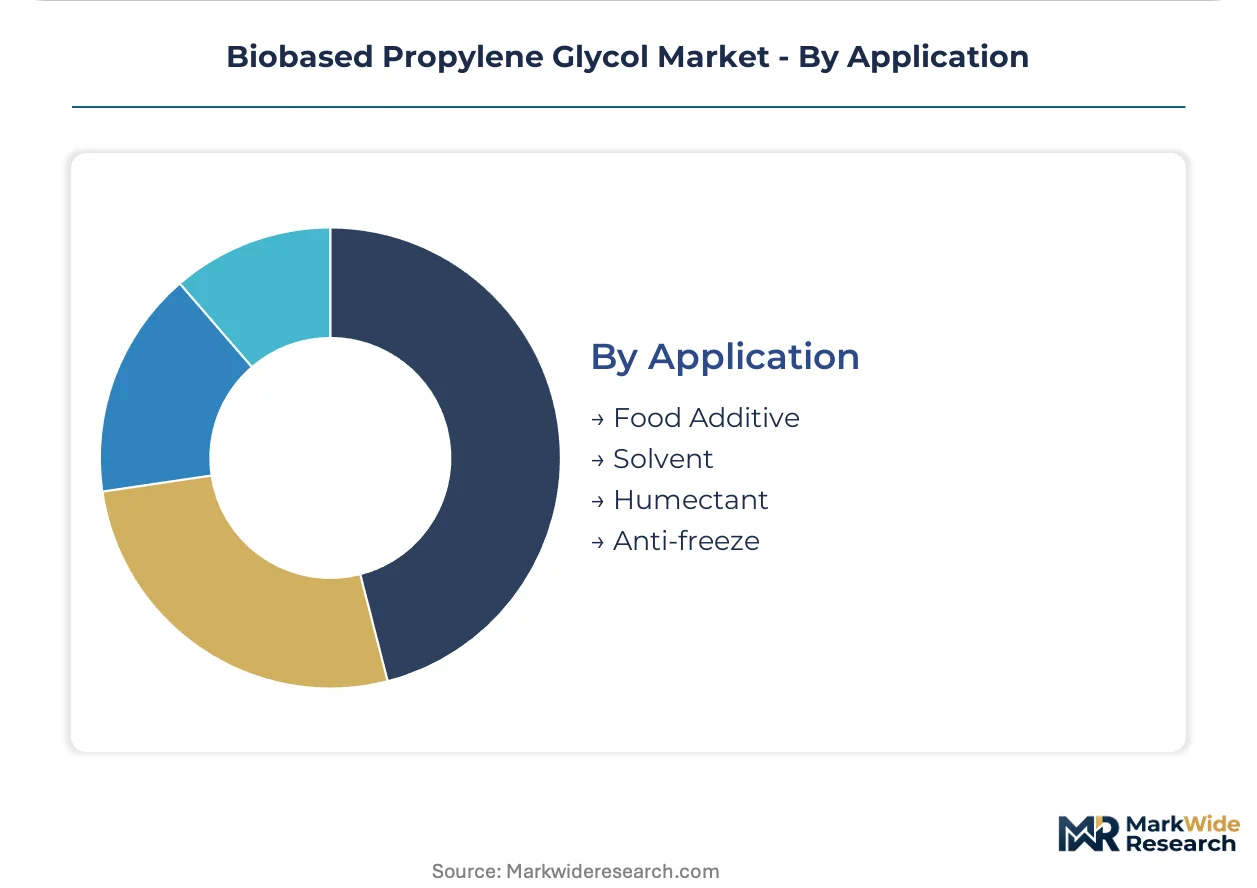
Functional performance requirements determine grade selection, with solvent and humectant functions tolerating broader purity ranges than parenteral or ingestible applications.
- Solvent:Flavor and color extraction processes in clean-label food manufacturing specify food grade purity with documented renewable feedstock provenance. European beverage producers drive specification tightening through procurement audit protocols.
- Humectant:Moisture retention functions in pharmaceuticals and cosmetics require hygroscopic stability testing that pharmaceutical grade suppliers document through USP monograph compliance.
- Food Additive:Direct ingestion applications face EFSA and FDA additive approval requirements that constrain supplier qualification to dedicated biorefinery operators.
- Anti-freeze:Industrial de-icing and heat transfer fluid compounding absorbs lowest-cost industrial grade output without food contact or pharmaceutical restrictions.
Solvent applications scale fastest; Anti-freeze retains volume dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates pharmaceutical-grade consumption through its Ludwigshafen chemical cluster, while the United States splits demand between Midwestern agricultural processing and coastal pharmaceutical formulation. China and India import technical-grade volumes for polyester manufacturing, diverging from Atlantic regulatory-grade procurement patterns.
Germany
Pharmaceutical excipient demand concentrates around Ludwigshafen and Leverkusen, where EMA inspection density enforces USP-grade procurement. REACH registration deadlines and the EU Green Deal's biobased substitution mandates compress supplier qualification timelines. The country's industrial biotech clusters anchor commercial-scale glycerol-to-propylene-glycol conversion through integrated refinery infrastructure.
United States
Midwestern agricultural processing hubs in Iowa and Illinois supply crude glycerol feedstock to captive conversion facilities, while New Jersey and Massachusetts pharmaceutical sponsors drive USP-grade demand. FDA GRAS determinations and EPA TSCA oversight govern renewable chemical commercialization. The Midwestern biorefinery network leverages proximity to soybean biodiesel production for feedstock cost advantages.
China
Polyester resin manufacturers in Jiangsu and Zhejiang provinces absorb industrial-grade volume for unsaturated polymer compounding. The country's dual carbon goals and MIIT industrial policy guidance incentivize renewable chemical capacity additions. Yangtze River Delta chemical parks attract glycerol hydrogenolysis investments from state-owned refinery operators seeking petrochemical diversification.
India
Biodiesel production in Maharashtra and Gujarat generates crude glycerol byproduct for emerging biobased glycol conversion projects. CDSCO pharmaceutical regulations and FSSAI food additive approvals constrain supplier qualification to dedicated quality systems. The country's PLI scheme for renewable chemicals supports capacity buildout in western industrial corridors.
France
Cosmetic formulators in Île-de-France specify biobased humectants for clean-label moisturizer and serum marketing claims. ANSM pharmaceutical oversight and ECHA REACH enforcement tighten hazard communication obligations for renewable substance imports. The country's perfume and personal care manufacturing base drives intermediate-purity procurement with carbon-14 verification requirements.
Biobased Propylene Glycol Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with consolidated capacity controlling pharmaceutical-grade certification while fragmented standalone operators serve industrial applications. The market structure bifurcates between captive biorefinery conversion and merchant specialty chemical supply. Three archetypes dominate: integrated agricultural processors with backward glycerol control, diversified chemical conglomerates with hydrogenolysis licensing, and dedicated bio-based diol technology specialists. Competitive moves center on capacity expansion in German and US Midwest clusters alongside strategic partnerships for pharmaceutical-grade distribution.
Within the integrated processor archetype, Cargill, Incorporated and Archer Daniels Midland Company occupy positions defined by agricultural feedstock procurement scale and captive biodiesel glycerol streams. BASF SE anchors the diversified chemical tier through its Ludwigshafen complex, exemplifying integrated refinery economics. DuPont Tate & Lyle Bio Products Company, LLC represents the dedicated specialist position, sitting within a technology-focused segment emphasizing pharmaceutical-grade certification and bio-based diol purity leadership.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| BASF SE |
| Dow Chemical Company |
| Cargill, Incorporated |
| Huntsman Corporation |
| DuPont Tate & Lyle Bio Products Company, LLC |
| Global Bio-chem Technology Group Company Limited |
| LyondellBasell Industries N.V. |
| UPM Biochemicals |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day pharmaceutical-grade qualification timelines compress working capital cycles and amplify pricing power for integrated German and US Midwest producers with captive glycerol streams. This lead-time band concentrates contract negotiation leverage among biorefinery operators while forcing standalone converters toward spot-market exposure.
Pricing Analysis
Long-term offtake agreements dominate pharmaceutical-grade procurement, with frame contracts spanning multi-year horizons securing batch-traceable supply against USP and EP compliance burdens. Three-tier pricing structure across pharmaceutical, food, and industrial grades reflects certification cost pass-through rather than manufacturing complexity alone. Pricing pressure stems from crude glycerol volatility tied to biodiesel production cycles, compressing margin predictability for non-integrated producers. Chemical manufacturers in anti-freeze and polyester resin applications exhibit highest price sensitivity, while parenteral drug sponsors absorb premiums for excipient master file documentation.
Supply Chain Analysis
Forty-five-day inventory buffers at Ludwigshafen and Iowa biorefinery hubs contrast with hand-to-mouth procurement patterns among Asian polyester manufacturers. Supply concentrates in Germany, the United States, and China, with the first two anchoring pharmaceutical-grade output through EMA and FDA inspection density. Feedstock flows draw from soybean biodiesel byproduct streams in the Midwest and rapeseed-derived crude glycerol in European clusters. Single-source vulnerability runs through glycerol hydrogenolysis catalyst supply chains dominated by specialty chemical licensors. Distribution runs through direct manufacturer relationships for regulated grades and regional chemical wholesalers for industrial volume aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH deadline compression and clean-label procurement mandates fragment supplier qualification requirements, creating service-layer niches between integrated biorefinery giants and commodity chemical distributors.
For Market Incumbents: Compound certification advantages by deepening backward integration into agricultural glycerol procurement and expanding dedicated USP-grade reactor capacity in German clusters. Petrochemical substitution threats from established synthetic glycol supply chains demand defensive frame-contract pricing to lock pharmaceutical sponsor relationships before 2027 REACH enforcement windows tighten. For New Entrants and Emerging Players: Regulatory documentation outsourcing represents a service-layer gap where incumbents under-serve mid-tier food and beverage manufacturers facing simultaneous FDA GRAS, EFSA additive, and carbon-14 verification requirements. Target Midwestern US flavor extraction facilities with modular micro-reactor output offering batch traceability without integrated refinery capital intensity. Go-to-market leverage rests on audit-ready documentation packages rather than purity premiums alone. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because biobased content thresholds in public procurement frameworks are hardening across EU member states and select US states, entrenching first-mover certification advantages. Acquisition targets center on dedicated bio-based diol technology specialists with existing pharmaceutical-grade monograph compliance rather than biodiesel operators seeking glycerol valorization. The signal to watch is ECHA guidance expansion on renewable chemical classification, which would accelerate compliance cost escalation and consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Glycerol | Captive feedstock supply from Iowa and Illinois biodiesel clusters insulates margin volatility from commodity price swings. |
| Pharmaceutical-Grade Certification Expansion | USP and EP compliance investments create defensible positioning against EMA inspection density in German formulation hubs. |
| Modular Micro-Reactor Deployment | Continuous hydrogenolysis units serving flavor extraction applications address clean-label procurement without refinery-scale capital. |
| Long-term Supply Agreement with Beverage Multinationals | Frame contracts with carbon-14 verification requirements lock procurement panels ahead of EU Green Deal enforcement. |
| Joint Venture with Biodiesel Operators | Partnerships in Maharashtra and Gujarat convert crude glycerol byproduct streams under CDSCO and FSSAI regulatory pathways. |
Study Parameters
The analysis maps pharmaceutical-grade, food-grade, industrial-grade, and cosmetic-grade production tiers, each validated through interviews with biorefinery plant managers, downstream chemical procurement leads at polyester manufacturers, distribution channel partners, and regulatory affairs directors at excipient qualification firms. Secondary validation draws from ECHA REACH registration databases, FDA GRAS notification filings, SEC 10-K disclosures from diversified chemical conglomerates, and customs trade flow records. Bottom-up capacity estimates triangulate against top-down demand modeling from end-use industry consumption patterns.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models grade tier, end-use industry, and regional production hub segmentation dimensions. CAGRs derive from feedstock cost trajectory assumptions, certification timeline compression effects, and petrochemical substitution elasticity parameters. Industry-specific inputs include biodiesel production cycle correlations with crude glycerol pricing and EMA inspection density proxies for pharmaceutical-grade demand concentration.
Forecasts assume regulatory continuity in EU REACH and US FDA frameworks; material policy shifts in biobased content thresholds or renewable chemical classification guidance would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Ethylhexane Diol Market
Specialty Chemicals
Cellulose Acetate Phthalate Market
Specialty Chemicals
UV/IR Blocker Market
Specialty Chemicals
Caryophyllene Market
Specialty Chemicals
Electrical Insulating Varnish for Motor Vehicle Market
Specialty Chemicals
Acesulfame Potassium Market
Specialty Chemicals
Ascorbic Acid Market
Specialty Chemicals
North America Non-Phthalate Plasticizers Market
Specialty Chemicals
Homosalate Market
Specialty Chemicals
Microcrystalline Wax Market
Specialty Chemicals
Silver Iodide Market
Specialty Chemicals
Polyimide Varnish Market
Specialty Chemicals
Antifouling Agent Market
Specialty Chemicals
Europe Optical Brighteners Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Non-Commercial Acrylic Paints Market