
 Global Smart Coating Market | 2026-2036
Global Smart Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Coating Market Foresight
Market Context with Strategic Players
ISO 12944 corrosion-protection certification is unwinding competitive access across marine and infrastructure coating procurement. PPG Industries leverages captive resin synthesis and laboratory networks across the United States, Germany, and China to sustain specification dominance in aerospace OEM channels. AkzoNobel N.V. anchors European marine demand through Rotterdam-based supply architecture and deepwater vessel relationships. Jotun competes aggressively in Southeast Asian shipyard clusters through localized technical service teams and direct applicator training programs.
Technical Definition and Structural Segments
Smart coatings constitute engineered surface treatments that autonomously respond to environmental stimuli—temperature, light, pH, or mechanical stress—through embedded microcapsules, nanoscale fillers, or stimuli-responsive polymer matrices, primarily serving to extend asset life and reduce maintenance cycles in high-value substrates. Anti-corrosion formulations and self-healing systems currently occupy the deepest margin pools, as infrastructure developers and marine operators prioritize lifecycle cost reduction over upfront material expenditure. Nanotechnology-based deposition methods are expanding fastest among fabrication routes, though microencapsulation retains manufacturing scale advantages for consumer electronics and packaging applications where uniform shell integrity governs performance.
Regulatory Frame and Forward-Looking Close
REACH registration requirements in Europe, EPA VOC limits in the United States, and China's GB standards for industrial emissions collectively constrain solvent-borne formulation options while accelerating waterborne and powder smart coating development. ECHA substance evaluation and EPA New Chemicals Program reviews extend commercialization timelines for novel responsive polymers, favoring incumbents with established regulatory dossiers. Stakeholders must monitor evolving PFAS restrictions across multiple jurisdictions, as fluorinated hydrophobic chemistries face substitution pressure that will redirect R&D investment toward silicone and bio-based alternatives.
Market Dynamics
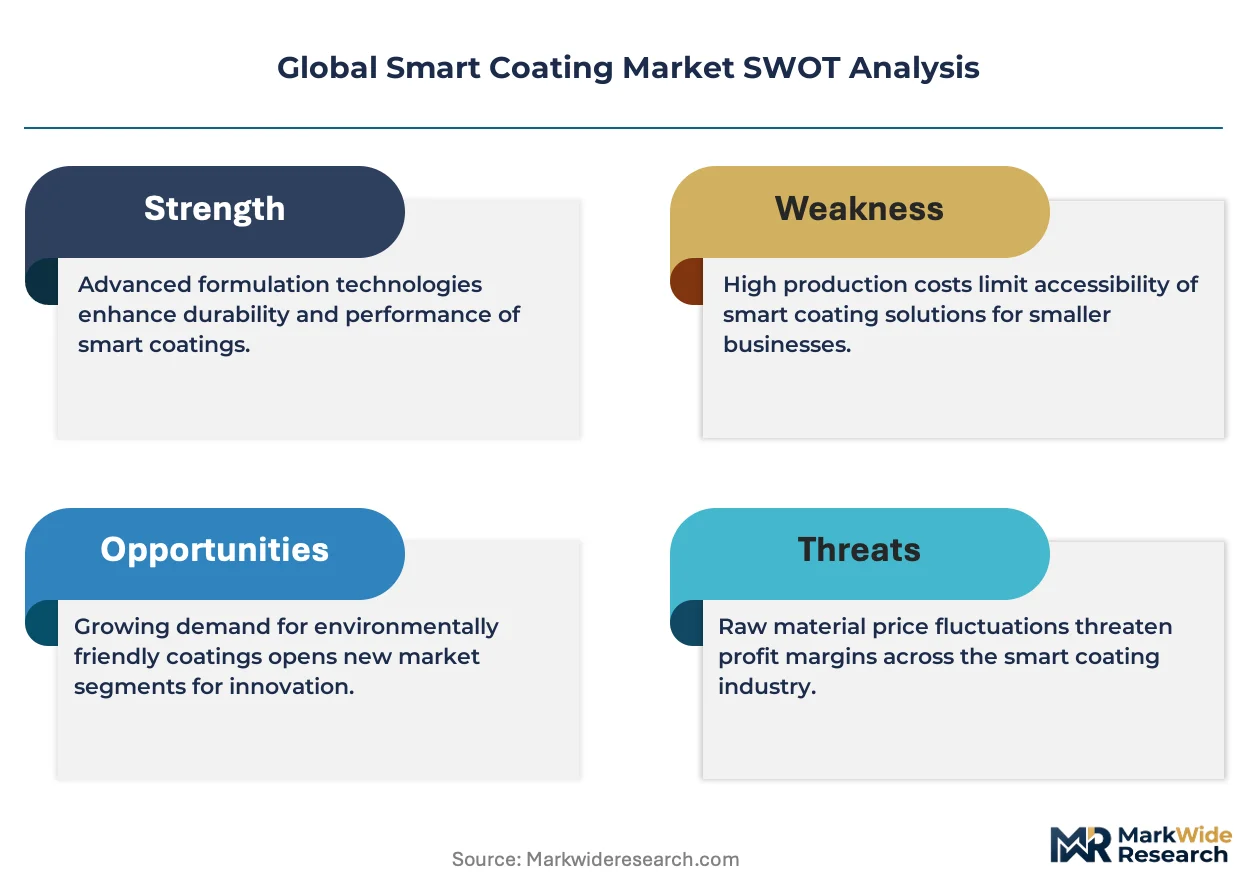
Stimuli-responsive polymer chemistry is forcing a recalibration of coating procurement economics as lifecycle cost modeling supersedes unit-price evaluation across marine and infrastructure verticals.
Growth Catalysts
- REACH substance evaluation:European ECHA registration requirements are accelerating waterborne formulation R&D, creating first-mover advantages for compliant suppliers in Rotterdam and Hamburg port clusters.
- Aerospace OEM specification:ISO 12944 certification is becoming mandatory for corrosion-protection coatings on commercial aircraft structures, tightening qualification pathways for incumbent suppliers.
- China marine fleet expansion:Domestic shipyard capacity growth in Dalian and Shanghai is concentrating demand for anti-fouling smart coatings with embedded microcapsule release systems.
Market Restraints
- Fluorinated chemistry substitution:PFAS restrictions across EU member states and US state-level bans are compressing hydrophobic coating margins as silicone alternatives require reformulation investment.
- Specialized applicator scarcity:Nanotechnology deposition methods demand certified technicians, creating supply bottlenecks in Southeast Asian shipyard clusters where training infrastructure remains underdeveloped.
- Raw material concentration:Captive resin synthesis capabilities concentrate among three multinational suppliers, exposing regional formulators to input cost volatility and allocation risk.
Strategic Opportunities
- India infrastructure pipeline:National highway and bridge construction programs under the Ministry of Road Transport and Highways are creating specification windows for self-healing concrete coatings.
- Consumer electronics integration:Microencapsulation for packaging and device protection is converging with printed electronics manufacturing, opening deposition partnerships with South Korean display producers.
- EU Green Deal procurement mandates:Public infrastructure tenders in Germany and France are embedding lifecycle carbon metrics that favor bio-based polymer matrices over petrochemical alternatives.
Industry Challenges
- Regulatory dossier timelines:EPA New Chemicals Program reviews for novel responsive polymers extend commercialization by 18-24 months, compressing patent exploitation windows.
- Cross-functional talent gaps:Formulation chemistry expertise must now integrate nanomaterials handling and stimuli-response modeling, a combination scarce in traditional coating labor pools.
- Legacy substrate compatibility:Self-healing systems face integration complexity with existing marine coating stacks, requiring blast-and-recoat protocols that disrupt drydock scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Coating Market |
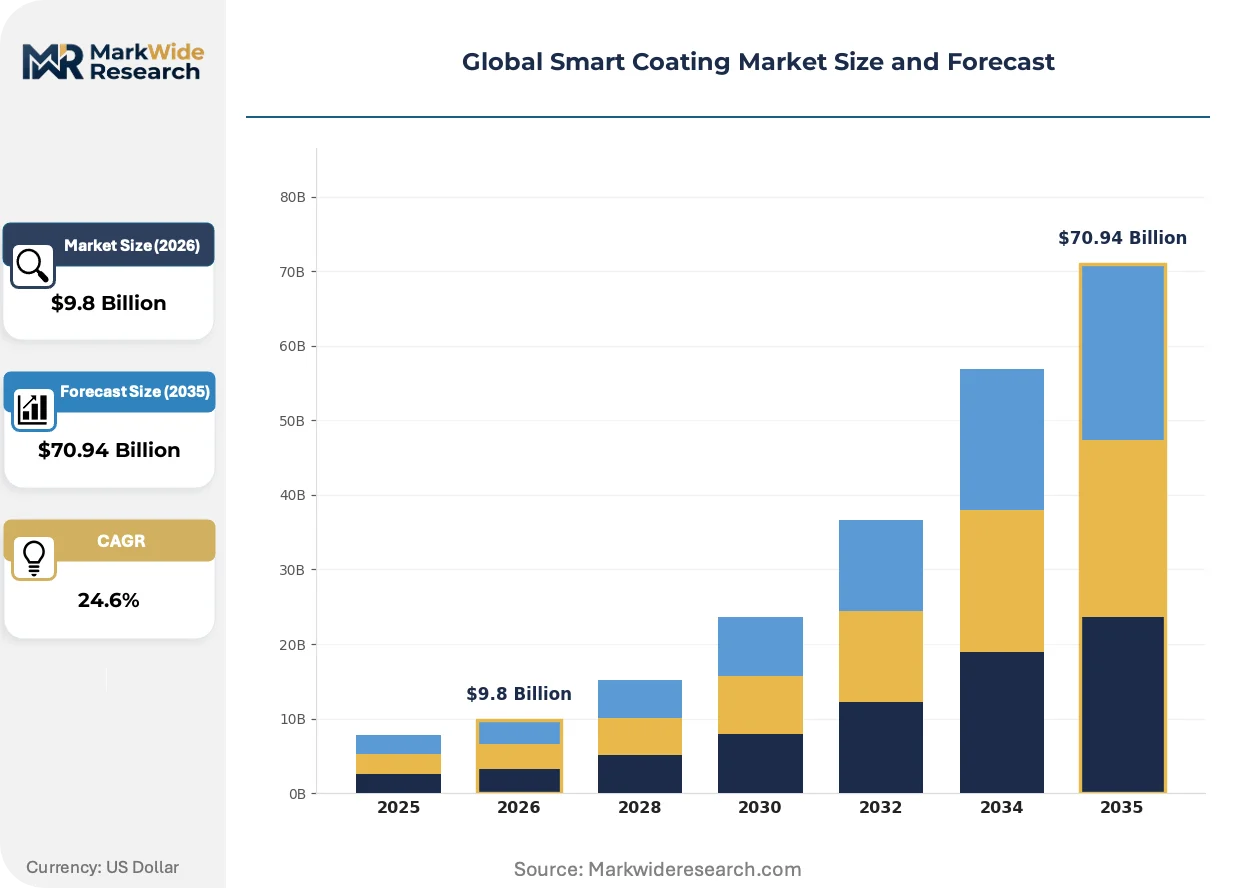
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $70.94 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Healing Coatings, Photochromic Coatings, Thermochromic Coatings, Anti-Corrosion Coatings, Anti-Fouling Coatings Technology: Microencapsulation, Nanotechnology, Sol-Gel Process, Polymer Blending, Layer-by-Layer Assembly Application: Construction Surfaces, Marine Protection, Aerospace Components, Consumer Electronics, Packaging Materials End User: OEMs, Aftermarket Providers, Equipment Manufacturers, Infrastructure Developers, Facility Management |
| Companies Covered | PPG Industries, DuPont, The Sherwin-Williams Company, Jotun, Hempel A/S, 3M, Axalta Coating Systems, RPM International, AkzoNobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Coating Market Shifts & Advancements
Responsive functionality is migrating from protective coatings into active surface management systems, embedding sensing and actuation capabilities that transform maintenance economics across capital-intensive assets.
Photocatalytic self-cleaning technology is fragmenting application methodologies across architectural glass and transportation infrastructure. Titanium dioxide nanocrystal deposition is gaining traction among European facade contractors seeking reduced cleaning-cycle frequency. The technology is fragmenting specification standards as regional certifiers develop divergent performance benchmarks for urban air quality remediation claims.
China's GB standards for industrial emissions are tightening VOC thresholds for solvent-borne marine coatings, accelerating powder smart coating development among domestic formulators. MEE enforcement in Shanghai and Tianjin port zones is compressing compliance timelines for existing product lines. Shipyard operators are responding with accelerated waterborne system trials during scheduled drydock maintenance windows.
Asset-owner procurement departments are consolidating coating specification authority from maintenance divisions into centralized engineering functions, compressing supplier relationship structures. Long-term performance guarantees are displacing unit-price contracting in North American pipeline and tank farm projects. This concentration is most visible in Gulf Coast petrochemical complexes where integrated operators demand unified coating system warranties across facility footprints.
Global Smart Coating Market Segmentation
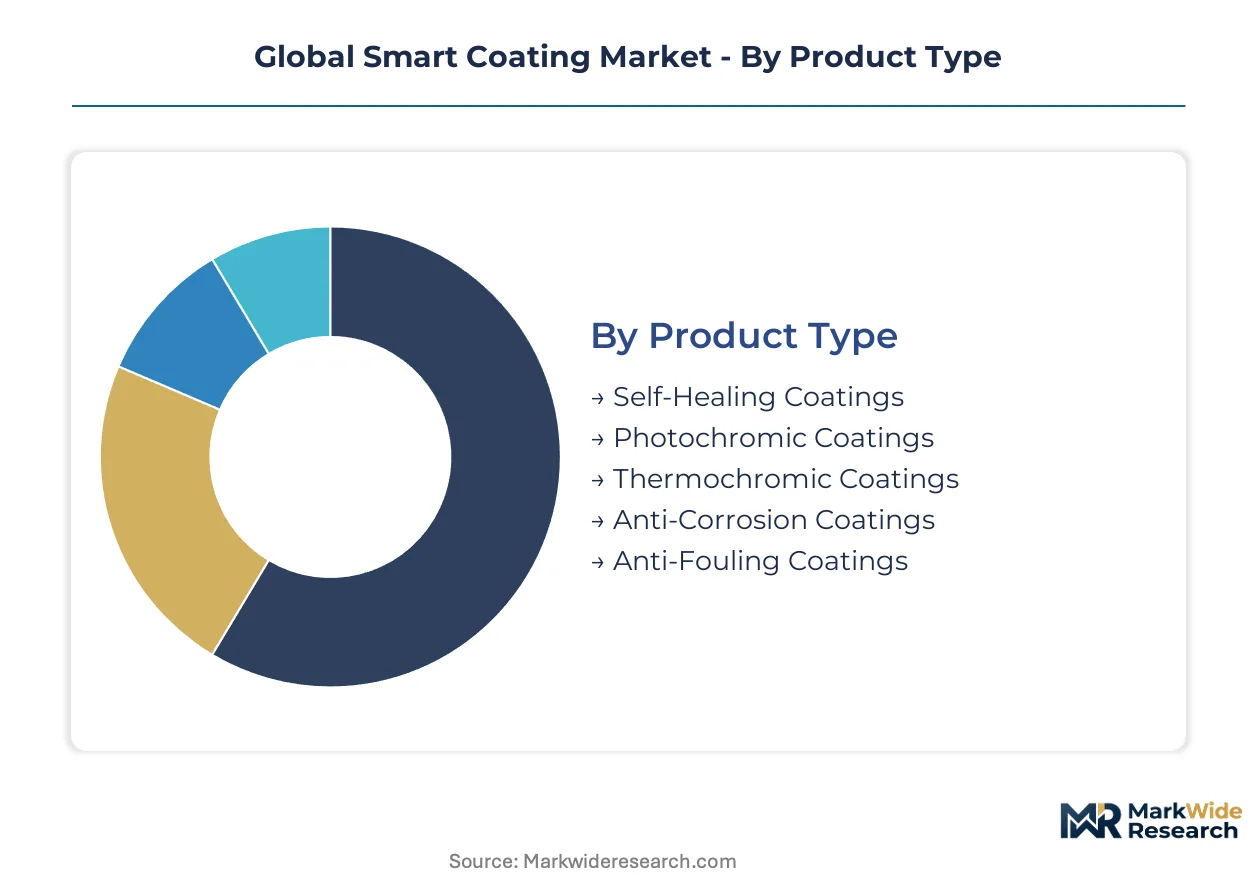
Smart coating procurement diverges sharply across functional requirements and substrate complexity, with formulation chemistry and deposition technology determining addressable contract value. Margin capture concentrates where responsive functionality intersects high-asset-value verticals willing to underwrite lifecycle performance guarantees.
Product Type:
Anti-corrosion and self-healing formulations command the deepest margin pools, as infrastructure developers and marine operators prioritize total cost of ownership over unit material pricing.
- Self-Healing Coatings:Embedded microcapsule systems release healing agents upon crack propagation, restoring barrier integrity in concrete and polymer substrates. Demand concentrates in German bridge infrastructure and Gulf Coast petrochemical facilities where maintenance access costs dwarf material expenditure.
- Anti-Corrosion Coatings:Stimuli-responsive polymer matrices with pH-sensitive inhibitors dominate marine and offshore specifications. Rotterdam port operators and Dalian shipyards are consolidating procurement around ISO 12944-certified systems with embedded corrosion sensing capability.
- Photochromic Coatings:Light-responsive molecular switches for architectural glazing and eyewear applications.
- Thermochromic Coatings:Temperature-indicating layers for industrial equipment and safety-critical surfaces.
- Anti-Fouling Coatings:Biocide-release microcapsule systems for vessel hulls facing tightening MEE enforcement in Chinese port zones.
Anti-corrosion formulations hold installed capacity across European marine infrastructure. Self-healing systems are rotating up the share rankings in North American pipeline specifications.
Technology:
Deposition method selection determines manufacturing scale ceiling and responsive fidelity, with nanotechnology commanding premium positioning in electronics integration while microencapsulation retains cost advantages in marine volume applications.
- Nanotechnology:Atomic-layer deposition and self-assembled monolayers enable sub-micron responsive precision for consumer electronics and aerospace sensor integration. South Korean display manufacturers are qualifying nanocoating partners for foldable device protection, though certified technician scarcity constrains Southeast Asian expansion.
- Microencapsulation:Shell-core particle engineering delivers controlled-release functionality at industrial scale. Chinese domestic formulators are scaling waterborne microcapsule lines to meet GB standard VOC thresholds in Shanghai and Tianjin port maintenance windows.
- Sol-Gel Process:Inorganic-organic hybrid networks for high-temperature and UV-stable applications.
- Polymer Blending:Multi-phase matrix engineering for cost-responsive formulation tuning.
- Layer-by-Layer Assembly:Electrostatic deposition for ultra-thin functional stacks in medical and optical devices.
Microencapsulation retains volume leadership in marine procurement. Nanotechnology is climbing the fastest in electronics specification pipelines.
Application:
End-use verticals separate by asset criticality and maintenance economics, with aerospace and marine commanding qualification-intensive supply relationships while construction surfaces offer volume scale through project bundling.
- Marine Protection:Hull and ballast tank systems integrating anti-fouling and corrosion management. Dalian and Shanghai shipyard clusters are consolidating drydock specification authority, compressing supplier relationships toward integrated system warranties.
- Aerospace Components:Structural and engine coatings with embedded health monitoring. FAA certification pathways and OEM specification lock-in favor incumbent suppliers with established regulatory dossiers.
- Construction Surfaces:Facade and infrastructure treatments including photocatalytic self-cleaning titanium dioxide systems.
- Consumer Electronics:Device protection and printed electronics integration through microencapsulated barrier layers.
- Packaging Materials:Active and intelligent packaging with freshness indication and tamper evidence.
Marine protection holds installed specification authority in Asian shipyard clusters. Aerospace components are gaining share fastest in OEM qualification pipelines.
End User:
Procurement authority concentration varies by vertical maturity, with infrastructure developers consolidating engineering specification control while equipment manufacturers retain fragmented maintenance purchasing.
- Infrastructure Developers:National highway authorities and port operators bundling coating systems into design-build contracts. India's Ministry of Road Transport and Highways is embedding self-healing concrete specifications into bridge construction tenders.
- OEMs:Original equipment manufacturers specifying integrated coating-warranty systems. Gulf Coast petrochemical operators are demanding unified coating guarantees across facility footprints.
- Aftermarket Providers:Maintenance contractors executing blast-and-recoat protocols in scheduled drydock and turnaround windows.
- Equipment Manufacturers:Industrial machinery builders sourcing protective treatments for new equipment.
- Facility Management:Building operators procuring responsive facade and interior surface treatments.
Infrastructure developers hold procurement authority concentration in public project pipelines. OEMs are rotating up the specification influence rankings in integrated industrial complexes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH substance evaluation and EPA VOC limits are redirecting formulation investment toward waterborne and powder systems across industrialized economies. China's GB standards for industrial emissions are compressing compliance timelines for solvent-borne marine coatings. India's infrastructure pipeline is embedding lifecycle performance specifications into public procurement frameworks.
United States
Gulf Coast petrochemical operators are consolidating coating specification authority into centralized engineering functions. EPA New Chemicals Program reviews extend commercialization timelines for novel responsive polymers by 18-24 months. Houston and Corpus Christi facility footprints now demand unified coating system warranties across integrated operations.
Germany
Bridge infrastructure developers prioritize self-healing concrete coatings that reduce maintenance access expenditures. EU Green Deal procurement mandates embed lifecycle carbon metrics favoring bio-based polymer matrices. The Ruhr industrial corridor and Hamburg port clusters are driving specification windows for ISO 12944-certified corrosion protection systems.
China
Domestic shipyard capacity expansion in Dalian and Shanghai concentrates demand for anti-fouling smart coatings with embedded microcapsule release. MEE enforcement in Tianjin port zones accelerates waterborne system trials during scheduled drydock maintenance. GB standard VOC thresholds are compressing legacy product line viability among domestic formulators.
India
National highway and bridge construction programs under the Ministry of Road Transport and Highways create specification entry points for self-healing surface treatments. BIS certification requirements are tightening qualification pathways for imported coating systems. Mumbai and Gujarat industrial corridors are emerging as procurement concentration zones for infrastructure-grade responsive coatings.
South Korea
Display manufacturers are qualifying nanocoating partners for foldable device protection applications. MFDS regulatory frameworks govern coating safety assessments for consumer electronics integration. Seoul and Gyeonggi-do manufacturing clusters are driving deposition technology partnerships with microencapsulation specialists.
Global Smart Coating Market Competitive Landscape
Player mix skews toward multinational integrated coating suppliers with captive resin synthesis capabilities and established regulatory dossiers. Market structure concentrates specification influence among three to five vertically positioned suppliers holding ISO 12944 certification and aerospace OEM approvals. Strategic archetypes include integrated resin-coating formulators, regional marine specialists with localized technical service networks, and nanotechnology licensors targeting electronics integration. Dominant competitive moves encompass backward integration into specialty resin production and geographic expansion through technical service team deployment in Asian shipyard clusters.
Among North American integrated suppliers, PPG Industries and The Sherwin-Williams Company exemplify the resin-captive formulator archetype with specification lock-in across aerospace OEM channels. AkzoNobel N.V. anchors the European marine specialist position through Rotterdam-based supply architecture and established deepwater vessel relationships. Jotun occupies a competitive position in Southeast Asian shipyard clusters through direct applicator training programs and localized technical presence.
| Leading Market Players |
|---|
| PPG Industries |
| DuPont |
| The Sherwin-Williams Company |
| Jotun |
| Hempel A/S |
| 3M |
| Axalta Coating Systems |
| RPM International |
| AkzoNobel N.V. |
| Others |
Supply & Pricing Matrix
ISO 12944 certification gates both supply qualification and price differentiation simultaneously, as marine and aerospace buyers withhold procurement authority from uncertified formulators while paying premiums for compliant systems with embedded sensing capability.
Pricing Analysis
Certification level creates the primary spread across smart coating procurement, with ISO 12944-certified systems commanding substantial premiums over uncertified alternatives in Rotterdam and Hamburg port clusters. Three-tier pricing structure separates aerospace OEM-grade formulations from industrial marine specifications and commodity construction treatments. Cost compression in standard-grade marine coatings is intensifying because Chinese domestic formulators are scaling waterborne microcapsule lines to meet GB standard VOC thresholds. Infrastructure developers exhibit the highest price sensitivity, while aerospace OEMs prioritize lifecycle performance guarantees over unit material expenditure.
Supply Chain Analysis
Captive resin synthesis capabilities concentrate among multinational suppliers in the United States, Germany, and China, exposing regional formulators to input cost volatility when specialty polymer allocations tighten. Raw material dependencies center on stimuli-responsive polymer precursors, nanoscale titanium dioxide feedstocks, and microcapsule shell-forming agents. Single-source vulnerability runs through German and Chinese specialty chemical producers who dominate responsive polymer patent estates. Distribution feeds from Rotterdam, Houston, and Shanghai supply hubs through direct technical service teams deployed at Dalian and Shanghai shipyard clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around REACH dossiers and ISO 12944 certification creates formidable defensive moats, as incumbent suppliers exploit 18-24 month EPA New Chemicals Program review timelines to foreclose competitive entry.
For Market Incumbents: Fortify specification lock-in by deepening captive resin synthesis capabilities in Germany and China while accelerating waterborne formulation R&D to capture first-mover advantages under tightening MEE enforcement. Invest in Rotterdam-based technical service expansion to defend against Jotun's Southeast Asian shipyard penetration. Prioritize ISO 12944 certification maintenance as the primary lever against emerging regional formulators. For New Entrants and Emerging Players: Anchor in India's infrastructure pipeline where BIS certification requirements are tightening qualification pathways for imported systems, creating specification windows for domestic self-healing concrete coating developers. Target aftermarket maintenance contracts in Southeast Asian shipyard clusters where certified technician scarcity constrains incumbent service capacity. Pursue deposition partnerships with South Korean display manufacturers as the most penetrable electronics integration channel. For Investors and Strategic Acquirers: ECHA substance evaluation and evolving PFAS restrictions reshape the acquisition landscape toward silicone and bio-based alternative specialists with established regulatory dossiers. Long-term viability favors vertically positioned suppliers holding aerospace OEM approvals and captive resin production. Monitor PFAS restriction implementation timelines across EU member states as the critical signal for fluorinated chemistry substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resins | PPG Industries and Sherwin-Williams sustain margin capture through captive polymer synthesis in Houston and Shanghai. |
| Waterborne Formulation Scale-Up | Chinese domestic formulators accelerate GB standard compliance trials in Tianjin port maintenance windows. |
| Technical Service Team Deployment | Jotun penetrates Southeast Asian shipyard clusters through direct applicator training programs. |
| ISO 12944 Certification Investment | AkzoNobel anchors European marine demand through Rotterdam-based supply architecture. |
| Silicone Alternative R&D Partnerships | EU Green Deal procurement mandates redirect investment away from PFAS-dependent hydrophobic systems. |
Research Methodology
Initial hypotheses were tested against primary input from coating formulator R&D directors, marine procurement managers at Rotterdam port operators, aerospace OEM specification engineers, and Southeast Asian shipyard maintenance contractors, then refined through secondary validation against ECHA substance evaluation databases, EPA New Chemicals Program filings, Chinese GB standard emission records, and SEC 10-K disclosures from listed coating suppliers. Bottom-up segment sizing triangulated with top-down macroeconomic elasticity checks.
Variance decomposition across product type, technology platform, application vertical, and end-user procurement authority shaped the analytical framework over the projection horizon. CAGRs derived from segment-level elasticity modeling against infrastructure investment flows, shipyard capacity expansion, and electronics manufacturing output. Industry-specific forecast inputs incorporated REACH registration timelines and MEE enforcement intensity in Shanghai and Tianjin port zones.
Material uncertainties — PFAS restriction implementation pace, nanotechnology deposition technician training pipeline development, and raw material allocation disruptions — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as ECHA substance evaluation timelines and EPA New Chemicals Program review durations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Cladding Coatings Market
Coatings
Rail Coatings Market
Coatings
Europe Thermal Spray Market
Coatings
Antifouling Coatings Market
Coatings
Global Fluorine Carbon Coatings Market
Coatings
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market
Coatings
Stain Resistance Coatings Market
Coatings
United Kingdom Automotive OEM Coatings Market
Coatings
Russia Protective Coatings Market
Coatings
Asia-Pacific Protective Coatings Market
Coatings
Mexico Industrial Wood Coatings Market
Coatings
Functional Coil Coating Market
Coatings
US Concrete Floor Coatings Market
Coatings
Bio-Based Coatings Market
Coatings
Global Radiation Cured Coatings Market
Coatings
Perfluoroalkoxy (PFA) Coatings Market