
 CVD Coating Technology Market | 2026-2036
CVD Coating Technology Market Size, Share, and Industry Trends Forecast 2026-2036
CVD Coating Technology Market Outlook
Multi-source procurement for precursor chemicals and chamber components is rebalancing supply risk across the CVD coating value chain. OC Oerlikon Corporation AG leverages its Balzers coating service network to anchor European aerospace demand. Applied Materials sustains technology leadership in semiconductor deposition platforms through intensive R&D spending. Veeco Instruments specializes in precision optical coating systems for augmented reality waveguide manufacturing.
Chemical vapor deposition coating technology deposits thin solid films from gaseous reactants onto heated substrates, typically operating at temperatures between 500°C and 1100°C with chamber pressures from atmospheric down to below 100 Pa, primarily to enhance surface hardness, corrosion resistance, or electrical properties. Silicon carbide coatings dominate wear-protection applications in automotive powertrain components due to their exceptional thermal stability and low friction coefficients. Semiconductor applications represent the fastest-expanding end-use segment as advanced logic and memory nodes require atomic-layer-precision dielectric and metal films. Batch deployment systems retain margin strength in medical device coating where lot traceability and process validation command premium pricing.
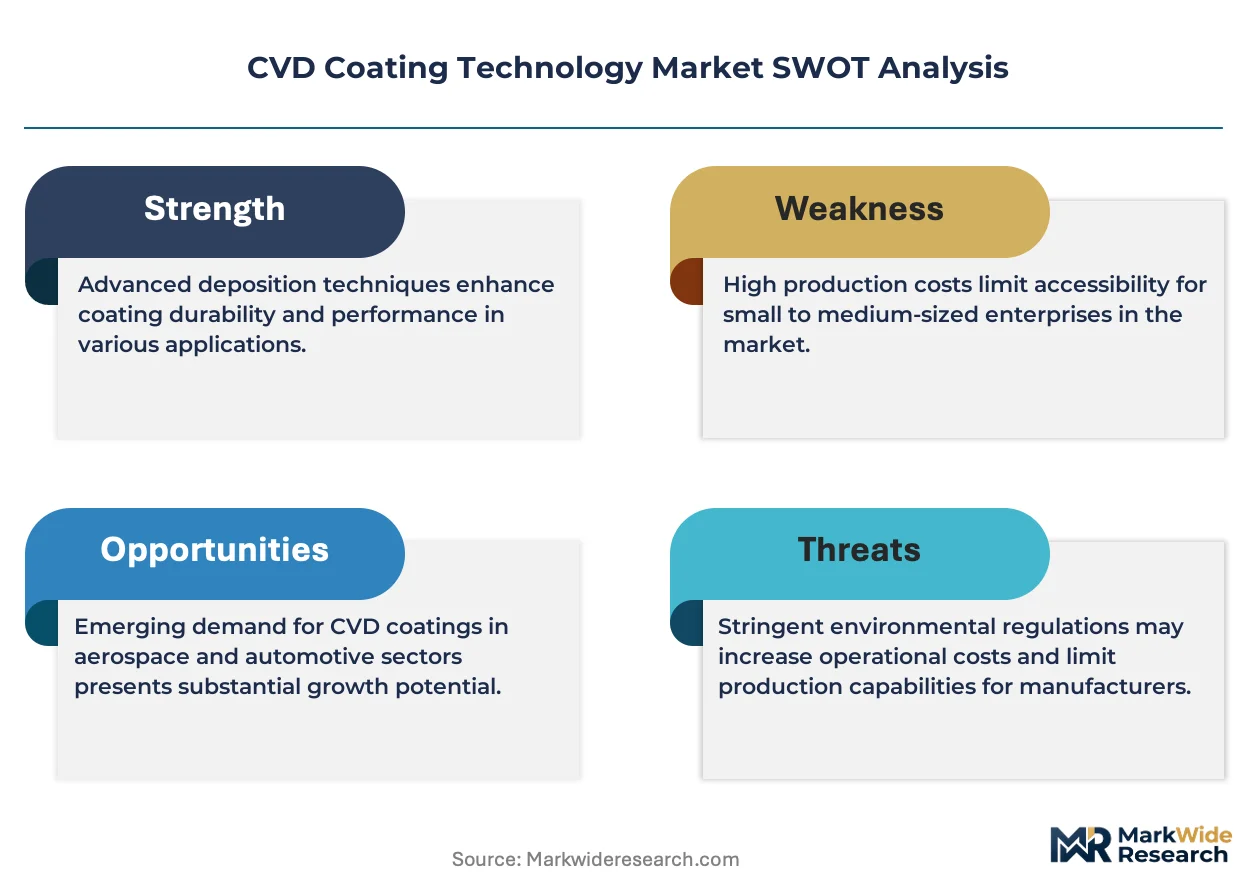
EPA hazardous air pollutant standards under the National Emission Standards for Hazardous Air Pollutants constrain precursor handling and exhaust treatment in U.S. manufacturing facilities. REACH registration requirements in the European Union govern the commercial use of organometallic precursor compounds, directly affecting material qualification timelines for coating service providers. FDA device regulations for implanted medical components mandate biocompatibility validation of CVD-coated surfaces, creating compliance barriers for new market entrants. Stakeholders must monitor evolving dual-use export controls on advanced deposition equipment as geopolitical tensions reshape equipment sourcing strategies.
Market Dynamics
Advanced node semiconductor fabrication is compressing deposition tolerances to atomic-layer precision, forcing equipment suppliers and coating service providers to synchronize process control architectures across Taiwan, South Korea, and Arizona fabrication clusters.
Growth Catalysts
- EPA hazardous air pollutant standards:U.S. facilities must upgrade exhaust treatment systems, creating replacement demand for thermal and plasma-enhanced CVD platforms with integrated abatement.
- Titanium nitride coatings:Aerospace turbine blade protection requirements in Germany and the United States are pulling high-temperature CVD capacity toward aviation-qualified service networks.
- East Asian semiconductor clusters:Taiwan and South Korea now account for the dominant share of ultra-thin dielectric layer demand, concentrating equipment procurement decisions in Hsinchu and Pyeongtaek corridors.
Market Restraints
- Organometallic precursor supply concentration:Specialty chemical synthesis for hafnium and zirconium precursors remains concentrated among European and Japanese suppliers, exposing coaters to allocation risk during supply shocks.
- REACH registration timelines:ECHA compliance for new precursor chemistries extends material qualification cycles by 18-24 months, delaying process transfers between coating service sites.
- Physical vapor deposition substitution:Sputtered coatings for decorative and some functional applications are capturing share in cost-sensitive automotive trim segments where thickness tolerance permits.
Strategic Opportunities
- India PLI scheme for semiconductors:Gujarat and Karnataka fab incentives are attracting deposition equipment providers to establish local service infrastructure ahead of projected 2027-2028 wafer start ramps.
- Augmented reality waveguide manufacturing:Precision optical coating requirements for AR headsets are creating a new equipment category between semiconductor and display deposition tool specifications.
- EU Green Deal industrial decarbonization:Carbon border adjustment mechanisms are incentivizing low-temperature plasma-enhanced CVD retrofits to reduce thermal energy intensity in European coating operations.
Industry Challenges
- Atomic-scale process control expertise:The gap between academic thin-film physics training and production-scale chamber matching is widening as node transitions accelerate.
- FDA biocompatibility validation timelines:Implantable medical device coatings require 24-36 month qualification cycles that compress equipment utilization rates for contract manufacturers.
- Dual-use export control alignment:Deposition platforms with sub-nanometer precision are attracting heightened licensing scrutiny, complicating cross-border equipment transfers and spare parts logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CVD Coating Technology Market |
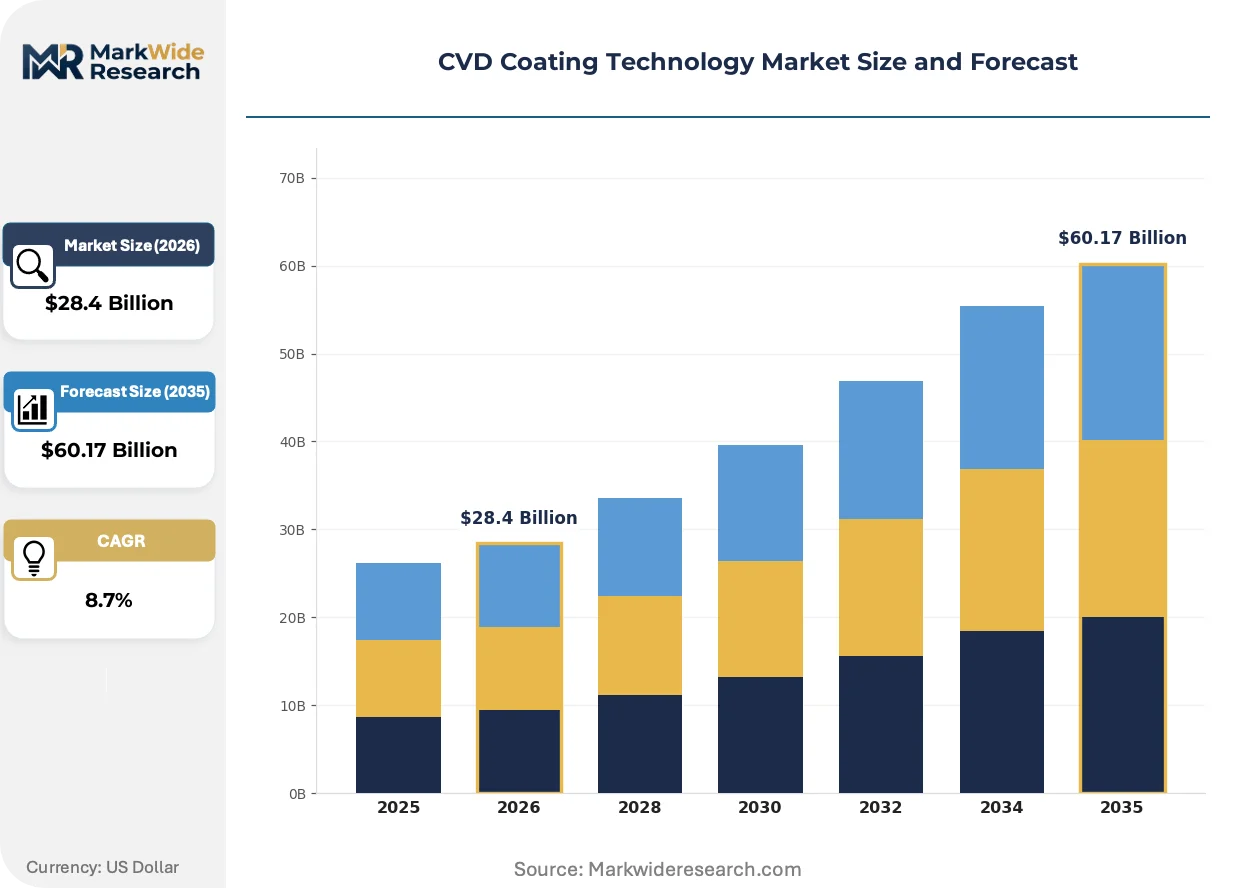
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $60.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
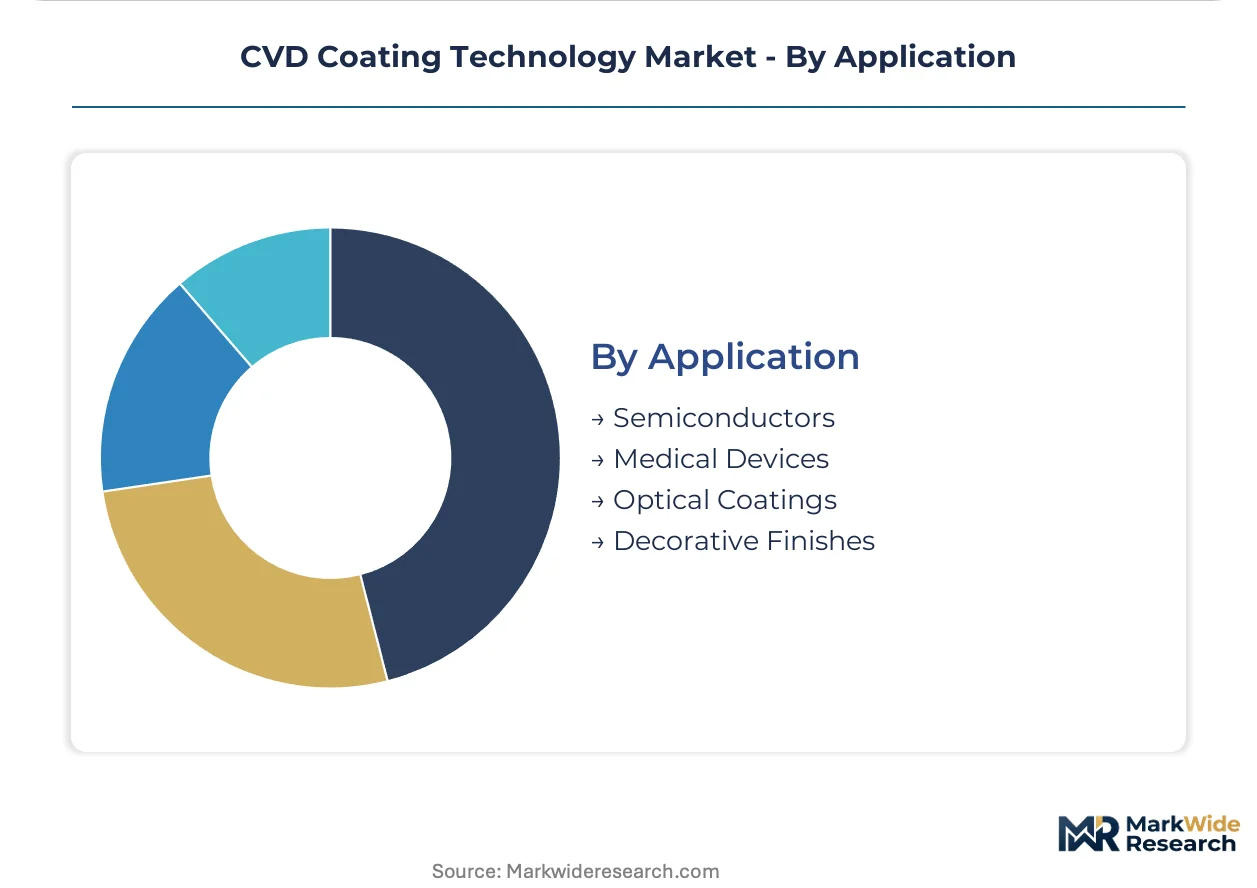
| Segmentation | Coating Material: Silicon Carbide, Titanium Nitride, Aluminum Oxide, Tungsten Carbide End User: Aerospace, Electronics, Automotive, Tool Manufacturing Deployment Type: Batch, Inline, Roll-to-Roll, Laboratory Application: Semiconductors, Medical Devices, Optical Coatings, Decorative Finishes |
| Companies Covered | OC Oerlikon Corporation AG, Oerlikon Balzers, CVD Equipment Corporation, Aixtron, Veeco Instruments, Applied Materials, ULVAC, ASM International, IHI Ionbond AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CVD Coating Technology Market Strategic Shifts
Plasma-enhanced and spatial atomic layer deposition variants are collapsing thermal budget requirements while extending film property control into previously inaccessible substrate temperature regimes.
Spatial atomic layer deposition is expanding into flexible electronics manufacturing where roll-to-roll substrate handling demands sub-200°C processing without sacrificing film density. Korean display panel manufacturers are piloting these systems for barrier layer deposition on foldable smartphone substrates. The technology is expanding into areas previously reserved for vacuum thermal processing, compressing the traditional temperature-performance tradeoff in polymer substrate coating.
REACH authorization requirements for chromium trioxide in functional plating are accelerating hard chrome replacement programs across European aerospace and industrial valve supply chains. Coating service providers must now qualify tungsten carbide-CVD and diamond-like carbon alternatives under ECHA substitution mandates. German automotive tier suppliers are consolidating process validation data to support downstream OEM environmental compliance declarations.
Buyer concentration in semiconductor capital procurement is compressing equipment vendor negotiation cycles and unbundling traditional service contract structures. Taiwan-based foundries are separating chamber component supply from preventive maintenance agreements, forcing Applied Materials and Tokyo Electron to restructure recurring revenue models. This pattern is most visible in Hsinchu Science Park procurement, where multi-fab consortia now negotiate precursor and spare parts contracts independently of platform purchases.
CVD Coating Technology Market Segmentation
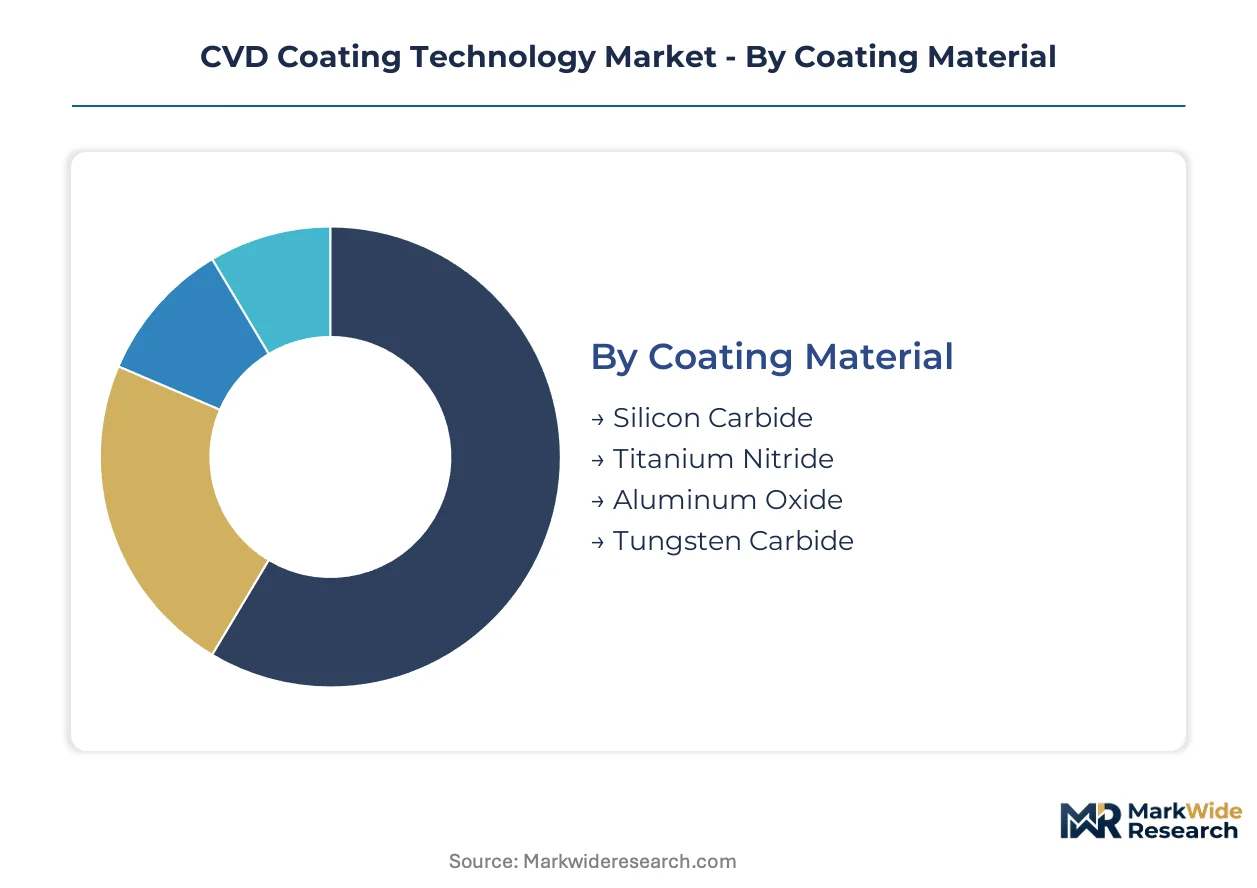
CVD coating technology serves divergent performance requirements across semiconductor fabrication, aerospace turbine protection, and medical implant surfaces. Material selection and deployment architecture directly determine thermal budget, film uniformity, and regulatory compliance pathways for each end-use vertical.
Coating Material:
Silicon carbide and titanium nitride anchor high-value applications through embedded integration into mission-critical systems, while aluminum oxide and tungsten carbide serve more cost-sensitive standalone protection roles.
- Silicon Carbide:Exceptional thermal stability above 1400°C and low friction coefficients make this ceramic ideal for automotive powertrain components and aerospace turbine seals. German and United States aviation manufacturers specify silicon carbide for blade tip clearance control in next-generation turbofans. Demand concentrates in Stuttgart and Cincinnati aerospace clusters where thermal barrier performance commands premium qualification cycles.
- Titanium Nitride:Golden-colored ceramic coating delivers hardness exceeding 2400 HV with biocompatibility clearance for surgical instruments. Aerospace cutting tool applications in Bavaria and Texas drive specification volumes, though medical device adoption in Minneapolis-Saint Paul and Tuttlingen is expanding fastest under FDA and EU MDR validation frameworks.
- Aluminum Oxide:Dielectric strength above 10^14 ohm-cm supports semiconductor insulator applications.
- Tungsten Carbide:Dense carbide structure replaces hard chrome plating under REACH substitution mandates across European industrial valve supply chains.
Silicon carbide leads volumes today; titanium nitride is gaining share fastest.
End User:
Customer type stratification separates capital-intensive semiconductor foundries from specification-driven aerospace primes and price-sensitive automotive tiers.
- Electronics:Advanced logic and memory node fabrication demands atomic-layer-precision dielectric deposition. Taiwan and South Korean foundries in Hsinchu and Pyeongtaek corridors concentrate procurement for ultra-thin barrier layers at 3nm and below nodes. Equipment utilization rates exceed 90% in these clusters, compressing maintenance windows and spurring predictive service contracts.
- Aerospace:Turbine blade thermal protection and fuel system component hardness specifications drive qualification-intensive coating programs. Germany's MTU Aero Engines and United States Pratt & Whitney operations in Munich and East Hartford anchor demand for aviation-qualified CVD service networks with Nadcap accreditation.
- Automotive:Powertrain wear protection and decorative trim applications span divergent price-performance requirements.
- Tool Manufacturing:Cutting insert coatings prioritize throughput over extreme precision in high-volume metalworking.
Electronics commands the highest unit values; aerospace is expanding most quickly.
Deployment Type:
System architecture selection trades throughput scalability against process validation rigor, with batch systems preserving margin in regulated medical applications.
- Batch:Single-chamber processing with full lot traceability supports FDA 21 CFR Part 820 compliance for implantable medical devices. Contract manufacturers in Warsaw, Indiana and Tuttlingen, Germany maintain dedicated batch lines with 24-36 month qualification cycles that command 40-60% price premiums over industrial coating services.
- Inline:Continuous substrate transport through multiple deposition zones enables semiconductor wafer throughput exceeding 100 wph. Applied Materials and Tokyo Electron dominate this architecture for 300mm logic fab deployments in Taiwan, South Korea, and Arizona.
- Roll-to-Roll:Flexible polymer substrate handling for barrier layer deposition on foldable display components.
- Laboratory:Research-scale systems for precursor chemistry development and process transfer validation.
Inline systems dominate capital expenditure; batch retains the steepest expansion trajectory in medical verticals.
Application:
Functional requirements separate electronic device fabrication from biocompatibility-validated surfaces and aesthetic finishes.
- Semiconductors:Atomic-layer deposition of high-k dielectrics and metal gates at sub-5nm nodes requires chamber matching precision below 0.5nm. Taiwan Semiconductor Manufacturing and Samsung Foundry procurement decisions in Hsinchu and Hwaseong determine equipment vendor R&D priorities for precursor delivery and plasma source architectures.
- Medical Devices:Orthopedic implant and cardiovascular stent coatings require ISO 10993 biocompatibility validation with 3-5 year FDA PMA or EU MDR approval timelines. Zimmer Biomet and Stryker sourcing specifications in Warsaw, Indiana and Freiburg im Breisgau concentrate demand among qualified contract coating providers.
- Optical Coatings:Augmented reality waveguide manufacturing demands precision between semiconductor and display deposition specifications.
- Decorative Finishes:Titanium nitride gold coloration for watchmaking and automotive trim competes against PVD alternatives on cost.
Semiconductors lead absolute spending; medical devices show the fastest climb in contract manufacturing value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors global demand for atomic-layer-precision deposition equipment, with procurement decisions from Taiwan Semiconductor Manufacturing compressing vendor negotiation cycles across the industry. East Asian fabrication clusters now dictate equipment R&D priorities, while European aerospace networks and North American medical device hubs sustain premium coating service margins.
United States
Pratt & Whitney's East Hartford operations and Arizona's emerging semiconductor corridor drive dual demand streams for aviation-qualified and sub-5nm deposition platforms. EPA hazardous air pollutant standards under NESHAP constrain precursor handling protocols, forcing facility upgrades across Ohio and California industrial coating networks. Cincinnati aerospace clusters concentrate silicon carbide blade seal capacity, while Minneapolis-Saint Paul medical device manufacturers expand titanium nitride surgical instrument coating under FDA 21 CFR Part 820.
Germany
MTU Aero Engines in Munich and Stuttgart automotive powertrain suppliers anchor European demand for thermal barrier and wear-protection coatings. REACH authorization requirements for chromium trioxide accelerate hard chrome replacement programs across Bavarian industrial valve supply chains. Tuttlingen orthopedic implant manufacturers maintain dedicated batch CVD lines with 24-36 month EU MDR qualification cycles, commanding premium pricing over industrial coating services.
Taiwan
TSMC and United Microelectronics foundries in Hsinchu Science Park concentrate procurement for ultra-thin dielectric layers at 3nm and below nodes. The island's dual-use export control alignment with U.S. licensing regimes complicates cross-border equipment transfers for sub-nanometer precision platforms. Multi-fab consortia now negotiate precursor and spare parts contracts independently of platform purchases, unbundling traditional service contract structures.
South Korea
Samsung Foundry and SK Hynix operations in Hwaseong and Pyeongtaek drive equipment utilization rates exceeding 90%, compressing maintenance windows. Korean display panel manufacturers pilot spatial atomic layer deposition for foldable smartphone barrier layers, expanding into sub-200°C polymer substrate regimes. MFDS medical device regulations govern biocompatibility validation for Seoul-based contract manufacturers serving cardiovascular stent markets.
India
Gujarat and Karnataka semiconductor fab incentives under the PLI scheme attract deposition equipment providers to establish local service infrastructure. CDSCO medical device regulations create compliance pathways for Mumbai and Bangalore contract manufacturers entering orthopedic implant coating. The country's central bank monitors capital goods import financing for Arizona-equivalent precision platforms ahead of projected 2027-2028 wafer start ramps.
CVD Coating Technology Market Competitive Environment
Global majors compete with regional champions across equipment architecture and coating service networks, producing a tiered structure where scale-driven platform vendors face specialized precision-optical and medical-batch specialists. Consolidation concentrates around semiconductor capital procurement, while fragmentation persists in aerospace-qualified service networks requiring Nadcap accreditation. Three archetypes dominate: integrated equipment-precursor systems houses, pure-play coating service networks with geographic anchoring, and precision-optical specialists serving adjacent display-AR convergence. Competitive moves center on unbundling service contracts and vertical integration into precursor chemical synthesis.
Among Swiss-anchored coating service networks, OC Oerlikon Corporation AG and Oerlikon Balzers exemplify the geographic-anchoring archetype, leveraging Central European aerospace proximity to defend premium positioning. Applied Materials occupies a position on the integrated-systems vector, representing the scale-driven consolidation of chamber component supply with platform architecture. Veeco Instruments sits within the precision-optical specialization tier, anchoring augmented reality waveguide manufacturing requirements between semiconductor and display deposition specifications.
| Leading Market Players |
|---|
| OC Oerlikon Corporation AG |
| Oerlikon Balzers |
| CVD Equipment Corporation |
| Aixtron |
| Veeco Instruments |
| Applied Materials |
| ULVAC |
| ASM International |
| IHI Ionbond AG |
| Others |
Value Chain & Pricing Dynamics
REACH chemical compliance in the European Union gates qualified supply for aerospace and medical coating services, restricting premium-tier pricing access to providers with validated low-toxicity precursor programs and ECHA-registered material portfolios.
Pricing Analysis
Input-cost pass-through from hafnium and zirconium organometallic precursors shapes contract structures across semiconductor deposition services. Three-tier pricing structure across aviation-qualified, industrial-standard, and research-grade levels separates Nadcap-accredited aerospace coaters from unqualified competitors. Pricing pressure stems from physical vapor deposition substitution in decorative automotive trim where thickness tolerances permit sputtered alternatives. Automotive tier suppliers exhibit highest price sensitivity; medical device manufacturers accept premiums for FDA-validated batch processing with full lot traceability.
Supply Chain Analysis
Freight costs for precursor chemical shipments from European and Japanese synthesis hubs compress margins for coating service providers in North American aerospace clusters. Taiwan, South Korea, and Germany anchor equipment and chamber component manufacturing, while specialty organometallic precursor synthesis draws from Belgium, Japan, and the United States. Single-source vulnerability concentrates in hafnium precursor supply during allocation periods. Distribution runs through direct equipment vendor relationships for semiconductor foundries and regional coating service networks for aerospace and medical verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA hazardous air pollutant standards and REACH authorization requirements continuously reshape qualified supply and drive replacement demand for compliant deposition platforms.
For Market Incumbents: Anchor aviation-qualified service networks through Nadcap accreditation investments in Stuttgart and Cincinnati clusters. Defend against physical vapor deposition erosion by qualifying silicon carbide and diamond-like carbon alternatives under ECHA substitution mandates. Backward integration into precursor chemical synthesis reduces allocation risk from European and Japanese suppliers. For New Entrants and Emerging Players: Enter via spatial atomic layer deposition equipment for foldable display barrier layers in South Korean and Taiwanese manufacturing corridors. Target medical device batch coating services in Warsaw, Indiana and Tuttlingen where 24-36 month FDA and EU MDR qualification cycles create incumbent protection. Pursue platform-as-a-service models with predictive maintenance contracts to bypass capital-intensive chamber manufacturing. For Investors and Strategic Acquirers: Roll-up economics work for precision-optical coating specialists because augmented reality waveguide manufacturing demands specifications between semiconductor and display deposition tool categories. Five-to-ten year viability hinges on equipment providers capturing AR headset production ramps before platform standardization. Watch for dual-use export control licensing delays on sub-nanometer precision platforms as the inflection signal for geographic supply restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | Reduces hafnium and zirconium supply allocation risk for coating service providers. |
| Spatial ALD Platform Development | Captures foldable smartphone barrier layer demand from Korean display manufacturers. |
| Nadcap Accreditation Expansion | Qualifies coating services for Pratt & Whitney and MTU Aero Engines turbine programs. |
| Low-Temperature PECVD Retrofit Programs | Aligns European operations with EU Green Deal carbon border adjustment mechanisms. |
| Medical Device Batch Line Investment | Commands 40-60% price premiums under FDA 21 CFR Part 820 traceability requirements. |
Study Parameters
Bottom-up semiconductor and aerospace demand modeling reconciled against top-down equipment vendor shipment tracking forms the analytical core of this study. Primary interviews with deposition platform engineers, coating service procurement managers, aerospace quality directors, and medical device regulatory affairs specialists combined with secondary validation from SEC 10-K filings, ECHA registration databases, and customs trade records. Triangulation across these sources ensures coverage of both capital expenditure decisions and operational qualification timelines.
Input-output matrix framing connects precursor chemical consumption rates to chamber utilization metrics across the projection horizon. Segmentation dimensions include coating material type, end-use vertical, deployment architecture, and regional regulatory cluster. CAGRs derive from equipment replacement cycles, node transition acceleration patterns, and aerospace engine program ramps. Forecast inputs incorporate EPA NESHAP compliance deadlines and REACH authorization timelines for chromium trioxide substitutes.
The model holds under stable dual-use export control licensing conditions; deviation in U.S.-China-Taiwan equipment transfer restrictions would shift capital expenditure timing and geographic supply concentration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Wood Protection Coating Market
Coatings
Global Mirror Coatings Market
Coatings
PU Coatings Market
Coatings
High Temperature Coatings Market
Coatings
Tablet and Pellet Coating Systems Market
Coatings
FBE Coatings Market
Coatings
Coating Auxiliaries Market
Coatings
Cool Roof Coatings Market
Coatings
Polyurethane (PU) Coatings Market
Coatings
Conductive Coatings Market
Coatings
Thermal Insulation Coating Market
Coatings
Architectural Metal Coatings Market
Coatings
Polysiloxane Coatings Market
Coatings
Anti-Graffiti Coatings Market
Coatings
United Arab Emirates Protective Coatings Market
Coatings
Phosphate Conversion Coatings Market