
 Food Grade Ceramic Coatings Market | 2026-2036
Food Grade Ceramic Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Ceramic Coatings Market Analytics
Specialty kitchen retail is fragmenting as direct-to-consumer channels and professional supply houses compete for ceramic-coated cookware volumes. Zwilling J.A. Henckels leverages its German forging heritage to anchor premium positioning in European commercial kitchens. GreenPan competes on sol-gel ceramic technology leadership and brand recognition among health-conscious North American households. Saint-Gobain dominates industrial-grade ceramic coating supply for food processing equipment through its materials science platform.
Food grade ceramic coatings are inorganic, non-metallic surface treatments—typically silica-based sol-gel formulations or alumina-titania composites—applied to metal substrates to create thermally stable, chemically inert barriers that prevent food adhesion and metal ion leaching during cooking or processing. Spray coatings occupy the largest volume share due to uniform thickness control on complex cookware geometries, while powder coatings represent the fastest-expanding format as electrostatic application reduces solvent emissions in manufacturing. Food processing equipment commands premium pricing relative to household cookware because industrial buyers prioritize thermal shock resistance and abrasive cleaning durability.
The FDA regulates food-contact substances under 21 CFR, while the EU enforces REACH registration and the Framework Regulation (EC) No 1935/2004 for materials contacting food. BIS in India and GB standards in China impose additional migration limits on heavy metals and specific coating chemistries. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across jurisdictions, as ceramic coatings positioned as PFAS-free alternatives face intensifying formulation scrutiny and certification requirements.
Market Dynamics
REACH chemicals framework enforcement and FDA food-contact material rule tightening are forcing ceramic coating formulators to eliminate residual heavy metals and per- and polyfluoroalkyl substances from sol-gel chemistries. This regulatory compression is accelerating R&D spend and reshaping competitive positioning among specialty coating suppliers.
Growth Catalysts
- EU Green Deal alignment:Commercial kitchens across Germany and France are replacing PTFE-coated equipment with PFAS-free ceramic alternatives to meet sustainability procurement mandates.
- Sol-gel process advancement:Low-temperature curing silica-based formulations now bond to aluminum substrates without thermal degradation, expanding cookware substrate compatibility.
- India:BIS migration limit enforcement on nickel and chromium leaching is compelling domestic cookware manufacturers to source certified ceramic coatings from established suppliers.
Market Restraints
- Fumed silica supply concentration:Three German and Japanese chemical conglomerates control pyrogenic silica precursor supply, creating input cost volatility for coating formulators.
- Thermal shock limitation:Alumina-titania composite coatings crack above 450°C, excluding them from high-temperature industrial frying and flash-searing equipment applications.
- Substitution threat:Diamond-like carbon coatings from industrial materials suppliers offer comparable non-stick performance with superior abrasion resistance in food processing environments.
Strategic Opportunities
- Brazil:ANVISA food-contact substance regulations are tightening ahead of EU alignment, creating first-mover advantage for certified coating suppliers in South American cookware manufacturing.
- Induction compatibility:Ferrite-doped ceramic coatings enable magnetic responsiveness on aluminum cookware, opening induction cooktop market penetration where steel substrates dominate.
- Direct-to-professional channels:Restaurant supply houses and institutional procurement platforms are bypassing traditional retail distribution for volume ceramic-coated equipment orders.
Industry Challenges
- Migration testing capacity:Third-party laboratories face 12-18 month backlogs for EU 10/2011 compliance certification, delaying product launches for coating developers.
- Application equipment retrofit:Electrostatic powder coating lines require $2-4 million capital outlays for cookware manufacturers transitioning from solvent-based spray systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Ceramic Coatings Market |
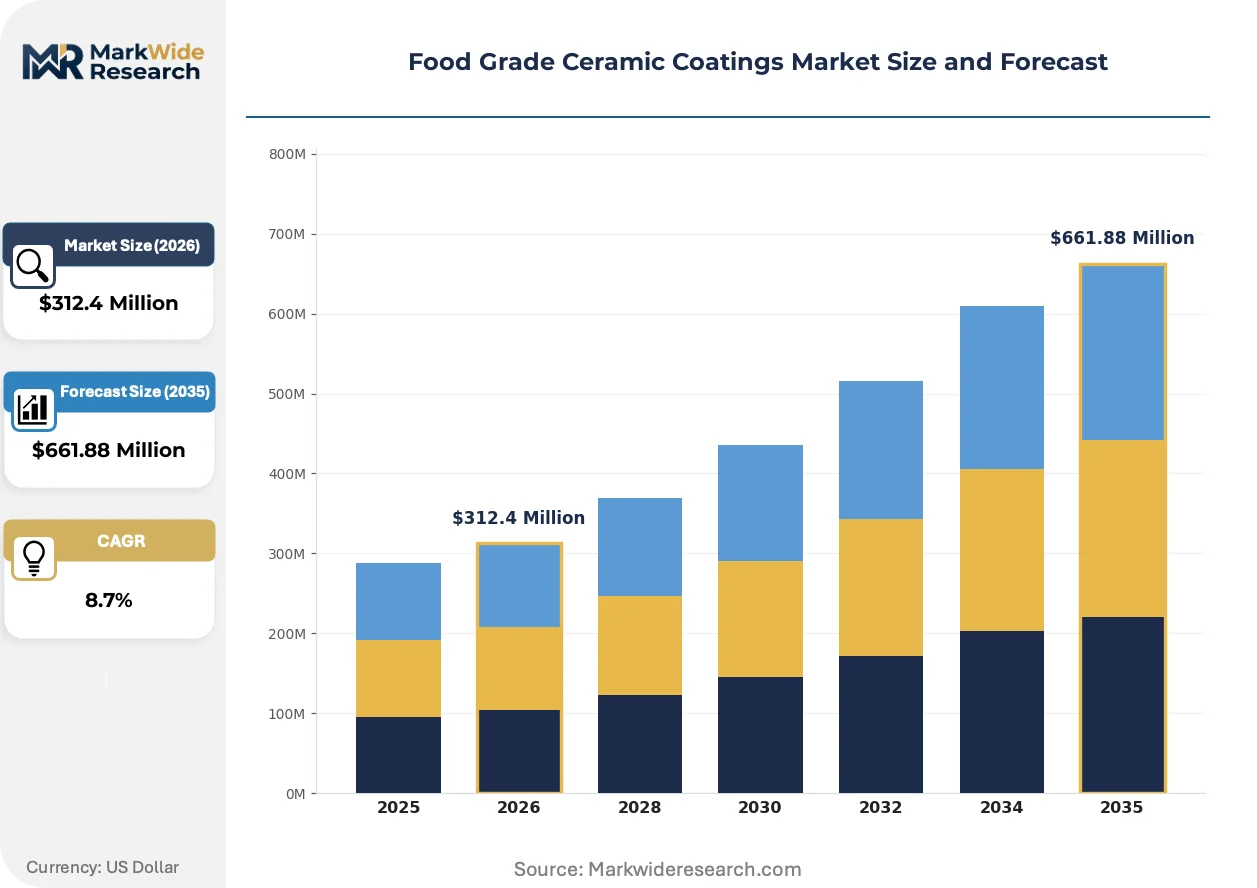
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray Coatings, Liquid Coatings, Powder Coatings, Paint Coatings Application: Cookware, Food Processing Equipment, Serving Ware, Packaging Materials End User: Restaurants, Catering Services, Food Manufacturers, Households Delivery Mode: Direct Supply, Distributors, Online Sales, Retail Outlets |
| Companies Covered | T-fal (Groupe SEB), GreenPan, Cuisinart, Calphalon, Saint-Gobain, Zwilling J.A. Henckels, Le Creuset, Scanpan, Bialetti, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Ceramic Coatings Market Evolving Landscape
Formulation chemistry and application technology are converging to eliminate process emissions while extending coating durability under aggressive commercial cleaning protocols. These developments are compressing the performance gap between industrial and household ceramic coating tiers.
Water-based sol-gel systems with organofunctional silane crosslinkers are collapsing the distinction between high-temperature industrial coatings and consumer-grade formulations. Food processing equipment manufacturers in Japan and Germany are adopting these hybrid chemistries to standardize inventory across household and commercial product lines. The convergence is collapsing pricing premiums historically attached to industrial-grade ceramic specifications.
REACH authorization list expansion for siloxanes and metal oxide nanoparticles is forcing coating suppliers to pre-register alternative precursors with ECHA. Industrial buyers in the Netherlands and Belgium are now requiring full substance disclosure down to 0.1% concentration thresholds. This transparency mandate is compressing formulation flexibility and accelerating vertical integration into precursor manufacturing among large coating houses.
Professional kitchen operators are consolidating vendor relationships and demanding 10-year coating performance guarantees with inclusive refurbishment services. Equipment lessors in France and the United Kingdom are bundling ceramic recoating into lease agreements, unbundling the traditional separation between capital equipment and consumable surface treatments. This service integration is compressing standalone coating supplier margins while expanding total addressable revenue for integrated equipment-service providers.
Food Grade Ceramic Coatings Market Segmentation
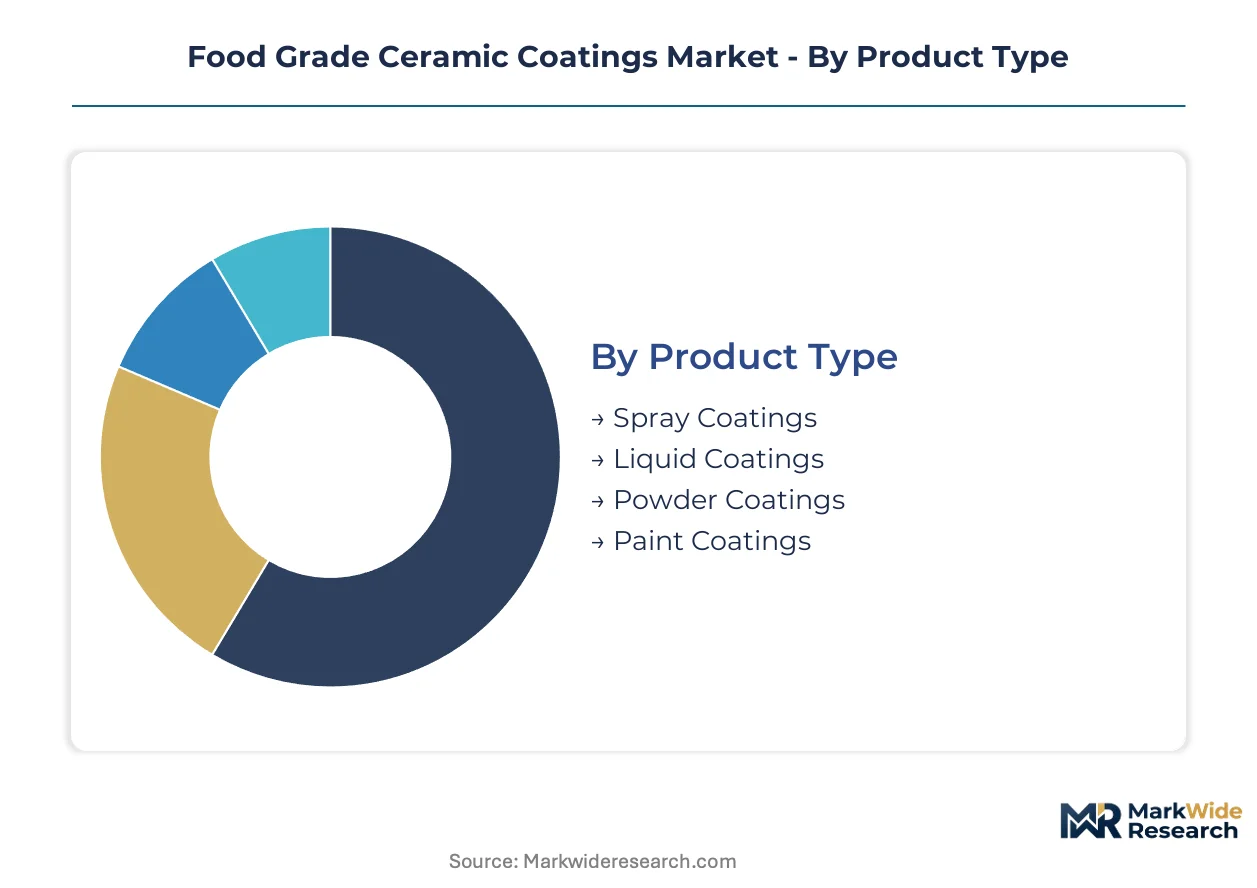
Segmentation in food grade ceramic coatings reveals how formulation chemistry, application method, and buyer sophistication create distinct commercial ecosystems. Each dimension carries unique regulatory burdens and margin structures that shape supplier strategy.
Product Type:
Mature spray formats dominate commercial cookware manufacturing while emerging powder technologies reshape environmental compliance economics.
- Spray Coatings:Solvent-based silica-alumina suspensions applied through automated reciprocating systems achieve uniform 25-40 micron thickness on complex pan geometries. German and Japanese cookware manufacturers specify spray coatings for premium aluminum product lines where surface consistency determines brand positioning.
- Powder Coatings:Electrostatically charged ceramic particles fuse to substrates without solvent carriers, eliminating VOC emissions during curing. French and Dutch regulators now mandate powder formats for government procurement contracts under EU Green Deal implementation timelines.
- Liquid Coatings:Water-dispersed sol-gel precursors suit manual touch-up applications and repair services.
- Paint Coatings:Brush-applied ceramic composites serve prototyping and custom equipment refurbishment.
Spray coatings retain volume leadership; powder coatings hold the steepest expansion curve.
Application:
Cost tier differentiation separates high-frequency thermal cycling applications from decorative or protective surface treatments.
- Cookware:Domestic frying pans and saucepans require FDA 21 CFR and EU 10/2011 migration compliance for direct food contact. Zwilling and GreenPan anchor demand in German and North American consumer markets where PFAS-free positioning commands price premiums.
- Food Processing Equipment:Industrial kettles, conveyors, and mixing vessels specify alumina-titania composites resisting thermal shock above 400°C and caustic washdown protocols. Saint-Gobain supplies European dairy and meat processing OEMs requiring 10-year surface integrity guarantees.
- Serving Ware:Hotel and institutional tableware applies thin ceramic barriers for stain resistance and metallic luster.
- Packaging Materials:Can interior linings and closure coatings prevent acidic food corrosion of metal substrates.
Cookware retains volume leadership; food processing equipment holds the steepest expansion curve.
End User:
Customer type determines specification authority—centralized procurement teams versus dispersed household decision-making.
- Restaurants:Commercial kitchen operators prioritize thermal shock resistance and rapid recovery from abrasive cleaning. Chains in France and the United Kingdom consolidate vendor relationships and demand bundled recoating services within equipment lease structures.
- Food Manufacturers:Industrial buyers specify coating performance through equipment OEMs rather than direct ceramic supplier engagement. Japanese and German processing equipment builders integrate coating selection into total system validation protocols.
- Catering Services:Mobile and event-based food service requires lightweight coated equipment with rapid turnaround durability.
- Households:Health-conscious consumers in North America and Germany drive PFAS-free ceramic cookware replacement cycles.
Food manufacturers retain volume leadership; restaurants hold the steepest expansion curve.
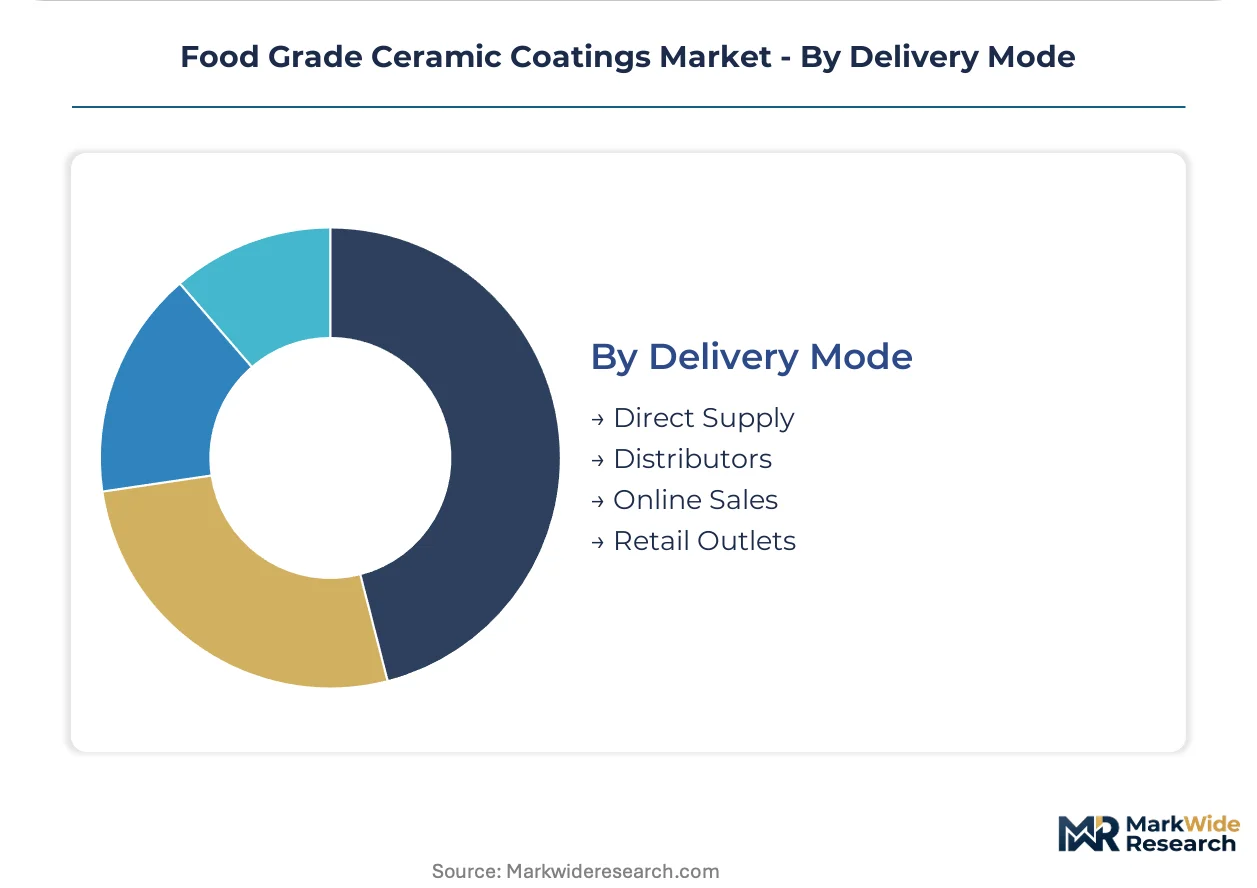
Delivery Mode:
Supply chain configuration separates bulk industrial procurement from fragmented retail distribution economics.
- Direct Supply:Coating formulators contract directly with cookware OEMs and food equipment manufacturers, embedding technical service teams within customer facilities. German chemical suppliers station application engineers at major aluminum cookware factories.
- Distributors:Regional industrial supply houses stock certified coating inventories for mid-volume equipment refurbishers and smaller cookware brands.
- Online Sales:Direct-to-consumer ceramic-coated cookware bypasses traditional retail markup, though coating chemistry transparency remains limited.
- Retail Outlets:Specialty kitchen stores and mass merchants carry finished goods rather than raw coating materials.
Direct supply retains volume leadership; online sales hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal procurement mandates and FDA food-contact rule tightening are redirecting manufacturing investment toward jurisdictions with established certification infrastructure and precursor chemical supply chains.
Germany
Commercial kitchen equipment manufacturers in Solingen and the Ruhr region specify REACH-compliant ceramic coatings for institutional procurement contracts. ECHA pre-registration requirements for siloxane precursors are compressing formulation flexibility among Mittelstand coating houses. Stuttgart-based materials suppliers are integrating application engineering teams directly into cookware OEM facilities.
United States
Health-conscious households in California and the Northeast are driving PFAS-free ceramic cookware replacement cycles. FDA 21 CFR migration testing backlogs of 12-18 months are delaying product launches for coating developers. Pittsburgh and Chicago industrial clusters host food processing equipment OEMs demanding 10-year coating performance guarantees.
Japan
Tokyo and Osaka metropolitan areas concentrate demand for hybrid sol-gel formulations standardizing across household and commercial product lines. METI industrial standards for food-contact materials are accelerating R&D spend on low-temperature curing silica systems. Nagoya-based processing equipment builders integrate coating selection into total system validation protocols.
France
Restaurant chains in Paris and Lyon are consolidating vendor relationships and demanding bundled recoating services within equipment lease structures. ANSM food-contact substance transparency mandates are forcing full substance disclosure down to 0.1% concentration thresholds. Lille and Grenoble industrial zones host dairy and meat processing OEMs sourcing alumina-titania composites.
India
BIS enforcement of nickel and chromium migration limits is compelling domestic cookware manufacturers to source certified ceramic coatings from established suppliers. Maharashtra and Gujarat industrial corridors concentrate aluminum cookware fabrication for export markets. Delhi-NCR institutional procurement platforms are bypassing traditional retail distribution for volume ceramic-coated equipment orders.
Food Grade Ceramic Coatings Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: multinational materials conglomerates with captive precursor production, mid-scale specialty coating houses with embedded application engineering, and cookware OEMs with in-house formulation capabilities. Competitive dynamics center on REACH pre-registration compliance and electrostatic powder coating line retrofits requiring substantial capital outlays. M&A activity targets coating formulators with ECHA-registered alternative precursors, while strategic partnerships link equipment lessors to recoating service providers.
Within the premium cookware tier, Zwilling J.A. Henckels and Le Creuset represent European heritage positioning, while GreenPan exemplifies North American health-conscious market segmentation. Saint-Gobain occupies the industrial-grade supply position for food processing equipment OEMs. These three anchors illustrate how geographic origin and company structure correlate with archetype specialization across consumer, commercial, and industrial end-use vectors.
| Leading Market Players |
|---|
| T-fal (Groupe SEB) |
| GreenPan |
| Cuisinart |
| Calphalon |
| Saint-Gobain |
| Zwilling J.A. Henckels |
| Le Creuset |
| Scanpan |
| Bialetti |
| Others |
Value Network & Pricing Analysis
Fumed silica precursor concentration among German and Japanese chemical conglomerates determines both the spread between premium and standard coating tiers and the geographic clustering of formulation facilities. REACH authorization bottlenecks for siloxane alternatives compound this dependency, forcing coating houses to absorb certification costs or surrender margin to integrated suppliers.
Pricing Analysis
Certification level—specifically EU 10/2011 migration compliance and FDA 21 CFR food-contact clearance—creates the primary spread between industrial-grade alumina-titania composites and commodity spray formulations. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal shock resistance guarantees and bundled refurbishment services. Pricing pressure stems from electrostatic powder coating line retrofits demanding capital outlays that smaller cookware OEMs cannot absorb. Household buyers in North America exhibit highest price sensitivity, while French and British equipment lessors prioritize total cost of ownership over unit coating costs.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for aluminum substrate cookware manufacturers. Pyrogenic silica feedstock concentrates in Germany and Japan, while alumina-titania composite precursors source primarily from domestic European suppliers. Single-source vulnerability in fumed silica supply rests on three chemical conglomerates controlling pyrogenic production capacity. Distribution runs through direct technical service contracts with major cookware OEMs, supplemented by regional industrial supply houses for mid-volume refurbishers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around REACH pre-registration and FDA migration certification creates durable defensive moats for established coating formulators. Switching costs for cookware OEMs—rooted in validated application processes and ECHA-registered precursor libraries—protect incumbent positioning.
For Market Incumbents: Pre-empt displacement by diamond-like carbon coatings through ferrite-doped induction-compatible formulation R&D and captive precursor manufacturing in Stuttgart or Nagoya industrial clusters. Lock in restaurant chain relationships via 10-year performance guarantees with inclusive recoating services, compressing standalone competitor margins. For New Entrants and Emerging Players: Mid-market commercial kitchen equipment in Brazil represents the most penetrable entry point ahead of ANVISA food-contact substance alignment with EU standards. Water-based sol-gel repair services for existing PTFE-coated equipment fleets offer a low-capital go-to-market angle, bypassing electrostatic line investment requirements. For Investors and Strategic Acquirers: REACH authorization list expansion for siloxanes and metal oxide nanoparticles reshapes the acquisition landscape toward coating formulators with ECHA-registered alternative precursors. Long-term viability hinges on backward integration into precursor manufacturing and application engineering capabilities. Monitor EU Green Deal procurement mandate enforcement velocity as the signal for industrial coating demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Manufacturing | Captive fumed silica supply insulates German coating houses from input cost volatility and REACH authorization delays. |
| Electrostatic Powder Coating Line Retrofit | VOC elimination aligns French and Dutch manufacturers with EU Green Deal government procurement contract requirements. |
| Long-term Performance Guarantee Programs | Bundled recoating services in equipment lease structures expand total addressable revenue for integrated service providers. |
| Joint Venture with Induction Cooktop OEMs | Ferrite-doped ceramic formulations penetrate aluminum cookware markets previously closed to magnetic responsiveness. |
| Regulatory Pre-registration Investment | ECHA-registered alternative precursors enable continued formulation flexibility as REACH authorization list expands. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR filings, ECHA pre-registration databases, EU 10/2011 compliance certifications, and customs trade data for pyrogenic silica imports. Coating formulator R&D directors, cookware OEM procurement leads, commercial kitchen equipment maintenance directors, and third-party migration testing laboratory managers provided qualitative inputs. Bottom-up demand modeling from end-use segments triangulates against top-down supply-side capacity assessments across German, Japanese, and North American production clusters.
Forecast inputs include sol-gel curing temperature advancement trajectories, REACH authorization timeline assumptions, and induction cooktop penetration rates by regional market. Segmentation dimensions span product type (spray, powder, liquid, paint), application (cookware, food processing equipment, serving ware, packaging), and end user (restaurants, food manufacturers, households). CAGRs derive from regression analysis of historical coating volume against aluminum cookware production and commercial kitchen equipment capital expenditure cycles.
Macroeconomic conditions sit as an overlay; deviation in aluminum commodity pricing, euro-yen exchange rates, or EU Green Deal implementation pacing would shift the trajectory. Forecasts reflect documented assumptions around regulatory enforcement intensity and precursor substitution timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Zero Friction Coatings Market
Coatings
Canada Protective Coatings Market
Coatings
Thermal Insulation Coating Market
Coatings
Middle-East and Africa Coil Coatings Market
Coatings
UV Coatings Market
Coatings
Noise and Vibration Coatings Market
Coatings
Electronic Protection Device (EPD) Coatings Market
Coatings
Russia Architectural Coatings Market
Coatings
Paper Coating Binders Market
Coatings
North America Polyimide Coating Market
Coatings
Global Sputter Coater Market
Coatings
Self-Healing Microcapsule Systems for Protective Coatings Market
Coatings
Plastic-Coated Wires Market
Coatings
Global Smart Coating Market
Coatings
Anti-Friction Coatings Market
Coatings
Asia-Pacific Floor Coatings Market