
 Urethane Surface Coatings Market | 2026-2036
Urethane Surface Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Urethane Surface Coatings Market Intelligence
Compliance with stringent volatile organic compound (VOC) emission standards, such as Europe's REACH and the US EPA's regulations, is reorganizing the competitive landscape for urethane coatings. BASF SE leverages its extensive chemical expertise to develop innovative low-VOC waterborne systems for industrial applications. The Sherwin-Williams Company sustains a strong position in the construction segment through its vast distribution network. Covestro AG specializes in producing the core polyurethane raw materials, controlling a critical part of the value chain.
Urethane surface coatings are high-performance polymers created from the reaction of isocyanates and polyols. Their cross-linked chemical structure delivers exceptional durability, abrasion resistance, and protection against chemicals and weathering. The shift to waterborne formulations represents a defining trend, driven by environmental compliance needs across multiple industries. Within end-user segments, the automotive and aerospace sectors demand premium aliphatic urethane systems for their superior UV stability and long-term color retention on exterior components.
The regulatory environment is shaped by a global push to reduce VOCs. Mandates from the US EPA, Europe's ECHA, and China's Ministry of Ecology and Environment (MEE) compel manufacturers to innovate in low-VOC and waterborne technologies. These rules directly influence product formulation and market access for coating suppliers. Consequently, formulators must decide between investing in advanced waterborne systems or developing high-solids solvent-borne alternatives to maintain performance characteristics while meeting compliance.
Market Dynamics
The fundamental market dynamic is the tension between stringent environmental mandates for low-VOC formulations and the unyielding performance requirements of industrial end-users. This conflict is forcing a rapid technological pivot towards waterborne systems across the value chain.
Growth Catalysts
- Automotive Sector Demand:The global expansion of electric vehicle manufacturing creates substantial demand for durable, high-gloss urethane topcoats and battery pack coatings that offer chemical resistance and thermal management properties.
- Regulatory Mandates:China's Ministry of Ecology and Environment (MEE) regulations on industrial emissions compel furniture and electronics manufacturers to adopt compliant, higher-performance coatings to maintain access to export markets.
- Waterborne Technology:Advances in polyurethane dispersion (PUD) technology are delivering waterborne systems with improved hardness and chemical resistance, making them viable alternatives to solvent-borne coatings in industrial applications.
Market Restraints
- Raw Material Volatility:The market is subject to price fluctuations and supply disruptions for key precursors, particularly isocyanates like MDI and TDI, and polyols, which directly impact formulation costs and margin stability.
- Performance Trade-offs:Despite advances, some waterborne urethane systems exhibit longer dry times and lower initial hardness compared to solvent-borne counterparts, which can slow production throughput for industrial applicators.
- Substitution Threats:In specific segments like architectural and floor coatings, urethane systems face competition from alternative technologies such as polyaspartics and advanced epoxies that offer faster cure rates or lower application costs.
Strategic Opportunities
- Bio-Based Formulations:The development and commercialization of urethane coatings derived from bio-based polyols and isocyanates present a significant opportunity to capture demand from customers with corporate sustainability goals.
- Emerging Market Penetration:Industrialization in Southeast Asian countries, including Vietnam and Thailand, offers new growth frontiers for urethane coatings in manufacturing, construction, and infrastructure projects.
- Functional Coatings:Incorporating functionalities like self-healing properties for automotive clearcoats or antimicrobial additives for medical and high-touch surfaces opens new, high-value application areas beyond traditional protection.
Industry Challenges
- Formulation Complexity:Reformulating products to meet divergent VOC regulations from the US EPA and Europe's ECHA, while maintaining performance and cost-effectiveness, presents a significant technical hurdle for manufacturers.
- Skilled Labor Shortage:The industry faces a deficit of experienced chemists and technical specialists capable of developing and scaling up next-generation waterborne and high-solids urethane systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urethane Surface Coatings Market |
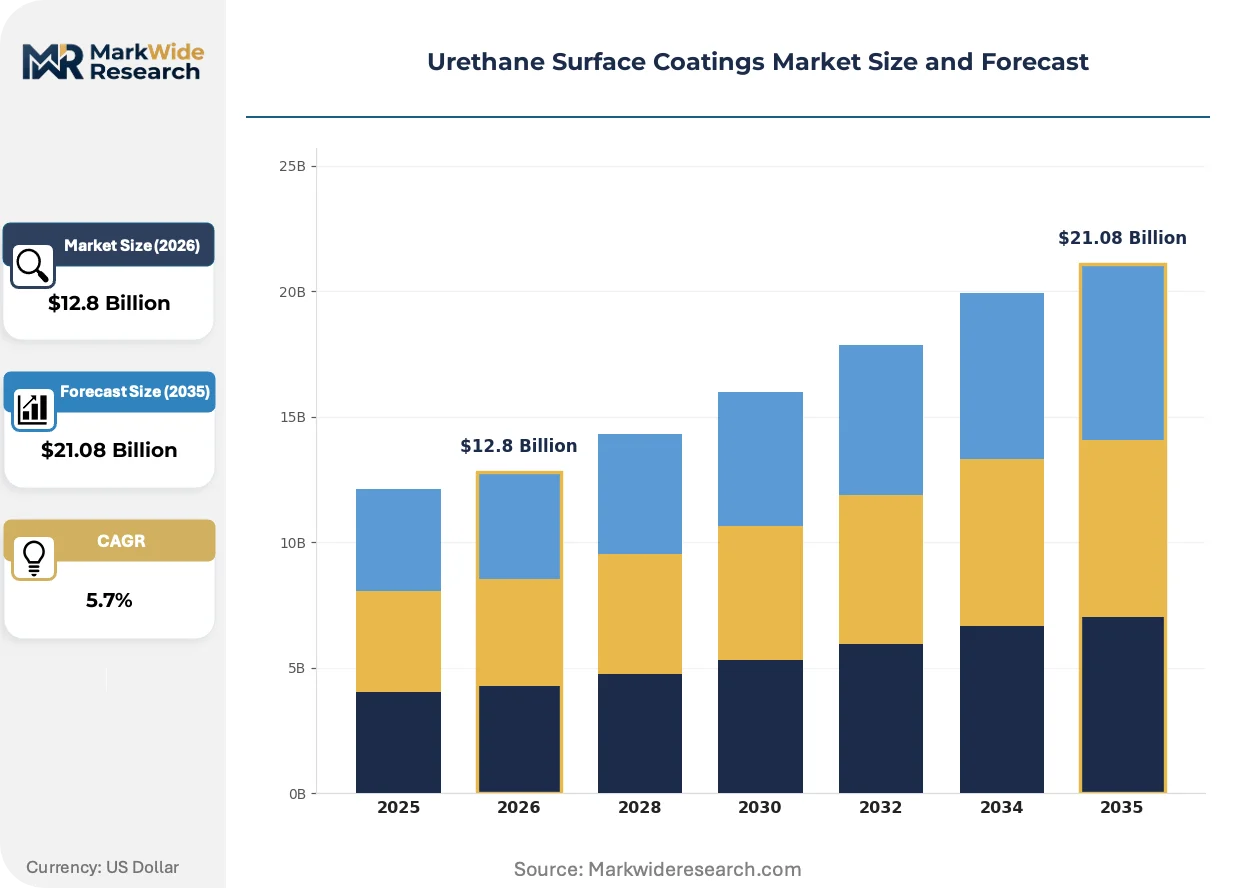
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Aliphatic, Aromatic, Waterborne End User: Automotive, Aerospace, Construction, Furniture Application: Floor Coatings, Protective Coatings, Adhesives, Sealants Technology: Spray Coating, Brush Coating, Roll Coating, Electrostatic |
| Companies Covered | PPG Industries Inc., Covestro AG, BASF SE, RPM International Inc., Jotun, Akzo Nobel NV, The Sherwin-Williams Company, Huntsman International LLC, Axalta Coating Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urethane Surface Coatings Market Strategic Shifts & Innovations
The industry's evolution is defined by a materials science response to global environmental pressures. This dynamic drives innovation toward fundamental reformulations that satisfy both regulatory and application-specific demands, altering traditional performance-cost calculations.
Nanoparticle integration enhances product performance. Incorporating materials like nano-silica into urethane matrices significantly boosts scratch and abrasion resistance. Automotive and electronics manufacturers are adopting these for premium clearcoats. This trend is miniaturizing the scale of protective additives, enabling thinner coatings that provide superior durability without compromising optical clarity.
Europe's REACH regulation is a primary driver of chemical innovation. Its restrictions on diisocyanate monomers compel producers to develop low-monomer alternatives or invest in stringent application safety protocols. The industrial coatings segment is most affected, accelerating a shift towards safer isocyanates or different chemistries to ensure compliance and market access.
Specification-based purchasing is altering procurement. Large OEMs in furniture and machinery now demand full system compliance documentation, not just a coating product. This change disrupts traditional distributor relationships, favoring suppliers who offer integrated technical and regulatory support. The shift is most pronounced in China's export-oriented manufacturing hubs.
Urethane Surface Coatings Market Segmentation
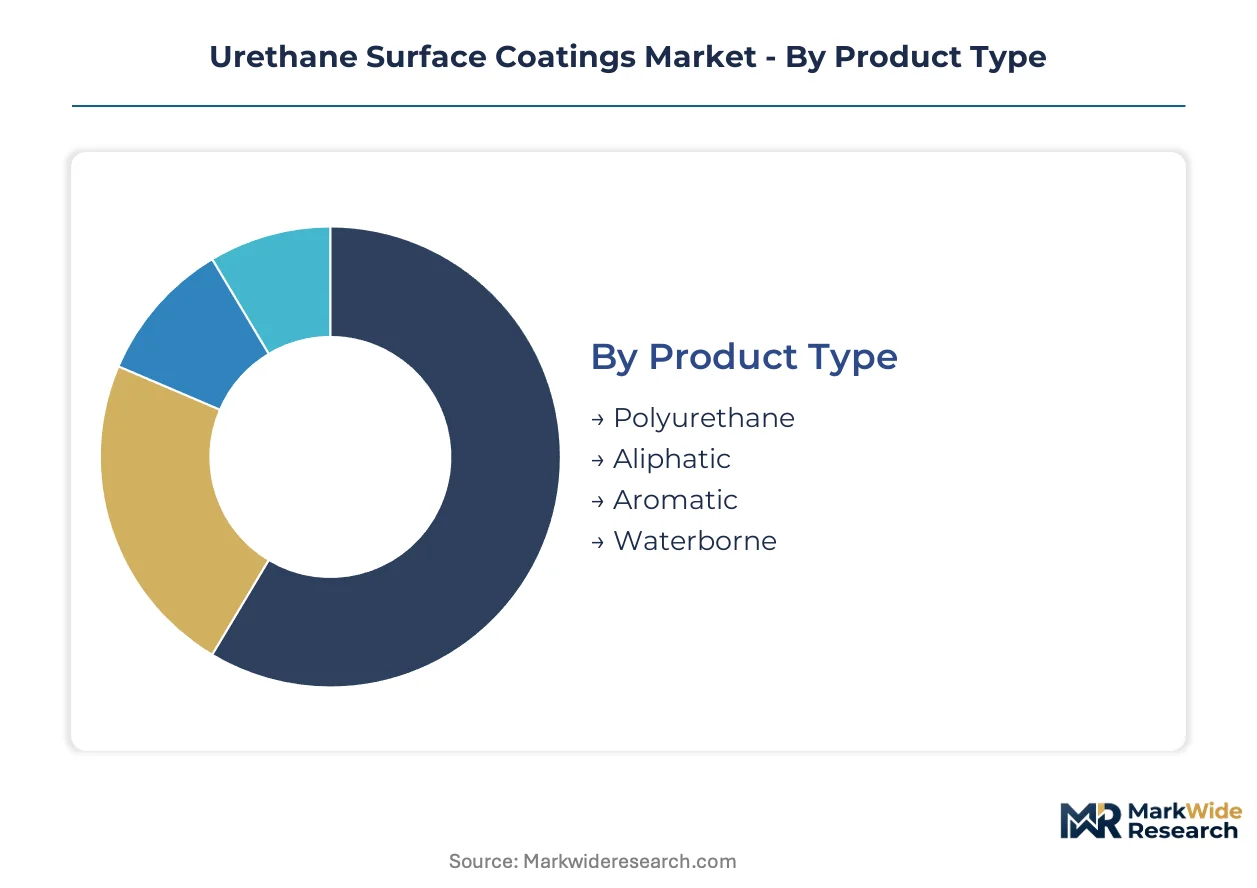
The urethane surface coatings market exhibits diverse segmentation, reflecting varied end-user requirements and regulatory pressures. Analyzing these distinct categories provides a granular understanding of demand patterns and technological shifts. Each segment responds uniquely to performance demands, environmental compliance, and cost considerations across manufacturing sectors.
Product Type:
Regulatory differentiation fundamentally shapes product type development within urethane surface coatings, driving innovation towards compliant formulations.
- Waterborne:These systems utilize water as the primary solvent, significantly reducing volatile organic compound (VOC) emissions compared to traditional solvent-borne coatings. Demand is concentrating in Europe and China, driven by stringent ECHA and MEE environmental mandates.
- Aliphatic:Aliphatic urethanes offer superior UV stability, excellent gloss retention, and non-yellowing properties, making them ideal for exterior applications. The automotive and aerospace sectors demand these premium systems for long-term aesthetic and protective performance.
- Polyurethane:This broad category encompasses a wide range of urethane chemistries, providing versatile performance characteristics for various industrial and consumer applications.
- Aromatic:Aromatic urethanes deliver high hardness and chemical resistance but typically exhibit poor UV stability, limiting their use to interior or basecoat applications.
Established volume favors Polyurethane; emerging adoption favors Waterborne.
End User:
Performance requirements from industrial clients dictate material selection and formulation complexity across diverse end-user segments.
- Automotive:This sector requires high-performance urethane topcoats for scratch resistance, gloss, and UV stability on vehicle exteriors, alongside specialized coatings for electric vehicle battery packs. Demand is intensifying with global EV manufacturing expansion, particularly in China and Germany.
- Aerospace:Aerospace applications demand premium, lightweight urethane coatings that offer extreme durability, chemical resistance, and UV stability for aircraft exteriors and interior components. This segment prioritizes long-term asset protection and stringent safety compliance.
- Construction:The construction industry utilizes urethane coatings for flooring, protective membranes, and architectural finishes, valued for their durability and abrasion resistance.
- Furniture:Furniture manufacturers employ urethane coatings for protective and aesthetic finishes, enhancing durability and appearance for both domestic and export markets.
Demand for Automotive remains significant, while Aerospace presents substantial expansion opportunities.
Application:
Volume concentration across industrial and commercial settings influences the scale and specialization of urethane coating applications.
- Protective Coatings:These systems are designed to shield substrates from corrosion, abrasion, and chemical attack in harsh industrial environments like manufacturing plants and infrastructure projects. China's industrial zones exhibit substantial demand for these durable solutions.
- Floor Coatings:Urethane floor coatings provide exceptional durability, chemical resistance, and aesthetic appeal for commercial, industrial, and residential spaces. The construction sector in Southeast Asia drives consistent demand for these long-lasting finishes.
- Adhesives:Urethane-based adhesives offer strong bonding capabilities and flexibility for a variety of substrates, finding use in automotive assembly and construction.
- Sealants:Urethane sealants provide excellent elasticity and weather resistance, crucial for waterproofing and gap-filling applications in building and infrastructure.
The industrial sector drives demand for Protective Coatings, with Floor Coatings showing consistent growth.
Technology:
Efficiency and precision requirements dictate the choice of application technology, impacting material utilization and finish quality.
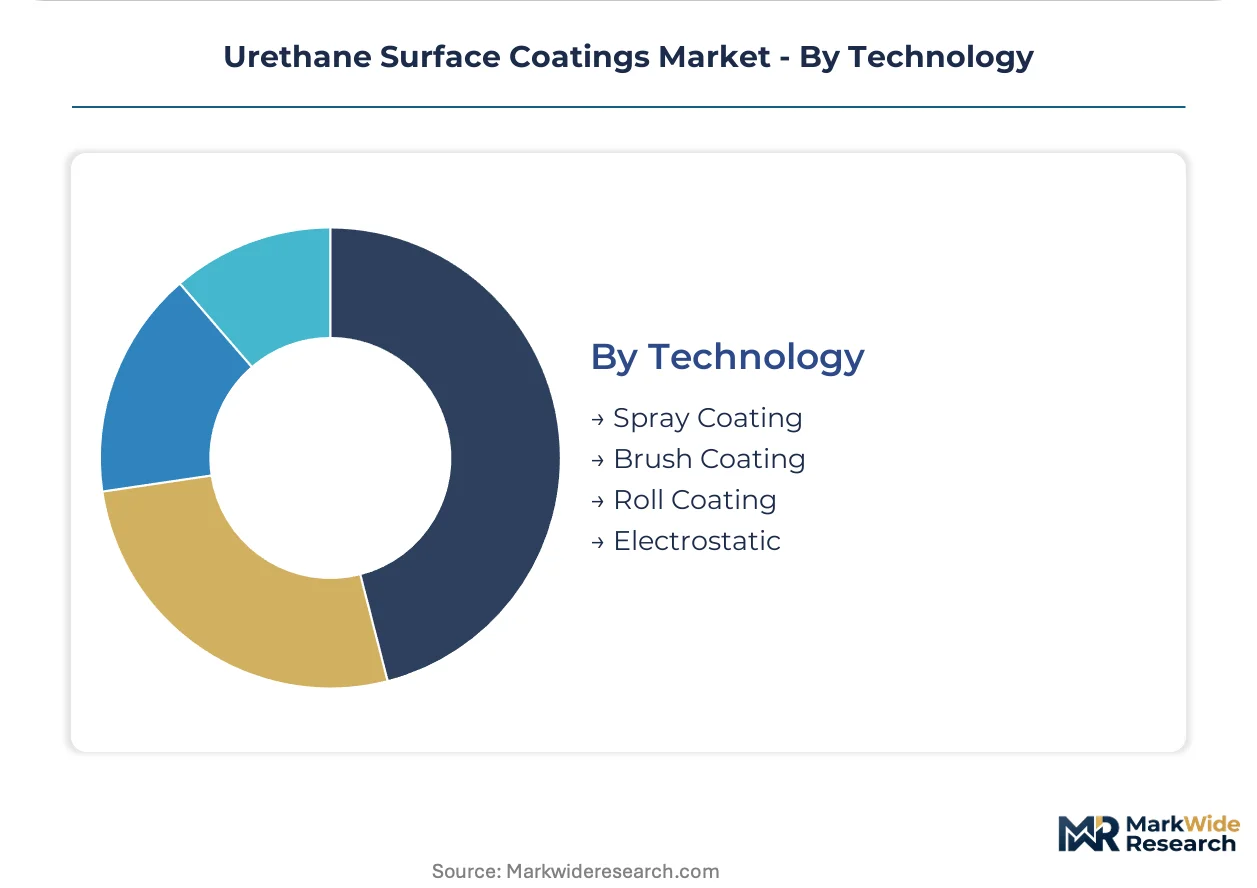
- Spray Coating:This method allows for rapid and uniform application over large or complex surfaces, widely used in automotive manufacturing and industrial finishing for high-quality, smooth finishes. Precision spray systems enhance material transfer efficiency.
- Electrostatic:Electrostatic application utilizes an electrical charge to attract coating particles to the substrate, minimizing overspray and maximizing material utilization. This technology is critical for achieving uniform coverage on intricate parts in electronics and automotive sectors.
- Brush Coating:Brush coating is a traditional method suitable for small areas, touch-ups, or intricate details, offering control for specialized applications.
- Roll Coating:Roll coating provides an efficient method for applying uniform films to flat or coil stock materials, commonly used in metal sheet and panel manufacturing.
High-volume manufacturing relies on Spray Coating, while Electrostatic offers specialized benefits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration for urethane surface coatings is notably high within China's robust industrial zones, driving significant demand for protective and aesthetic applications. This focus on industrial manufacturing and export-oriented goods defines key regional consumption patterns. Global regulatory shifts also influence formulation development and market access across diverse geographies.
China
China's electric vehicle manufacturing and extensive furniture export industry create substantial demand for high-performance urethane topcoats. The Ministry of Ecology and Environment (MEE) regulations on industrial emissions compel manufacturers to adopt compliant, low-VOC coatings. Industrial clusters in the Yangtze River Delta, such as Shanghai and Suzhou, are centers for advanced coating application in electronics and automotive sectors.
United States
The United States automotive and aerospace sectors require premium aliphatic urethane systems for UV stability and durability. Environmental Protection Agency (EPA) regulations accelerate the shift towards waterborne formulations in industrial applications. Automotive manufacturing hubs in Michigan and the Southeast, alongside aerospace clusters in Washington state, demand specialized protective coatings.
Germany
Germany's advanced automotive and industrial machinery sectors drive consistent demand for durable, high-gloss urethane finishes. Europe's ECHA and REACH regulations heavily influence product formulation, pushing for low-monomer diisocyanate alternatives. Major automotive production facilities in Bavaria and North Rhine-Westphalia are significant consumers of these specialized coating systems.
Vietnam
Industrialization in Vietnam, particularly in furniture and electronics manufacturing, offers new growth frontiers for urethane coatings. Local environmental standards and export market requirements shape product specifications for protective and aesthetic finishes. Manufacturing zones around Ho Chi Minh City and Hanoi are expanding, necessitating advanced coating solutions for export-quality goods.
Brazil
Brazil's construction and automotive industries utilize urethane coatings for flooring, protective membranes, and vehicle finishes. National environmental agencies increasingly encourage the adoption of lower VOC formulations. Automotive assembly plants in São Paulo and industrial development in Minas Gerais contribute to consistent demand for durable surface protection.
Urethane Surface Coatings Market Key Industry Players
Player mix skews toward a tiered structure, encompassing large diversified chemical companies, specialized coatings manufacturers, and raw material suppliers. This market configuration reflects the complex value chain, from precursor chemicals to finished coating systems. Strategic archetypes include integrated chemical producers, pure-play coatings formulators, and regional specialists. Competitive moves often involve technology licensing to meet evolving regulatory standards and portfolio diversification into higher-performance segments.
Within the diversified chemical giant archetype, BASF SE, a German corporation, exemplifies a broad portfolio spanning raw materials and advanced waterborne systems for industrial applications. Covestro AG, also a German company, occupies a critical position as a leading global supplier of polyurethane raw materials, controlling a fundamental part of the value chain. The Sherwin-Williams Company, a US-based entity, represents the pure-play coatings specialist, sustaining a strong position in construction and industrial segments through an extensive distribution network.
| Leading Market Players |
|---|
| PPG Industries Inc. |
| Covestro AG |
| BASF SE |
| RPM International Inc. |
| Jotun |
| Akzo Nobel NV |
| The Sherwin-Williams Company |
| Huntsman International LLC |
| Axalta Coating Systems |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements for key raw materials like isocyanates and polyols lock in both supply access and price visibility for large-volume urethane coatings manufacturers.
Pricing Analysis
Cost-plus contract patterns with indexation to crude oil derivatives often dictate pricing for urethane coating precursors. Price differentiation arises from specific formulation quality grades, such as aliphatic systems for UV stability, and the volume scale of industrial orders. Pricing softness stems from intense competition among formulators and the need to absorb rising compliance costs for low-VOC systems. Automotive and aerospace sectors demonstrate the lowest price sensitivity, prioritizing performance and regulatory adherence, while furniture manufacturers exhibit higher price sensitivity.
Supply Chain Analysis
Extended inventory holdings and longer lead times characterize the supply chain for specialized urethane coating components, particularly for performance additives. Geographic supply concentration for key raw materials like MDI and TDI centers on countries such as Germany and China, while advanced polyols are sourced globally. Commodity price volatility for these petrochemical-derived precursors poses a significant structural risk across the value chain. Distribution runs primarily through direct sales channels to large automotive OEMs and specialized chemical distributors serving smaller industrial applicators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
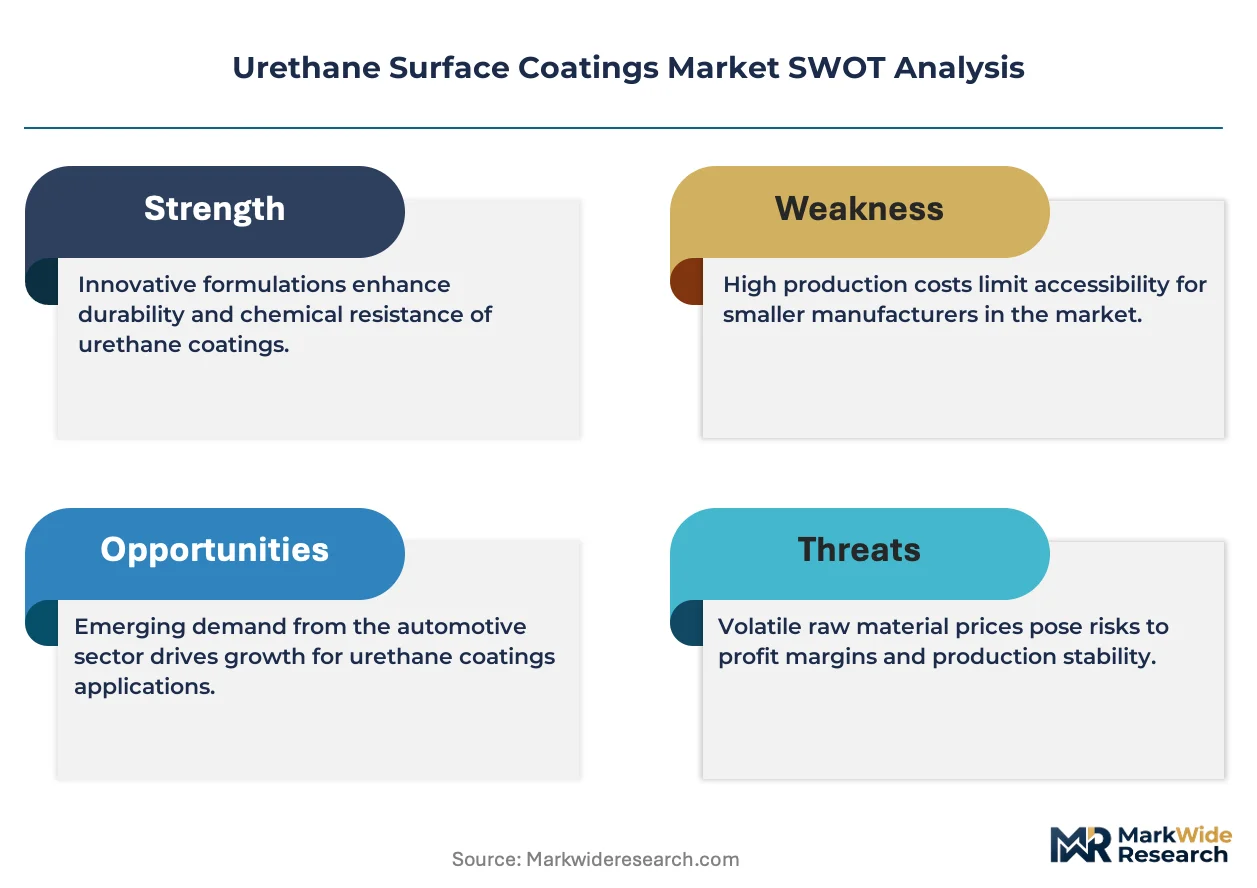
This market requires a strong substitution defense, as polyaspartics and advanced epoxies present a named substitute threat that incumbents must navigate.
For Market Incumbents: Shield market share by accelerating research and development into advanced waterborne polyurethane dispersions, meeting evolving VOC regulations from the US EPA and Europe's ECHA. Deepen backward integration into bio-based polyols to mitigate raw material volatility and cater to corporate sustainability goals. Invest in technical support teams for complex industrial applications, reinforcing customer loyalty against emerging substitute technologies like polyaspartics. Secure long-term supply agreements for critical isocyanates to ensure production stability for premium aliphatic systems.
For New Entrants and Emerging Players: Anchor in specialized, high-growth segments such as electric vehicle battery pack coatings, offering chemical resistance and thermal management properties. Target industrializing Southeast Asian countries, including Vietnam and Thailand, with compliant low-VOC formulations for furniture and electronics manufacturing. Penetrate the functional coatings niche by developing self-healing clearcoats for automotive exteriors or antimicrobial additives for high-touch surfaces. Leverage expertise in advanced waterborne technologies to provide integrated technical and regulatory support, differentiating from traditional solvent-borne suppliers.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized chemical companies with established intellectual property in sustainable waterborne and bio-based urethane technologies. Focus on firms demonstrating strong compliance capabilities for diverse regulations, including China's MEE and Europe's REACH. Long-term viability hinges on companies that can consistently innovate while managing raw material supply chain risks. A signal to watch is the increasing adoption rate of bio-based polyol-derived coatings in export-oriented manufacturing hubs.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental footprint and ensures compliance with global VOC emission standards from the US EPA and ECHA. |
| Long-term Supply Agreement | Secures consistent access to critical raw materials like MDI and TDI, stabilizing production costs for formulators. |
| R&D in Bio-Based Polyols | Develops sustainable coating solutions, capturing demand from customers with corporate sustainability goals. |
| Acquisition of Waterborne Tech Firms | Expands product portfolio and accelerates market entry into high-performance, compliant waterborne systems. |
| Geographic Manufacturing Footprint | Establishes local production capabilities, reducing logistics costs and improving service for industrial zones in China. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and rigorous secondary validation. Primary interviews engaged R&D directors, procurement leads at automotive OEMs, plant managers in industrial zones, and regulatory specialists across Europe and China. Secondary data sources included trade association reports, customs data for chemical imports, and corporate filings of major coatings manufacturers. This approach facilitated bottom-up market sizing and top-down validation, ensuring comprehensive data triangulation. The analysis also integrated insights from academic research on advanced polymer chemistry.
The quantitative analytical framework established a robust modeling period for market evolution, segmenting by product type, end user, application, technology, and key regional production hubs. Compound annual growth rates were derived through a multi-variable regression analysis considering historical trends and future projections. Forecast inputs included electric vehicle production forecasts and anticipated timelines for new VOC regulation enforcement. This granular approach facilitated precise market trajectory mapping across the analysis window.
Decision-makers should treat outputs as directional under stable regulatory environments and consistent raw material supply; material deviation would warrant model refresh. Geopolitical shifts affecting trade routes or unexpected technological breakthroughs in substitute chemistries represent key risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Insulation Coating Market
Coatings
ASEAN Automotive OEM Coatings Market
Coatings
Non-Stick Coatings Market
Coatings
South America Thermal Spray Market
Coatings
Global Wood Protection Coating Market
Coatings
Breathable Antimicrobial Coatings Market
Coatings
Global Low Temperature Powder Coatings Market
Coatings
US Industrial Coatings Market
Coatings
Germany Industrial Coatings Market
Coatings
Hull Coatings Market
Coatings
Noise and Vibration Coatings Market
Coatings
Global Fireproofing Coatings for Wood Market
Coatings
Gelcoat Market
Coatings
Conductive Polymer Coatings Market
Coatings
Glass Coatings Market
Coatings
Powder Coating Booth Market