
 South America Thermal Spray Market | 2026-2036
South America Thermal Spray Market Size, Share, and Industry Trends Forecast 2026-2036
South America Thermal Spray Market Analytics
Certified thermal spray operator shortages across Brazil and Argentina are unwinding capacity expansion timelines for coating service providers. OC Oerlikon Management AG leverages its plasma spray equipment portfolio to anchor technical support networks in São Paulo and Buenos Aires. Hoganas AB sustains powder supply advantages through backward integration into atomized metal production. Sulzer competes via specialized HVOF system installations for oil field equipment refurbishment in Colombia and Venezuela.
South America thermal spray encompasses deposition processes where molten or semi-molten materials—typically metals, ceramics, or cermets at 1,500–15,000°C—impact substrates at velocities exceeding 200 m/s to build protective coatings 50 μm to several millimeters thick. These processes primarily extend component service life in corrosive, erosive, or high-temperature operating environments. Plasma spray equipment commands the technology segment due to its versatility across ceramic and metallic coating portfolios for aerospace turbine blades and medical implants. HVOF systems represent the fastest-expanding technology category as energy sector buyers prioritize dense, low-porosity coatings for downhole drilling components exposed to abrasive wear. Ceramic materials dominate margin pools in medical and aerospace applications where alumina-titania and hydroxyapatite coatings command premium qualification protocols.
ANVISA regulates medical device surface treatments through biocompatibility testing mandates that restrict market access to coating providers with validated sterilization and particulate control protocols. Brazil's INMETRO certification requirements for pressure equipment and the country's adoption of ABNT NBR ISO 14922 corrosion protection standards shape product specifications for industrial coating contracts. Argentina's IRAM standards and Chile's SEC technical regulations add compliance layers for cross-border equipment suppliers. Stakeholders must monitor how MERCOSUR technical harmonization negotiations reshape certification reciprocity for coating materials and processes across the customs union.
Market Dynamics
Certified thermal spray operator shortages across Brazil and Argentina are compressing coating service capacity just as aerospace maintenance demand accelerates in São Paulo's industrial corridor. This labor scarcity is forcing equipment owners to extend turnaround times or invest in automated deposition systems.
Growth Catalysts
- HVOF technology penetration:Energy sector buyers in Colombia and Venezuela prioritize dense, low-porosity coatings for downhole drilling components exposed to abrasive wear conditions.
- ANVISA biocompatibility mandates:Brazil's medical device regulator tightens qualification requirements for implant coatings, filtering market access toward validated sterilization and particulate control protocols.
- São Paulo industrial clustering:Southeastern Brazil's automotive and energy equipment manufacturers concentrate demand within a 200-kilometer radius, reducing logistics costs for coating service providers.
Market Restraints
- Atomized metal powder supply concentration:Backward-integrated powder producers in Europe and North America control premium alloy feedstock pricing, exposing South American coaters to currency fluctuation risk.
- ABNT NBR ISO 14922 compliance friction:Brazil's corrosion protection standards for pressure equipment require extensive third-party validation, extending contract qualification timelines by 4-8 months.
- Plasma spray equipment capex intensity:Automated multi-axis deposition systems require capital outlays exceeding $800,000 per installation, restricting independent service provider expansion.
Strategic Opportunities
- Argentine medical implant coating underpenetration:Buenos Aires metropolitan area hosts growing orthopedic device manufacturing with limited local thermal spray qualification capacity.
- MERCOSUR technical harmonization:Ongoing customs union negotiations may create certification reciprocity for coating materials across Brazil, Argentina, Paraguay, and Uruguay.
- Cold spray technology convergence:Solid-state deposition methods combined with robotics enable repair of temperature-sensitive aluminum aerospace structures without substrate distortion.
Industry Challenges
- Certified operator pipeline collapse:Brazil's SENAI technical training centers produce fewer than 120 qualified plasma spray technicians annually against industry demand exceeding 400.
- INMETRO pressure equipment certification delays:Backlogged inspection queues extend coating qualification timelines for oil and gas sector contracts by 6-12 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Thermal Spray Market |
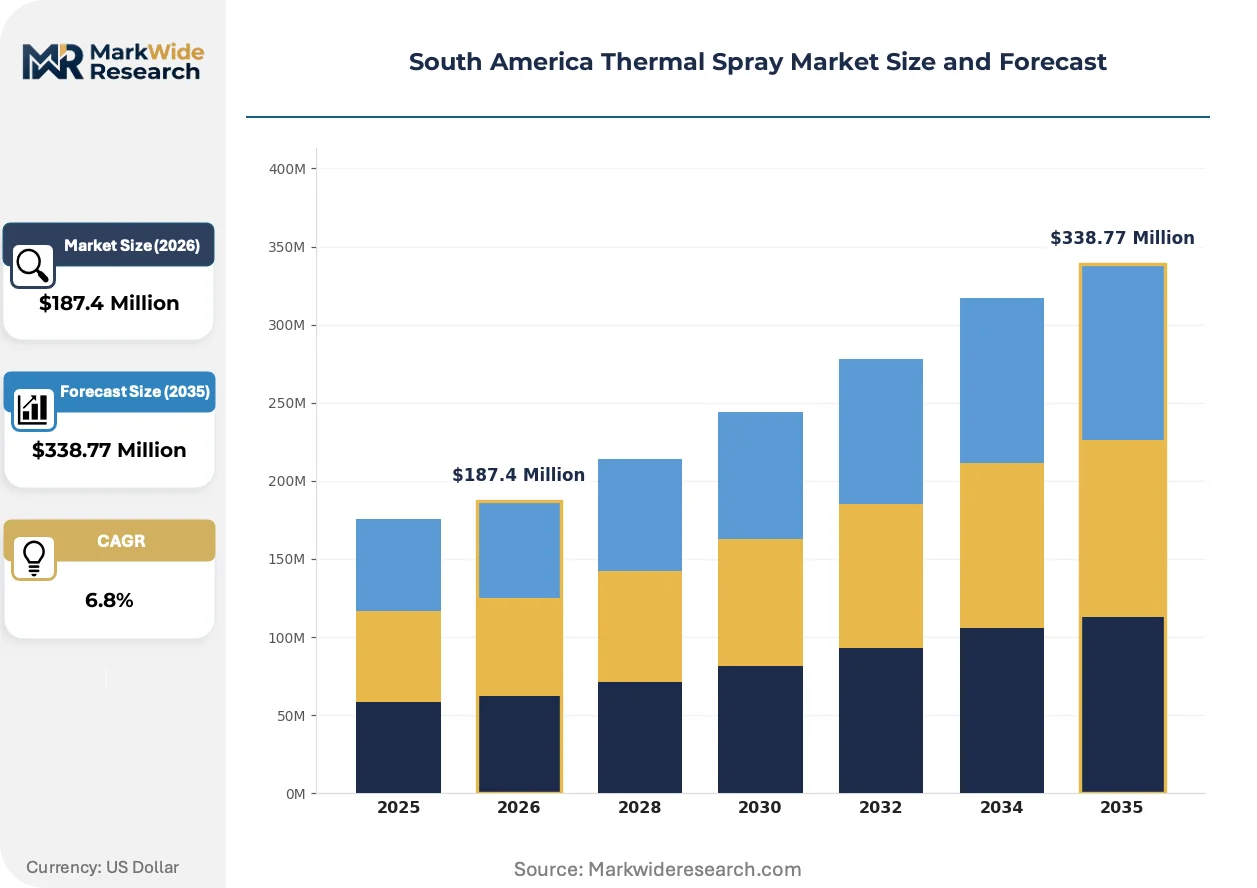
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Plasma Spray, Flame Spray, HVOF, Electric Arc Material: Ceramics, Metals, Composites, Polymers Application: Aerospace, Automotive, Energy, Medical End User: Manufacturing, Oil & Gas, Defense, Electronics |
| Companies Covered | OC Oerlikon Management AG, Saint-Gobain, Hoganas AB, Linde Plc, Castolin Eutectic, Sulzer, H.C. Starck, Praxair Surface Technologies, Wall Colmonoy, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Thermal Spray Market Evolving Landscape
Process automation and regulatory digitization are compressing traditional coating service models while creating new technical barriers to market entry. Equipment manufacturers now compete on integrated software-control platforms rather than hardware specifications alone.
Cold spray deposition is fragmenting the repair coating landscape for temperature-sensitive substrates. Aerospace maintenance operations in Brazil adopt solid-state aluminum and copper deposition for rotorcraft gearbox housings and wing structures. The technology eliminates heat-affected zones but requires inert gas consumption rates three times higher than thermal spray, compressing margin structures for high-volume contractors.
ANVISA's biocompatibility testing mandates are reshaping medical coating procurement patterns. Implant manufacturers must now document particulate contamination thresholds below 50 particles per cubic meter during deposition. São Paulo-based coating houses invest in ISO 14644-1 Class 7 cleanroom installations to maintain qualification status, raising fixed cost structures across the medical device supply chain.
Buyer consolidation among Brazilian oil field service companies is compressing vendor lists for equipment refurbishment. Petrobras and its tier-one contractors now mandate single-source coating agreements covering HVOF, plasma spray, and flame spray processes. Independent service providers in Rio de Janeiro state respond by forming technical alliances to present unified qualification packages against integrated multinational competitors.
South America Thermal Spray Market Segmentation
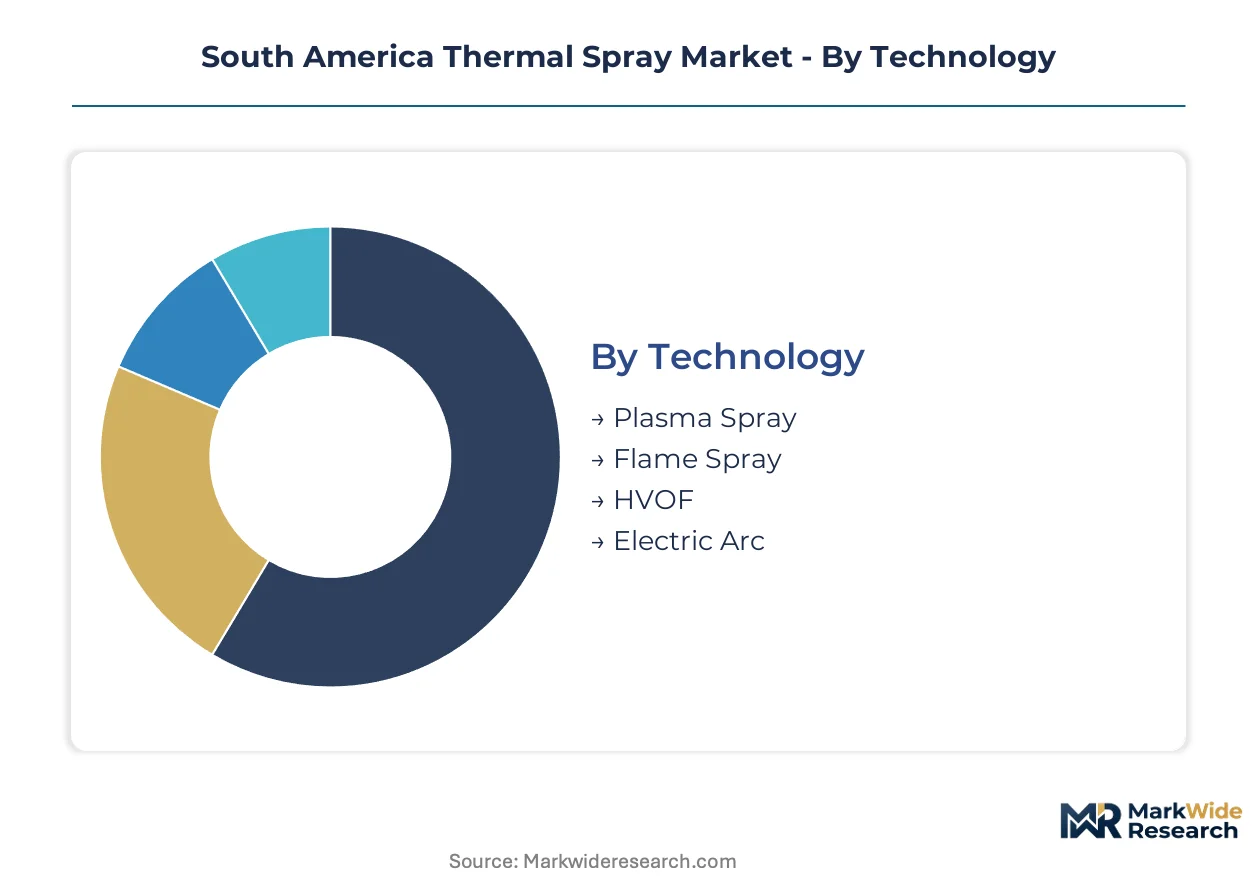
Thermal spray segmentation in South America reflects divergent channel economics. Equipment sales flow through distributor networks anchored in São Paulo, while coating services concentrate around industrial clusters where certified operators maintain proximity to aerospace and energy buyers.
Technology:
Technology selection determines capital deployment intensity and operator certification requirements across Brazilian and Argentine service channels.
- Plasma Spray:High-velocity ionized gas streams propel ceramic and metallic powders at temperatures exceeding 15,000°C, producing dense coatings with controlled microstructures. São Paulo's aerospace maintenance corridors concentrate demand for turbine blade restoration, though equipment capex exceeding $800,000 per automated cell restricts independent provider participation.
- HVOF:Combustion-driven supersonic particle velocities generate low-porosity, high-bond-strength deposits ideal for wear-resistant applications. Colombian and Venezuelan oil field operators prioritize this technology for downhole drilling component refurbishment, driving fastest expansion among all thermal spray categories.
- Flame Spray:Oxygen-fuel combustion delivers economical metallic and ceramic coatings for lower-specification industrial applications. Brazilian agricultural equipment manufacturers in Rio Grande do Sul utilize flame spray for harvester component protection.
- Electric Arc:Twin-wire arc discharge melts feedstock directly, offering high deposition rates for large-area corrosion protection. Argentine shipyards along the Paraná River employ electric arc systems for vessel hull maintenance.
Plasma spray dominates installed base. HVOF is where expansion concentrates.
Material:
Material margins stratify sharply across medical qualification tiers and industrial volume segments.
- Ceramics:Alumina-titania and hydroxyapatite formulations command premium pricing in ANVISA-regulated implant coating workflows. São Paulo cleanroom installations processing ceramic medical deposits maintain particulate thresholds below 50 particles per cubic meter, raising fixed cost barriers for new entrants.
- Metals:Atomized nickel, cobalt, and iron-based alloys constitute the volume foundation for industrial repair and protection applications. Brazilian coating houses face currency exposure on premium alloy feedstock sourced from European backward-integrated producers.
- Composites:Cermet blends combining ceramic hardness with metallic toughness address extreme wear environments. Chilean copper mining operations specify tungsten carbide-cobalt composites for slurry pump refurbishment.
- Polymers:Thermoplastic deposits provide corrosion barriers on temperature-sensitive substrates. Argentine chemical processing plants deploy polymer coatings for tank interior protection.
Metals anchor volume throughput. Ceramics capture margin concentration.
Application:
Application mix varies with regional industrial structure and regulatory stringency.
- Aerospace:Turbine component restoration and airframe repair demand AS9100-qualified processes with full traceability documentation. Brazil's expanding MRO sector in São José dos Campos drives plasma spray adoption for engine hot section refurbishment.
- Automotive:Cylinder bore thermal barriers and transmission component wear coatings support OEM and aftermarket demand. São Paulo state's powertrain manufacturing cluster concentrates automotive coating procurement.
- Energy:Power generation turbines and oil field equipment require erosion-corrosion protection for extended service intervals. Petrobras vendor consolidation mandates single-source agreements spanning multiple thermal spray technologies.
- Medical:Orthopedic and dental implants demand biocompatible hydroxyapatite and porous titanium coatings. ANVISA's tightening sterilization validation protocols filter market access toward established cleanroom operators.
Energy commands largest project scale. Medical maintains steepest qualification barriers.
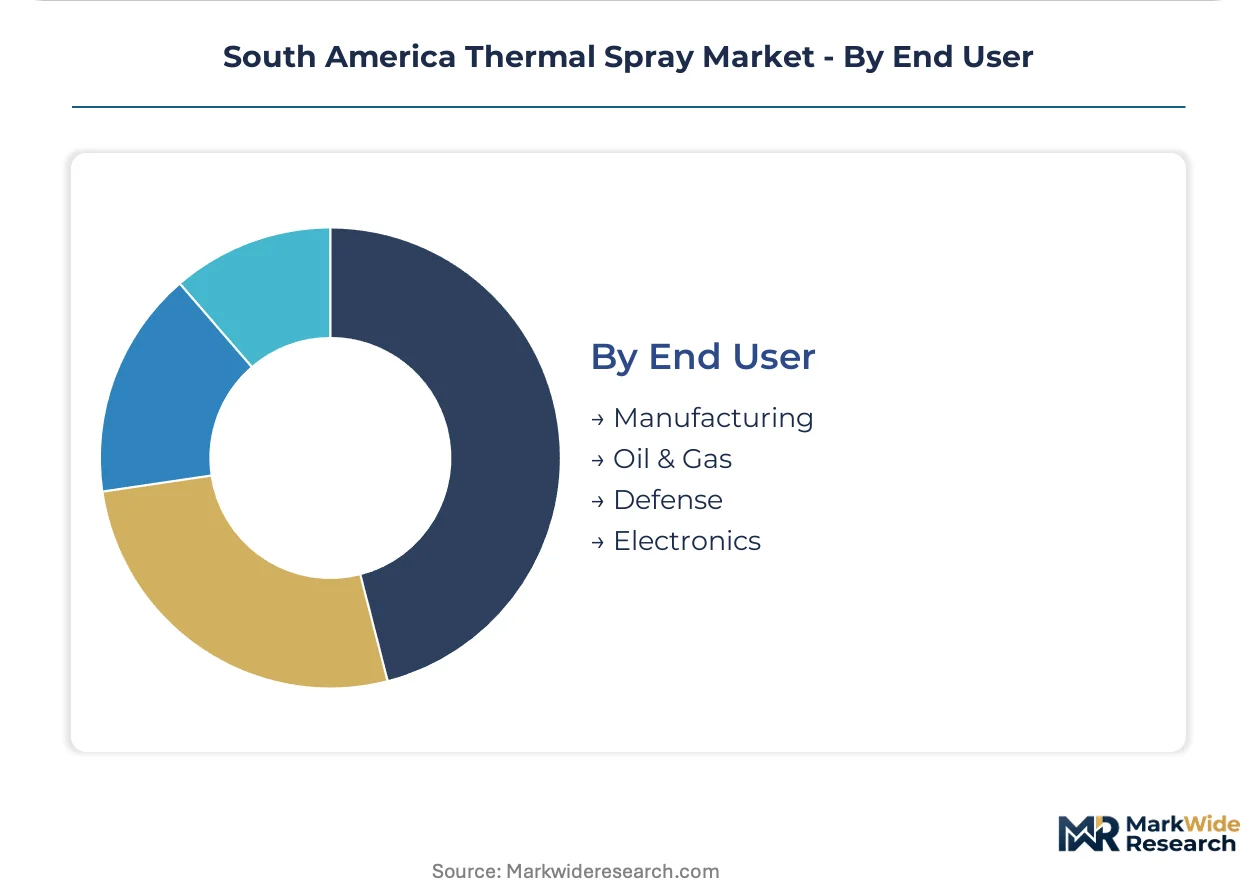
End User:
End user procurement patterns diverge between capital-intensive asset owners and outsourced maintenance providers.
- Manufacturing:In-house coating capabilities at Brazilian automotive and machinery producers compete with independent service bureaus for maintenance workflow capture.
- Oil & Gas:Petrobras and tier-one contractors specify coating performance warranties tied to field service life, shifting technical risk onto coating providers.
- Defense:Brazilian Armed Forces maintenance depots require ITAR-compliant processes for aerospace component restoration, limiting supplier pools.
- Electronics:Semiconductor manufacturing equipment demands specialized thermal management coatings with ultra-low outgassing specifications.
Manufacturing retains largest captive coating capacity. Oil & Gas drives outsourced service expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA regulates Brazil's medical device surface treatments through biocompatibility mandates that filter coating provider access. The South America thermal spray market concentrates demand across southeastern industrial corridors and Andean energy basins.
Brazil
São Paulo state's automotive and aerospace clusters drive plasma spray adoption for turbine blade restoration and cylinder bore thermal barriers. INMETRO certification requirements for pressure equipment extend coating qualification timelines by 4-8 months. The São José dos Campos maintenance corridor hosts expanding MRO operations requiring AS9100-qualified thermal spray processes.
Argentina
Buenos Aires metropolitan area orthopedic device manufacturers generate underpenetrated demand for hydroxyapatite implant coatings. IRAM standards add compliance layers for cross-border equipment suppliers entering from Brazil. Paraná River shipyards employ electric arc spray systems for vessel hull corrosion protection.
Colombia
Oil field operators in the Llanos Basin prioritize HVOF coatings for downhole drilling components exposed to abrasive wear. The national hydrocarbons regulator shapes equipment refurbishment standards for Petrobras-tier contractors operating across the border. Bogotá-based service providers coordinate with Venezuelan field operations for cross-border equipment restoration.
Chile
Copper mining operations in the Atacama Desert specify tungsten carbide-cobalt cermet composites for slurry pump refurbishment. SEC technical regulations govern industrial equipment safety certifications affecting coating procurement workflows. Antofagasta's mining equipment maintenance hubs concentrate demand for wear-resistant thermal barrier applications.
Venezuela
Orinoco Belt heavy crude extraction drives demand for erosion-corrosion protection in progressive cavity pumps and wellhead equipment. Currency fluctuation risk complicates powder feedstock procurement from European backward-integrated producers. Maracaibo-based maintenance depots rely on Colombian service providers for specialized HVOF system installations.
South America Thermal Spray Market Competitive Landscape
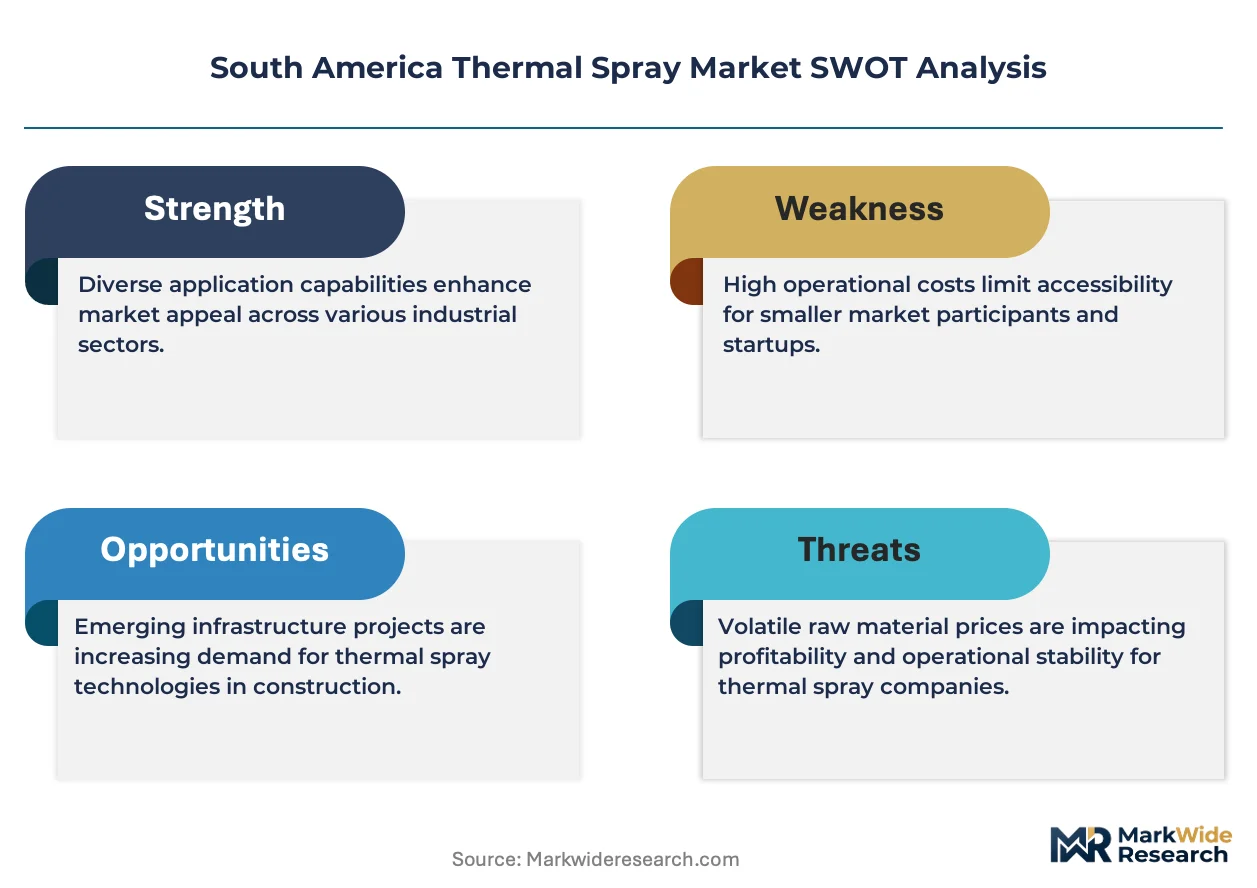
A small set of integrated leaders sits above a broader specialist tier in South America's thermal spray market. Equipment manufacturers with captive powder supply chains command pricing leverage over independent coating houses. Two strategic archetypes dominate: European-origin integrated systems suppliers and regional service bureaus with certified operator networks. Competitive moves concentrate on automated deposition system deployments and technical alliance formations to present unified qualification packages against multinational competitors.
Among European-integrated leaders, OC Oerlikon Management AG and Sulzer exemplify the equipment-led expansion archetype, while Hoganas AB occupies a position representing backward-integrated powder supply dominance. These three companies anchor the competitive structure through differentiated control points across the value chain.
| Leading Market Players |
|---|
| OC Oerlikon Management AG |
| Saint-Gobain |
| Hoganas AB |
| Linde Plc |
| Castolin Eutectic |
| Sulzer |
| H.C. Starck |
| Praxair Surface Technologies |
| Wall Colmonoy |
| Others |
Value Network & Pricing Analysis
Ninety-to-120-day lead times on atomized metal powders from European backward-integrated producers compress Brazilian coating houses' working capital cycles and amplify currency-driven pricing volatility across São Paulo's service corridor. This inventory pressure concentrates pricing power with Hoganas AB and OC Oerlikon Management AG, which leverage captive powder supply to undercut independent operators on project bids.
Pricing Analysis
Brazil-Argentina price spreads of 15-25% on equivalent HVOF coating services reflect INMETRO certification cost absorption and logistics fragmentation across MERCOSUR borders. Project-based pricing dominates, with differentiation anchored in AS9100 aerospace qualification tiers versus standard industrial repair grades. Cost compression in the automotive tier intensifies as São Paulo powertrain manufacturers consolidate vendor lists and demand extended payment terms. Medical device coaters show least price sensitivity due to ANVISA biocompatibility validation barriers that filter qualified competitors.
Supply Chain Analysis
Inventory buffers at Colombian oil field service depots rarely exceed 45 days due to Venezuelan currency instability disrupting cross-border powder replenishment. Feedstock draws from Sweden, Germany, and Austria for premium nickel-cobalt alloys; Brazil and Argentina supply lower-grade ferrous wire for electric arc systems. Single-source vulnerability concentrates in ceramic oxide feedstock for medical implants, where Saint-Gobain and H.C. Starck control qualified hydroxyapatite formulations. Distribution runs through São Paulo-based technical distributors with field service capabilities, bypassing direct equipment sales to independent coating houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America thermal spray market sits in early-cycle recovery as Brazilian aerospace MRO capacity expansion reactivates deferred maintenance workflows. Petrobras capital expenditure normalization and ANVISA medical device approval acceleration provide twin demand anchors.
For Market Incumbents: Secure certified operator pipelines through SENAI training center partnerships before Argentine orthopedic manufacturers expand coating demand. Backward integration into ceramic powder qualification protocols defends margin position against emerging cold spray entrants targeting temperature-sensitive aerospace substrates. Anchor technical support networks in Buenos Aires to preempt MERCOSUR harmonization arbitrage. For New Entrants and Emerging Players: Lead with automated plasma spray cell deployments in Rio Grande do Sul's agricultural equipment cluster, where flame spray quality thresholds create upgrade demand without AS9100 qualification barriers. Argentine medical implant coating underpenetration offers the most penetrable white space given IRAM compliance friction that slows Brazilian incumbent expansion. Pursue Petrobras-tier contractor technical alliances to present unified HVOF-plasma-flame qualification packages against integrated multinational competitors. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because certified operator scarcity and ANVISA cleanroom fixed cost barriers favor scaled platforms over fragmented independent service bureaus. Target mid-cap coating houses with established São Paulo aerospace qualifications and latent capacity for Argentine medical expansion. Watch MERCOSUR technical harmonization implementation velocity as the signal for cross-border vendor list rationalization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Production | Hoganas AB's atomized metal captive supply anchors pricing leverage against currency-exposed Brazilian coaters. |
| Automated Deposition System Deployment | OC Oerlikon Management AG's multi-axis plasma cells address SENAI-certified operator shortages compressing São Paulo capacity. |
| Cleanroom Certification Investment | ISO 14644-1 Class 7 installations filter ANVISA-compliant medical coating competitors and raise fixed cost barriers. |
| Cross-Border Technical Alliance Formation | Independent Rio de Janeiro providers present unified qualification packages against Sulzer's integrated HVOF-plasma-flame offerings. |
| Cold Spray Technology Convergence | Solid-state aluminum deposition captures Brazilian rotorcraft MRO demand without heat-affected zone distortion risks. |
Research Methodology
Cross-validation between primary interviews with coating service operations managers and secondary validation through ANVISA regulatory filings anchors the qualitative findings. Field discussions with SENAI training center directors, Petrobras procurement leads, and Argentine orthopedic device manufacturing engineers informed operator pipeline and demand trajectory assessments. Bottom-up triangulation against customs data on atomized metal powder imports and top-down reconciliation with INMETRO pressure equipment certification queues shaped volume estimates. Secondary sources included ABNT NBR ISO 14922 corrosion protection documentation, MERCOSUR technical harmonization negotiation records, and aerospace MRO capacity announcements from São José dos Campos.
Sensitivity analysis on currency fluctuation scenarios and certified operator production rates frames the projection uncertainty. The analytical framework segments across technology, material, application, and end-use dimensions, with additional modeling on regulatory compliance tier and geographic industrial cluster density. CAGRs derive from installed equipment base depreciation schedules and replacement demand curves, informed by HVOF system penetration rates in Colombian oil fields and plasma spray adoption in Brazilian turbine restoration workflows.
Forecasts assume regulatory continuity in ANVISA biocompatibility mandates and INMETRO pressure equipment standards; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Industrial Floor Coatings Market
Coatings
ASEAN Protective Coatings Market
Coatings
Global PET Film Coated Steel Coil Market
Coatings
Polysiloxane Coatings Market
Coatings
Global Coated Steel Market
Coatings
Protective Coatings Market
Coatings
Global Solar Panel Coatings Market
Coatings
Dispersion Coating Market
Coatings
Carpet Back Coatings Market
Coatings
Anti-Corrosion Nanocoatings Market
Coatings
Fluoropolymer Coating Market
Coatings
Plastic-Coated Wires Market
Coatings
Industrial Coatings Market
Coatings
Global Mirror Coatings Market
Coatings
Metallic Powder Coating Market
Coatings
Self-Healing Coatings Market