
 Color-Shifting Coating Market | 2026-2036
Color-Shifting Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Color-Shifting Coating Market Intelligence
Aftermarket service revenue for color-matching and finish restoration is narrowing as OEMs extend factory warranty coatings and captive refinish networks. BASF SE leverages its pigments-to-coatings integration to control raw material quality for interference pigment systems. PPG Industries sustains automotive refinish dominance through its global distribution network and brand strength in collision repair channels. VIAVI Solutions Inc. specializes in optical thin-film expertise, positioning its layered coating technology for security and anti-counterfeiting applications where precision differentiates performance.
Color-shifting coatings employ multi-layer thin-film interference structures, liquid crystal microencapsulation, or thermochromic pigment systems to produce angle-dependent hue changes, typically measured by flop index values exceeding 15 on standardized goniophotometers. These finishes serve anti-counterfeiting, premium aesthetics, and functional signaling roles across packaging, currency, automotive, and electronics sectors. Interference pigments occupy the largest value pool due to mature supply chains and broad automotive adoption, while thermochromic formulations represent the fastest-expanding technology segment driven by interactive packaging and temperature-indicating medical applications. Security printing anchors steady demand from government document issuers, with polymer integration technology enabling substrate-compatible coatings that resist mechanical wear and chemical degradation.
EPA VOC regulations under 40 CFR Part 59 restrict solvent-borne formulation sales in the United States, while REACH Annex XVII entries on nickel compounds and chromium VI constrain pigment selections across European coatings production. China's MEE enforces GB standards on industrial coating VOC emissions, accelerating domestic waterborne platform development. Stakeholders must monitor evolving substance restrictions and certification requirements for food-contact packaging coatings, as regulatory divergence between jurisdictions reshapes product development priorities and geographic market access conditions.
Market Dynamics
Automotive OEMs now mandate color-shifting finishes for electric vehicle differentiation, forcing coating suppliers to reconfigure pigment supply chains and reformulate platforms for waterborne and UV-curable compliance.
Growth Catalysts
- Electric vehicle premiumization:OEMs specify interference pigments for exterior differentiation, creating dedicated specification pipelines for multi-layer thin-film systems.
- REACH Annex XVII constraints:Nickel compound and chromium VI restrictions accelerate compliant pigment development, favoring suppliers with integrated raw material control.
- Anti-counterfeiting mandates:Government document issuers embed optical thin-film layers in polymer substrates, expanding security printing demand.
Market Restraints
- Interference pigment supply concentration:Multi-layer flake production clusters in limited geographies, exposing formulators to single-source vulnerability.
- EPA 40 CFR Part 59 compliance costs:Solvent-borne platform phase-out requires capital-intensive waterborne conversion for US-based production.
- Fluoropolymer substitution threat:High-performance conventional coatings capture functional signaling applications where angle-dependent hue is secondary.
Strategic Opportunities
- Interactive packaging expansion:Thermochromic microencapsulation enables temperature-indicating medical and food-contact applications with regulatory-compliant substrates.
- China GB standards alignment:Domestic waterborne platform development accelerates as MEE enforcement tightens, creating captive supply advantages for local producers.
- UV-curable convergence:Electron beam and UV-LED curing technologies merge with interference pigment dispersion, enabling instant-process automotive refinish.
Industry Challenges
- Thin-film deposition expertise scarcity:Optical coating engineers capable of precision layer-stack design command premium compensation, constraining R&D scaling.
- Food-contact certification timelines:FDA and EFSA migration testing for packaging coatings extends commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Color-Shifting Coating Market |
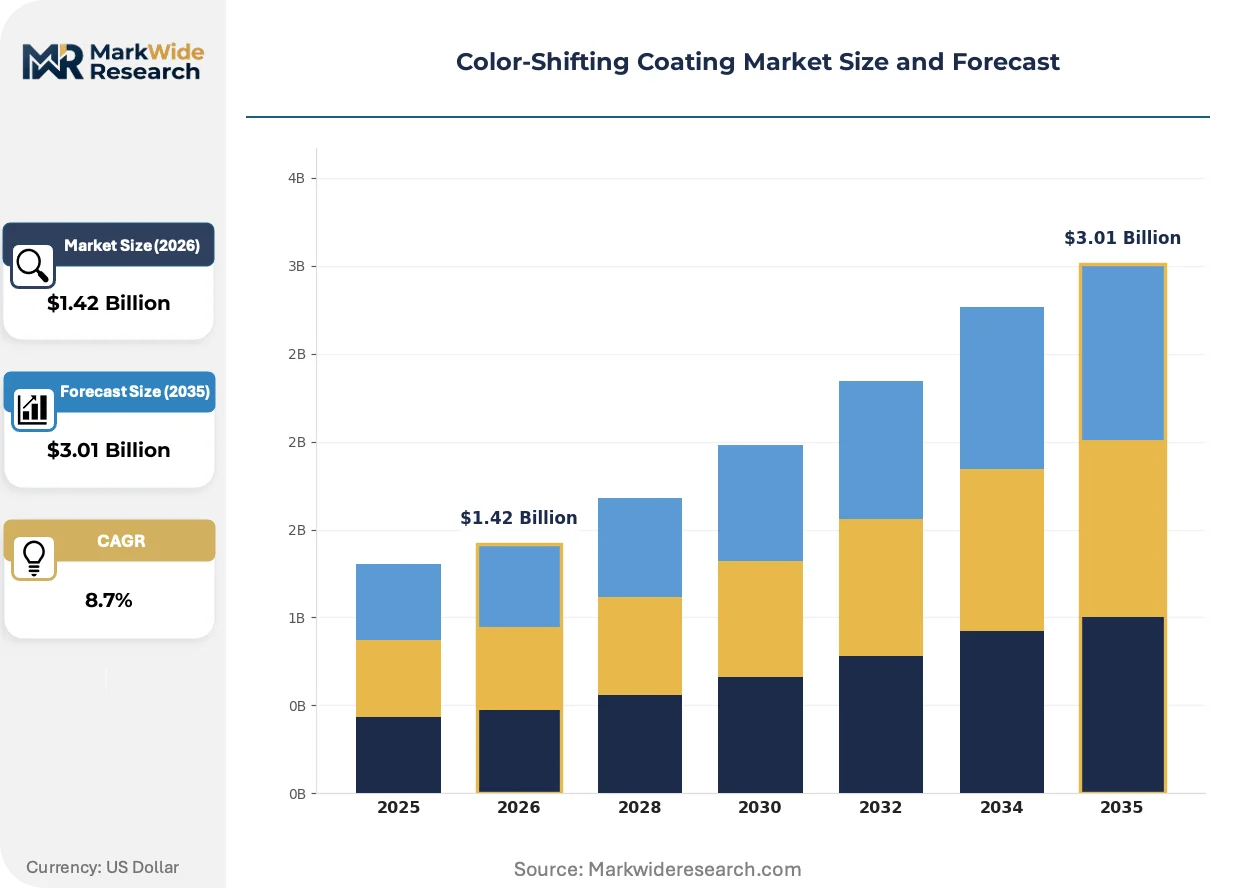
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interference Pigments, Liquid Crystals, Thermochromic, Photochromic, Iridescent Application: Packaging Decoration, Security Printing, Consumer Electronics, Automotive Finishes, Textile Coatings End User: Packaging Manufacturers, Printing Specialists, Electronics Assemblers, Vehicle Refurbishers, Textile Producers Technology: Layered Coatings, Nanoparticle Dispersion, Polymer Integration, UV-Curable Systems, Waterborne Formulations |
| Companies Covered | 3M, BASF SE, The Sherwin-Williams Company, PPG Industries, Akzo Nobel, VIAVI Solutions Inc., Axalta Coating Systems, Nippon Paint Holdings, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Color-Shifting Coating Market Strategic Shifts & Innovations
Formulation platforms are pivoting toward instant-cure and substrate-flexible systems as regulatory pressure and automotive cycle times compress development windows.
Spectrophotometric color-matching hardware is digitizing quality control workflows across collision repair networks. BASF and PPG distributors deploy handheld goniophotometers linked to cloud-based flop index databases, compressing color verification from hours to minutes. This capability is digitizing aftermarket service economics and eroding independent refinish shops without capital access.
REACH Annex XVII entries on microplastics and PFAS precursors are reshaping pigment carrier systems. European formulators substitute fluorinated wetting agents with bio-based alternatives, degrading interference pigment orientation efficiency until process parameters stabilize. Automotive exterior clears face the steepest reformulation burden as OEM durability warranties require 10-year weathering performance.
Certificate-of-analysis requirements now govern spot-purchasing for security printing substrates. Government document issuers unbundle coating supply from substrate procurement, inserting accredited testing laboratories as mandatory intermediaries. This pattern concentrates most visibly in European and Middle Eastern currency and passport programs where optical variable device specifications carry legal tender status.
Color-Shifting Coating Market Segmentation

Color-shifting coating procurement decisions cascade through four interconnected dimensions: pigment chemistry determines optical performance, application substrate dictates formulation compatibility, end-user operational scale shapes volume contracting, and curing technology locks in capital equipment requirements. Understanding these segment boundaries clarifies where specification power concentrates and where supplier margins erode.
Product Type:
Interference pigments, liquid crystals, and thermochromic systems each occupy distinct positions on the cost-performance spectrum for angle-dependent color effects.
- Interference Pigments:Multi-layer thin-film metal oxide flakes deposited on mica or synthetic substrates create precise hue shifts through optical path length variation. Automotive OEM exterior specifications in Germany and China absorb the majority of high-flake-content formulations, with BASF and Merck KGaA controlling substrate quality through captive supply of synthetic mica.
- Liquid Crystals:Cholesteric mesophases self-assemble into helical structures that selectively reflect circularly polarized light across temperature and voltage ranges. Security printing applications in Swiss and Japanese passport programs specify polymer-encapsulated cholesteric layers for machine-readable authentication features.
- Thermochromic:Microencapsulated leuco dye-developer-solvent systems trigger reversible color transitions at defined temperature thresholds. Interactive packaging for temperature-sensitive pharmaceuticals in the United States and medical cold-chain indicators represent the steepest expansion trajectory.
- Photochromic:Spiropyran and naphthopyran molecules undergo reversible ring-opening under UV exposure. Eyewear and architectural glazing applications in Australia and South Africa drive demand for durable organic photochromic dispersions.
- Iridescent:Structural color from periodic nanostructures in butterfly-wing mimetic coatings provides angle-independent metallic effects without metallic content. Cosmetics and premium spirits packaging in France and Italy specify iridescent finishes for regulatory-compliant metallic aesthetics.
The dominant share belongs to interference pigments, while thermochromic is closing the gap fastest.
Application:
End-use requirements fragment sharply between decorative premiumization and functional authentication mandates.
- Packaging Decoration:Premium cosmetics and spirits brands specify color-shifting finishes for shelf differentiation. Folding carton and flexible film converters in Milan and São Paulo integrate interference varnishes into existing press lines with minimal speed reduction.
- Security Printing:Government document issuers mandate optical variable devices with defined color-switch angles for banknotes and passports. De La Rue and Giesecke+Devrient procurement specifications govern flake orientation and adhesion standards.
- Consumer Electronics:Smartphone and laptop OEMs specify subtle color travel for device back panels. Foxconn and Luxshare assembly lines in Shenzhen and Zhengzhou apply vacuum-deposited thin-film stacks before final component integration.
- Automotive Finishes:OEM clearcoat and basecoat systems incorporate interference pigments for exterior differentiation. Tesla and BYD specification pipelines now require waterborne-compliant multi-layer systems with 10-year durability warranties.
- Textile Coatings:Synthetic leather and technical fabric finishes incorporate thermochromic microcapsules for wearable temperature indication. Italian and Portuguese automotive upholstery suppliers pilot production lines for heated-seat visual feedback systems.
Security printing commands specification authority through legal tender requirements, while automotive finishes scale fastest as EV premiumization accelerates.
End User:
Procurement sophistication varies dramatically across buyer categories, with captive specification pipelines separating strategic accounts from spot purchasers.
- Packaging Manufacturers:Folding carton, corrugated, and flexible film converters specify coatings compatible with existing press speeds and drying infrastructure. Tetra Pak and Amcor negotiate annual volume contracts with pigment-to-formulation suppliers.
- Printing Specialists:Security printers and narrow-web label converters maintain accredited laboratories for optical variable device verification. De La Rue and Bundesdruckerei certificate-of-analysis requirements now govern all raw material lots.
- Electronics Assemblers:Contract manufacturers integrate coating application into component assembly sequences. Foxconn and Pegatron specify vacuum deposition partners with Class 1000 cleanroom capability for back-panel finishing.
- Vehicle Refurbishers:Collision repair networks purchase refinish systems through distributor relationships. PPG and Axalta distributor networks in Texas and California deploy spectrophotometric color-matching hardware to compress verification cycles.
- Textile Producers:Synthetic leather and technical fabric manufacturers integrate coating into calendering or knife-over-roll processes. Italian automotive upholstery specialists in Tuscany pilot thermochromic integration for heated-seat applications.
Printing specialists extract maximum supplier performance through accreditation mandates, while electronics assemblers are gaining procurement leverage fastest as smartphone volumes concentrate.
Technology:
Curing chemistry and deposition method determine capital intensity, regulatory compliance, and substrate compatibility.
- Layered Coatings:Physical vapor deposition of metal oxides onto polymer or paper substrates creates precise optical thin-film stacks. VIAVI Solutions and OVD Kinegram supply vacuum deposition systems for security substrate manufacturers in Switzerland and Germany.
- Nanoparticle Dispersion:Colloidal metal and metal oxide particles in liquid carriers provide structural color without flake orientation requirements. University spinouts in Cambridge and Boston pilot plasmonic nanoparticle systems for packaging applications.
- Polymer Integration:Pigment incorporation into extruded or cast polymer substrates enables durable security features. ID card and passport substrate manufacturers in the Netherlands and Finland specify polymer-integrated optical variable devices.
- UV-Curable Systems:Acrylate oligomers with photoinitiator packages enable instant cure for high-speed printing and automotive refinish. PPG and BASF development programs target UV-LED compatible interference pigment dispersions for collision repair networks.
- Waterborne Formulations:Acrylic and polyurethane dispersions replace solvent-borne systems to meet EPA and MEE VOC regulations. Chinese domestic producers in Guangdong and Jiangsu accelerate waterborne platform development for GB standard compliance.
Layered coatings retain premium positioning for security applications, while waterborne formulations are expanding most quickly as regulatory enforcement tightens across multiple jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multi-layer thin-film flake production clusters in Germany and China, exposing formulators elsewhere to raw material dependency. Regulatory divergence across EPA, REACH, and China's MEE standards fragments formulation development priorities. Tier-one cities in China and automotive clusters in Germany absorb premium volumes.
China
Beijing, Shanghai, and Shenzhen drive premium automotive and electronics consumption for color-shifting finishes. The MEE enforces GB standards on industrial coating VOC emissions, accelerating domestic waterborne platform development. Guangdong and Jiangsu provinces host captive supply advantages for local producers meeting these tightened requirements.
Germany
Automotive OEM specifications from Stuttgart and Munich mandate interference pigment systems for EV exterior differentiation. REACH Annex XVII entries on nickel compounds and chromium VI constrain pigment selections, favoring suppliers with integrated raw material control. The Rhine-Main industrial corridor concentrates reformulation expertise for compliant multi-layer systems.
United States
EPA 40 CFR Part 59 restricts solvent-borne formulation sales, forcing capital-intensive waterborne conversion for domestic production. Tesla and Detroit-based OEMs specify color-shifting clearcoats with 10-year durability warranties. Texas and California collision repair networks deploy spectrophotometric color-matching hardware to compress verification cycles.
Japan
Cholesteric liquid crystal layers in polymer-encapsulated formats serve machine-readable authentication for passport programs. METI guidance on sustainable materials influences coating substrate selections. The Kansai region around Osaka anchors optical thin-film deposition expertise for security printing applications.
Switzerland
Swiss passport and currency programs specify optical variable devices with defined color-switch angles for legal tender status. Certificate-of-analysis requirements now govern spot-purchasing for security printing substrates. The Zurich-Geneva corridor concentrates accredited testing laboratories as mandatory intermediaries in procurement chains.
Color-Shifting Coating Market Key Industry Players
Pigment-to-formulation integrators and specialized optical coating houses split the market between automotive scale and security precision. The structure favors suppliers with captive raw material control or vacuum deposition expertise. Three archetypes dominate: diversified chemical conglomerates with backward integration into pigment substrates, standalone coating formulators reliant on external flake supply, and optical technology specialists leveraging thin-film physics. Competitive moves center on waterborne platform certification and accredited laboratory partnerships for government document issuers.
Among diversified chemical conglomerates, BASF SE and Merck KGaA represent the integrated archetype with captive synthetic mica supply. PPG Industries occupies a position within automotive refinish distribution. VIAVI Solutions Inc. exemplifies the optical specialization vector for security substrate applications. These three anchors illustrate how strategic positioning diverges between volume automotive specifications and precision anti-counterfeiting mandates.
| Leading Market Players |
|---|
| 3M |
| BASF SE |
| The Sherwin-Williams Company |
| PPG Industries |
| Akzo Nobel |
| VIAVI Solutions Inc. |
| Axalta Coating Systems |
| Nippon Paint Holdings |
| Merck KGaA |
| Others |
Cost & Logistics Intelligence
Synthetic mica substrate production clusters in China and Germany concentrate upstream margin capture for interference pigment systems, forcing downstream formulators to absorb flake cost volatility or surrender margin to integrated suppliers like BASF and Merck KGaA. Automotive OEMs and security printers occupy opposite ends of pricing power, with specification authority determining who bears reformulation costs under tightening VOC regulations.
Pricing Analysis
Aftermarket refinish service revenue now drives lifetime value for coating suppliers, with PPG and Axalta bundling spectrophotometric color-matching hardware into annual distributor contracts. Three-tier pricing structure across premium interference systems, standard thermochromic formulations, and economy-grade iridescent finishes segments buyers by certification requirements and durability warranties. Pricing pressure stems from waterborne platform conversion costs as EPA and China's MEE enforcement tightens. Independent collision repair shops show highest price sensitivity due to capital constraints on color-matching equipment, while government document issuers accept premium positioning for legal-tender-grade optical variable devices.
Supply Chain Analysis
Export-control restrictions on vacuum deposition equipment limit technology transfer for multi-layer thin-film production, constraining capacity expansion outside Germany, China, and Japan. Raw material dependencies center on synthetic mica substrates, metal oxide precursors, and photoinitiator packages for UV-curable platforms. Single-source vulnerability concentrates in high-purity titanium dioxide and cholesteric liquid crystal precursors where qualified suppliers number fewer than five globally. Distribution runs through authorized distributor networks for automotive refinish, direct procurement contracts for security printing substrates, and spot purchasing for packaging converters with certificate-of-analysis requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Color-shifting coating procurement is evolving into a service-attach business where color-matching verification and extended durability warranties expand recurring revenue faster than pigment volume growth. Formulation suppliers capturing aftermarket service relationships will outearn commodity flake vendors.
For Market Incumbents: Harden specification pipelines by embedding waterborne platform certification into OEM procurement contracts before REACH Annex XVII microplastics restrictions phase out legacy solvent systems. Deepen backward integration into synthetic mica production to insulate margin from raw material concentration in Chinese and German substrate suppliers. Capture collision repair channel control through spectrophotometric hardware deployment that locks independent shops into proprietary color databases. For New Entrants and Emerging Players: Thermochromic microencapsulation for pharmaceutical cold-chain indicators in the United States represents the most penetrable entry point, with FDA food-contact certification timelines creating a moat against established pigment houses. UV-curable interference dispersions for automotive refinish in Texas and California offer second-mover advantage as PPG and BASF struggle with UV-LED compatibility. Partner with accredited testing laboratories to shortcut certificate-of-analysis requirements for security printing substrate qualification. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive refinish distributors consolidating collision repair networks through color-matching hardware financing. Long-term viability hinges on waterborne platform dominance as regulatory enforcement eliminates solvent-borne alternatives across multiple jurisdictions. Watch for inflection when China's MEE accelerates GB standard enforcement, triggering captive supply advantages for domestic producers with certified waterborne systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Mica | BASF and Merck KGaA control substrate quality for interference pigments, insulating margin from supply concentration. |
| UV-Curable Platform Development | PPG targets UV-LED compatible dispersions to compress automotive refinish cycle times in collision repair networks. |
| Accredited Laboratory Partnership | De La Rue and Giesecke+Devrient procurement now mandates testing intermediaries for optical variable device verification. |
| Waterborne Formulation Certification | Chinese domestic producers in Guangdong accelerate GB compliance to capture MEE enforcement-driven substitution demand. |
| Spectrophotometric Hardware Deployment | Cloud-linked goniophotometers digitize aftermarket economics and erode independent refinish shop competitiveness. |
Research Approach
A spread of perspectives from automotive OEM procurement managers, security printer technical directors, coating formulator R&D leads, and pigment supplier sales executives converged on the working assumptions for volume and value segmentation. Primary fieldwork combined structured interviews with downstream specification authorities and upstream raw material suppliers, validated against customs trade data for interference pigment flake movements, ECHA REACH registration databases, EPA 40 CFR Part 59 regulatory filings, and SEC 10-K disclosures from listed coating manufacturers. Bottom-up triangulation across end-use demand segments and top-down reconciliation against disclosed production capacity produced convergent estimates.
Demand-supply balance modeling anchored projections, with segmentation across pigment chemistry tiers, application substrates, curing technology platforms, and regional regulatory clusters. The analytical framework incorporated automotive OEM specification pipelines, government document issuer procurement cycles, and packaging converter press-line integration constraints. CAGRs derived from fitted growth curves against historical adoption patterns for comparable coating technology transitions, with cross-checks against disclosed capital expenditure plans for waterborne platform capacity and UV-LED curing equipment installations.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, currency exchange rate movements affecting raw material import costs, or abrupt regulatory enforcement acceleration would shift the trajectory. Forecasts reflect documented assumptions on specification adoption timelines and reformulation cost pass-through rates. Material shifts in REACH microplastics restrictions or EPA VOC rulemaking stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Polyvinylidene Chloride (PVDC) Coated Films Market
Coatings
Hydrophilic Interior Glass Defogging Coatings Market
Coatings
Functional Coil Coating Market
Coatings
E-Coat Market
Coatings
Polyvinylidene Fluoride (PVDF) Coatings Market
Coatings
Canada Automotive OEM Coatings Market
Coatings
Global Surface Protection Films Market
Coatings
Vacuum Coating Machine Market
Coatings
Fire Retardant Coatings Market
Coatings
Asia-Pacific Epoxy Powder Coatings Market
Coatings
Electrocoat Market
Coatings
Sol-Gel Coatings Market
Coatings
Coating Auxiliaries Market
Coatings
Hydrophilic Coatings Market
Coatings
Global Powder Coating Market
Coatings
Breathable Antimicrobial Coatings Market