
 Coating Pre-Treatment Market | 2026-2036
Coating Pre-Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Coating Pre-Treatment Market Outlook
China is tilting toward expanded phosphate and zirconium conversion coating capacity to serve domestic automotive OEMs and heavy equipment builders. Henkel AG & Co. KGaA leverages its Chemetall surface treatment division to anchor European aerospace and automotive pre-treatment supply. PPG Industries competes through integrated coating-to-pre-treatment systems that control specification-setting at major manufacturing accounts. Nihon Parkerizing dominates Japan's automotive pre-treatment segment with specialized phosphate process technology and captive R&D facilities.
Coating pre-treatment encompasses chemical, electrochemical, and mechanical surface conditioning processes applied to metal substrates before protective or decorative coating deposition, typically involving phosphate, alkaline, or acidic formulations that enhance adhesion and corrosion resistance through controlled microcrystalline layer formation. The primary industrial purpose is to ensure coating durability on steel and aluminum components exposed to cyclic moisture, salt, and mechanical stress in automotive body panels, aerospace structures, and heavy machinery frames. Conversion coatings and phosphate systems occupy the largest value share due to entrenched automotive OEM specifications and established supply chain qualification requirements, while alkaline cleaners sustain steady demand from electronics manufacturers processing precision metal housings. Chemical treatment technology leads in installed capacity and process familiarity, though electrochemical processes are gaining traction where reduced wastewater volumes and tighter film weight control justify capital investment.
REACH restrictions on hexavalent chromium and nickel compounds are forcing reformulation across European pre-treatment chemical suppliers, while EPA effluent guidelines in the United States shape wastewater handling investments at metal finishing operations. China's GB standards and MEE environmental enforcement are tightening discharge limits for phosphate sludge and heavy metal content from surface treatment facilities. Japan's METI energy efficiency directives influence process temperature reduction targets that favor low-temperature zirconium and silane-based conversion systems. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation investments and misaligned capacity commitments.
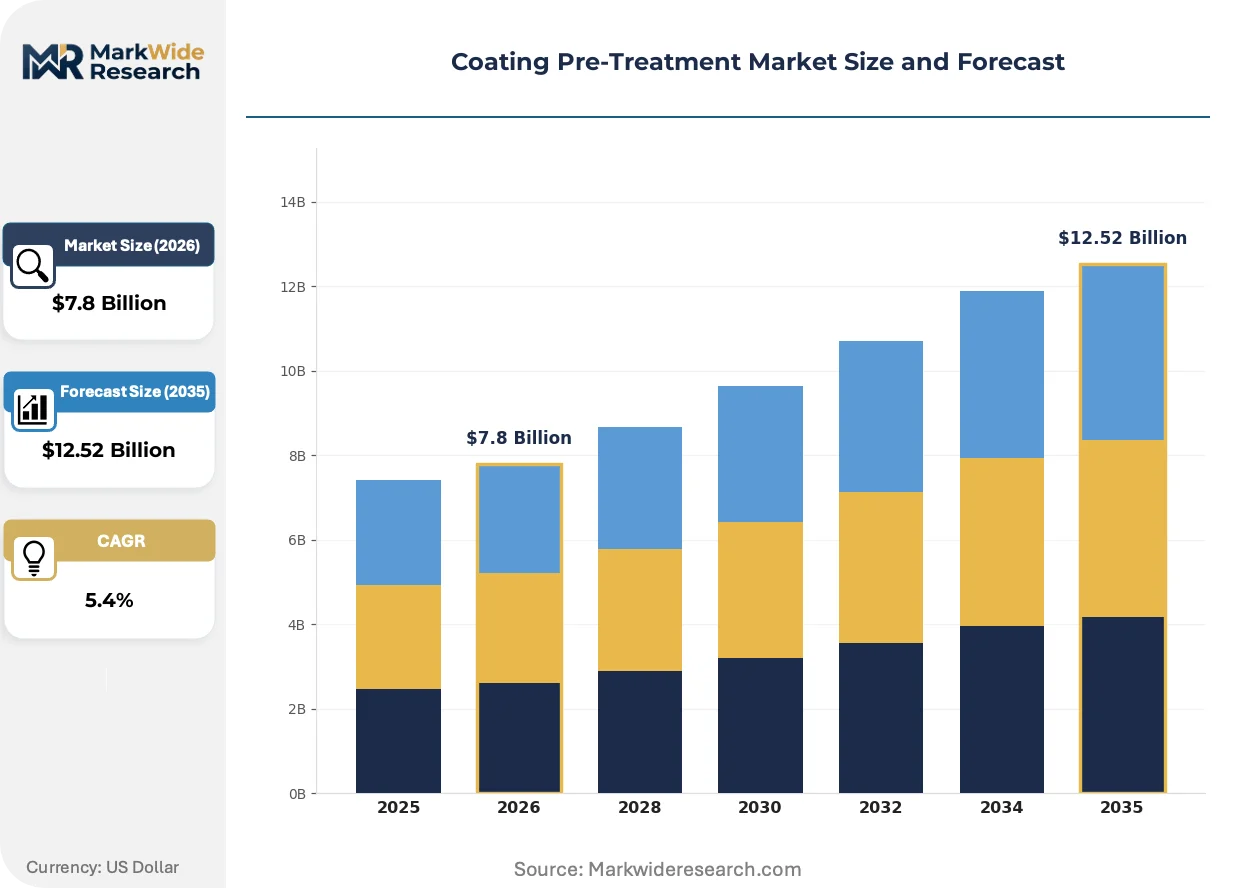
Market Dynamics
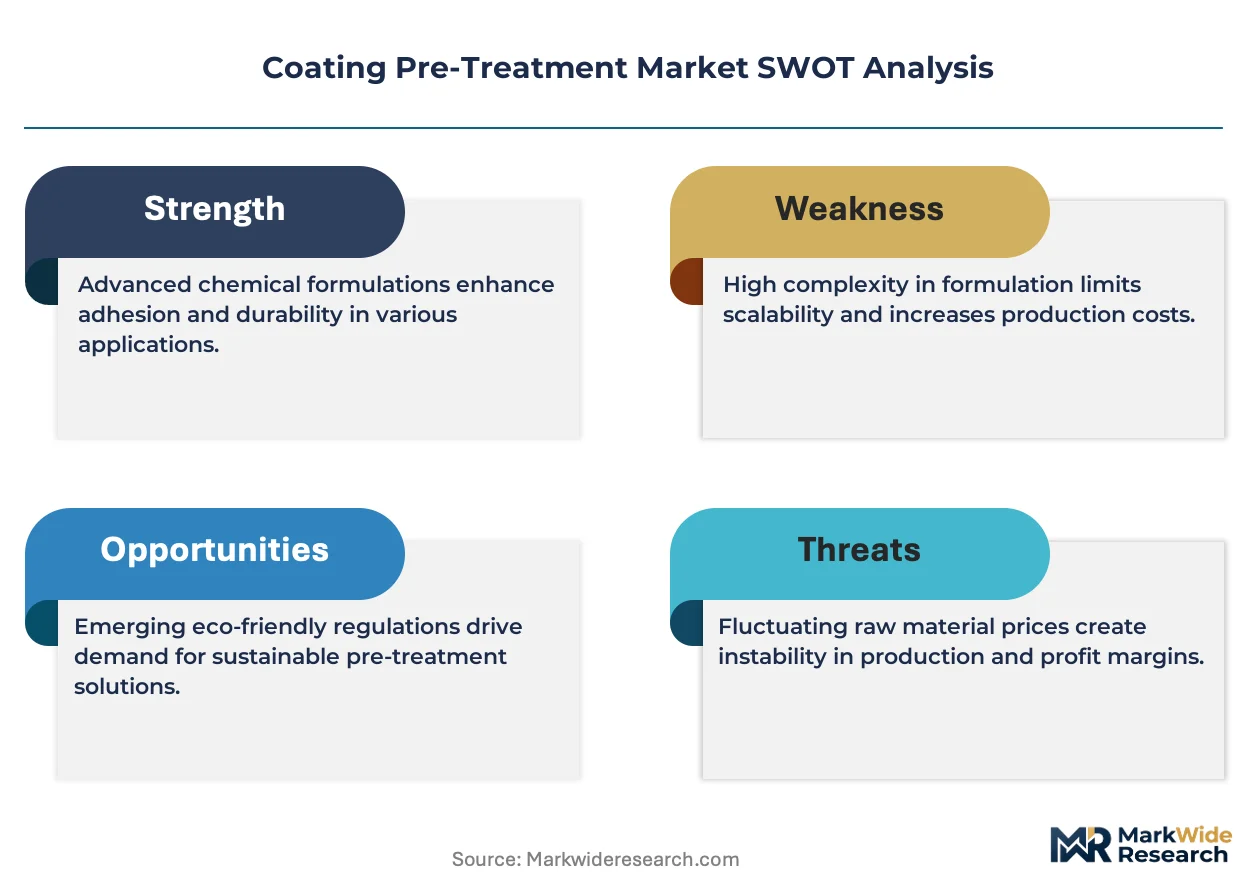
REACH restrictions on hexavalent chromium formulations are forcing European automotive paint shops to requalify entire pre-treatment process chains ahead of 2026 supply contract renewals, compressing the timeline for zirconium-based conversion coating adoption.
Growth Catalysts
- Automotive OEM specification tightening:German manufacturers around Wolfsburg and Stuttgart production corridors are mandating phosphate and zirconium conversion coatings for new vehicle assembly programs, pulling demand from captive surface treatment facilities.
- EPA effluent guideline enforcement:US metal finishing operations face stricter wastewater discharge limits that favor electrochemical pre-treatment processes with reduced sludge generation and tighter film weight control.
- China's GB standard alignment:Domestic automotive OEMs and heavy equipment builders are expanding phosphate capacity to meet MEE environmental enforcement on heavy metal content from surface treatment discharge.
Market Restraints
- Phosphate raw material concentration:Phosphoric acid supply concentrates in Chinese and Moroccan phosphate rock processing, exposing formulated pre-treatment chemical suppliers to input cost volatility and freight disruption.
- REACH reformulation friction:The ECHA authorization process for chromium-free alternatives creates 18-24 month qualification delays that strand existing hexavalent chromium investments at European metal finishing operations.
- Silane substitution threat:Thin-film silane-based conversion coatings from electronics precision metal housing applications are migrating into automotive specification trials, threatening phosphate system volume in lower-corrosion-duty segments.
Strategic Opportunities
- India automotive paint shop expansion:PLI scheme incentives for domestic vehicle manufacturing are attracting pre-treatment chemical suppliers to establish local formulation and technical service presence around Chennai and Pune assembly clusters.
- Low-temperature zirconium convergence:Silane-based coupling agents combined with zirconium oxide conversion layers enable ambient-temperature process lines that reduce natural gas consumption and align with METI energy efficiency directives in Japan.
- Aerospace MRO channel development:Independent maintenance repair overhaul facilities serving European and Middle Eastern aviation fleets represent an underpenetrated channel for chromate-free conversion coating qualification beyond OEM captive shops.
Industry Challenges
- Process chemistry skill scarcity:Electrochemical pre-treatment line operation requires combined metallurgical and electrochemical expertise that metal finishing operations struggle to recruit against semiconductor and battery manufacturing compensation benchmarks.
- Legacy phosphate line retrofit capex:Conversion from heated zinc phosphate to ambient zirconium systems demands tank replacement, heating system decommissioning, and rinse water recycling infrastructure that mid-cap job shops cannot finance internally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coating Pre-Treatment Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline, Acidic, Phosphate, Conversion Coatings Application: Aerospace, Automotive OEMs, Electronics, Heavy Equipment End User: Manufacturers, Service Providers, Original Equipment Manufacturers, Research Institutions Technology: Chemical Treatment, Biochemical Treatment, Electrochemical Processes, Mechanical Processes |
| Companies Covered | PPG Industries, 3M, Henkel AG & Co. KGaA, Nippon Paint, Axalta Coating Systems, The Sherwin-Williams Company, Chemetall GmbH, Nihon Parkerizing, Akzo Nobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coating Pre-Treatment Market Strategic Shifts
Process digitalization and closed-loop chemistry management are compressing the gap between laboratory formulation and production line stability, enabling real-time bath adjustment that reduces chemical consumption and extends solution life.
Digital twin modeling of conversion coating bath chemistry is virtualizing the traditional laboratory titration and hull cell testing workflow that pre-treatment chemical suppliers rely on for technical service. Automotive paint shops in Germany are deploying inline spectroscopic monitoring that feeds predictive algorithms, compressing the feedback loop between bath degradation and chemical replenishment from shift-based to continuous. This virtualization is enabling remote technical service models that reduce on-site chemist deployment and shift margin capture toward software-enabled monitoring subscriptions.
REACH authorization requirements for hexavalent chromium under Annex XIV are forcing reformulation commitments across European aerospace and automotive surface treatment supply chains. The ECHA sunset date enforcement is accelerating zirconium and trivalent chromium alternative qualification programs at metal finishing operations serving German OEM specification holders. Suppliers without pre-positioned chromium-free portfolios face exclusion from 2026-2027 supply contract tenders as Wolfsburg and Stuttgart production corridors complete process requalification.
Buyer concentration around integrated coating-to-pre-treatment system vendors is compressing standalone chemical supplier access to specification-setting accounts. Automotive OEM procurement teams are consolidating approved vendor lists toward suppliers offering combined primer, pre-treatment, and technical service packages, marginalizing pure-play pre-treatment formulators. This preference consolidation is most visible in North American and European automotive assembly operations where paint shop process ownership sits with global coating suppliers rather than captive chemical management teams.
Coating Pre-Treatment Market Segmentation
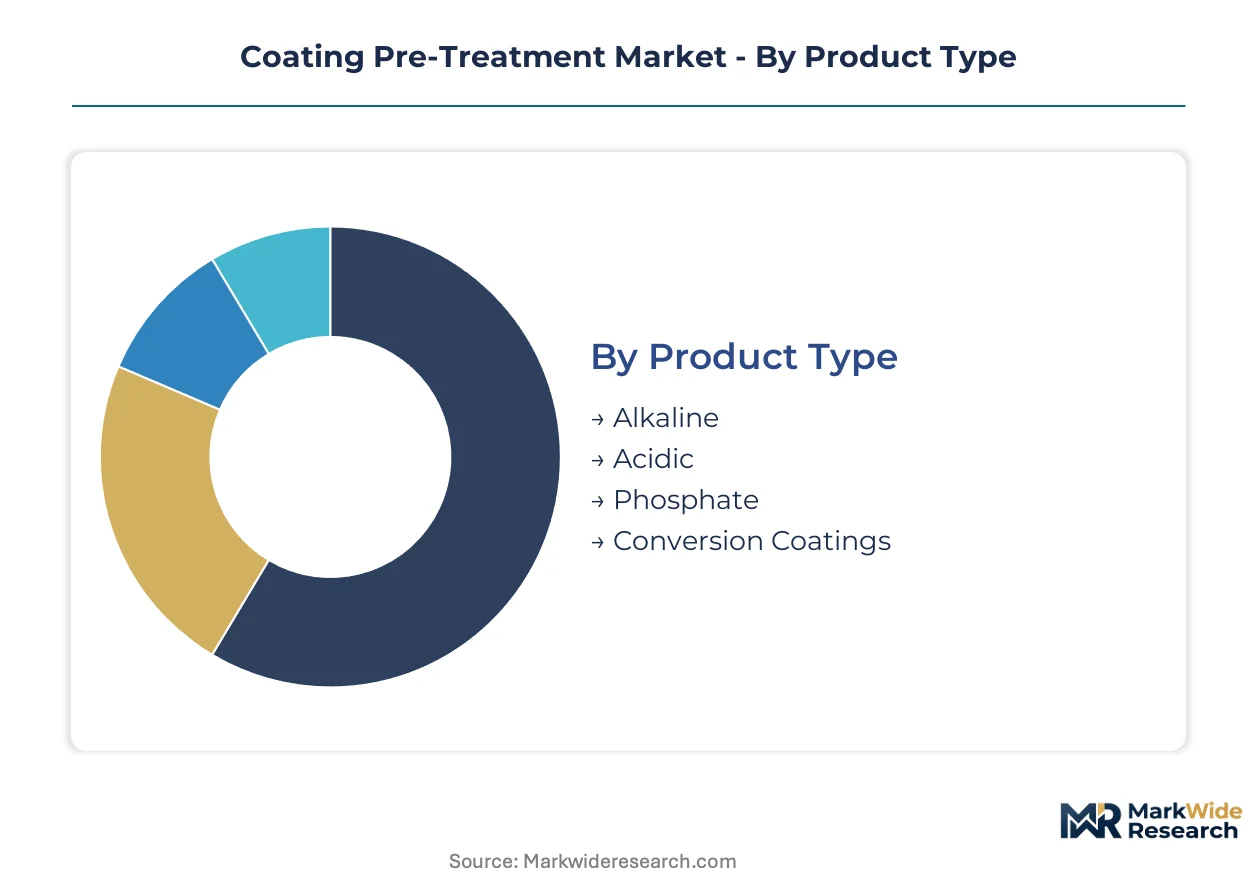
Pre-treatment chemical suppliers configure product portfolios around substrate compatibility and regulatory constraints rather than universal application. Segment boundaries blur where automotive OEMs demand phosphate systems for steel body panels while specifying zirconium conversion coatings for aluminum closure panels within identical paint shops.
Product Type:
Mature phosphate formulations dominate installed capacity, yet emerging zirconium and silane chemistries are capturing specification trials at European automotive assembly plants.
- Phosphate:Zinc and iron phosphate microcrystalline layers provide established corrosion resistance on automotive steel substrates. German OEMs around Wolfsburg and Stuttgart mandate phosphate pre-treatment for structural body-in-white assemblies, though REACH-driven hexavalent chromium restrictions are forcing manganese phosphate substitution in some aerospace fastener applications.
- Conversion Coatings:Zirconium-based thin-film systems deposit at ambient temperature with near-zero sludge generation, aligning with METI energy efficiency targets in Japan. Henkel's Chemetall division anchors European supply for chromate-free aerospace conversion coatings as ECHA sunset dates approach.
- Alkaline:Caustic-based cleaners remove mill oils and forming lubricants from precision metal housings serving electronics manufacturers.
- Acidic:Pickling and etching formulations activate aluminum and magnesium alloy surfaces prior to anodizing or coating deposition.
Phosphate retains volume leadership; conversion coatings hold the steepest expansion curve.
Application:
Customer concentration varies sharply across end-use sectors, with automotive OEM procurement teams wielding specification authority that chemical suppliers cannot circumvent.
- Automotive OEMs:Paint shop process ownership sits with global coating suppliers who bundle pre-treatment chemicals with primer and clearcoat systems. Chinese domestic OEMs are expanding captive phosphate capacity to serve heavy equipment and passenger vehicle assembly programs under tightening MEE discharge enforcement.
- Aerospace:Chromate-free conversion coating qualification lags at independent MRO facilities compared to OEM captive shops, creating channel development opportunity. FAA and EASA airworthiness directives govern pre-treatment process documentation for structural adhesive bonding.
- Electronics:Precision metal housing manufacturers favor low-temperature silane-based systems that protect aluminum smartphone and laptop chassis without dimensional distortion.
- Heavy Equipment:Agricultural and construction machinery frames demand phosphate corrosion protection for extended outdoor service life in abrasive environments.
Automotive OEMs command the largest chemical volume; aerospace MRO channels show the most rapid specification opening.
End User:
Procurement sophistication diverges between captive manufacturing operations and independent job shops that lack internal chemical engineering resources.
- Original Equipment Manufacturers:Automotive and aerospace OEMs specify pre-treatment chemistry through approved vendor lists that marginalize standalone chemical formulators. Integrated coating-to-pre-treatment system vendors capture margin through technical service bundling.
- Service Providers:Independent metal finishing job shops process components for multiple industrial customers, requiring formulation flexibility that conflicts with process standardization.
- Manufacturers:Heavy equipment builders with captive surface treatment lines balance chemical cost against wastewater handling infrastructure investment.
- Research Institutions:National laboratories and university materials science departments pilot next-generation conversion coating chemistries ahead of commercial qualification.
Original equipment manufacturers concentrate specification authority; service providers face the most acute reformulation cost pressure.
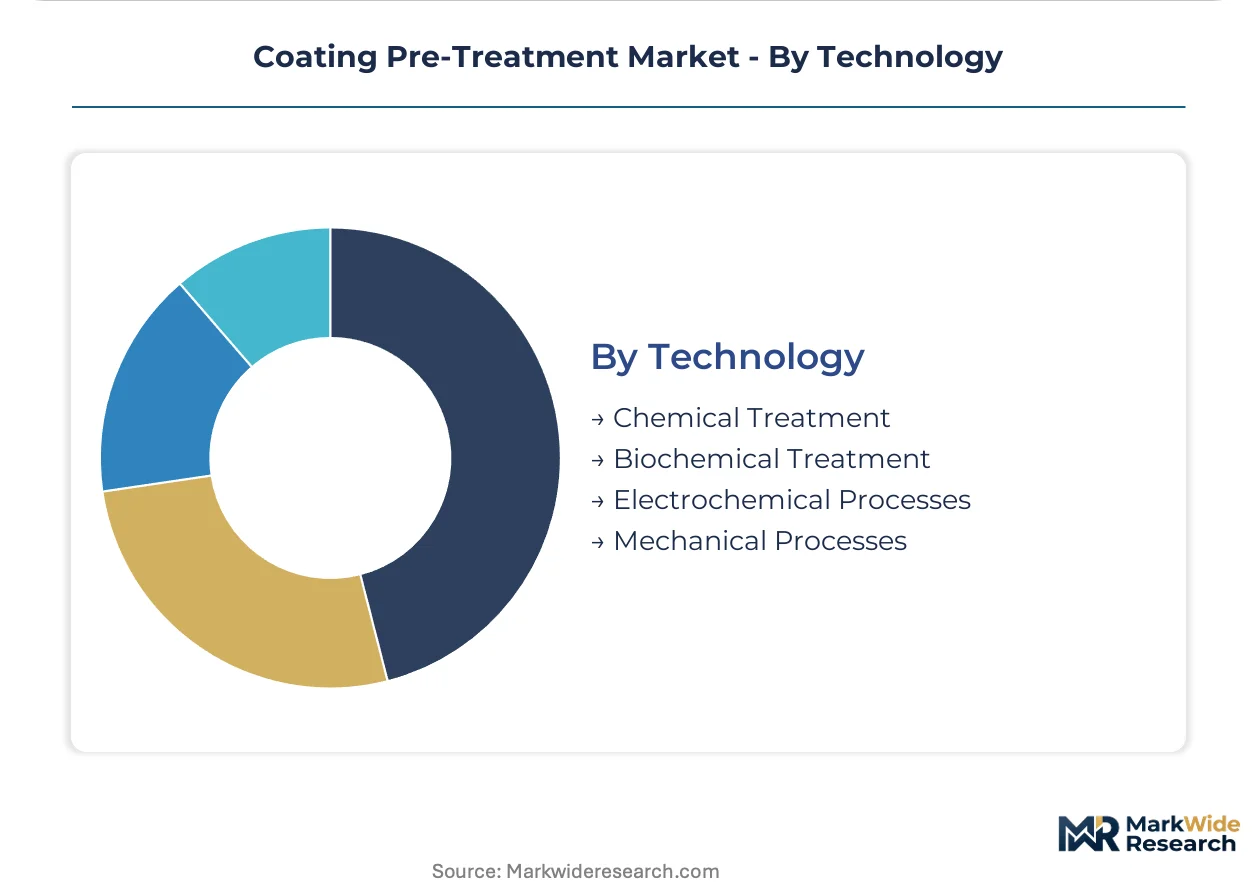
Technology:
Process selection hinges on capital availability, wastewater discharge limits, and film weight precision requirements rather than chemical performance alone.
- Chemical Treatment:Immersion and spray application of formulated pre-treatment solutions dominates installed base due to process familiarity and lower capital threshold. EPA effluent guideline enforcement in the United States favors chemical treatment lines with closed-loop rinse water recycling.
- Electrochemical Processes:Anodizing and plasma electrolytic oxidation deliver precise film weight control on aluminum aerospace components with reduced chemical consumption. Electrochemical line operation demands metallurgical expertise that metal finishing operations struggle to recruit.
- Biochemical Treatment:Enzymatic degreasing formulations reduce caustic chemical handling at precision metal cleaning operations.
- Mechanical Processes:Grit blasting and abrasive cleaning prepare heavy steel weldments where chemical residue would interfere with subsequent coating adhesion.
Chemical treatment maintains installed base dominance; electrochemical processes are climbing the fastest on specification value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH enforcement anchors European pre-treatment reformulation, while divergent regulatory timelines across major automotive manufacturing bases create uneven adoption curves for chromium-free conversion systems.
United States
EPA effluent guideline enforcement tightens wastewater discharge limits at metal finishing operations serving automotive and aerospace supply chains. The agency's updated pretreatment standards for electroplating and metal finishing categories favor electrochemical processes with reduced sludge generation. Michigan and Ohio surface treatment corridors around Detroit and Cleveland face capital investment pressure for closed-loop rinse water recycling infrastructure.
Germany
Wolfsburg and Stuttgart automotive production corridors mandate phosphate and zirconium conversion coatings for new vehicle assembly programs, pulling demand from captive surface treatment facilities. REACH Annex XIV sunset dates for hexavalent chromium force 18-24 month requalification timelines at metal finishing operations serving KBA-certified automotive suppliers. Bavarian and Baden-Württemberg paint shops compress supplier selection windows ahead of 2026 contract renewals.
China
Domestic automotive OEMs and heavy equipment builders expand phosphate capacity to serve assembly programs under tightening MEE environmental enforcement. GB standards alignment on heavy metal discharge limits from surface treatment facilities accelerates captive pre-treatment line investment. Yangtze River Delta manufacturing clusters around Shanghai upgrade wastewater handling infrastructure to meet provincial discharge permits.
Japan
METI energy efficiency directives drive process temperature reduction targets that favor low-temperature zirconium and silane-based conversion systems. Automotive paint shops in Aichi Prefecture's Chubu manufacturing corridor retrofit heated zinc phosphate lines to ambient zirconium processes. Kanto region surface treatment facilities pilot silane-zirconium hybrid chemistries to reduce natural gas consumption.
Coating Pre-Treatment Market Competitive Environment
Capability concentration sits with specialty chemical formulators possessing aerospace qualification heritage; scale advantage sits with integrated coating suppliers controlling automotive OEM specification-setting. The market structures around three tiers: global diversified chemical conglomerates with surface treatment divisions, standalone pre-treatment specialists with captive technical service networks, and regional job shop chemical distributors lacking formulation depth. Dominant competitive moves include backward integration into phosphate raw material sourcing and technology licensing partnerships that transfer process expertise without capital-intensive manufacturing commitments.
Within the integrated coating-to-pre-treatment tier, PPG Industries and Axalta Coating Systems occupy positions that bundle specification authority across primer, pre-treatment, and clearcoat systems. Among European specialty chemical formulators, Henkel AG & Co. KGaA exemplifies capability concentration through its Chemetall surface treatment division, while Nihon Parkerizing represents the Japanese automotive pre-treatment archetype with phosphate process specialization. These three companies anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| PPG Industries |
| 3M |
| Henkel AG & Co. KGaA |
| Nippon Paint |
| Axalta Coating Systems |
| The Sherwin-Williams Company |
| Chemetall GmbH |
| Nihon Parkerizing |
| Akzo Nobel N.V. |
| Others |
Value Chain & Pricing Dynamics
Wolfsburg and Stuttgart automotive production corridors concentrate European phosphate and zirconium conversion coating demand, anchoring specification-setting power among German OEM procurement teams that compress supplier margins through integrated coating-to-pre-treatment bundling. This geographic buyer concentration shapes pricing power downstream, as captive paint shop process ownership shifts margin capture toward global coating suppliers with technical service scale.
Pricing Analysis
Contract-based long-term offtake dominates European automotive pre-treatment procurement, with pricing stratifying across premium, standard, and economy tiers based on REACH compliance certification and technical service bundling. Price differentiation rests on formulation qualification heritage and wastewater handling support, with mid-cap job shops showing acute price sensitivity against OEM captive operations. Cost compression in standard-grade phosphate systems is intensifying because Chinese domestic capacity expansion feeds raw material oversupply into global trade flows.
Supply Chain Analysis
Tariff exposure between China and European Union member states dominates supply chain risk planning for phosphoric acid and phosphate rock derivatives that feed pre-treatment chemical formulation. Raw material supply concentrates in Chinese phosphate rock processing and Moroccan mining operations, with formulated chemistry production anchored in Germany, Japan, and the United States. Distribution runs through regional technical service networks that co-locate inventory with automotive paint shop clusters, creating single-source vulnerability where Chemetall and Nihon Parkerizing operate captive blending facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive OEM procurement consolidation toward integrated coating-to-pre-treatment system vendors has shifted buyer power decisively, marginalizing standalone chemical formulators from specification-setting accounts. This concentration demands differentiated defensive positioning from incumbents and targeted white-space entry from challengers.
For Market Incumbents: Build regulatory qualification moats by accelerating ECHA-compliant chromium-free portfolio completion ahead of Annex XIV sunset enforcement. Backward integration into phosphate raw material sourcing secures input cost stability against Moroccan and Chinese supply volatility. Technical service digitalization, through inline spectroscopic monitoring subscriptions, defends margin position against pure-play formulators lacking process virtualization capabilities. For New Entrants and Emerging Players: Build out aerospace MRO channel presence in European and Middle Eastern aviation clusters where chromate-free conversion coating qualification lags OEM captive shops. Target Indian automotive paint shop expansion around Chennai and Pune assembly corridors, where PLI scheme incentives attract domestic vehicle manufacturing without entrenched supplier relationships. Lead with low-temperature zirconium-silane hybrid systems that reduce natural gas consumption and align with METI energy efficiency directives in Japan. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because REACH and EPA effluent enforcement will sustain reformulation demand across successive specification cycles. Acquisition targets should surface among European specialty chemical formulators with aerospace qualification heritage and stranded hexavalent chromium portfolios requiring transition capital. The signal to watch is ECHA authorization timeline acceleration for trivalent chromium and zirconium alternatives, which would compress qualification windows and favor pre-positioned suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Sourcing | Captive supply of phosphoric acid from Moroccan rock processing insulates margin from Chinese export volatility. |
| Chromate-Free Formulation Launch | ECHA REACH Annex XIV compliance opens 2026-2027 German automotive contract tender participation. |
| Digital Twin Deployment | Virtualized bath chemistry monitoring shifts margin capture from on-site chemist deployment to software subscriptions. |
| Aerospace MRO Channel Partnership | FAA and EASA airworthiness directive documentation capabilities penetrate independent maintenance facilities. |
| Low-Temperature Process Line Retrofit | Ambient zirconium systems reduce natural gas consumption and align with Japan METI energy efficiency targets. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with pre-treatment chemical plant managers, automotive OEM procurement leads, aerospace MRO technical directors, and metal finishing job shop operators; and secondary validation through customs and trade data, SEC 10-K filings, ECHA REACH authorization databases, and ACC industry reports. Bottom-up triangulation across formulation volume estimates and top-down reconciliation against automotive production and aerospace MRO activity indices anchored market sizing.
Forecast inputs spanned product type segmentation across phosphate, conversion coating, alkaline, and acidic chemistries; application dimensions covering automotive OEM, aerospace, electronics, and heavy equipment end-uses; and technology distinctions between chemical treatment, electrochemical processes, and emerging biochemical alternatives. CAGRs were derived through regression analysis of historical specification adoption curves and regulatory enforcement timelines, with automotive OEM program launches and ECHA sunset dates as primary demand inflection inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic suppliers or accelerated EPA effluent guideline enforcement would shift outcomes beyond modeled parameters. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Polyvinylidene Fluoride (PVDF) Coatings Market
Coatings
Tablet and Pellet Coating Systems Market
Coatings
Global Heat Resistant Coatings Market
Coatings
Global Waterborne Coatings Market
Coatings
BRIC Performance Coatings Market
Coatings
Mexico Floor Coatings Market
Coatings
Stain Resistant Coatings Market
Coatings
US Industrial Coatings Market
Coatings
Global Sputter Coatings Market
Coatings
Polyurethane (PU) Coatings Market
Coatings
OEM Coatings Market
Coatings
Italy Protective Coatings Market
Coatings
Bio-Based Coatings Market
Coatings
Fillers and Coating Market
Coatings
Intumescent Fire Retardant Coating Market
Coatings
South Korea Protective Coatings Market