
 Global Polyurea Coating Market | 2026-2036
Global Polyurea Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyurea Coating Market Foresight
Hybrid polyurea formulations incorporating polyaspartic esters is reshaping application windows and cure profiles across commercial flooring and waterproofing jobs. PPG Industries leverages its global distribution network to supply certified systems to marine operators and infrastructure developers. Huntsman International anchors its position through backward integration into MDI and amine chemistry, sustaining raw material security for high-performance grades. BASF SE competes on formulation breadth, spanning aromatic through aliphatic polyurea lines for secondary containment and protective maintenance.
Polyurea coating denotes a two-component elastomer formed by reaction of an isocyanate component with a resin blend of amine-terminated polyethers, achieving gel times under ten seconds and tensile strengths exceeding 2,500 psi for severe-service environments. Its primary industrial purpose centers on rapid-cure waterproofing, corrosion protection, and abrasion-resistant surfacing where downtime minimization commands premium value. Pure polyurea dominates specification-driven segments demanding zero VOC compliance and instantaneous return-to-service, while polyaspartic variants capture fastest growth in decorative flooring where extended pot life enables roller or brush application by smaller contractor crews. Spray coating remains the primary deployment method for large-area infrastructure, though roll coating gains traction in maintenance budgets where equipment mobilization costs outweigh speed requirements.
EPA oversight of methylene diphenyl diisocyanate emissions shapes product formulation and applicator certification requirements across US commercial and industrial projects. REACH registration obligations in Europe constrain raw material sourcing for non-compliant suppliers, elevating documentation burdens for construction contractors bidding cross-border work. ISO 12944 corrosion protection standards and NORSOK M-501 offshore specifications govern qualification for marine and oilfield services procurement. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs that erode project margins on international contracts.
Market Dynamics
EU REACH enforcement on isocyanate handling is forcing contractors toward certified applicator networks and reformulated low-emission systems, compressing the viable supplier base while elevating compliance costs across European infrastructure tenders.
Growth Catalysts
- Smart City Infrastructure Mandates:Government-funded metro rail and sewage treatment specifications in India are locking polyurea into waterproofing contracts for underground structures and containment systems.
- REACH-Driven Formulation Upgrades:ECHA registration obligations are accelerating contractor migration from solvent-based alternatives toward zero-VOC polyurea systems in bridge and tunnel rehabilitation.
- Polyaspartic Ester Chemistry:Extended pot life variants are enabling roller and brush application by smaller flooring crews, expanding addressable contractor capacity in commercial refurbishment.
Market Restraints
- MDI Feedstock Concentration:Backward-integrated MDI producers in China and Germany control critical aromatic isocyanate supply, exposing formulators to input cost volatility and allocation risk.
- Equipment Capital Intensity:High-pressure plural-component spray rigs and heated hose systems require substantial capital outlay, restricting market entry for regional applicators.
- Epoxy Substitution in Budget Segments:Lower-cost epoxy coatings continue capturing maintenance budgets where cure speed carries less premium value than material cost minimization.
Strategic Opportunities
- Offshore Wind Foundations:NORSOK M-501 qualified polyurea systems for monopile splash zone protection represent underpenetrated demand as North Sea capacity expands.
- Secondary Containment Retrofit:EPA spill prevention mandates for chemical storage facilities are generating refurbishment cycles at petroleum terminals and agricultural cooperatives.
- Direct-to-Contractor Digital Channels:E-commerce platforms supplying certified small-batch kits are bypassing traditional distributor markups for maintenance-scale projects.
Industry Challenges
- Certified Applicator Shortage:Factory-trained spray technicians meeting manufacturer warranty requirements remain scarce relative to project pipeline expansion in Southeast Asia.
- Cross-Border Documentation Burden:REACH registration gaps between EU member states and non-compliant raw material sources are delaying contractor qualification for international infrastructure bids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyurea Coating Market |
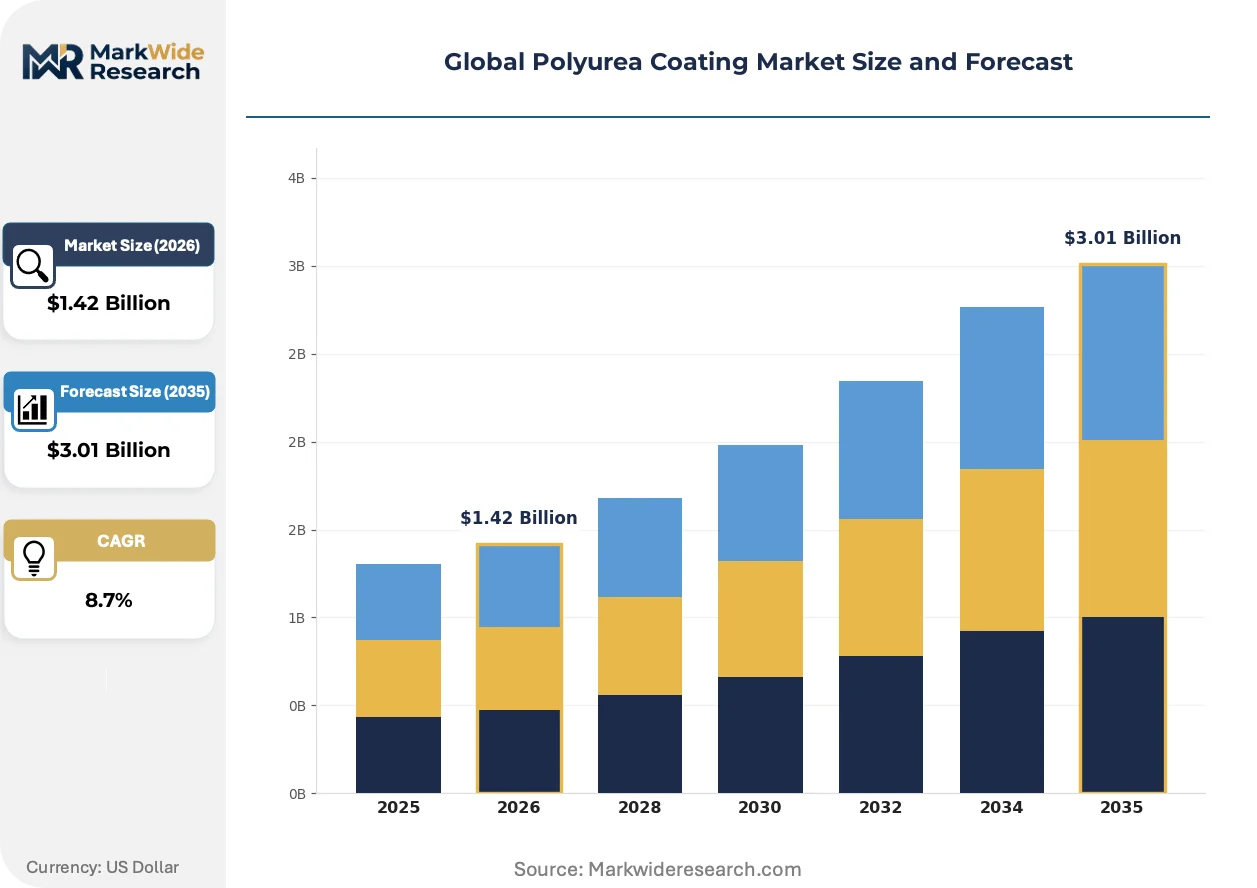
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Polyurea, Aromatic Polyurea, Aliphatic Polyurea, Polyaspartic Application: Waterproofing, Secondary Containment, Wall Coating, Flooring Systems, Protective Maintenances End User Industry: Construction Contractors, Marine Operators, Oilfield Services, Government Entities, Infrastructure Developers Deployment Method: Spray Coating, Brush Coating, Roll Coating, Dip Coating |
| Companies Covered | PPG Industries, Inc., The Sherwin-Williams Company, Huntsman International LLC, BASF SE, Sika AG, Rhino Linings Corporation, Armorthane, Covestro AG, VersaFlex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyurea Coating Market Shifts & Advancements
Formulation chemistry and application methodology are converging to compress project timelines while expanding the addressable contractor base beyond specialized spray operators.
Polyaspartic aliphatic polyurea is hybridizing aromatic backbone structures to deliver UV-stable topcoats with roller-applicable viscosity profiles. Commercial flooring contractors in retail and healthcare sectors are adopting these systems for occupied-space renovations. The technology is hybridizing equipment requirements, reducing reliance on high-pressure spray rigs and enabling smaller crews to capture maintenance-scale jobs.
EPA oversight of methylene diphenyl diisocyanate emissions is tightening permissible exposure limits and mandating enhanced respiratory protection protocols. Industrial facilities in the US Gulf Coast chemical corridor are retrofitting ventilation systems and reformulating toward pre-polymer isocyanates. Aromatic polyurea grades for secondary containment face the steepest compliance cost escalation, pushing specification toward aliphatic alternatives where color stability justifies premium positioning.
Asset owner purchasing departments are consolidating coating procurement under multi-year framework agreements with certified applicator networks. Large infrastructure developers in India and Indonesia are displacing spot-market spot buying with performance-guaranteed maintenance contracts. This concentration is most visible in bridge authority programs where warranty-backed application bundles now dominate tender specifications over material-only supply.
Global Polyurea Coating Market Segmentation
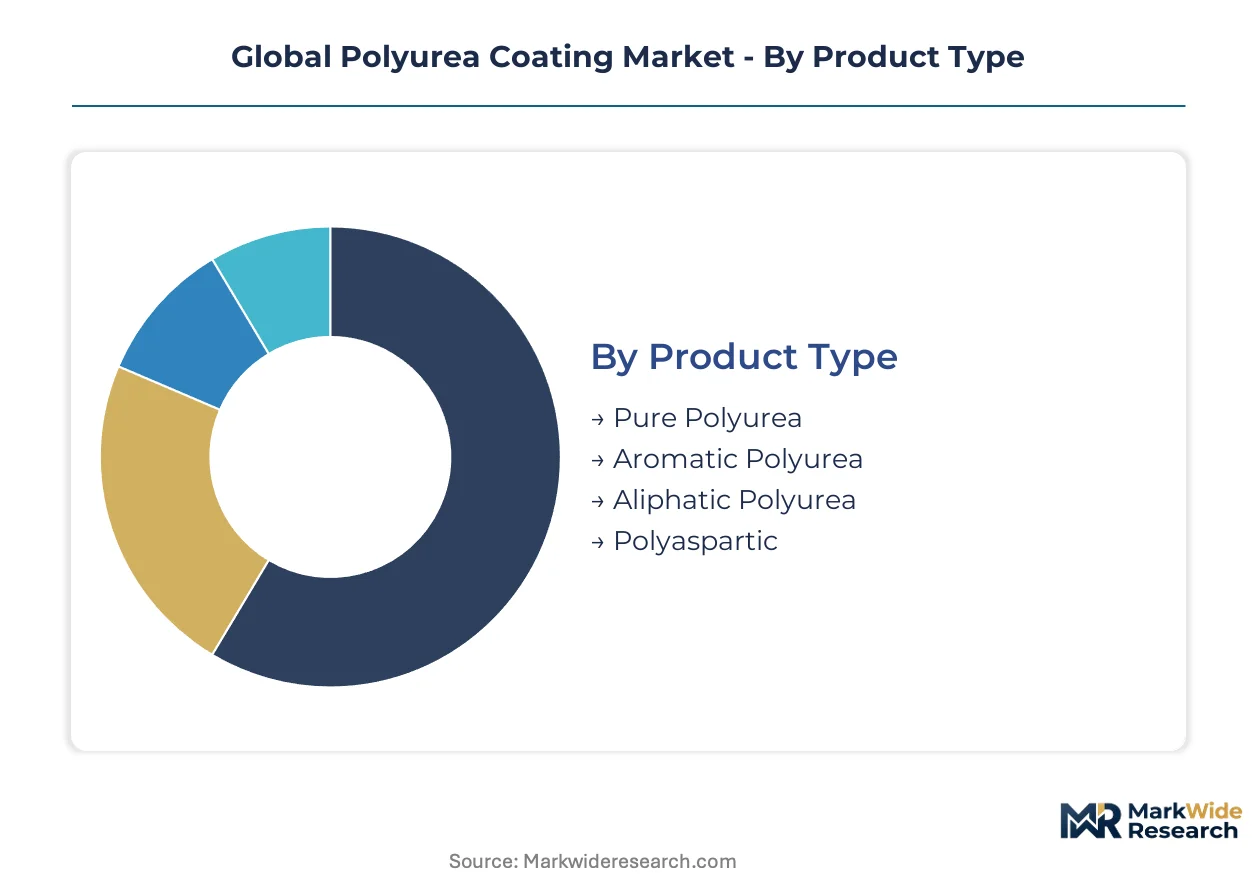
Polyurea coating segmentation reflects divergent technical specifications and procurement patterns across infrastructure verticals. Specification engineers select formulations based on cure speed, UV stability, and applicator certification requirements rather than material cost alone. Each dimension carries distinct margin structures and regulatory exposure profiles.
Product Type:
Cost tier stratification separates specification-grade systems from maintenance-grade alternatives, with raw material chemistry determining both performance ceiling and compliance burden.
- Pure Polyurea:Zero-VOC systems formulated with amine-terminated polyethers and isocyanate pre-polymers achieve sub-ten-second gel times. Demand concentrates in US Gulf Coast chemical facilities where EPA methylene diphenyl diisocyanate exposure limits mandate instantaneous cure to minimize worker contact duration.
- Polyaspartic:Aliphatic ester-modified variants extend pot life to 30-120 minutes, enabling roller application by smaller contractor crews. Flooring refurbishment in German retail and healthcare sectors is absorbing volume as REACH registration elevates solvent-based coating costs.
- Aromatic Polyurea:MDI-based formulations deliver high tensile strength for secondary containment and bridge decks where color stability is secondary to chemical resistance.
- Aliphatic Polyurea:UV-stable topcoats command premium positioning for exterior architectural applications and marine superstructures requiring long-term gloss retention.
Pure polyurea holds installed capacity. Polyaspartic is rotating up the share rankings.
Application:
Application focus determines equipment requirements and project scale, with infrastructure waterproofing commanding the longest warranty terms and most stringent applicator certification.
- Waterproofing:Bridge deck and tunnel membrane systems specify 2-3mm build thickness with elastomeric elongation exceeding 300%. Indian metro rail authorities in Mumbai and Delhi are embedding polyurea into underground station contracts as mandatory waterproofing layers.
- Secondary Containment:EPA spill prevention regulations for petroleum terminals and agricultural chemical storage mandate impermeable barrier systems. Refurbishment cycles at US Midwest ethanol facilities and Brazilian fuel terminals are sustaining demand.
- Flooring Systems:Decorative and industrial floor coatings prioritize abrasion resistance and rapid return-to-service in manufacturing environments.
- Protective Maintenances:Spot repair and recoating of existing assets reduces capital expenditure versus full replacement.
- Wall Coating:Vertical surface application requires modified rheology to prevent sag on structural concrete and masonry substrates.
Waterproofing captures the steepest expansion trajectory. Secondary containment is climbing the fastest among industrial end-uses.
End User Industry:
Customer type governs procurement modality, with government entities favoring multi-year framework agreements and marine operators prioritizing offshore qualification certifications.
- Infrastructure Developers:Southeast Asian bridge and tunnel contractors in Indonesia, Vietnam, and the Philippines are expanding waterproofing contract scopes. Factory-trained applicator scarcity relative to project pipeline expansion is compressing viable bidder pools.
- Construction Contractors:Commercial flooring specialists in US retail and healthcare renovation segments are adopting polyaspartic systems to compress project timelines and minimize tenant disruption.
- Government Entities:Indian smart city mandates specify polyurea for sewage treatment plants and metro infrastructure, locking formulations into public procurement frameworks.
- Marine Operators:NORSOK M-501 qualified systems for offshore platform splash zone protection require specialized applicator certification and documentation.
- Oilfield Services:Secondary containment and pipeline coating demand correlates with North American shale infrastructure maintenance cycles.
Infrastructure developers hold installed capacity. Government entities are rotating up the share rankings.
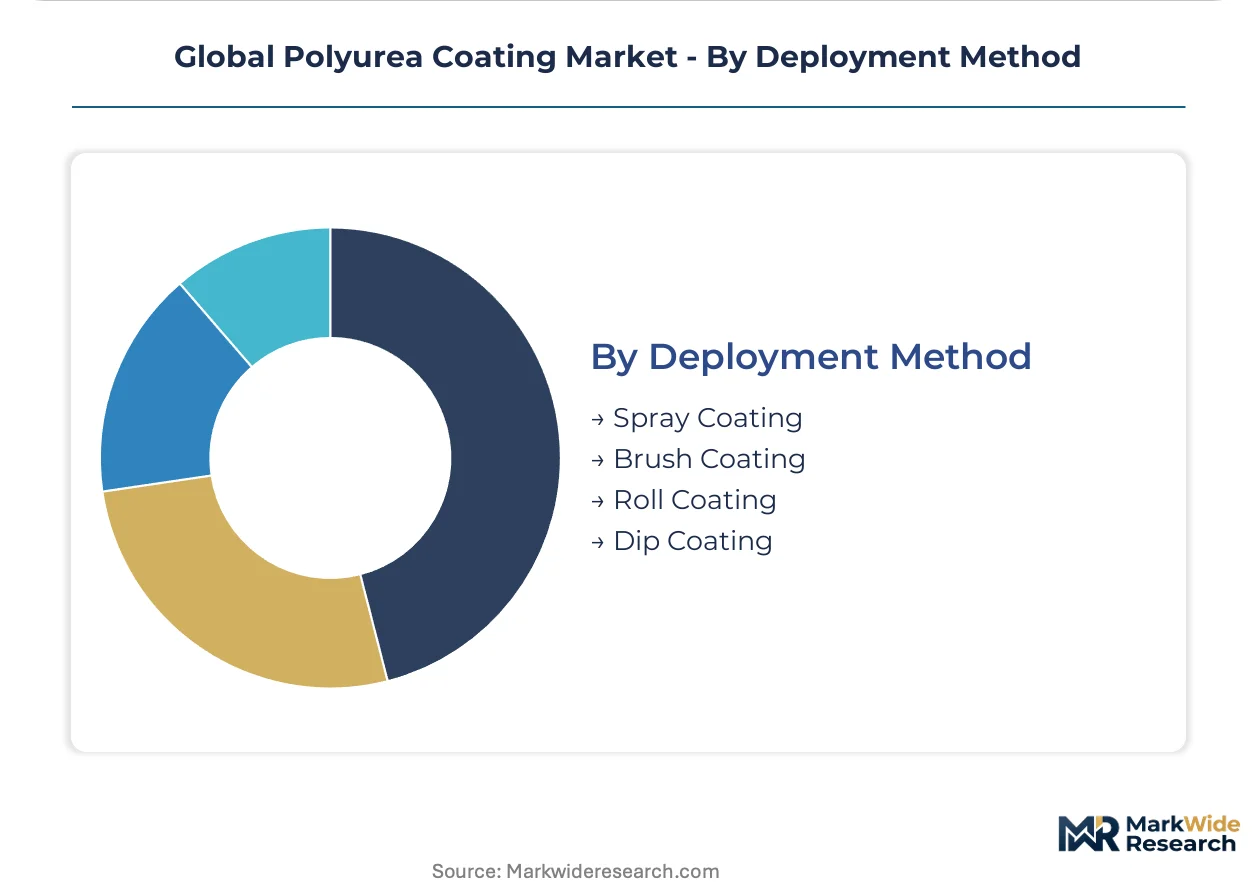
Deployment Method:
Volume considerations separate large-area infrastructure projects from maintenance-scale refurbishment, with equipment capital intensity creating distinct contractor entry barriers.
- Spray Coating:High-pressure plural-component rigs deliver 10-15 kg per minute throughput for bridge decks and tank farms. Equipment mobilization costs dominate project economics for large-footprint applications.
- Roll Coating:Reduced equipment capital enables smaller contractors to capture maintenance budgets where speed requirements are secondary to cost minimization.
- Brush Coating:Detail work and touch-up applications in confined spaces where spray overspray is prohibitive.
- Dip Coating:Small component batch processing for manufactured parts and prefabricated structural elements.
Spray coating holds installed capacity. Roll coating is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German formulators export REACH-certified polyurea systems to infrastructure contractors across Southeast Asia, with shipment volumes tracking metro rail and bridge rehabilitation contracts in Vietnam and Indonesia.
United States
EPA methylene diphenyl diisocyanate exposure limits are tightening permissible worker contact thresholds across Gulf Coast chemical facilities. Industrial coating applicators in Texas and Louisiana are retrofitting ventilation infrastructure and migrating toward pre-polymer isocyanate formulations. Secondary containment refurbishment cycles at Midwest ethanol terminals sustain demand for aromatic grades.
Germany
ECHA registration obligations are accelerating contractor migration from solvent-based alternatives toward zero-VOC polyurea systems in bridge and tunnel rehabilitation. REACH enforcement compresses the viable supplier base while elevating compliance costs across European infrastructure tenders. The Rhine-Ruhr industrial corridor hosts formulation facilities supplying certified systems to marine operators.
India
Government-funded smart city mandates specify polyurea for sewage treatment plants and metro rail infrastructure in Mumbai and Delhi. BIS certification requirements are locking formulations into public procurement frameworks for underground station waterproofing. Factory-trained applicator scarcity relative to project pipeline expansion compresses viable bidder pools.
Vietnam
Infrastructure developers are expanding waterproofing contract scopes for bridges and tunnels across the Mekong Delta transport corridor. The country's national chemical regulator is elevating documentation burdens for imported coating systems. Ho Chi Minh City contractors are absorbing certified spray technicians from regional training networks.
Brazil
ANVISA oversight of industrial chemical handling is shaping applicator certification requirements at petroleum terminals and agricultural cooperatives. Refurbishment cycles at fuel terminals in São Paulo state sustain secondary containment demand. The Southeast industrial cluster concentrates formulation distribution for South American offshore maintenance contracts.
Global Polyurea Coating Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct procurement modalities. The vendor base organizes around three tiers: backward-integrated chemical conglomerates with captive MDI supply, formulation specialists with certified applicator networks, and regional distributors capturing maintenance-scale projects. Consolidation pressure concentrates among European REACH-compliant suppliers while fragmentation persists in emerging market service layers. Dominant competitive moves include strategic partnerships with infrastructure developers and portfolio diversification into polyaspartic ester hybrids.
Within the chemical conglomerate tier, Huntsman International LLC and BASF SE exemplify backward-integrated positioning through in-house production of aromatic isocyanates and amine chemistry. Among formulation specialists, PPG Industries, Inc. occupies a channel-control position leveraging global distribution infrastructure. These three companies represent divergent strategic archetypes: raw material security, formulation breadth, and distribution reach.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Huntsman International LLC |
| BASF SE |
| Sika AG |
| Rhino Linings Corporation |
| Armorthane |
| Covestro AG |
| VersaFlex Incorporated |
| Others |
Supply & Pricing Matrix
The Rhine-Ruhr industrial corridor anchors European polyurea formulation capacity, with captive MDI production at BASF Ludwigshafen and Covestro Leverkusen facilities translating into downstream pricing leverage over REACH-compliant systems exported to Southeast Asian infrastructure tenders.
Pricing Analysis
Pure polyurea commands substantial premiums over polyaspartic and aromatic grades due to instantaneous cure requirements and zero-VOC compliance burdens. Three-tier pricing structure across specification-grade, certified-application, and maintenance-economy levels separates EPA-compliant systems for Gulf Coast chemical facilities from budget-tier alternatives facing epoxy substitution. Cost compression in aromatic grades is intensifying because MDI feedstock volatility from Chinese and German producers transmits directly into formulation costs. Budget-conscious maintenance contractors in Brazilian fuel terminals exhibit highest price sensitivity, while Indian government entities lock in multi-year framework agreements with lowest sensitivity.
Supply Chain Analysis
Export-control restrictions on dual-use chemical processing equipment limit technology transfer to non-compliant jurisdictions, constraining indigenous formulation capacity in emerging markets. Supply concentrates in Germany, China, and the United States, with backward-integrated producers controlling aromatic isocyanate feedstock. Raw material dependencies center on MDI, amine-terminated polyethers, and aliphatic pre-polymers sourced from petrochemical complexes. Single-source vulnerability around Chinese MDI allocation risk threatens formulator margins during supply crunches. Distribution runs through certified applicator networks rather than spot-market commodity channels, with manufacturer-direct digital platforms gaining share in small-batch maintenance segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from lower-cost epoxy systems in budget maintenance segments, requiring active defense of specification-driven premium positioning through certification investments and applicator network control.
For Market Incumbents: Harden warranty-backed application bundles against epoxy incursion by embedding factory-trained technician certification into tender specifications for Indian metro rail and Southeast Asian bridge contracts. Deepen backward integration into amine chemistry to insulate margins from MDI volatility transmitted by Chinese and German feedstock suppliers. Prioritize REACH registration maintenance to compress viable European supplier pools and elevate compliance barriers for non-integrated competitors. For New Entrants and Emerging Players: Build out polyaspartic roller-application capacity to capture commercial flooring refurbishment in German healthcare and US retail segments where extended pot life reduces equipment capital barriers. Target secondary containment retrofit cycles at US Midwest ethanol facilities and Brazilian agricultural cooperatives facing EPA and ANVISA spill prevention mandates. Pursue direct-to-contractor digital channels supplying certified small-batch kits to bypass traditional distributor markups in maintenance-scale projects. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because REACH compliance burdens and applicator certification requirements favor scaled formulation specialists with captive raw material security over fragmented regional distributors. Acquisition targets should exhibit backward integration into MDI or amine chemistry, established NORSOK M-501 or ISO 12944 qualification portfolios, and anchored positions in Indian government procurement frameworks. Monitor MDI allocation announcements from Chinese state-owned producers as inflection indicator for input cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI | Captive aromatic isocyanate supply insulates Huntsman and BASF from feedstock volatility. |
| REACH Certification Investment | ECHA registration elevates compliance costs that compress viable European supplier bases. |
| Applicator Network Expansion | Factory-trained technician scarcity in Southeast Asia compresses bidder pools for infrastructure tenders. |
| Polyaspartic Formulation Development | Extended pot life variants enable roller application by smaller crews in commercial flooring segments. |
| Direct-to-Contractor Digital Platform | E-commerce channels bypass distributor markups for small-batch maintenance-scale project supply. |
Research Methodology
Cross-validation between primary interviews with formulation R&D directors, certified applicator network managers, and infrastructure procurement officers anchors the qualitative findings, supplemented by secondary analysis of ECHA registration databases, EPA enforcement actions, and Indian BIS certification records. Bottom-up project pipeline tracking across Mumbai and Delhi metro authorities triangulates against top-down chemical trade flow analysis from German and Chinese customs disclosures.
Calibration against historical capacity buildout patterns and raw material cost transmission mechanisms shapes the analytical framework across the analysis window. Segmentation dimensions span product chemistry tier, application method, end-use industry vertical, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand projections incorporating smart city infrastructure spend trajectories and REACH enforcement intensity variations.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-owned MDI producers or accelerated epoxy formulation improvements would shift outcomes. Material shifts in EPA methylene diphenyl diisocyanate exposure limits or ECHA substance restriction amendments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Mirror Coatings Market
Coatings
Japan Marine Coatings Market
Coatings
ASEAN Automotive OEM Coatings Market
Coatings
Biopolymer Coatings Market
Coatings
Graphene Coatings Market
Coatings
Global Solar Panel Coatings Market
Coatings
Water Based Enamel Market
Coatings
Automotive Refinish Coatings Market
Coatings
France Protective Coatings Market
Coatings
Wood Preservative Coatings Market
Coatings
Polymer Modified Cementitious Coatings Market
Coatings
Vietnam Architectural Coatings Market
Coatings
China Marine Coatings Market
Coatings
Global Anti-Reflective Coatings Market
Coatings
Intumescent Fire Retardant Coating Market
Coatings
Global Fluorinated Ethylene Propylene (FEP) Coatings Market