
 Emulsion Coatings Market | 2026-2036
Emulsion Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Emulsion Coatings Market Foresight
The EU Green Deal is realigning emulsion coatings procurement across European commercial real estate, pushing asset managers toward verified low-carbon interior systems. PPG Industries leverages its architectural coatings R&D network to sustain reformulation leadership in APEO-free binders. AkzoNobel anchors European distribution through certified sustainable product lines that dominate specification channels for commercial interiors. BASF SE extends its position by controlling captive acrylic emulsion supply for third-party coatings formulators.
Emulsion coatings are aqueous dispersions of polymer particles—typically acrylic, vinyl acetate, or styrene-acrylic copolymers at 40–60% solids—that form continuous protective films upon water evaporation, with glass transition temperatures engineered between -20°C and +40°C for flexibility or hardness. Their primary commercial purpose is to provide decorative and protective finishes for building substrates with reduced solvent emissions versus alkyd alternatives. Interior applications now lead volume globally as residential refurbishment cycles compress in mature economies, while low-VOC technology captures the fastest growth trajectory as regulatory thresholds tighten across multiple jurisdictions. Water-based systems occupy the dominant share of new capacity investment, though high-solids formulations retain margin pools in industrial maintenance segments where corrosion resistance specifications are most demanding.
EPA VOC limits under 40 CFR Part 59 and REACH Annex XVII restrictions on hazardous substances shape product eligibility across North American and European markets, while China's GB standards for architectural coatings enforce comparable emission ceilings in the largest national demand center. BIS certification requirements in India and ECHA substance evaluations in Europe collectively raise compliance costs for non-specialist formulators, filtering market access toward integrated polymer-coatings producers. Stakeholders must monitor evolving biobased content mandates in public procurement rules across multiple geographies, as these specifications increasingly determine qualification for large-scale infrastructure and institutional coating contracts.
Market Dynamics
Water-based formulation chemistry is displacing solvent-borne systems as the dominant industrial standard, with regulatory emission ceilings compressing reformulation timelines and reshaping raw material procurement across architectural coatings value chains.
Growth Catalysts
- REACH Annex XVII restrictions:Hazardous substance limitations in Europe are forcing APEO elimination from interior emulsions, opening specification channels for compliant acrylic binders in commercial real estate.
- India's residential construction recovery:Urban housing stock expansion in Mumbai, Delhi, and Bangalore is accelerating uptake of water-based interior finishes for new unit completions.
- China's green building certification mandates:Tier-one city commercial developments now require low-VOC coating systems, concentrating specification demand for certified emulsion products.
Market Restraints
- Acrylic monomer supply concentration:Captive production by integrated petrochemical majors in Northeast Asia creates input cost volatility for independent formulators lacking backward integration.
- Alkyd system residual performance:Industrial maintenance segments with severe corrosion resistance specifications retain solvent-borne alkyd alternatives where water-based films fail humidity-cure requirements.
- BIS certification timelines:India's mandatory quality standards for architectural coatings extend product registration cycles, filtering market access toward established polymer-coatings producers with compliance infrastructure.
Strategic Opportunities
- Biobased content mandates:Public procurement rules across multiple geographies are increasingly specifying renewable feedstock thresholds, creating qualification barriers for petroleum-derived emulsions in infrastructure contracts.
- High-solids waterborne convergence:Hybrid formulations combining elevated solids content with aqueous dispersion technology are penetrating industrial maintenance segments previously closed to conventional emulsions.
- Tier-two China urbanization:Chengdu, Wuhan, and Xi'an commercial construction pipelines lack mature green building enforcement, creating temporary specification windows before mandate expansion.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in glass transition temperature engineering and particle size distribution control is concentrating among legacy coatings R&D centers, constraining new entrant product development velocity.
- Multi-jurisdiction compliance synchronization:Simultaneous EPA 40 CFR Part 59, REACH Annex XVII, and GB standard adherence requires parallel testing protocols, extending product launch timelines and inflating registration expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emulsion Coatings Market |
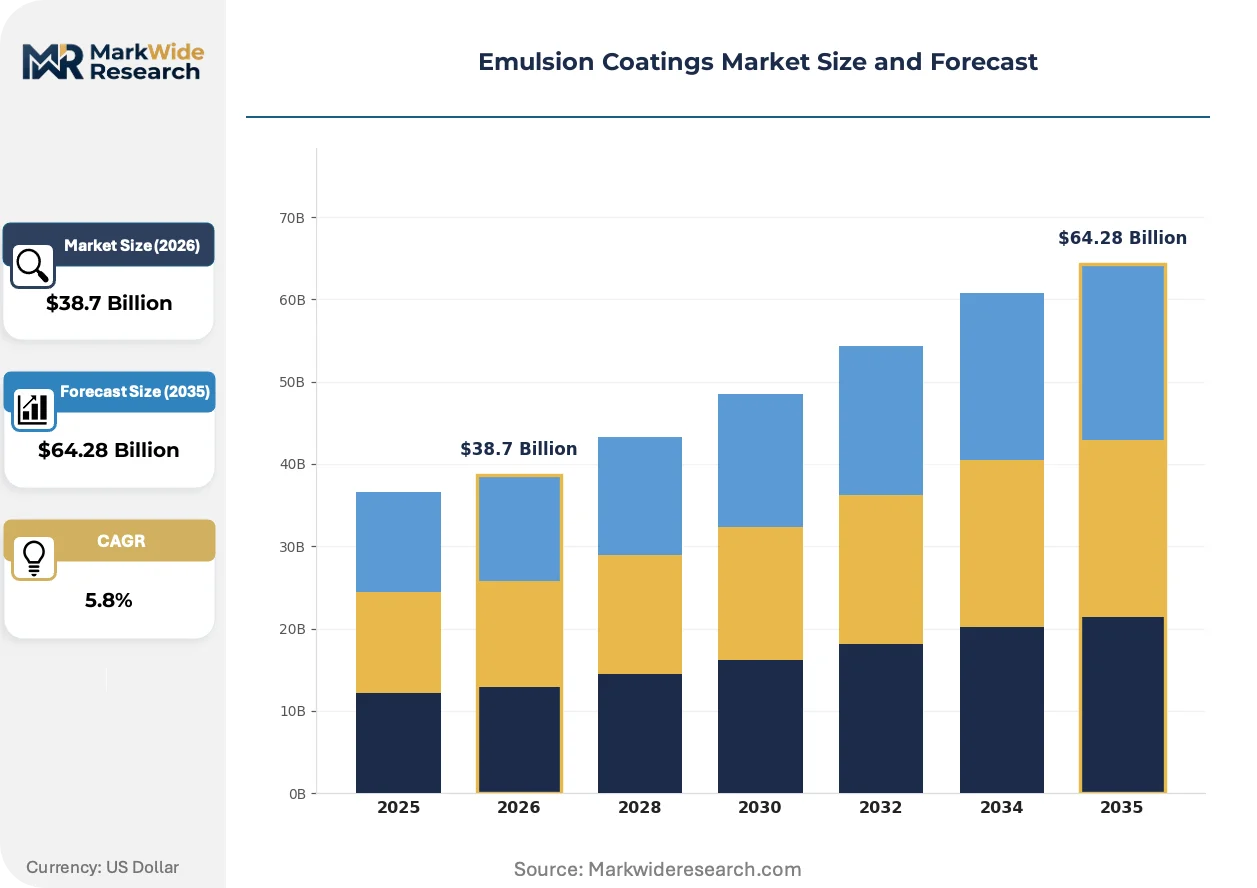
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exterior, Interior, Primers, Sealers Application: Residential, Commercial, Industrial, Automotive Technology: Water-Based, Solvent-Based, High Solids, Low VOC End User: Contractors, DIY Consumers, Manufacturers, Distributors |
| Companies Covered | The Sherwin-Williams Company, PPG Industries, Inc., AkzoNobel N.V., Nippon Paint Holdings Co., Ltd., RPM International Inc., BASF SE, Dow Inc., Arkema S.A., Kansai Paint Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emulsion Coatings Market Shifts & Advancements
Acrylic emulsion technology is fragmenting into application-specific modules as formulators abandon universal binder platforms in favor of performance-optimized particle architectures tailored to substrate and exposure conditions.
Hybrid acrylic-silane core-shell emulsion chemistry is modularizing protective coating architectures. Industrial maintenance contractors in marine and infrastructure segments are adopting these systems for combined corrosion resistance and UV durability. The technology is modularizing what were previously separate primer-topcoat sequences into single-build applications, compressing labor cost structures and site time requirements.
EPA VOC limits under 40 CFR Part 59 are tightening architectural coating emission thresholds. Manufacturers are accelerating waterborne alkyd and high-Tg acrylic development to maintain product positioning in decorative segments. California Air Resources Board supplementary restrictions are driving the most aggressive reformulation activity, with South Coast AQMD districts enforcing sub-category limits that preclude legacy styrene-acrylic systems.
Asset managers in European commercial real estate are embedding coating specifications into green lease clauses. Property technology platforms are disintermediating traditional distributor relationships by connecting specification-grade emulsion procurement directly to verified low-carbon product databases. Germany and the Netherlands exhibit the most advanced adoption, with DGNB and BREEAM-NL certification schemes mandating embodied carbon disclosure for interior finish materials.
Emulsion Coatings Market Segmentation
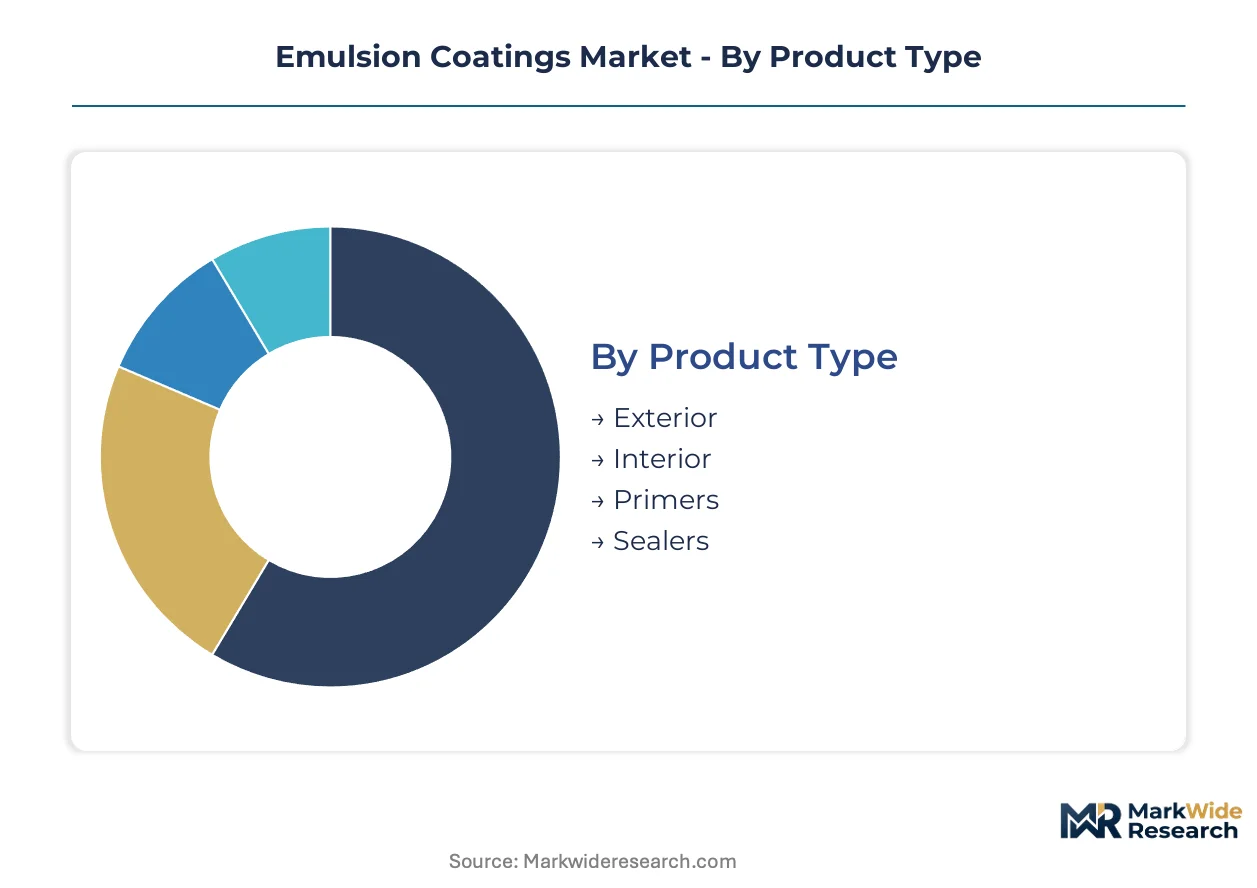
Segmentation in emulsion coatings reveals how formulation chemistry, application environment, and procurement channel each dictate distinct performance specifications and margin structures. Buyers prioritize different attributes—durability, application speed, regulatory compliance, or total applied cost—depending on their position in the value chain.
Product Type:
Professional contractors and facility managers select product types based on substrate exposure severity and recoating frequency economics.
- Interior:Water-based acrylic and vinyl acetate copolymers dominate this segment, formulated for scrub resistance and low odor during occupied-space application. Demand concentrates in India's residential construction recovery, where Mumbai and Delhi developers specify quick-dry systems to accelerate unit handover timelines.
- Exterior:Styrene-acrylic and pure acrylic binders with engineered Tg above 20°C deliver UV durability and hydrophobicity for facade protection. China's tier-one city commercial developments drive specification volume as green building certification mandates now require low-VOC exterior systems with verified weathering performance.
- Primers:Alkali-resistant formulations for concrete and gypsum substrates.
- Sealers:Penetrating acrylics for porous masonry and wood protection.
Interior leads volumes today; exterior is gaining share fastest as climate-adaptive facade specifications expand.
Application:
Application segments diverge by project scale, specification authority, and regulatory exposure severity.
- Residential:Single-family and multi-unit housing drives the largest absolute volume, with refurbishment cycles compressing in mature economies. DIY consumers and small contractors in India favor economy-grade vinyl acetate emulsions for rental property turnover, while owner-occupiers in European markets specify premium low-VOC systems.
- Commercial:Office, retail, and hospitality interiors command specification-grade products with certified emission profiles. Asset managers in Germany and the Netherlands embed coating requirements into green lease clauses tied to DGNB and BREEAM-NL certification, filtering procurement toward verified low-carbon emulsion databases.
- Industrial:Manufacturing facilities and warehouses require chemical-resistant and high-build formulations.
- Automotive:Refinish and OEM applications favor high-solids waterborne systems for color matching and durability.
Residential anchors current volume; commercial applications show the steepest expansion trajectory as green building mandates proliferate.
Technology:
Technology selection reflects regulatory ceiling stringency and performance requirements that aqueous systems must now satisfy.
- Water-Based:Acrylic and styrene-acrylic dispersions at 40-60% solids form the industrial standard, with continuous film formation upon water evaporation. REACH Annex XVII APEO restrictions and EPA 40 CFR Part 59 VOC limits are accelerating displacement of solvent alternatives in architectural segments across Europe and North America.
- Low VOC:Formulations engineered below 50 g/L VOC content capture specification premiums in certified green buildings. China's GB standards for architectural coatings enforce comparable emission ceilings, concentrating demand in tier-one city developments where mandate compliance determines project approval.
- Solvent-Based:Alkyd and polyurethane systems retain position in humidity-sensitive industrial maintenance.
- High Solids:70-85% solids content delivers build and corrosion resistance for marine and infrastructure protection.
Water-based technology commands the dominant position; low VOC formulations are climbing the fastest as regulatory thresholds tighten across multiple jurisdictions.
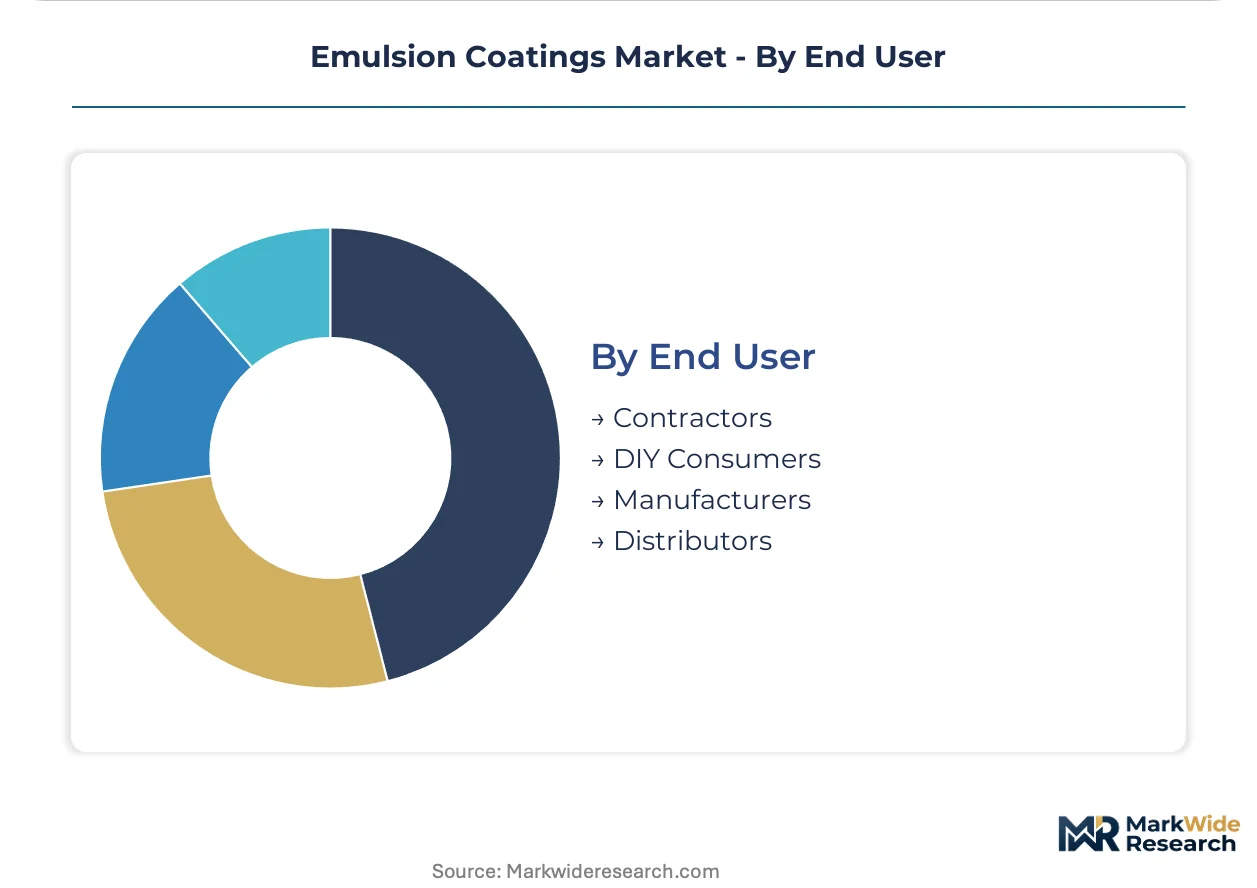
End User:
End user categories separate by technical sophistication, volume purchasing power, and specification influence.
- Contractors:Professional applicators prioritize coverage rates, touch-up compatibility, and inventory consolidation. Large painting contractors in China's commercial construction sector specify single-source emulsion systems to reduce site complexity, while European contractors respond to EU Green Deal procurement alignment by demanding verified embodied carbon data.
- DIY Consumers:Home improvement retailers and e-commerce platforms serve this price-sensitive segment. India's urban housing stock expansion in Bangalore and Chennai drives volume through organized retail channels, though product registration delays under BIS certification requirements filter access toward established polymer-coatings producers with compliance infrastructure.
- Manufacturers:Industrial OEMs and furniture producers integrate captive coating operations.
- Distributors:Merchant distributors and specification consultants intermediate between formulators and project owners.
Contractors represent the largest revenue channel; DIY consumers are expanding most quickly as residential refurbishment accelerates in emerging urban markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Emulsion coatings industrialization traces to post-war European reconstruction, where water-based acrylic systems first displaced solvent-borne alkyds for interior architectural applications. The technology subsequently diffused through German chemical engineering networks into North American and Asian manufacturing bases.
United States
Commercial real estate asset managers in California and New York now embed low-VOC coating specifications into green lease clauses. EPA 40 CFR Part 59 enforces sub-category emission limits that preclude legacy styrene-acrylic systems in South Coast AQMD districts. Dallas-Fort Worth and Houston construction corridors concentrate specification-grade procurement for multi-unit residential developments.
Germany
DGNB certification schemes mandate embodied carbon disclosure for interior finish materials across commercial property portfolios. REACH Annex XVII restrictions on APEO content filter procurement toward compliant acrylic binder systems. The Rhine-Ruhr industrial corridor hosts integrated polymer-coatings producers with captive emulsion supply chains.
China
Tier-one city commercial developments in Shanghai, Beijing, and Shenzhen now require low-VOC coating systems under GB standards for architectural coatings. MIIT dual carbon goals accelerate displacement of solvent-borne alternatives in state-backed infrastructure projects. The Yangtze River Delta concentration of petrochemical capacity supplies captive acrylic monomer to domestic formulators.
India
Urban housing stock expansion in Mumbai, Delhi, and Bangalore accelerates uptake of water-based interior finishes for new unit completions. BIS certification requirements for architectural coatings extend product registration cycles, filtering market access toward established producers. The Gujarat chemical belt anchors domestic acrylic emulsion manufacturing for third-party coatings formulators.
Netherlands
BREEAM-NL certification drives specification demand for verified low-carbon emulsion products in commercial interior applications. ECHA substance evaluations under REACH raise compliance costs for non-specialist formulators lacking polymer-coatings integration. The Rotterdam-Antwerp chemical cluster supplies specialty acrylic dispersions to northwest European coatings manufacturers.
Emulsion Coatings Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation chemistry sophistication and specification channel access. The vendor base organizes into three tiers: integrated petrochemical majors with captive acrylic supply, specialized coatings formulators with certified sustainable product lines, and regional distributors serving price-sensitive refurbishment segments. Consolidation pressure concentrates among mid-scale formulators lacking backward integration into polymer production. Dominant competitive moves include strategic partnerships for biobased feedstock sourcing and geographic expansion into tier-two China urbanization corridors.
Within the integrated petrochemical tier, BASF SE and Dow Inc. exemplify archetypes combining captive acrylic emulsion production with third-party supply relationships. Among specialized coatings formulators, AkzoNobel N.V. occupies a position representing certified sustainable product lines that dominate European specification channels. These three entities anchor competitive positioning across distinct value chain segments without overlapping strategic territory.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| PPG Industries, Inc. |
| AkzoNobel N.V. |
| Nippon Paint Holdings Co., Ltd. |
| RPM International Inc. |
| BASF SE |
| Dow Inc. |
| Arkema S.A. |
| Kansai Paint Co., Ltd. |
| Others |
Supply & Pricing Matrix
Acrylic monomer feedstock costs cascade through three distinct pricing tiers as integrated petrochemical majors in Northeast Asia leverage captive production to extract margin premiums from independent formulators lacking backward integration into polymer supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates specification-grade low-VOC systems from commodity vinyl acetate emulsions. Price differentiation hinges on certification grade—REACH Annex XVII compliance and green building database verification—and volume scale for contractor procurement. Cost compression in economy tiers is intensifying as Indian BIS registration delays filter access toward established producers with compliance infrastructure. DIY consumers in emerging urban markets exhibit highest price sensitivity; European commercial asset managers demonstrate lowest sensitivity due to green lease clause embedding.
Supply Chain Analysis
Specialized formulation chemist scarcity concentrates in legacy coatings R&D centers across Germany, the Netherlands, and the United States, constraining new entrant product development velocity. Acrylic monomer production draws from captive petrochemical complexes in China, Germany, and the United States; styrene and vinyl acetate monomer supplies feed from integrated crackers in the Yangtze River Delta and Rotterdam-Antwerp cluster. Single-source vulnerability persists for APEO-free binder technology controlled by integrated majors. Distribution runs through specification consultants and merchant distributors for commercial projects, with direct retail channels serving DIY refurbishment demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The emulsion coatings market functions as a stable compounder anchored by regulatory ratchets on VOC emissions that perpetually refresh reformulation demand across architectural and industrial segments.
For Market Incumbents: Cement specification channel control by embedding certified low-carbon product lines into European green lease procurement platforms. Prioritize backward integration into biobased acrylic monomer production to defend margin position against petroleum feedstock volatility. The threat of hybrid acrylic-silane core-shell technology displacing conventional primer-topcoat sequences demands accelerated R&D in single-build application systems. For New Entrants and Emerging Players: E-commerce platform routes into India's tier-two urban housing markets bypass established distributor relationships and BIS registration bottlenecks. Target white-space in Chengdu, Wuhan, and Xi'an commercial construction before green building mandate expansion closes specification windows. Pursue white-label supply partnerships with Gujarat chemical belt emulsion manufacturers to compress capital requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale formulators lack captive polymer production and face simultaneous REACH, EPA, and GB compliance cost inflation. Long-term viability favors integrated petrochemical-coatings producers with verified sustainable product databases and specification channel lock-in. Watch hybrid high-solids waterborne penetration rates in industrial maintenance segments as inflection indicator for technology displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biobased Monomer Supply | Secures feedstock cost stability against petroleum volatility for APEO-free binder production. |
| Green Building Database Certification | Unlocks specification channels in German DGNB and Dutch BREEAM-NL commercial real estate procurement. |
| Hybrid Core-Shell Emulsion R&D Partnership | Accelerates single-build industrial maintenance coatings that compress labor cost structures for marine contractors. |
| Tier-Two China Distribution Expansion | Captures temporary specification windows in Chengdu and Wuhan before mandate expansion closes access. |
| Digital Platform Direct Procurement | Disintermediates traditional distributors by connecting asset managers to verified low-carbon product databases. |
Research Methodology
Multiple input streams — technical R&D directors at integrated polymer producers, procurement leads at European commercial real estate asset managers, plant managers at Gujarat chemical belt facilities, and merchant distributors serving Indian retail channels — were reconciled against customs and trade data, SEC 10-K filings, Cefic industry reports, and REACH registration databases. Primary fieldwork with coatings formulators and specification consultants was cross-validated through bottom-up capacity assessments and top-down demand modeling across application segments.
Historical volume trajectories were cross-referenced against expert panel assessments of regulatory implementation timelines and green building mandate expansion patterns across the projection horizon. Segmentation dimensions modeled include product type, application environment, technology tier, and end-user procurement authority, with CAGRs derived from elasticity-adjusted demand curves and capacity utilization rates. Forecast inputs incorporated MIIT dual carbon goal enforcement intensity and BIS certification timeline projections for architectural coatings registration.
The model assumes a particular technology adoption path; alternative pathways for hybrid high-solids waterborne systems would alter the outlook if industrial maintenance contractors accelerate displacement of solvent-borne alkyds. Forecasts reflect assumptions on REACH Annex XVII enforcement consistency and tier-two China urbanization velocity. Material deviation in green building mandate expansion timelines or acrylic monomer supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Low Friction Coatings Market
Coatings
Leisure Boat Marine Coatings Market
Coatings
Global Fireproofing Coatings for Wood Market
Coatings
Asia-Pacific Automotive Refinish Coatings Market
Coatings
US Industrial Coatings Market
Coatings
Conductive Coatings Market
Coatings
Dispersion Coating Market
Coatings
United Kingdom Automotive OEM Coatings Market
Coatings
Coating Auxiliaries Market
Coatings
Topcoat Market
Coatings
Fillers and Coating Market
Coatings
Self-Healing Microcapsule Systems for Protective Coatings Market
Coatings
North America Superhydrophobic Coating Market
Coatings
Electrocoat Market
Coatings
BPA-Free Coatings Market
Coatings
Water Based Enamel Market