
 Asia-Pacific Superhydrophobic Coating Market | 2026-2036
Asia-Pacific Superhydrophobic Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Superhydrophobic Coating Market Outlook
Electronics OEMs is bifurcating from automotive as the dominant buyer archetype across the Asia-Pacific superhydrophobic coating value chain. NTT Advanced Technology Corporation anchors Japan's precision electronics supply with fluoropolymer expertise refined through decades of telecom infrastructure work. P2i Ltd leverages its plasma-enhanced deposition platform to sustain premium positioning in smartphone waterproofing contracts across East Asia. Nanex Co competes aggressively on water-based formulations for China's domestic textile processors.
Superhydrophobic coatings are thin-film surface treatments engineered with contact angles exceeding 150 degrees and roll-off angles below 10 degrees, typically incorporating fluorinated compounds or silica nanoparticles to repel water, oil, and contaminants in harsh operational environments. Spray coating technology dominates volume throughput in automotive underbody applications where line-speed compatibility matters most, while nano coatings command margin premiums in semiconductor cleanroom protocols where atomic-layer precision prevents catastrophic shorting. Dip coating retains structural importance for textile batch processing across India's technical fabrics sector, though solvent-based chemistries face mounting compliance costs under REACH-aligned regulatory convergence.
China's SAMR enforces GB standards on volatile organic compound emissions from solvent-based formulations, while Japan's METI promotes low-carbon manufacturing incentives that favor water-based and hybrid coating transitions. India's BIS certification requirements for imported nano materials create procedural friction for foreign suppliers seeking direct market access. Stakeholders must monitor regulatory divergence between national standards bodies versus the harmonization pressure from ISO 23131 surface characterization protocols.
Market Dynamics
Electronics OEM procurement is displacing automotive buyers as the dominant demand anchor across Asia-Pacific superhydrophobic coating value chains. South Korean and Japanese circuit board manufacturers now specify nano-scale fluoropolymer formulations for moisture protection in 5G infrastructure and foldable device assemblies.
Growth Catalysts
- GB Standard VOC Limits:China's SAMR enforcement on solvent-based emissions is accelerating water-based formulation R&D among domestic suppliers.
- Semiconductor Cleanroom Protocols:Atomic-layer deposition demand from Yangtze River Delta fabs is pulling precision nano coating capacity expansion.
- Textile Technical Fabrics:India's technical fabrics sector is absorbing dip-coated superhydrophobic batches for industrial protective gear.
Market Restraints
- Fluorinated Feedstock Concentration:Precursor chemical supply clusters in Zhejiang and Guangdong provinces create geographic vulnerability to weather disruptions.
- BIS Import Friction:India's Bureau of Indian Standards certification timelines for nano material imports extend supplier qualification cycles by 8-14 months.
- Plasma Equipment Capex:PVD and CVD deposition systems require capital outlays that exclude mid-scale textile processors from premium coating access.
Strategic Opportunities
- Vietnam Electronics Assembly:Samsung and Foxconn expansion in Bac Ninh and Bac Giang provinces is creating greenfield demand for smartphone waterproofing contracts.
- METI Low-Carbon Incentives:Japan's Ministry of Economy, Trade and Industry manufacturing subsidies favor hybrid water-solvent formulation transitions.
- Medical Device Convergence:Combination of superhydrophobic barriers with antimicrobial silver nanoparticles is opening catheter and implant coating specifications.
Industry Challenges
- Thin-Film Technician Scarcity:Plasma-enhanced deposition operation and maintenance expertise concentrates in Osaka and Seoul metropolitan clusters.
- ISO 23131 Adoption Lag:Surface characterization protocol harmonization remains incomplete across Chinese, Japanese, and Indian testing laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Superhydrophobic Coating Market |
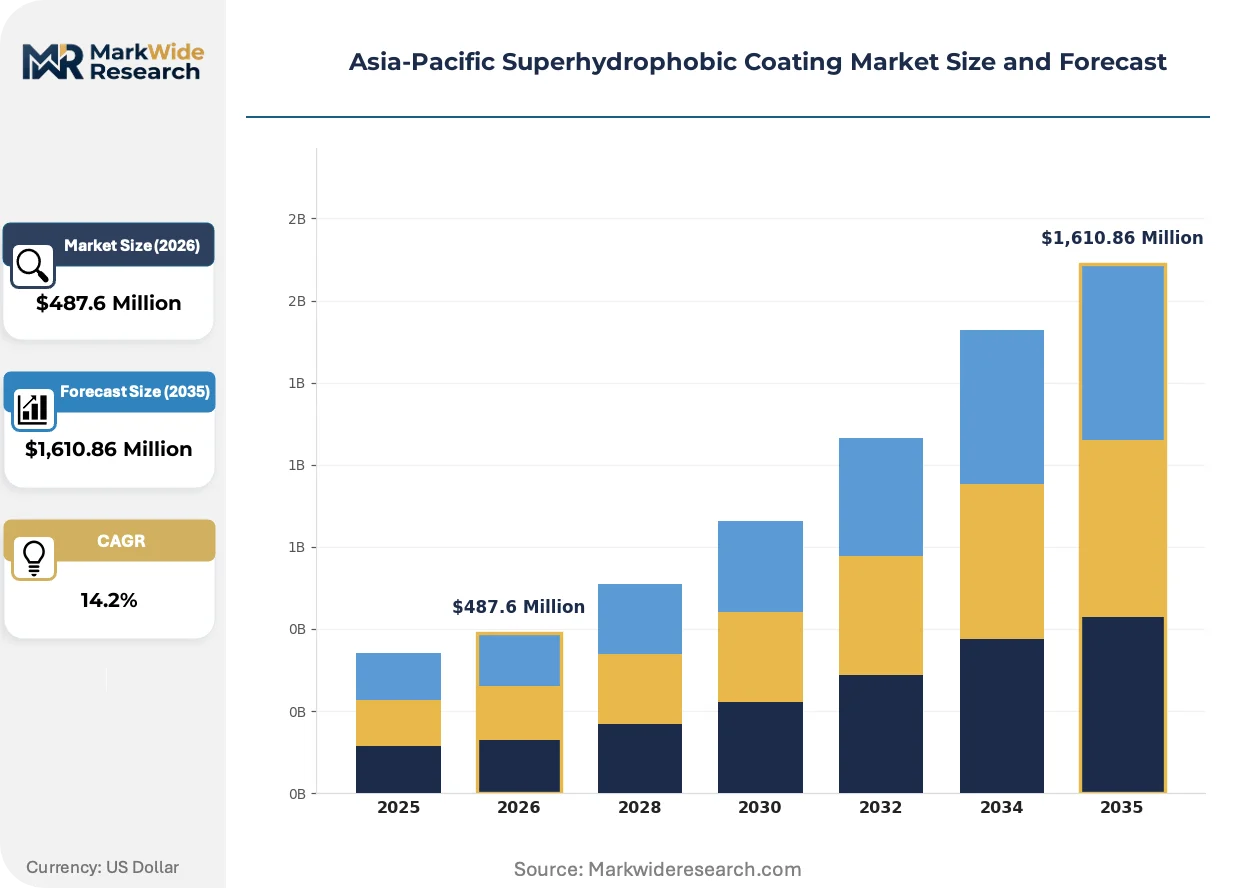
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,610.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Nano Coatings, Hybrid Coatings Application: Automotive, Electronics, Textiles, Construction Technology: Spray Coating, Dip Coating, Brush Coating, Roll Coating End User: Manufacturers, Retailers, Contractors, Service Providers |
| Companies Covered | Nanex Co, P2i Ltd, NTT Advanced Technology Corporation, Advanced Nanotech Lab, NEI Corporation, Beijing Neatrition Tech Co Ltd, Aculon, Nanoshel LLC, Nasiol Nano Coating, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Superhydrophobic Coating Market Strategic Shifts
Formulation chemistry and application hardware are converging to enable sub-micron precision at production-line speeds previously incompatible with superhydrophobic performance requirements.
Silica nanoparticle-fluoropolymer hybrid coatings are miniaturizing. These composites achieve sub-100 nanometer film thickness while maintaining contact angles above 150 degrees. Semiconductor packaging houses in Hsinchu and Suwon are adopting them for flip-chip underfill protection. The technology is miniaturizing equipment footprints and permitting inline integration with existing SMT lines.
Japan's METI energy efficiency directives now mandate process carbon disclosure for coating operations above specified throughput thresholds. Formulators must document solvent recovery rates and thermal energy consumption per square meter treated. Automotive underbody coating lines in Toyota City and Yokohama are retrofitting spray booths with closed-loop solvent systems to maintain supplier qualification status.
Electronics OEMs now require coating suppliers to assume end-of-life environmental liability through take-back clauses in master service agreements. Contract manufacturers in Dongguan and Penang are transferring compliance costs upstream to chemical providers. South Korean smartphone assemblers have pioneered this model, with Japanese electronics houses now embedding similar terms in 2024 procurement frameworks.
Asia-Pacific Superhydrophobic Coating Market Segmentation
Superhydrophobic coating procurement patterns diverge sharply across formulation chemistry, deposition method, and end-use specifications. Margin capture concentrates in nano-scale precision applications where semiconductor fabs and smartphone OEMs enforce atomic-layer tolerances.
Product Type:
Margin pools concentrate in fluoropolymer nano formulations where semiconductor packaging houses pay premiums for sub-100 nanometer precision.
- Nano Coatings:Silica nanoparticle-fluoropolymer composites achieve contact angles exceeding 150 degrees at film thicknesses below 100 nanometers. Yangtze River Delta fabs in Suzhou and Hsinchu specify these for flip-chip underfill protection against moisture-induced shorting.
- Water-Based:Acrylic and polyurethane dispersions carry lower VOC footprints that satisfy China's SAMR GB standard enforcement. Domestic Chinese textile processors in Shaoxing and Nantong favor these formulations to avoid solvent recovery capital expenditure.
- Solvent-Based:Fluorinated alkyl silane solutions in organic carriers deliver superior durability for automotive underbody applications.
- Hybrid Coatings:Water-solvent blends balance performance and compliance for mid-tier electronics contract manufacturers.
The dominant share belongs to solvent-based formulations, while nano coatings are gaining share fastest through semiconductor cleanroom specifications.
Application:
Electronics OEM procurement now exceeds automotive volumes as foldable devices and 5G infrastructure expand moisture protection requirements.
- Electronics:Circuit board manufacturers in Suwon and Osaka specify nano fluoropolymer coatings for 5G base station assemblies and foldable smartphone hinge mechanisms. Samsung and Foxconn expansion in Vietnam's Bac Ninh province is pulling additional coating capacity toward Southeast Asian assembly lines.
- Automotive:Spray-applied underbody treatments protect against road salt and corrosion in Japan's snowy Tohoku region and South Korea's Gangwon province. Toyota City suppliers retrofit closed-loop solvent systems to maintain METI supplier qualification.
- Textiles:Dip-coated technical fabrics serve India's industrial protective gear sector.
- Construction:Exterior facade treatments repel monsoon-driven moisture accumulation in Mumbai and Jakarta high-rises.
Electronics commands the largest revenue pool, with automotive applications climbing fastest through electric vehicle battery enclosure specifications.
Technology:
Deposition method selection tracks production scale and precision requirements across batch textile processing and inline electronics assembly.
- Spray Coating:Robotic spray booths dominate automotive underbody lines where line speeds exceed 30 meters per minute. Japanese suppliers in Toyota City and Yokohama invest in closed-loop solvent recovery to satisfy METI carbon disclosure mandates.
- Dip Coating:Batch immersion systems serve India's technical fabrics sector in Surat and Tiruppur, though solvent-based chemistries face mounting compliance costs under REACH-aligned regulatory convergence.
- Brush Coating:Manual application persists in construction maintenance and repair segments.
- Roll Coating:Continuous web processing suits high-volume textile finishing operations.
Spray coating holds the dominant share, while dip coating is expanding most quickly through India's protective gear export growth.
End User:
Procurement authority concentrates in integrated manufacturers who embed coating specifications into component supplier qualification frameworks.
- Manufacturers:Electronics OEMs in South Korea and Japan now require coating suppliers to assume end-of-life environmental liability through take-back clauses. Contract manufacturers in Dongguan transfer compliance costs upstream to chemical providers.
- Contractors:Construction applicators in Southeast Asia specify coating systems for facade and infrastructure projects.
- Retailers:Consumer product distributors stock aftermarket waterproofing treatments.
- Service Providers:Maintenance and repair specialists apply refresh coatings to extend asset lifecycles.
Manufacturers control the dominant procurement volume, while service providers are climbing fastest through industrial maintenance contract expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese superhydrophobic coating exports flow primarily toward Vietnam's expanding electronics assembly corridors, where Samsung and Foxconn contract manufacturers specify moisture protection for smartphone waterproofing programs.
China
Yangtze River Delta semiconductor fabs drive nano-coating procurement for flip-chip underfill protection. SAMR enforces GB standard VOC emission limits on solvent-based formulations. Suzhou and Hsinchu packaging houses specify sub-100 nanometer fluoropolymer films for 5G infrastructure components.
Japan
Precision electronics manufacturers anchor demand for atomic-layer deposition coatings in Osaka and Nagoya metropolitan clusters. METI mandates process carbon disclosure for coating operations above specified throughput thresholds. Toyota City automotive suppliers retrofit spray booths with closed-loop solvent systems to maintain supplier qualification.
South Korea
Suwon-based circuit board manufacturers specify nano fluoropolymer formulations for foldable device hinge mechanisms and 5G base station assemblies. The country's national industrial regulator promotes low-carbon manufacturing incentives favoring water-based formulation transitions. Seoul metropolitan plasma deposition expertise concentrates technician talent for equipment operation.
India
Technical fabrics processors in Surat and Tiruppur absorb dip-coated superhydrophobic batches for industrial protective gear exports. BIS certification requirements for imported nano materials extend supplier qualification cycles significantly. Domestic textile manufacturers favor water-based acrylic dispersions to avoid solvent recovery capital expenditure.
Vietnam
Samsung and Foxconn expansion in Bac Ninh and Bac Giang provinces generates greenfield demand for smartphone waterproofing contracts. The country's national standards body aligns import certification with REACH-adjacent chemical safety protocols. Northern electronics assembly corridors pull coating capacity toward Southeast Asian manufacturing lines.
Asia-Pacific Superhydrophobic Coating Market Competitive Environment
Player mix skews toward technology licensors and formulation specialists rather than integrated chemical conglomerates. Market structure fragments across three tiers: premium nano-precision suppliers serving semiconductor cleanrooms, mid-tier hybrid formulators balancing compliance and performance, and volume-focused water-based producers for textile batch processing. Dominant competitive moves include plasma equipment partnerships with electronics OEMs and geographic expansion toward Vietnam's electronics assembly corridor.
Within the precision-tier segment, NTT Advanced Technology Corporation and P2i Ltd exemplify technology-intensive positioning anchored through decades of telecom infrastructure refinement and plasma-enhanced deposition platforms respectively. Nanex Co occupies a competitive position among water-based formulation specialists serving China's domestic textile processors. These three entities represent distinct strategic archetypes: fluoropolymer expertise accumulated through vertical industry relationships, equipment-integrated coating platforms commanding premium smartphone contracts, and compliance-driven cost leadership for regulated manufacturing environments.
| Leading Market Players |
|---|
| Nanex Co |
| P2i Ltd |
| NTT Advanced Technology Corporation |
| Advanced Nanotech Lab |
| NEI Corporation |
| Beijing Neatrition Tech Co Ltd |
| Aculon |
| Nanoshel LLC |
| Nasiol Nano Coating |
| Others |
Value Chain & Pricing Dynamics
GB standard VOC certification gates supplier qualification while simultaneously stratifying price tiers across the Asia-Pacific superhydrophobic coating market. SAMR enforcement creates compliance premiums that separate certified water-based formulators from solvent-dependent competitors facing recovery capital expenditure.
Pricing Analysis
Second-generation plasma-enhanced nano coatings command premiums against first-generation spray-applied fluoropolymers, while third-generation hybrid water-solvent formulations target mid-tier displacement. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 23131 surface characterization compliance and METI carbon disclosure thresholds. Cost compression in solvent-based tiers is intensifying because closed-loop recovery systems add fixed cost burdens. Contract manufacturers in Dongguan exhibit highest price sensitivity, while Yangtze River Delta semiconductor fabs prioritize atomic-layer precision over unit cost.
Supply Chain Analysis
Strategic stockpiling of fluorinated precursors dominates procurement behavior among Japanese automotive suppliers, contrasting with just-in-time nano-powder sourcing at South Korean electronics houses. Feedstock concentration centers on Zhejiang and Guangdong provinces in China, with secondary clusters in Osaka and Seoul metropolitan areas. Raw material dependencies rest on fluorinated alkyl silanes, silica nanoparticles, and plasma deposition equipment. Single-source vulnerability concentrates in specialty fluoropolymer resin supply. Distribution runs through qualified chemical distributors holding SAMR and BIS import certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma deposition technician scarcity constrains capacity expansion across the Asia-Pacific superhydrophobic coating value chain. Equipment-integrated coating platforms require operational expertise that concentrates in Osaka and Seoul metropolitan clusters.
For Market Incumbents: Compound technical moats through captive plasma equipment partnerships with Vietnam's expanding electronics assembly corridors. Acquire water-based formulation specialists in Shaoxing and Nantong to preempt SAMR compliance displacement. Defensive consolidation must address emerging hybrid coating entrants from South Korea's national low-carbon incentive programs. For New Entrants and Emerging Players: Differentiate on METI-aligned carbon disclosure credentials to capture Toyota City automotive retrofit contracts. White-space targets include Vietnam's Bac Ninh smartphone waterproofing programs and India's BIS-certified nano material import substitution. Go-to-market positioning should leverage water-based acrylic dispersions for Surat technical fabrics processors seeking solvent recovery avoidance. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed equipment-integrated coating platforms holding Samsung and Foxconn master service agreements. Long-term viability hinges on end-of-life environmental liability transfer mechanisms embedded in OEM procurement frameworks. Acquisition targets should display ISO 23131 laboratory accreditation and established SAMR registration pathways. Watch for BIS certification timeline compression as India's signal of import policy inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Equipment Partnership | Locks in Samsung and Foxconn capacity allocation across Vietnam's Bac Ninh corridor. |
| Water-Based Formulation Transition | Secures SAMR GB standard compliance for Yangtze River Delta textile processors. |
| Backward Integration into Fluorinated Resins | Reduces Zhejiang supply cluster weather vulnerability for Japanese automotive suppliers. |
| ISO 23131 Laboratory Accreditation | Enables cross-border qualification between Chinese, Japanese, and Indian testing protocols. |
| End-of-Life Liability Assumption | Matches South Korean OEM procurement frameworks embedding take-back clause requirements. |
Study Parameters
A standing panel of thin-film deposition technicians, SAMR regulatory consultants, semiconductor packaging procurement managers, and textile chemical formulators provided ongoing calibration against secondary validation. Primary interviews combined with customs trade data, ACC and Cefic chemical industry reports, SEC 10-K filings from listed coating suppliers, and METI energy efficiency disclosure databases. Bottom-up capacity estimates from Yangtze River Delta and Osaka metropolitan clusters triangulated against top-down electronics OEM procurement spend analysis.
Consistency checks validated volume and value outputs against semiconductor fab capex disclosures and automotive coating line throughput benchmarks across the analysis window. Segmentation modeling tracked formulation chemistry, deposition technology, end-use application, and regional regulatory cluster dimensions. CAGRs derived from installed base growth rates and replacement cycle analysis, incorporating SAMR enforcement timeline assumptions and Vietnam electronics assembly expansion trajectories.
Material uncertainties — fluorinated feedstock price volatility, BIS certification timeline extension, and plasma equipment delivery delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding SAMR GB standard phase-in schedules and METI low-carbon incentive continuity. Revision becomes warranted when semiconductor packaging house capex crosses downward thresholds or Vietnam's national standards body accelerates REACH-adjacent chemical safety alignment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Optical Coating Market
Coatings
Carpet Back Coatings Market
Coatings
Industrial Liquid Coating Market
Coatings
Trim Coatings Market
Coatings
Anti-Microbial Powder Coatings Market
Coatings
Conductive Coatings Market
Coatings
Germany Industrial Coatings Market
Coatings
Global Abrasion Resistant Coatings Market
Coatings
Coating Thickness Gauge Market
Coatings
Marine Coatings Market
Coatings
South Africa Protective Coatings Market
Coatings
Spain Automotive OEM Coatings Market
Coatings
Corrosion Protection Polymer Coating Market
Coatings
North America Powder Coatings Market
Coatings
Vinyl Surface Coatings Market
Coatings
US Protective Coatings Market