
 Gelcoat Market | 2026-2036
Gelcoat Market Size, Share, and Industry Trends Forecast 2026-2036
Gelcoat Market Analysis
Asset-light toll manufacturing and third-party resin leasing arrangements are fragmenting competitive boundaries in gelcoat supply. Polynt S.p.A. leverages backward integration into specialty polyester resins to secure feedstock consistency across European marine yards. Owens Corning anchors its position through fiberglass-compatible gelcoat formulations that dominate North American wind energy nacelle production. Akzo Nobel N.V. competes via marine-certified color-stable systems that command premium positioning in superyacht finishing.
Gelcoat is a thermosetting resin surface coating, typically formulated from unsaturated polyester, vinyl ester, or epoxy bases with pigment and thixotropic additives, applied at 0.4–0.6 mm thickness to provide UV resistance, osmotic barrier protection, and cosmetic finish to fiber-reinforced plastic substrates. Polyester gelcoat retains the largest volume share due to its cost efficiency in marine and construction molding, though vinyl ester gelcoat is gaining share in chemical containment and corrosive industrial environments where blister resistance justifies higher material cost. Epoxy gelcoat occupies a specialized tier in aerospace tool molds and high-performance marine racing craft where thermal stability and adhesion strength override price sensitivity.
EPA VOC regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based gelcoat formulations in US manufacturing facilities, while REACH registration requirements in Europe mandate full substance dossiers for styrene and cobalt drier chemistries. The EU Green Deal carbon border adjustment mechanism will progressively penalize imported gelcoat systems with high embodied emissions, reshaping sourcing decisions for multinational composites fabricators. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and reformulation costs.
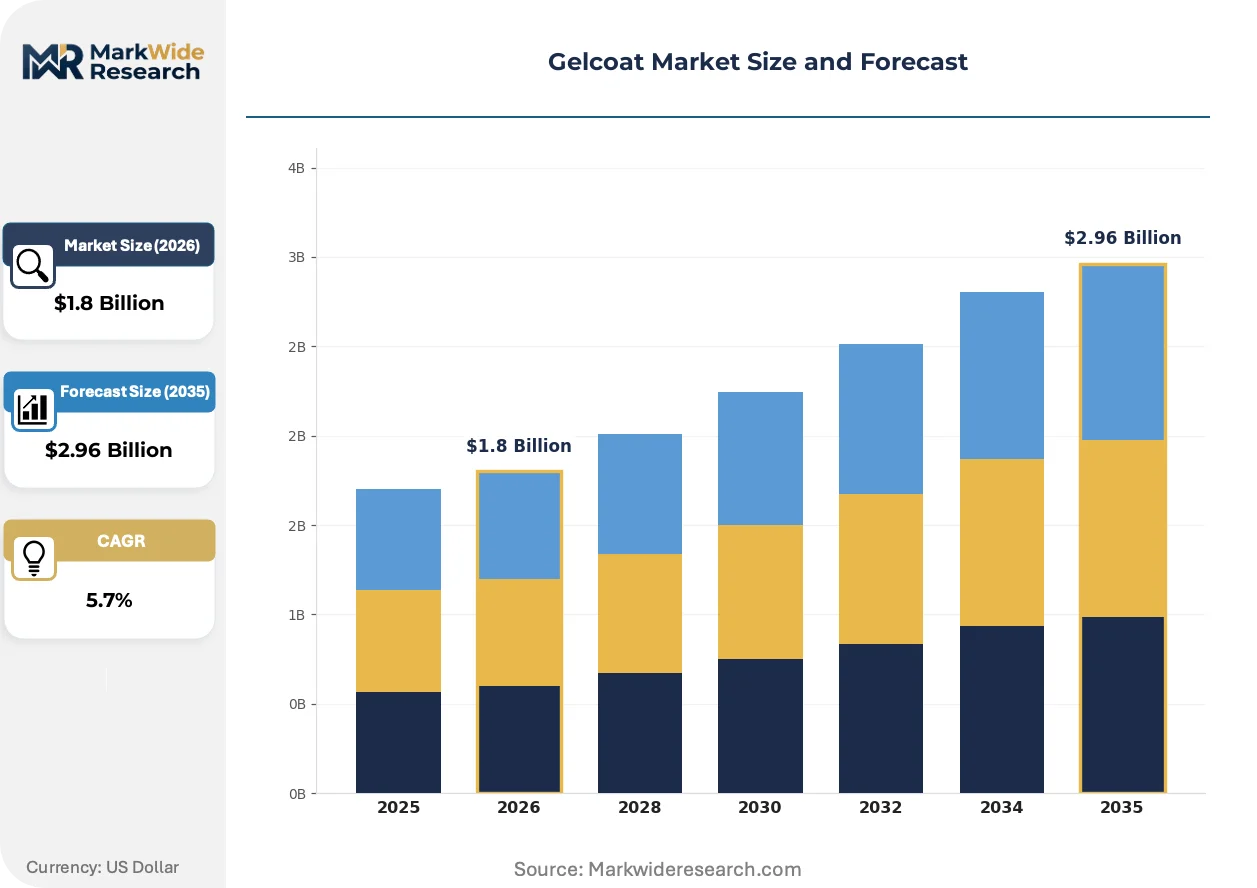
Market Dynamics
REACH compliance in Europe is forcing wholesale reformulation of styrene-based gelcoat systems, compressing margins for manufacturers dependent on conventional unsaturated polyester chemistries while creating first-mover advantages for low-VOC resin developers.
Growth Catalysts
- Marine hull protection mandates:Classification societies in Norway, Japan, and the United States are tightening osmotic barrier requirements for fiberglass vessels, expanding gelcoat specification in newbuild contracts.
- Wind blade fabrication scaling:China’s shipbuilding clusters are integrating gelcoat application lines into nacelle manufacturing, pulling vinyl ester formulations for lightning strike protection.
- EPA NESHAP alignment:US composites fabricators are retrofitting spray booths to meet hazardous air pollutant standards, accelerating compliant waterborne gelcoat adoption.
Market Restraints
- Styrene price volatility:Feedstock costs for unsaturated polyester resins fluctuate with benzene-crude spreads, squeezing batch-to-batch margin predictability for toll manufacturers.
- Specialty cobalt drier concentration:Supply of cobalt carboxylate accelerators concentrates in southern African mining jurisdictions, exposing formulators to export restriction risk.
- Epoxy gelcoat cost premium:Aerospace tool mold specifications require thermal stability thresholds that polyester cannot meet, but the five-to-seven-fold material cost differential limits addressable market expansion.
Strategic Opportunities
- EU carbon border adjustment mechanism:The phased implementation will penalize high-embodied-emission imports, rewarding European producers with low-carbon resin sourcing.
- Recyclable thermoplastic gelcoat development:Polypropylene-based surface films are converging with in-mold coating robotics, opening automotive exterior panel applications.
- Third-party resin leasing channels:Asset-light toll manufacturing arrangements are fragmenting traditional supply boundaries, enabling regional formulators to access captive resin streams without vertical infrastructure.
Industry Challenges
- Spray application technician certification:OSHA respiratory protection and EPA hazardous waste handling requirements extend training timelines, constraining workforce elasticity during demand surges.
- Legacy mold compatibility testing:Low-VOC reformulations exhibit divergent shrinkage coefficients against existing tooling, forcing expensive mold recalibration or replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gelcoat Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester Gelcoat, Epoxy Gelcoat, Vinyl Ester Gelcoat, Unsaturated Polyester Gelcoat Application: Marine, Automotive, Construction, Aerospace End User: OEMs, Manufacturers, Contractors, Retailers Distribution Channel: Direct Sales, Online, Retail, Wholesale |
| Companies Covered | Ashland Inc., Polynt S.p.A., Akzo Nobel N.V., 3M, Eastman Chemical Company, LyondellBasell Industries Holdings B.V., Interplastic Corporation, Owens Corning, INEOS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gelcoat Market Emerging Trajectories
Active reformulation of gelcoat chemistries is compressing the viable product lifecycle for conventional styrenated systems while opening competitive terrain for bio-based and waterborne alternatives.
Waterborne polyurethane-acrylic hybrid gelcoats are rendering obsolete solvent-borne marine finishing systems in Scandinavian and Baltic shipyards. Boatbuilders in Finland and Sweden are specifying these systems for production runs exceeding fifty hulls annually. The shift is compressing VOC compliance costs while extending color stability warranties beyond conventional polyester limits.
REACH registration dossiers for cobalt drier substances are tightening disclosure requirements across European formulators. The European Chemicals Agency is mandating full substance characterization for carboxylate accelerators used in ambient cure systems. Marine gelcoat producers in Italy and Spain are accelerating drier substitution trials to preempt authorization sunset dates.
Buyer consolidation among superyacht finishers is unbundling after-sales color-matching services from original material supply. Large refit yards in the Netherlands and Germany are internalizing spectrophotometric formulation capabilities. This pattern is most visible in North Sea cruising corridors where vessel downtime costs exceed material premiums by an order of magnitude.
Gelcoat Market Segmentation
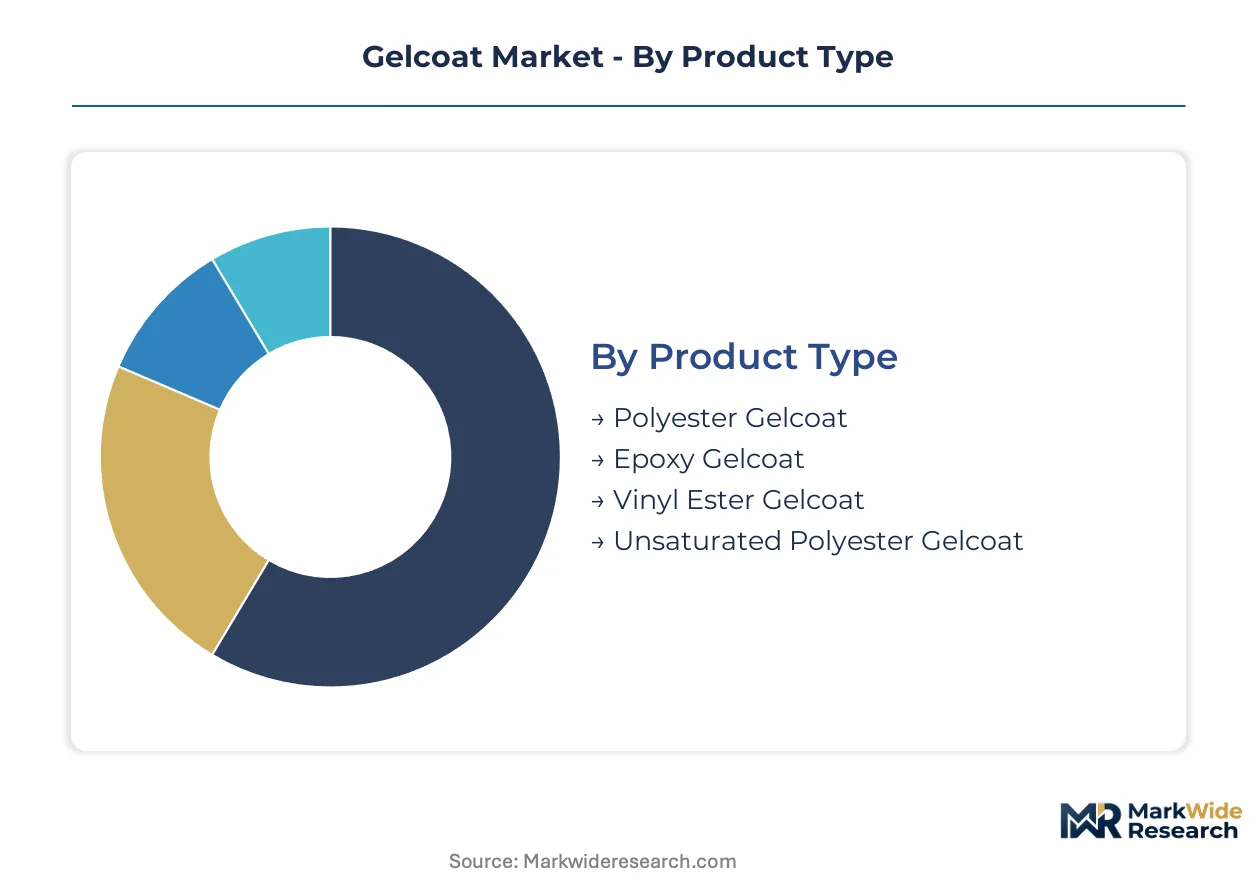
Gelcoat procurement patterns diverge sharply across resin chemistry, application environment, and buyer sophistication. Manufacturers configure formulation portfolios around thermal stability thresholds, VOC compliance mandates, and mold compatibility requirements that vary by end-use sector.
Product Type:
Cost tier differentiation separates commodity polyester systems from premium epoxy and vinyl ester formulations serving performance-critical specifications.
- Polyester Gelcoat:Unsaturated polyester resin systems dominate marine hull production and construction molding due to favorable cost-per-kilogram economics and ambient cure compatibility. Chinese shipyards and fiberglass pool manufacturers in the United States specify these formulations for high-volume lamination cycles where material cost compression outweighs thermal performance requirements.
- Vinyl Ester Gelcoat:Hybrid styrene-vinyl ester chemistries deliver superior blister resistance and chemical containment integrity for corrosive industrial environments. Demand concentrates in chemical storage tank fabrication and wind turbine nacelle production, where lightning strike protection and osmotic barrier specifications justify the 40-60% material cost premium over conventional polyester.
- Epoxy Gelcoat:Aerospace tool molds and high-performance marine racing craft require these systems for thermal stability above 120°C and adhesion strength to carbon fiber prepregs.
- Unsaturated Polyester Gelcoat:Standard orthophthalic and isophthalic formulations serve budget-sensitive applications in recreational watercraft and sanitary ware where regulatory pressure for low-VOC alternatives remains limited.
Polyester gelcoat commands the established base. The steepest expansion runs through vinyl ester formulations.
Application:
End-use performance requirements dictate resin selection, application thickness, and cure system configuration across industrial sectors.
- Marine:Classification societies in Norway, Japan, and the United States mandate osmotic barrier specifications for fiberglass vessel hulls, driving gelcoat thickness requirements of 0.5-0.7mm in newbuild contracts. Superyacht finishers in the Netherlands and Germany specify color-stable systems with 10-year warranty coverage.
- Automotive:In-mold coating robotics and thermoplastic gelcoat films are converging for exterior panel applications, though thermoset epoxy systems retain niche positioning in motorsport bodywork where surface temperature resistance exceeds 150°C.
- Construction:Fiberglass-reinforced plastic cladding, roofing panels, and sanitary fixtures specify pigmented polyester gelcoats for UV degradation resistance in exterior exposure conditions.
- Aerospace:Tooling gelcoats for composite mold fabrication require CTE-matched epoxy formulations that withstand autoclave curing cycles without surface crazing or dimensional drift.
Marine applications anchor volume demand. Automotive exterior panels show the most rapid technology substitution potential.
End User:
Buyer scale and technical capability determine procurement channel preference and formulation customization depth.
- OEMs:Original equipment manufacturers in wind energy and marine sectors negotiate multi-year resin supply agreements with backward-integrated formulators, securing volume pricing and batch consistency guarantees for nacelle and hull production lines.
- Manufacturers:Tier-1 composites fabricators operate captive spray booths with EPA NESHAP-compliant ventilation, enabling direct procurement of high-solids gelcoat in bulk tote quantities.
- Contractors:Independent boat repair and refit specialists purchase through distributor networks, prioritizing color-matched kit packaging and technical support access over unit cost minimization.
- Retailers:Marine chandleries and hardware stores serve DIY fiberglass repair markets with pre-packaged quart and gallon quantities, carrying limited SKU breadth focused on white and neutral pigmented standards.
OEMs and manufacturers capture the procurement value pool. Contractor channel expansion is accelerating most quickly in coastal refit corridors.
Distribution Channel:
Supply chain configuration aligns with buyer technical sophistication and inventory velocity requirements.
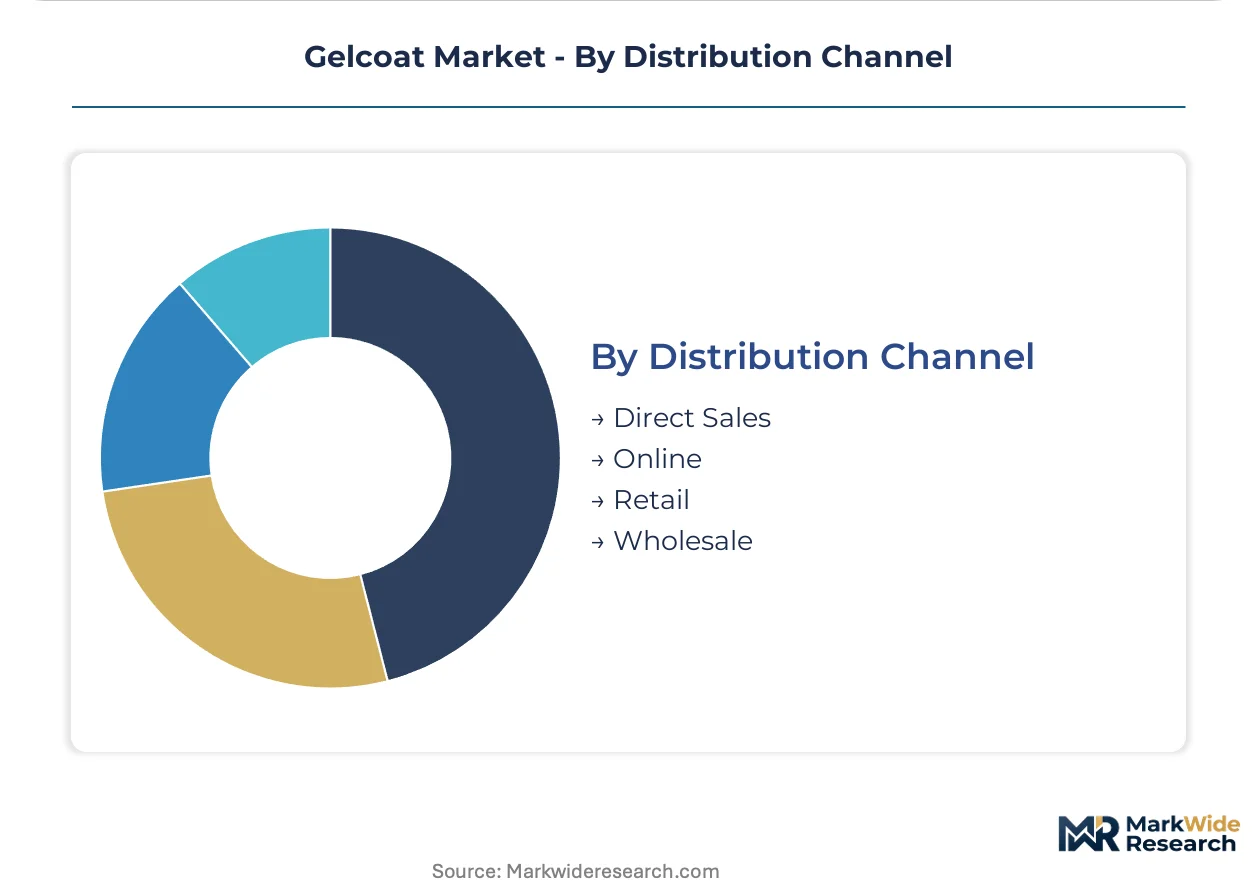
- Direct Sales:Large-volume marine and wind energy producers source through mill-direct arrangements with resin formulators, eliminating distributor margin and enabling just-in-time drum delivery to application lines.
- Online:E-commerce penetration remains limited to standard pigmented formulations and repair kit accessories, constrained by hazardous material shipping regulations and temperature-controlled storage requirements.
- Retail:Independent marine supply stores serve recreational boat owners with small-package gelcoat and catalyst combinations, supported by counter staff with spray application expertise.
- Wholesale:Regional distributors maintain refrigerated warehousing for perishable catalyzed systems, providing same-day availability to composites shops and mobile repair contractors.
Direct sales and wholesale channels command the volume flow. Online distribution is gaining share fastest in aftermarket repair segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in European marine finishing corridors where REACH compliance costs filter out marginal suppliers, while Chinese fabricators compete on volume scale without equivalent regulatory burden.
United States
Marine hull production in Florida and Washington state drives polyester gelcoat consumption for recreational watercraft. EPA NESHAP regulations constrain solvent-based spray operations, pushing Gulf Coast fabricators toward waterborne system retrofits. Charleston and Newport News shipyards specify vinyl ester formulations for military vessel contracts.
China
Wind turbine nacelle manufacturing in Jiangsu and Guangdong provinces pulls vinyl ester gelcoat for lightning strike protection. MEE enforcement of dual carbon goals tightens emissions standards for composites molding operations. Dalian and Shanghai shipbuilding clusters integrate automated gelcoat application lines into newbuild hull production.
Germany
Superyacht refit yards in Hamburg and Bremen internalize spectrophotometric color-matching capabilities to reduce vessel downtime. EU Green Deal carbon border adjustments penalize high-embodied-emission imports, favoring domestic producers with low-carbon resin sourcing. Bavarian automotive suppliers trial thermoplastic gelcoat films for exterior panel applications.
Netherlands
North Sea cruising corridors concentrate superyacht finishing demand where material premiums pale against downtime costs. ECHA cobalt drier authorization requirements accelerate substitution trials among marine gelcoat formulators. Rotterdam-area composites fabricators serve offshore wind installation vessel construction.
Japan
Classification society osmotic barrier mandates expand gelcoat specification in fiberglass vessel newbuilds. METI industrial standards guide low-VOC reformulation timelines for domestic resin producers. Nagoya and Osaka marine manufacturing clusters emphasize color-stable systems with extended warranty coverage.
Gelcoat Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in resin and additive supply. The vendor base spans backward-integrated chemical conglomerates, captive resin producers, and toll manufacturing specialists. Three archetypes dominate: polyester resin manufacturers extending downstream, fiberglass producers bundling compatible surface coatings, and marine-certified color houses serving superyacht finishers. Capacity expansion and strategic partnerships represent the dominant competitive moves, with asset-light toll arrangements fragmenting traditional supply boundaries.
Among European chemical conglomerates, Polynt S.p.A. and Akzo Nobel N.V. occupy positions reflecting distinct strategic archetypes—resin integration versus marine-certified formulation expertise. Owens Corning anchors the fiberglass-compatible tier through its position in wind energy nacelle supply chains. These three exemplify how geographic regulatory exposure and end-use specialization stratify competitive positioning without requiring equivalent scale.
| Leading Market Players |
|---|
| Ashland Inc. |
| Polynt S.p.A. |
| Akzo Nobel N.V. |
| 3M |
| Eastman Chemical Company |
| LyondellBasell Industries Holdings B.V. |
| Interplastic Corporation |
| Owens Corning |
| INEOS |
| Others |
Supply Flow & Price Mechanics
Cobalt carboxylate supply concentration in southern African mining jurisdictions determines both three-tier pricing spreads across premium, standard, and economy gelcoat grades and the geographic shape of resin distribution networks. REACH authorization timelines for drier substances compress margins for European formulators while amplifying cost advantages for toll manufacturers with flexible feedstock sourcing.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across marine and wind energy procurement channels. Price differentiation separates marine-certified color-stable systems with extended warranty coverage from commodity polyester formulations serving construction molding. Cost compression in standard-grade polyester tiers is intensifying because Chinese shipbuilding clusters exploit scale economies without equivalent regulatory compliance burdens. DIY repair contractors through retail channels exhibit the highest price sensitivity, while superyacht finishers in North Sea corridors prioritize color-matching service bundles over unit cost minimization.
Supply Chain Analysis
Styrene and benzene feedstock extraction concentrates in China, the United States, and Middle Eastern petrochemical hubs. Unsaturated polyester resin production draws from these aromatic hydrocarbon streams, with vinyl ester formulations additionally sourcing methacrylic acid derivatives. Single-source vulnerability sits with cobalt carboxylate accelerator supply, where export restrictions from southern African jurisdictions could disrupt ambient cure system availability. Distribution runs through mill-direct arrangements for high-volume marine and wind energy producers, while wholesale channels with refrigerated warehousing serve regional composites fabricators and mobile repair contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gelcoat market sits at a platform-economics inflection where thermoplastic film convergence with in-mold coating robotics threatens to unbundle traditional thermoset formulation value pools.
For Market Incumbents: Entrench backward integration into specialty polyester resins to secure feedstock consistency against styrene price volatility. Lock in multi-year resin supply agreements with wind energy OEMs before EU carbon border adjustments reshape import competitiveness. Prioritize cobalt drier substitution R&D to preempt ECHA authorization sunset dates that would strand conventional formulation inventories.
For New Entrants and Emerging Players: Establish a beachhead in waterborne polyurethane-acrylic hybrid systems for Scandinavian marine production runs exceeding fifty hulls annually. Target automotive exterior panel applications where thermoplastic gelcoat films and in-mold coating robotics converge. Pursue toll manufacturing arrangements with asset-light infrastructure to access captive resin streams without vertical capital deployment.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors formulators with marine-certified color-matching capabilities and REACH-compliant low-VOC portfolios. Long-term viability over the coming decade hinges on regulatory compliance infrastructure rather than commodity scale. Watch ECHA cobalt drier authorization rulings as the inflection signal for competitive repricing across European supply.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resins | Polynt S.p.A. secures feedstock consistency across European marine yards through captive polyester production. |
| Low-VOC Reformulation Investment | Finnish and Swedish boatbuilders specify waterborne systems that compress compliance costs below conventional polyester limits. |
| Marine Certification Expansion | Akzo Nobel N.V. commands premium positioning in superyacht finishing through color-stable warranty coverage. |
| Toll Manufacturing Partnership | Asset-light arrangements fragment traditional supply boundaries for regional formulators accessing captive resin streams. |
| Thermoplastic Film Development | Bavarian automotive suppliers trial polypropylene-based surface films for exterior panel in-mold coating applications. |
Methodological Framework
The analysis maps polyester, vinyl ester, and epoxy gelcoat chemistries alongside thermoplastic film convergence, each validated through plant managers at resin formulators, procurement leads at marine and wind energy OEMs, distribution channel partners, and technical R&D directors. Primary interview data triangulates against customs and trade flow records, ACC and Cefic industry reports, SEC 10-K filings from listed chemical conglomerates, and EPA NESHAP compliance disclosures. Bottom-up volume builds from application-line specifications and batch production records reconcile with top-down market sizing from trade association aggregates.
Forecast assumptions hold regulatory implementation timelines and carbon border adjustment phase-ins as fixed boundary conditions while varying feedstock cost scenarios and substitution elasticities across the projection horizon. Segmentation dimensions modeled include resin chemistry tier, end-use industry application, buyer procurement channel, and regional regulatory cluster. CAGRs derive from slope-intercept analysis of historical volume trajectories adjusted for technology substitution coefficients and compliance-driven demand elasticity shifts specific to marine osmotic barrier mandates and wind blade lightning protection specifications.
Macroeconomic conditions sit as an overlay; deviation in crude-benzene spreads, cobalt export restriction severity, or EU carbon border adjustment enforcement pace would shift the trajectory. Forecasts reflect these assumptions without claiming predictive certainty. Cross-checking against ECHA substance authorization timelines and MEE dual carbon enforcement intensity is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Anti-Reflective Coatings Market
Coatings
Soft Touch Polyurethane Coatings Market
Coatings
Marine Nanocoating Market
Coatings
Germany Industrial Coatings Market
Coatings
Global Anti Slip Coatings Market
Coatings
Canada Floor Coatings Market
Coatings
Global Wood Protection Coating Market
Coatings
Egypt Automotive OEM Coatings Market
Coatings
United Arab Emirates Protective Coatings Market
Coatings
United Kingdom Protective Coatings Market
Coatings
Automotive Refinish Coatings Market
Coatings
Marine Anti Fouling Coatings Market
Coatings
Tablet and Pellet Coating Systems Market
Coatings
Paper Coating Binders Market
Coatings
Acrylic Surface Coating Market
Coatings
Global Radiation Cured Coatings Market