
 US Coated Steel Market | 2026-2036
US Coated Steel Market Size, Share, and Industry Trends Forecast 2026-2036
US Coated Steel Market Intelligence
A divergence in capital investment for advanced coating lines is reorganizing the competitive landscape. Nucor Corporation leverages its electric arc furnace production model to integrate downstream into specialized galvanized and pre-painted steel products. Cleveland-Cliffs Inc. sustains its market position through its extensive iron ore and blast furnace assets, supplying its own coating facilities. Meanwhile, Steel Dynamics, Inc. competes on process innovation and regional production hubs.
Coated steel comprises a carbon steel substrate that is layered with a metallic or organic coating to enhance durability and corrosion resistance. The process involves methods like hot-dip galvanization or continuous coil coating to apply layers often measured in microns. Galvanized steel products dominate volume for the construction end-use sector, particularly in structural framing and roofing applications. Higher-margin, pre-painted steel finds its primary outlet in automotive manufacturing and consumer appliances, where aesthetics are critical.
The Environmental Protection Agency (EPA) imposes strict limits on volatile organic compound (VOC) emissions from coating lines, influencing technology choices. Occupational Safety and Health Administration (OSHA) standards govern worker exposure to hexavalent chromium and other chemicals used in coating processes. Future profitability will hinge on navigating these environmental regulations while developing coatings that meet evolving performance demands from end-users.
Market Dynamics
Stringent EPA regulations on emissions and the geographic re-concentration of manufacturing into the US Southeast define the US coated steel market. This interplay is steering capital investment and shaping supply chains for the industrial base.
Growth Catalysts
- Automotive Sector Demand:The transition to electric vehicles in the US automotive industry drives requirements for lightweight, corrosion-resistant galvanized and pre-painted steel for body panels and structural components.
- Infrastructure Investment:Federal spending on public works and infrastructure upgrades stimulates consumption of galvanized steel products for applications like guardrails, roofing, and structural framing in commercial buildings.
- Southeastern Industrialization:The expansion of manufacturing facilities across the US Southeast creates localized demand, attracting new investments in advanced coil coating lines to serve this growing regional hub.
Market Restraints
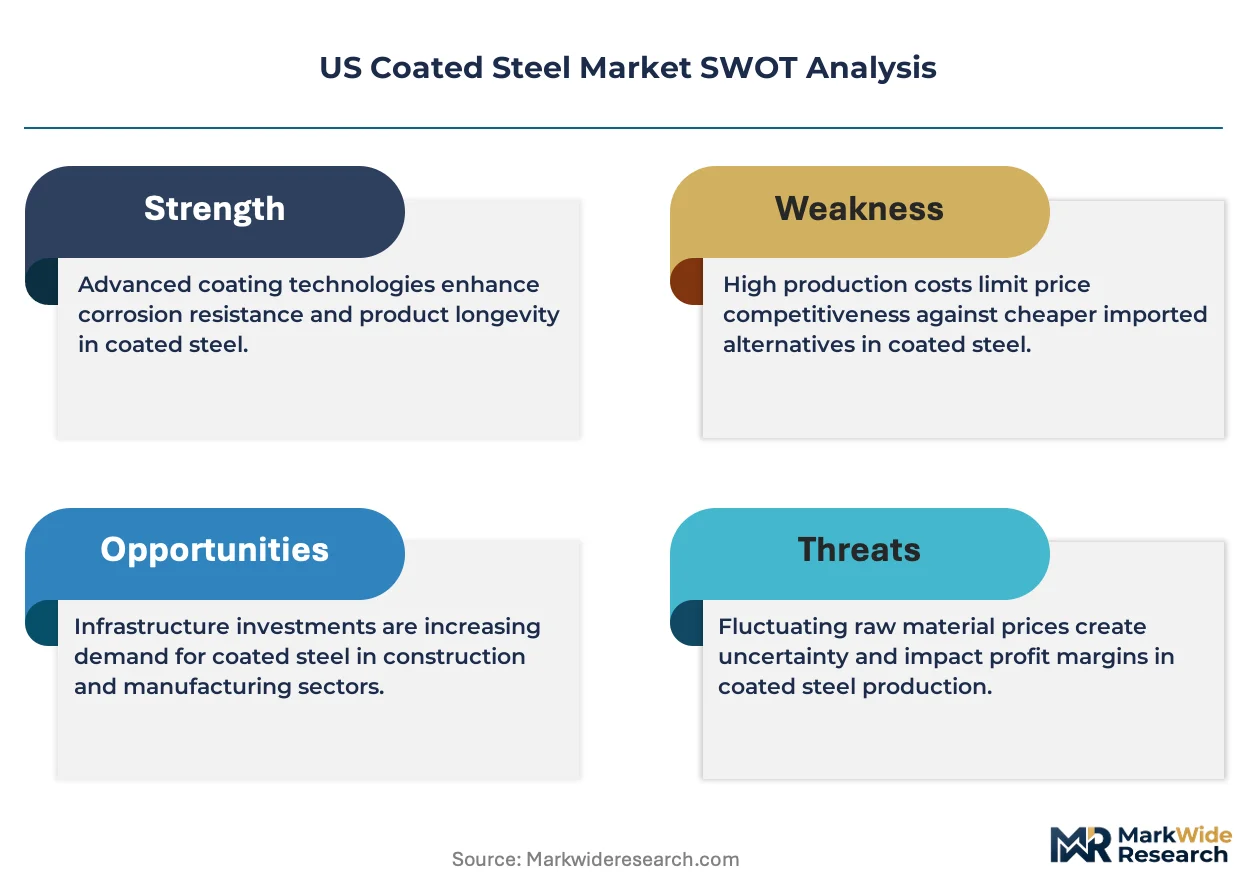
- Input Cost Volatility:Fluctuations in the prices of key raw materials, such as zinc for galvanization and specialized polymers for organic coatings, directly impact production costs and compress manufacturer margins.
- Regulatory Compliance Costs:The capital and operational expenses associated with meeting strict EPA standards for volatile organic compounds (VOCs) create a significant barrier to entry for smaller producers.
- Substitution from Aluminum:In specific automotive applications where extreme weight reduction is paramount, aluminum poses a substitution threat to advanced high-strength coated steels, despite its higher material cost.
Strategic Opportunities
- Specialized Applications:Developing coatings for electric vehicle battery enclosures presents a high-margin opportunity tied to unique thermal and electrical insulation demands.
- Regulatory Tailwinds:EPA rules favoring low-VOC technologies create an opening for powder and water-based coatings that meet new environmental standards.
- Infrastructure Renewal:Retrofitting aging structures in the Northeast with modern, corrosion-resistant coated steel opens demand for architectural and structural products.
Industry Challenges
- Capital Intensity:The high capital expenditure required to construct new, or upgrade existing, continuous coil coating lines to meet modern environmental and quality specifications constrains capacity expansion.
- Skilled Labor Scarcity:A shortage of technicians and engineers with expertise in modern coating chemistry and automated process controls presents an operational hurdle for steel producers.
- Lengthy Qualification Cycles:New coating systems face extensive and time-consuming testing and certification processes before they can be approved for use by automotive and architectural customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Coated Steel Market |
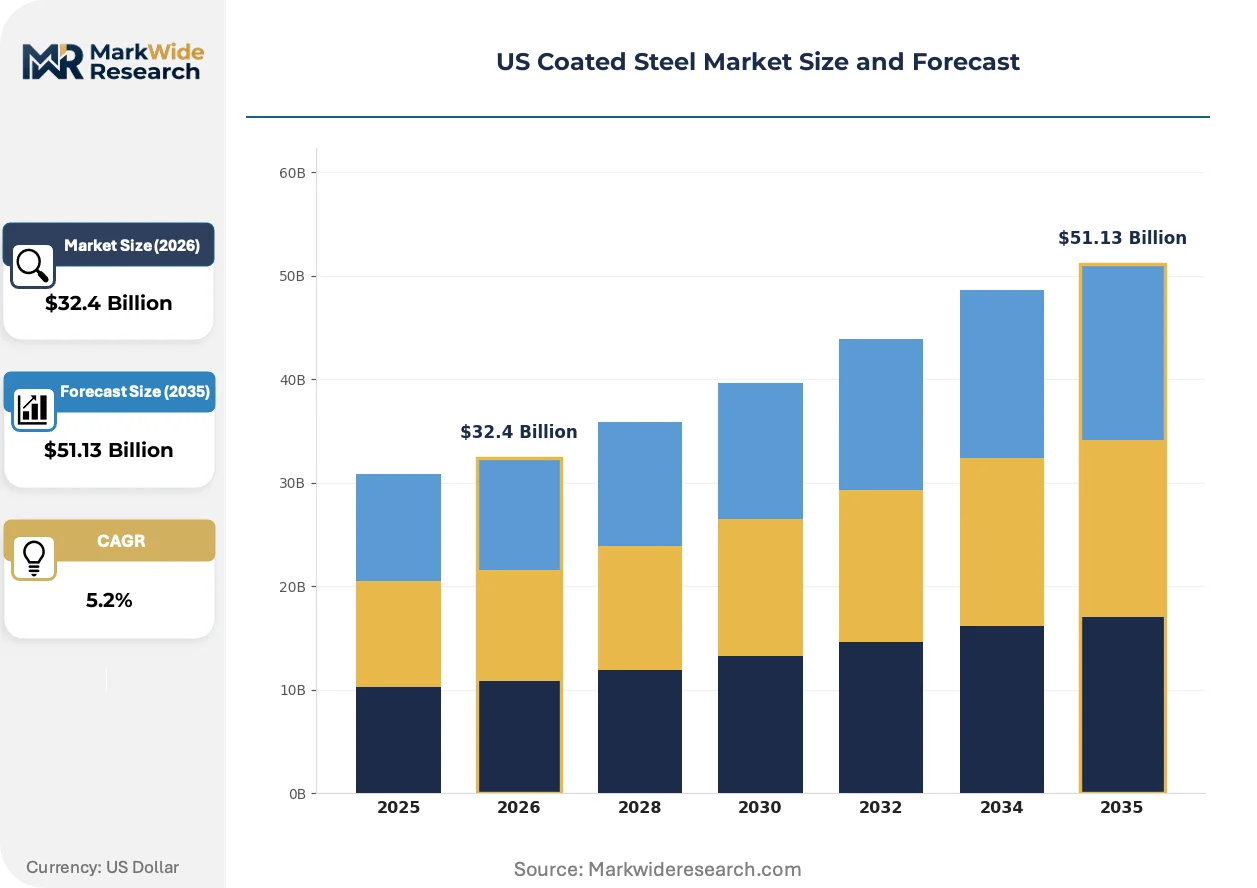
| Market Size in 2026 | $32.4 Billion |
| Market Size in 2035 | $51.13 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Galvanized Steel, Aluzinc Steel, Pre-painted Steel, Galvalume Steel End User: Construction, Automotive Manufacturing, Appliances, Electronics Coating Type: Polyester, Epoxy, PVC, Mica Thickness: Thin, Medium, Thick, Ultra-thin |
| Companies Covered | United States Steel Corporation, Commercial Metals Company, Nucor Corporation, Salzgitter AG, Nippon Steel Corporation, Cleveland-Cliffs Inc., ArcelorMittal, voestalpine AG, Steel Dynamics, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Coated Steel Market Strategic Shifts & Innovations
Advanced coating chemistries and the digitalization of production processes are fundamentally altering product capabilities and manufacturing economics. These innovations enable coated steel to meet more demanding performance criteria while navigating a complex regulatory environment in the United States.
Self-healing coatings incorporate microcapsules of healing agents that rupture upon damage to repair scratches and protect the underlying steel substrate. The consumer appliance and architectural panel sectors are adopting this technology to enhance product durability and aesthetic longevity. This innovation is supplanting traditional passive coating systems by providing active surface protection, which creates a distinct performance advantage in high-value applications.
OSHA's stringent standards governing worker exposure to hexavalent chromium are a powerful force for chemical innovation in the coating industry. This regulation is forcing the phase-out of traditional chromate conversion treatments, long used for their superior corrosion resistance. The building products and HVAC sectors are most affected, accelerating their transition to chrome-free pretreatment systems to ensure worker safety and regulatory compliance.
A demand-side shift toward shorter production runs and greater color customization is altering purchasing patterns from steel service centers. This change disrupts the traditional mill model of producing large, single-color coils, creating an advantage for agile service centers with digital coil coating capabilities. This trend is most pronounced within the metal building and architectural components segments, particularly in fast-growing metropolitan areas across the Sun Belt.
US Coated Steel Market Segmentation
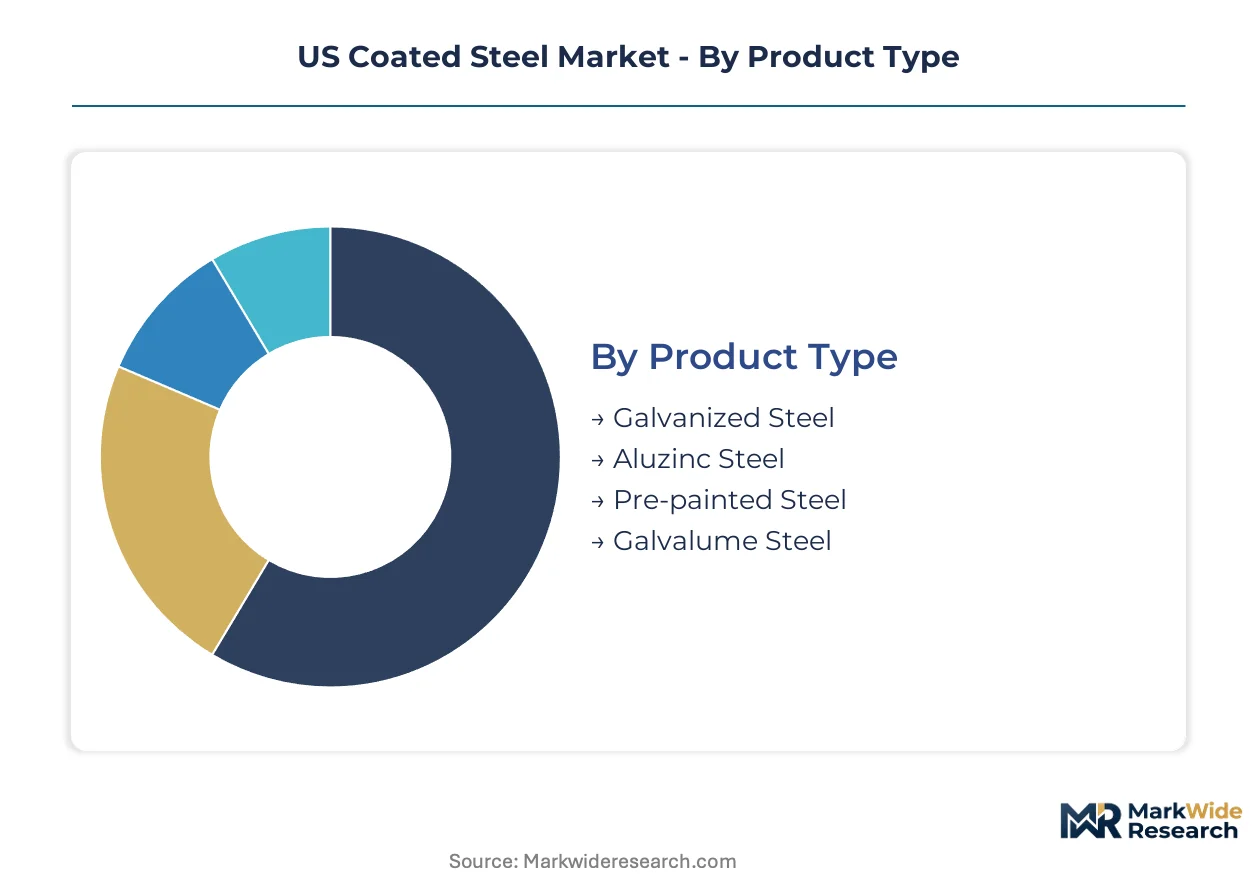
Understanding the segmentation of the US coated steel market illuminates the varied performance requirements and regulatory pressures shaping product development. Each segment addresses distinct end-user needs, influencing material specifications and process innovations across the supply chain.
Product Type:
US environmental regulations, particularly those from the EPA, significantly influence the selection and development of different coated steel product types by dictating acceptable emission levels during production.
- Galvanized Steel:This product features a zinc coating applied via hot-dip galvanization, offering robust cathodic and barrier corrosion protection to the underlying carbon steel. Demand concentrates in the US construction sector, driven by federal infrastructure spending on structural framing and roofing applications.
- Pre-painted Steel:Organic coatings are applied to steel coils, providing both aesthetic appeal and enhanced corrosion resistance for finished products. US automotive manufacturing increasingly demands pre-painted steel for body panels, where visual quality and durability are critical for consumer appeal.
- Aluzinc Steel:An aluminum-zinc alloy coating provides superior corrosion resistance compared to traditional galvanization, particularly in harsh outdoor environments. This product type finds application in roofing and exterior building components across the Sun Belt region.
- Galvalume Steel:Similar to Aluzinc, this specific aluminum-zinc alloy coating offers excellent heat reflectivity and long-term corrosion protection. US industrial and commercial construction projects utilize Galvalume for roofing and wall panels.
Established volume favors Galvanized Steel; emerging adoption favors Pre-painted Steel.
End User:
The specific application requirements of various end-user industries determine the performance characteristics and coating chemistries demanded from US coated steel manufacturers.
- Construction:This sector utilizes large volumes of coated steel for structural components, roofing, wall panels, and infrastructure projects requiring long-term durability. Federal investment in public works across the US stimulates consumption of corrosion-resistant galvanized steel products.
- Automotive Manufacturing:The industry requires lightweight, high-strength, and corrosion-resistant coated steels for vehicle bodies, chassis components, and electric vehicle battery enclosures. The transition to electric vehicles in the US drives demand for advanced pre-painted and galvanized steels.
- Appliances:Coated steel provides both structural integrity and aesthetic finishes for consumer goods like refrigerators, washing machines, and ovens. Manufacturers prioritize scratch resistance and color consistency for visible appliance surfaces.
- Electronics:Smaller volumes of specialized coated steel are used for casings, internal components, and enclosures where electromagnetic shielding or specific corrosion protection is required. This segment often demands thinner gauge materials.
Performance requirements drive demand for Automotive Manufacturing, while durability concerns prioritize Construction.
Coating Type:
The choice of coating type is often dictated by the balance between performance, cost, and environmental compliance, influencing material selection for various US industrial applications.
- Polyester:These organic coatings offer good weather resistance, color retention, and cost-effectiveness, making them suitable for general exterior architectural panels and roofing. Polyester coatings are widely used in commercial building projects throughout the US.
- Epoxy:Known for excellent adhesion, hardness, and chemical resistance, epoxy coatings are primarily used as primers or for industrial applications requiring robust protection against harsh environments. US manufacturers utilize epoxy coatings for internal structural components.
- PVC:Polyvinyl chloride coatings provide high durability, chemical resistance, and flexibility, often employed in demanding environments like roofing and wall cladding. PVC-coated steel is specified for long-life industrial buildings.
- Mica:Mica-pigmented coatings offer unique aesthetic properties, including metallic sheen and depth, primarily used for decorative architectural panels and high-end consumer appliances. These coatings provide visual differentiation in premium US construction.
Durability needs often dictate the selection of Epoxy, with aesthetic flexibility offered by Mica.
Thickness:
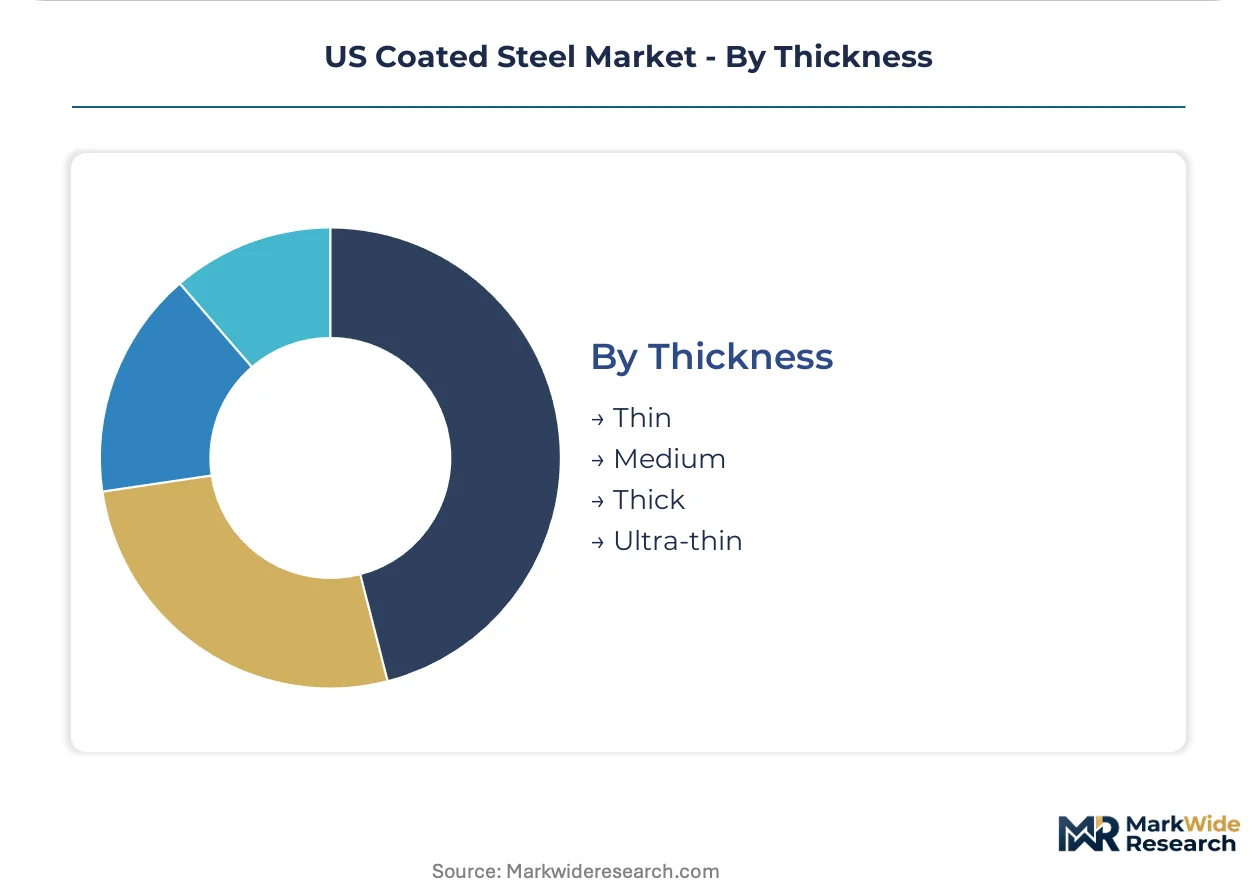
The thickness of the steel substrate, combined with its coating, directly impacts the material's structural properties, weight, and suitability for various end-use applications within the US market.
- Thin:Coated steel in thin gauges is critical for lightweighting initiatives in the US automotive sector, particularly for electric vehicle body panels and structural components. This thickness category also finds use in certain appliance parts.
- Ultra-thin:Representing the cutting edge in material reduction, ultra-thin coated steel offers significant weight savings for advanced automotive designs and specialized electronic enclosures. Demand for ultra-thin steel is expanding most quickly for EV battery casings.
- Medium:This thickness range represents a versatile category, commonly used across general construction, structural framing, and various industrial applications where a balance of strength and formability is required. US commercial buildings frequently incorporate medium-thickness coated steel.
- Thick:Coated steel with greater thickness provides enhanced structural integrity and load-bearing capacity, making it suitable for heavy-duty construction, infrastructure projects like guardrails, and large industrial components. Infrastructure upgrades across the US utilize thick galvanized steel.
Structural integrity often relies on Thick, whereas weight reduction initiatives favor Ultra-thin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US coated steel market exhibits regional pricing-power asymmetry, with the industrializing Southeast attracting significant capital investment for new coating lines. In contrast, established manufacturing centers in the Midwest face higher operational costs for legacy facilities. This dynamic influences supply chain optimization and product distribution across the country, creating distinct regional market characteristics.
US Southeast
The US Southeast experiences robust demand from its expanding manufacturing base, particularly for automotive and construction applications. EPA regulations on volatile organic compounds steer innovation towards advanced coating lines in the region, promoting water-based and powder coating technologies. New investments in states like Alabama and Kentucky are establishing localized production hubs, supporting electric vehicle battery enclosures and industrial infrastructure.
Midwest
Midwestern states maintain significant demand from their legacy automotive and appliance manufacturing sectors, requiring durable and aesthetically pleasing coated steels. OSHA standards governing hexavalent chromium exposure necessitate continuous process upgrades in older facilities, driving adoption of chrome-free pretreatment systems. Steel producers in Indiana and Illinois are modernizing operations to supply advanced coated steels for evolving industrial needs, including specialized components for agricultural machinery.
Northeast
Federal spending on infrastructure upgrades stimulates consumption of corrosion-resistant coated steel throughout the Northeast, particularly for bridges, guardrails, and public buildings. Regional environmental agencies enforce strict air quality standards, influencing coating material choices for construction and industrial maintenance. Cities such as Philadelphia and Baltimore utilize galvanized steel for public works and commercial building retrofits, emphasizing long-term durability in challenging climates.
Southwest
The Sun Belt's rapid expansion fuels demand for coated steel in residential and commercial construction across the Southwest, driven by population growth. Local building codes often prioritize energy efficiency, favoring products like Galvalume steel for its excellent heat reflectivity in hot climates. In areas like Phoenix and Dallas, galvanized and aluzinc steels are widely adopted for roofing and structural framing, meeting the region's specific architectural and environmental requirements.
US Coated Steel Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the US coated steel market, reflecting diverse operational models. The market exhibits a tiered structure, with large integrated steelmakers competing alongside specialized coil coaters and agile service centers. Strategic archetypes include vertically integrated producers leveraging raw material control, innovation-focused specialists developing advanced coating chemistries, and regionally concentrated distributors. Dominant competitive moves involve significant capital expenditure for capacity expansion in strategic geographies and continuous investment in advanced coating technologies to meet evolving performance demands.
At the scale-driven end of the market, Nucor Corporation exemplifies a competitive strategy focused on electric arc furnace production integrated downstream into specialized coated products. Cleveland-Cliffs Inc. occupies a position rooted in extensive iron ore and blast furnace assets, supplying its own coating facilities to maintain cost control. Steel Dynamics, Inc. sits within the archetype of a process innovator, leveraging regional production hubs for efficient supply to diverse end-use sectors. These companies collectively anchor significant production capacity and drive technological advancements in the US coated steel industry.
| Leading Market Players |
|---|
| United States Steel Corporation |
| Commercial Metals Company |
| Nucor Corporation |
| Salzgitter AG |
| Nippon Steel Corporation |
| Cleveland-Cliffs Inc. |
| ArcelorMittal |
| voestalpine AG |
| Steel Dynamics, Inc. |
Cost & Logistics Intelligence
Long-term contractual agreements in the US coated steel market lock in both supply access and price visibility for major automotive and construction customers. This contract structure mitigates some volatility from raw material costs for large buyers, but smaller purchasers often rely on spot markets.
Pricing Analysis
Customization-premium spreads characterize pricing within the US coated steel market, where configured-to-order pre-painted coils command higher value than standard galvanized products. Price differentiation stems from the specific quality grade required for demanding applications like automotive body panels and the geographic delivery costs to regional manufacturing hubs. Pricing pressure stems from input cost volatility for zinc and specialized polymers. Construction sector buyers, needing high volumes of commodity-grade galvanized steel, exhibit the highest price sensitivity.
Supply Chain Analysis
The US anchors significant coated steel production capacity, particularly with new investments concentrating in the Southeast and established mills in the Midwest. This production relies heavily on raw material dependencies like zinc for galvanization and iron ore for primary steelmaking. Commodity price volatility for these inputs presents a structural supply chain risk. Distribution runs through a network of direct mill sales to large customers and agile steel service centers serving diverse regional end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a strong substitution defense, as the threat of aluminum in lightweight automotive applications compels incumbents to innovate continuously.
For Market Incumbents:Fortify market share by investing in advanced low-VOC coating lines, especially within the US Southeast, to meet evolving EPA standards and regional demand. Deepen vertical integration into specialized pre-painted products for electric vehicle battery enclosures, leveraging R&D into chrome-free and self-healing chemistries. Secure long-term supply agreements for key raw materials like zinc to buffer against input cost volatility, strengthening competitive positioning against aluminum substitution.
For New Entrants and Emerging Players:A service-layer gap exists in agile, short-run production for customized pre-painted steel, particularly for architectural components in fast-growing Sun Belt metropolitan areas. Target niche applications requiring specialized thermal or electrical insulation properties, such as electric vehicle battery casings, where performance outweighs initial material cost. Develop a go-to-market angle focused on rapid prototyping and faster qualification cycles for new coating systems to address customer demand for speed and customization.
For Investors and Strategic Acquirers:Capital is best deployed toward mid-sized coil coaters with proven expertise in advanced low-VOC coating technologies or those strategically located in the US Southeast. Long-term viability in this market is supported by federal infrastructure spending and the automotive industry's transition to electric vehicles. The signal to watch is the rate of adoption of new chrome-free pretreatment systems across the building products and HVAC sectors, indicating successful regulatory compliance and technological transition.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in US Southeast | Supports regional manufacturing growth and reduces logistics costs for automotive and construction customers. |
| Green Manufacturing Transition | Addresses EPA regulations on VOC emissions, enhancing compliance and market access for new coating lines. |
| Long-term Zinc Supply Agreements | Mitigates input cost volatility for galvanization, stabilizing production costs for coated steel manufacturers. |
| Product Launch: EV Battery Coatings | Captures high-margin opportunities in the electric vehicle sector, meeting unique thermal and electrical demands. |
| Joint Venture for Chrome-Free Pretreatment | Accelerates adoption of compliant technologies, ensuring worker safety and regulatory adherence for affected sectors. |
Research Approach
Desk research of US government reports, industry association publications, and company financial filings preceded structured interviews with steel mill executives, automotive procurement managers, construction material specifiers, and EPA officials. This approach combined primary insights with secondary validation, facilitating both bottom-up and top-down triangulation of market data. The study incorporated a comprehensive review of regulatory documents from OSHA and the EPA.
Variance decomposition informed the analytical framework, modeling market dynamics across the analysis window. Segmentation dimensions included product type, end-user, coating type, thickness, and regional demand patterns within the US. Compound annual growth rates were derived from historical data and projected forward based on identified growth catalysts and market restraints. Key forecast inputs included US electric vehicle production forecasts and federal infrastructure spending allocations.
Forecasts assume regulatory continuity in US federal and state regimes; material policy shifts would require re-modeling. The analysis acknowledges potential revisions due to unforeseen trade policies or rapid material science breakthroughs in competing materials like aluminum. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Direct Reduced Iron (DRI) Market
Metals & Minerals
Colored Gemstones Market
Metals & Minerals
Global Magnesium Oxide Market
Metals & Minerals
Garnet Market
Metals & Minerals
Chromium Mining Market
Metals & Minerals
Recycled Lead Market
Metals & Minerals
Prefab Iron Market
Metals & Minerals
Flake Graphite Market
Metals & Minerals
Phosphorus Ore Market
Metals & Minerals
Mineral Screening Market
Metals & Minerals
Testing Inspection and Certification TIC for the Metals and Minerals Market
Metals & Minerals
Selenium Market
Metals & Minerals
Diamond Market
Metals & Minerals
Middle-East and Africa Sodium Sulfide Market
Metals & Minerals
Frac Sand Market
Metals & Minerals
Bauxite Market