
 Anti-Adhesion Coatings Market | 2026-2036
Anti-Adhesion Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Adhesion Coatings Market Analytics
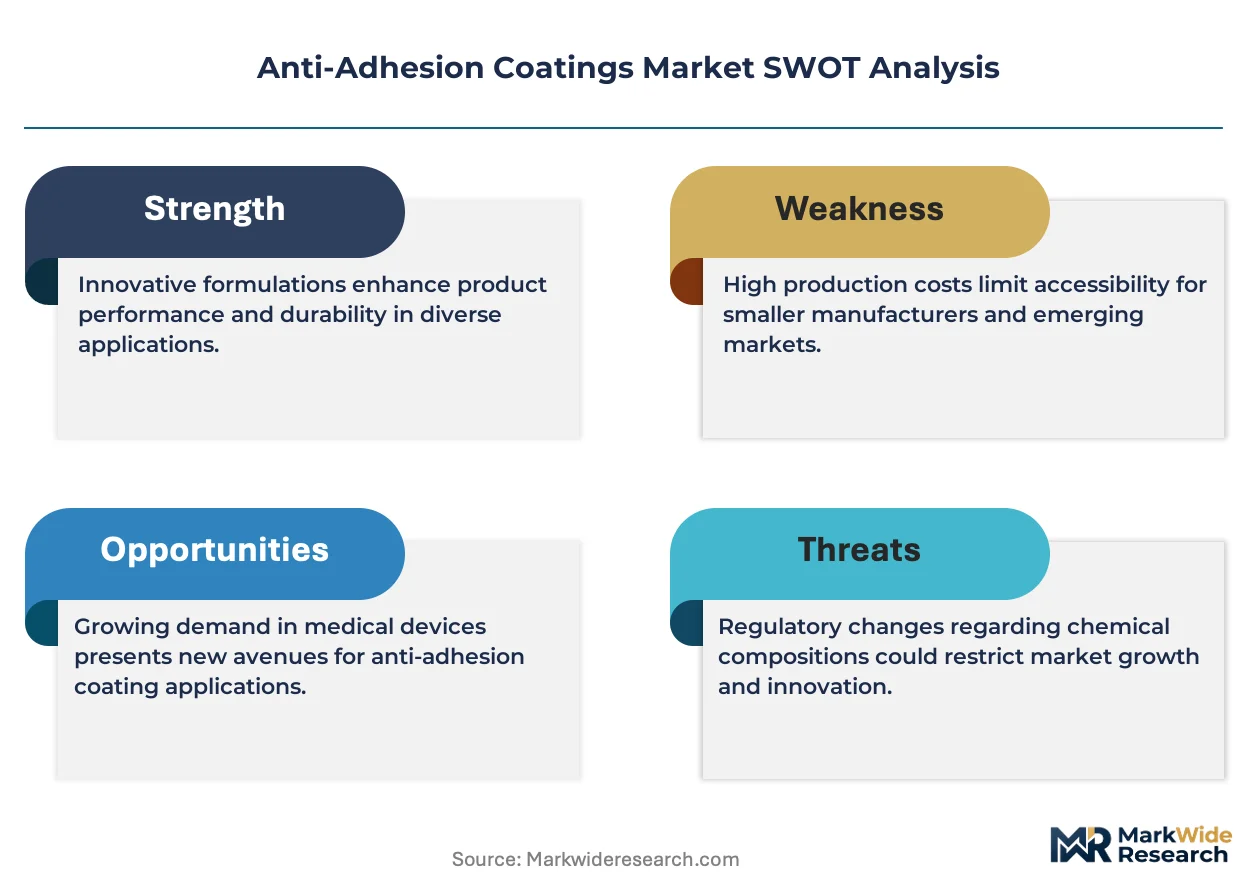
The performance gap between premium fluoropolymer formulations and commodity silicone alternatives is repositioning procurement criteria across industrial buyers. Dow Inc. leverages captive siloxane supply chains to anchor pricing power in medical-grade segments. PPG Industries competes through automotive OEM certifications that dominate North American coating specifications. Akzo Nobel differentiates via marine and industrial equipment channel control in European distribution networks.
Anti-adhesion coatings constitute thin-film surface treatments engineered to reduce frictional coefficients and prevent material buildup on substrates, typically applied through spray, dip, or plasma deposition processes at thicknesses ranging from sub-micron to several hundred microns depending on thermal load requirements. Their primary commercial purpose centers on extending equipment service intervals, reducing cleaning downtime, and enabling clean release in manufacturing operations. Liquid coatings occupy the largest volume share across industrial equipment applications where spray application infrastructure already exists, while solid films represent the fastest-expanding category in aerospace end-use segments where weight reduction and precise thickness control command margin premiums. Polymer-based formulations retain mature market status despite regulatory pressure, whereas ceramic material segments capture expanding specification share in high-temperature automotive and packaging machinery environments.
FDA biocompatibility requirements for medical device coatings and EPA restrictions on perfluorinated compound emissions jointly constrain formulation freedom and accelerate substitution R&D timelines. REACH authorization procedures under ECHA governance add European compliance layers that favor suppliers with established substance registration portfolios. Stakeholders must monitor evolving regulatory thresholds for persistent organic pollutants while building formulation flexibility into product development roadmaps.
Market Dynamics
REACH authorization procedures under ECHA governance are compressing formulation freedom for fluoropolymer suppliers while simultaneously accelerating R&D investment into silicone and ceramic substitutes across European manufacturing clusters.
Growth Catalysts
- FDA biocompatibility mandates:Medical device manufacturers in the United States are accelerating coating procurement to meet tightened 510(k) submission requirements for implantable instruments.
- Precision engineering clusters:Germany's automotive OEM tooling specifications for injection molding applications are driving volume demand for high-performance anti-adhesion layers.
- Plasma deposition advancement:Aerospace contractors are specifying solid film coatings processed through atmospheric plasma techniques to achieve sub-micron thickness control.
Market Restraints
- Fluoropolymer feedstock concentration:Virgin PTFE resin supply concentrates among three dominant chemical conglomerates, creating input cost volatility for formulated coating producers.
- Perfluorinated substance substitution timeline:REACH restrictions on PFAS compounds force European manufacturers to validate alternative chemistries against established performance baselines.
- Ceramic application infrastructure:Thermal spray equipment for ceramic coating deposition requires capital investment that mid-scale industrial buyers defer.
Strategic Opportunities
- Packaging machinery retrofit demand:Food processing equipment operators in France are specifying ceramic anti-adhesion layers to eliminate fluoropolymer contact surfaces.
- EU Green Deal alignment:The European Commission's sustainable chemistry incentives favor coating suppliers with bio-based formulation portfolios.
- Digital distribution platforms:Industrial coating procurement through specialized B2B marketplaces is reducing distributor margin capture in North American maintenance channels.
Industry Challenges
- Cross-functional formulation expertise:Coating developers must integrate surface chemistry, polymer science, and regulatory compliance capabilities that rarely coexist within single hiring pools.
- Multi-jurisdiction certification timelines:Simultaneous FDA 510(k), CE marking under MDR, and REACH registration processes extend product commercialization cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Adhesion Coatings Market |
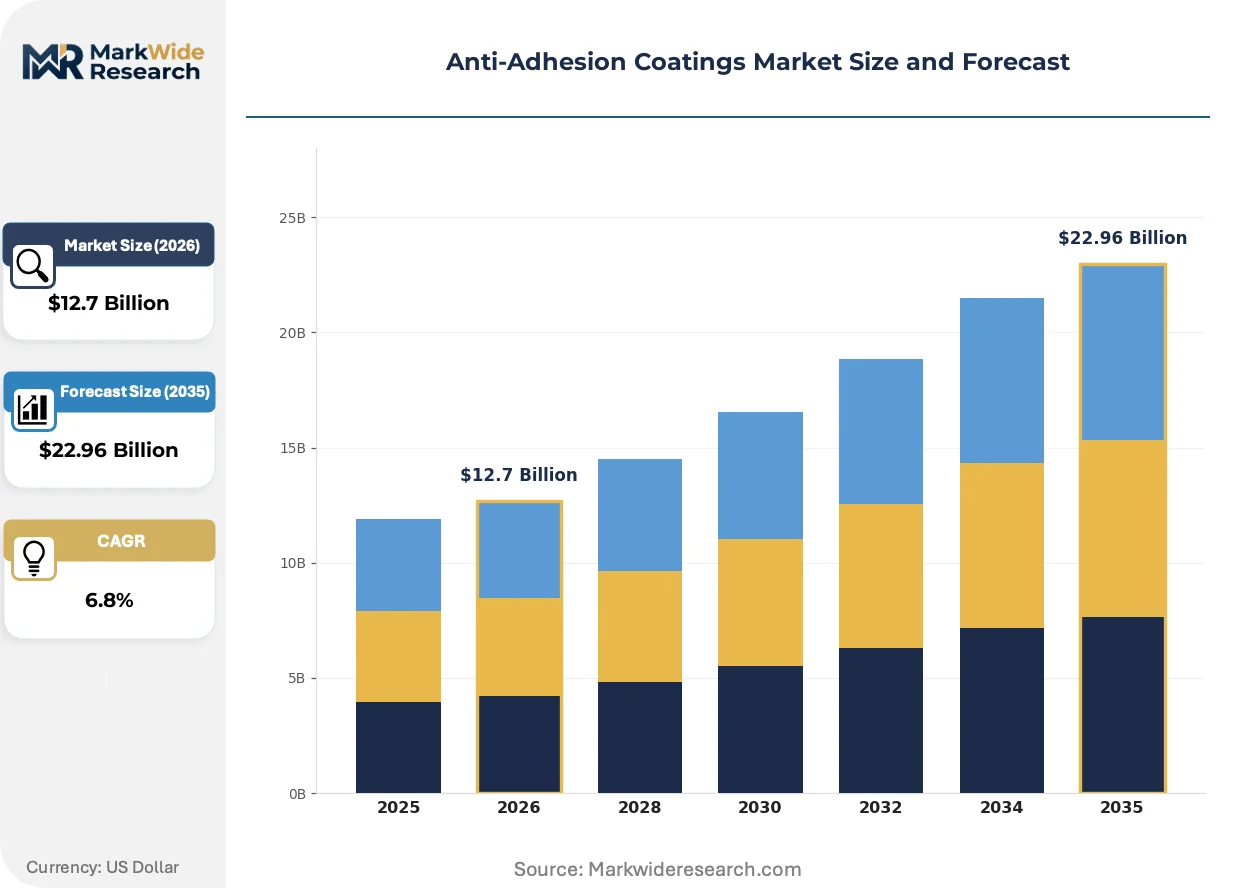
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $22.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Coatings, Solid Films, Aerosol Products, Gel Coatings End User: Aerospace, Automotive, Medical Devices, Home Appliances Application: Industrial Equipment, Consumer Electronics, Packaging, Construction Material: Polymers, Composites, Metals, Ceramics |
| Companies Covered | Dow Inc., PPG Industries, Inc., Akzo Nobel N.V., Henkel AG & Co. KGaA, Evonik Industries, Wacker Chemie AG, Shin-Etsu Chemical Co., Ltd., Momentive, EP Mineral, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Adhesion Coatings Market Evolving Landscape
Plasma-enhanced chemical vapor deposition techniques are consolidating technical specification control among aerospace and semiconductor equipment manufacturers who demand angstrom-level thickness precision.
Sol-gel ceramic formulations are consolidating market position in high-temperature automotive applications where exhaust system components exceed fluoropolymer thermal limits. Tier-one suppliers in Stuttgart and Wolfsburg are qualifying these coatings for turbocharger housings and EGR valves. The technology is consolidating specification share previously held by sprayed polymer alternatives.
EPA restrictions on perfluorinated compound emissions are forcing coating applicators to invest in thermal oxidizer systems or transition to waterborne silicone chemistries. Industrial finishers in Ohio and Michigan face compliance deadlines that compress capital allocation timelines. The regulatory pressure is concentrating service provider capacity among operators with existing air quality infrastructure.
Buyer concentration among medical device OEMs is compressing supplier negotiation leverage and accelerating volume-based pricing structures. Original equipment manufacturers with captive coating operations are vertically integrating formulation supply, displacing independent coating houses from specification development. This pattern concentrates most visibly in Minnesota and Massachusetts medical technology corridors.
Anti-Adhesion Coatings Market Segmentation
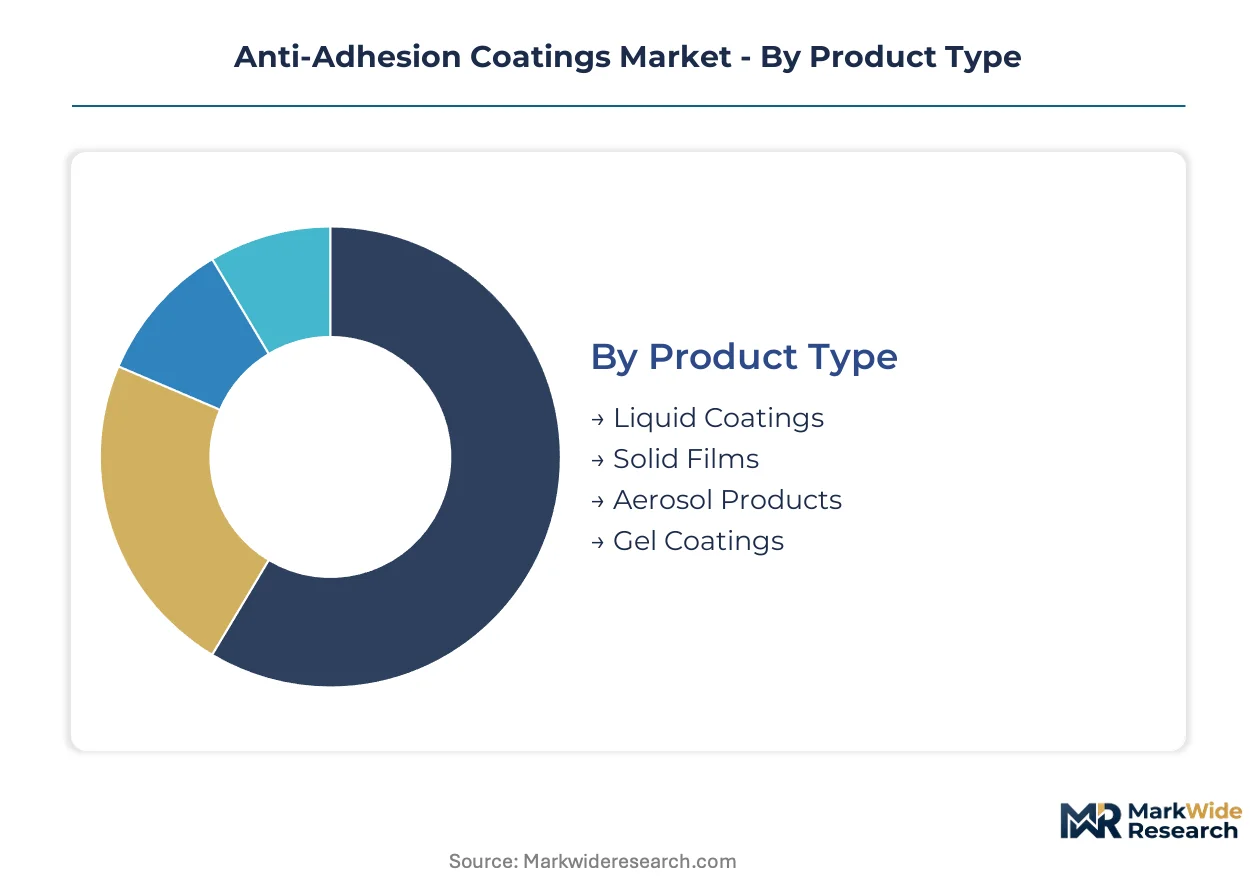
Anti-adhesion coatings serve fundamentally different performance requirements across medical implant surfaces, aerospace turbine components, and food processing equipment. Segmentation by product form, end-use industry, application environment, and base material determines which regulatory frameworks govern commercialization timelines and which technical specifications command price premiums.
Product Type:
FDA 510(k) submissions concentrate among liquid coating formulations for medical devices, while aerospace solid films require FAA airworthiness certifications. REACH registration obligations vary by carrier chemistry and volatile organic compound content.
- Liquid Coatings:Solvent-borne and waterborne formulations dominate industrial maintenance applications where spray equipment infrastructure already exists. Automotive OEMs in Stuttgart specify these layers for injection molding tooling to reduce cycle times and eliminate release agent residues.
- Solid Films:Pre-cured sheets and tapes processed through sintering or skiving deliver precise thickness control for aerospace component specifications. Plasma deposition techniques enable sub-micron application for semiconductor equipment manufacturers demanding angstrom-level uniformity.
- Aerosol Products:Field maintenance crews in packaging facilities favor portable application for emergency repairs and localized touch-ups on conveyor systems.
- Gel Coatings:Thixotropic formulations serve marine and industrial equipment operators requiring vertical surface adhesion without sagging during cure cycles.
Liquid coatings sit at the top of the volume ranking, with solid films climbing the fastest.
End User:
Cost tier stratification separates implant-grade medical specifications from commodity automotive applications, with aerospace and home appliances occupying intermediate positions.
- Aerospace:Solid film and ceramic formulations withstand turbine inlet temperatures exceeding fluoropolymer degradation thresholds. OEMs in Toulouse and Seattle specify these coatings for engine components and landing gear assemblies where weight reduction and thermal stability coexist as design imperatives.
- Automotive:Sol-gel ceramic alternatives displace sprayed polymers in exhaust system applications where EGR valves and turbocharger housings exceed thermal limits. Wolfsburg and Stuttgart engineering centers drive qualification protocols.
- Medical Devices:Silicone and fluoropolymer formulations face tightened FDA biocompatibility standards for implantable instruments. Minnesota and Massachusetts OEM corridors concentrate procurement volume.
- Home Appliances:Cookware and bakeware specifications favor commodity silicone coatings for consumer price points.
Automotive applications command the highest unit values, with aerospace expanding most quickly.
Application:
Customer type segmentation separates capital equipment OEMs from maintenance operators, with specification authority residing differently across each channel.
- Industrial Equipment:Injection molding platens, extrusion dies, and conveyor systems consume bulk volumes through distributor networks. German precision engineering clusters specify high-performance layers to extend service intervals.
- Consumer Electronics:Precision deposition requirements for semiconductor manufacturing equipment favor solid film and PECVD-processed coatings.
- Packaging:Food contact surfaces in France are transitioning to ceramic alternatives to eliminate fluoropolymer migration risks.
- Construction:Formwork and concrete placement equipment utilize commodity formulations where abrasion resistance outweighs release precision.
Industrial equipment captures the largest addressable base, with packaging gaining share fastest.
Material:
Supply concentration varies dramatically by chemistry, with virgin PTFE resin controlled by three chemical conglomerates while ceramic precursor markets fragment across regional suppliers.
- Polymers:Fluoropolymer and silicone formulations retain mature specification share despite REACH pressure on perfluorinated substances. Medical-grade silicone supply chains anchor Dow Inc.'s pricing power in implantable device segments.
- Ceramics:Alumina, zirconia, and sol-gel formulations capture expanding share in high-temperature automotive and packaging machinery where thermal limits exclude organic alternatives.
- Composites:Polymer-ceramic hybrid layers balance release performance with mechanical durability for mid-temperature industrial applications.
- Metals:Hard chrome and thermal spray alternatives serve heavy equipment operators prioritizing abrasion resistance over release coefficient optimization.
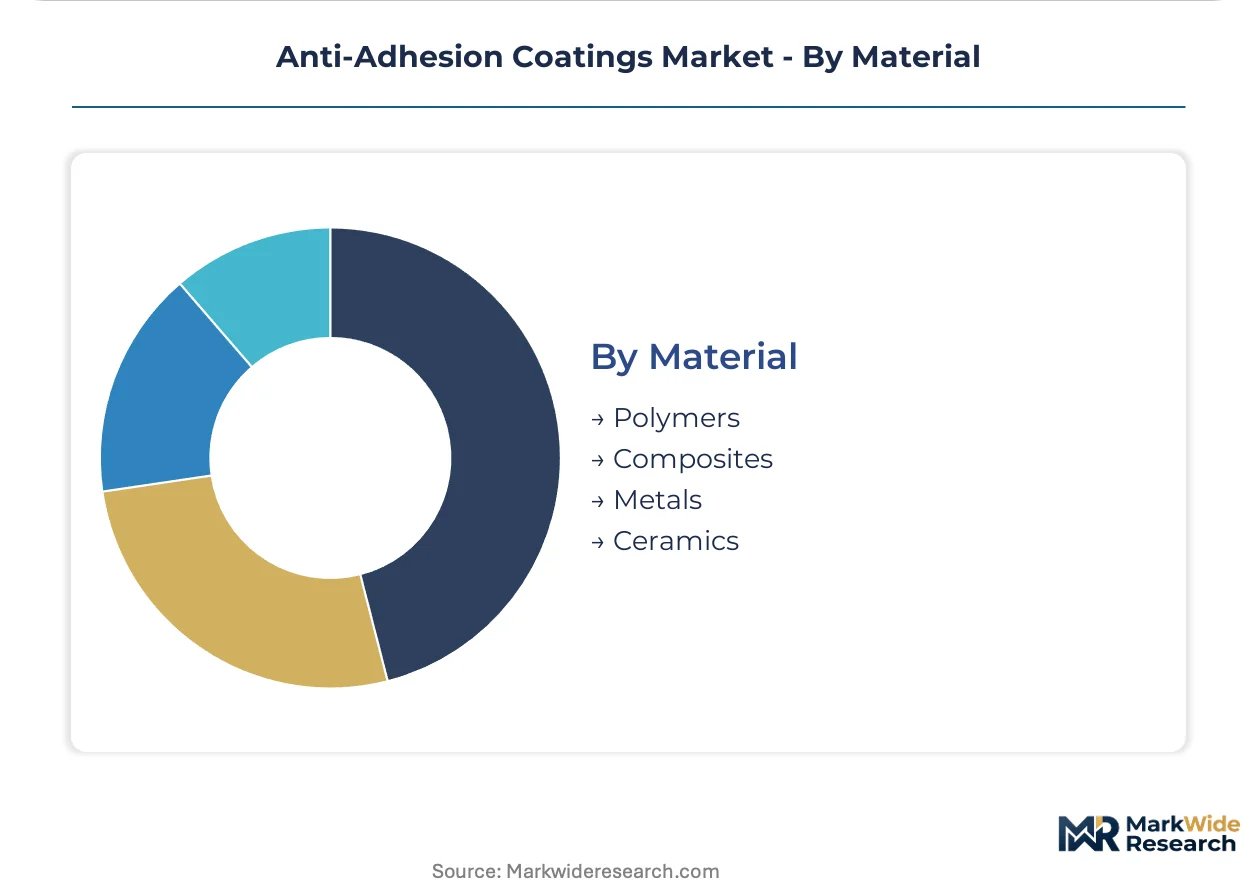
Polymers retain volume leadership, with ceramics showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision engineering clusters command premium specification authority for automotive tooling applications, while the United States concentrates medical device coating procurement under tightened FDA biocompatibility mandates.
United States
Minnesota and Massachusetts medical technology corridors drive implantable device coating procurement as FDA 510(k) submission requirements tighten for fluoropolymer and silicone formulations. EPA restrictions on perfluorinated compound emissions compress capital allocation timelines for industrial finishers in Ohio and Michigan. Aerospace contractors in Seattle specify solid film coatings through atmospheric plasma deposition for turbine components.
Germany
Automotive OEMs in Stuttgart and Wolfsburg qualify sol-gel ceramic alternatives for turbocharger housings and EGR valves exceeding fluoropolymer thermal limits. REACH authorization procedures under ECHA governance accelerate R&D investment into silicone substitutes across European manufacturing clusters. Precision engineering specifications for injection molding tooling anchor volume demand for high-performance anti-adhesion layers.
China
Semiconductor equipment manufacturers in the Yangtze River Delta specify plasma-enhanced chemical vapor deposition coatings demanding angstrom-level thickness precision. NMPA biocompatibility standards for medical devices tighten formulation requirements for implantable instruments. Packaging machinery producers in the Pearl River Delta retrofit ceramic anti-adhesion layers to eliminate fluoropolymer contact surfaces.
France
Food processing equipment operators specify ceramic anti-adhesion layers to eliminate fluoropolymer migration risks under EU Green Deal sustainable chemistry incentives. ANSM oversight of medical device coatings adds national compliance layers beyond CE marking requirements. Industrial equipment maintenance channels in Île-de-France consolidate procurement through specialized B2B distribution platforms.
Japan
Shin-Etsu Chemical's captive siloxane supply chains anchor pricing power in medical-grade silicone segments across domestic implantable device markets. METI industrial standards for high-temperature automotive applications favor ceramic formulations in exhaust system components. Precision deposition requirements from semiconductor equipment manufacturers in the Tokyo region drive solid film coating specifications.
Anti-Adhesion Coatings Market Competitive Landscape
Top-tier vendors anchor premium medical and aerospace specifications, while mid-scale formulated coating producers compete on volume pricing for industrial maintenance applications. Three chemical conglomerates control virgin PTFE resin supply, concentrating input cost leverage upstream. Strategic archetypes separate siloxane-integrated suppliers, automotive OEM certification holders, and marine distribution network controllers. Competitive moves concentrate on backward integration into precursor supply and geographic expansion through regional formulation facilities.
Among North American chemical conglomerates, Dow Inc. exemplifies siloxane-integrated supply chain control, while PPG Industries occupies a position within automotive OEM certification tiers. Akzo Nobel N.V. represents European distribution network anchoring in marine and industrial equipment channels. These three entities collectively illustrate the strategic segmentation between medical-grade pricing power, automotive specification authority, and regional channel control.
| Leading Market Players |
|---|
| Dow Inc. |
| PPG Industries, Inc. |
| Akzo Nobel N.V. |
| Henkel AG & Co. KGaA |
| Evonik Industries |
| Wacker Chemie AG |
| Shin-Etsu Chemical Co., Ltd. |
| Momentive |
| EP Mineral |
| Others |
Value Network & Pricing Analysis
Formulation chemists with plasma deposition expertise concentrate in Stuttgart and Wolfsburg engineering corridors, creating labor-cost differentials that widen pricing-tier spreads between commodity silicone applicators and precision ceramic specialists serving automotive OEMs.
Pricing Analysis
Application service bundling separates coating procurement from standalone material supply across industrial maintenance channels. Three-tier pricing structure across implant-grade, automotive-certified, and economy industrial levels reflects FDA 510(k) pathway costs versus commodity spray applications. Price differentiation hinges on thermal stability certification and volume commitment scale. Mid-scale industrial buyers exhibit highest price sensitivity as capital deferral pressures intensify against REACH compliance investment requirements.
Supply Chain Analysis
Dual-sourcing mandates from medical device OEMs in Minnesota and Massachusetts force coating houses to qualify secondary silicone suppliers alongside primary fluoropolyder formulations. Virgin PTFE resin concentrates among three chemical conglomerates in the United States, Germany, and Japan while ceramic precursor markets fragment across regional Chinese and European suppliers. Raw material dependencies rest on siloxane monomers, alumina nanopowders, and fluorinated feedstocks. Single-source vulnerability in medical-grade silicone channels threatens formulation continuity. Distribution runs through specialized B2B platforms consolidating North American maintenance procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Anti-Adhesion Coatings Market functions as a stable compounder where regulatory substitution mandates for perfluorinated substances generate sustained R&D reinvestment cycles across formulation suppliers.
For Market Incumbents: Hedge fluoropolymer exposure by accelerating silicone and ceramic formulation portfolios before REACH authorization deadlines compress viable chemistry options. Secure captive siloxane supply through backward integration into precursor production or long-term offtake agreements with Shin-Etsu Chemical and Dow Inc. Channel control in German precision engineering clusters defends pricing power against emerging ceramic specialists. For New Entrants and Emerging Players: Packaging machinery operators in France represent an underserved buyer archetype seeking ceramic alternatives to eliminate fluoropolyder migration risks under EU Green Deal incentives. Target food processing equipment retrofit demand through direct technical sales teams bypassing incumbent distributor networks. Sol-gel ceramic qualification protocols at Wolfsburg engineering centers offer the most penetrable entry path for high-temperature automotive specifications. For Investors and Strategic Acquirers: Chemical conglomerates with captive feedstock positions are the most active acquirers in this space, consolidating formulated coating houses to secure downstream specification control. Five-to-ten year viability favors suppliers with dual polymer-ceramic portfolios navigating regulatory transition windows. Monitor ECHA substance authorization timelines as the critical inflection signal for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Precursors | Dow Inc. and Wacker Chemie anchor medical-grade pricing power through captive monomer supply. |
| Ceramic Formulation Qualification | Sol-gel alternatives at Stuttgart OEMs displace sprayed polymers in exhaust system applications exceeding thermal limits. |
| REACH Registration Portfolio Expansion | ECHA compliance layers favor suppliers with established substance dossiers across silicone and ceramic chemistries. |
| Plasma Deposition Capability Buildout | Aerospace contractors in Seattle specify PECVD-processed solid films demanding angstrom-level thickness precision. |
| Digital Distribution Platform Partnership | Specialized B2B marketplaces reduce distributor margin capture in North American industrial maintenance channels. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with coating formulators, automotive OEM procurement teams, medical device regulatory affairs leads, and industrial maintenance directors combined with secondary validation from ECHA substance databases, FDA 510(k) filings, and customs trade records. Triangulation across stakeholder inputs and documentary sources ensures cross-verified demand estimates.
Historical trendline analysis across the projection horizon establishes baseline growth patterns before applying segment-specific adjustment factors. Segmentation dimensions span product form, end-use industry, base material chemistry, and regional regulatory cluster. CAGRs derive from fitted growth curves incorporating REACH substitution timelines, FDA biocompatibility mandate phase-ins, and automotive thermal specification evolution. Forecast inputs include medical device OEM procurement cycles and aerospace contractor qualification protocols.
Underlying measurement precision varies by segment; medical device and aerospace specifications carry tighter precision than commodity industrial maintenance applications. Forecasts reflect assumptions about regulatory enforcement intensity and substitution technology maturation. Deviation in ECHA authorization timelines or EPA perfluorinated compound emission thresholds would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Smart Coating Market
Coatings
Marine Nanocoating Market
Coatings
Germany Protective Coatings Market
Coatings
Europe Thermal Spray Market
Coatings
Coatings Raw Materials Market
Coatings
Canada Protective Coatings Market
Coatings
Global Fluorine Carbon Coatings Market
Coatings
Global Low Friction Coatings Market
Coatings
Global Low Temperature Powder Coatings Market
Coatings
High Performance Coatings Market
Coatings
US Antifouling Yacht Coatings Market
Coatings
South Korea Automotive OEM Coatings Market
Coatings
High Temperature Coatings Market
Coatings
Global Fireproofing Coatings for Wood Market
Coatings
Polyurethane Powder Coatings Market
Coatings
North America Coil Coatings Market