
 Prefab Iron Market | 2026-2036
Prefab Iron Market Size, Share, and Industry Trends Forecast 2026-2036
Prefab Iron Market Analytics
The EU Green Deal is expanding embodied carbon disclosure requirements for construction materials across member states, compelling prefab iron suppliers to certify lifecycle emissions. Butler Manufacturing Company leverages its captive steel supply chain to control input costs and delivery timelines. Nucor Building Systems sustains its position through electric-arc-furnace steelmaking that aligns with low-carbon procurement mandates. BlueScope Buildings North America anchors its competitiveness via proprietary connection systems that reduce on-site labor intensity.
Prefab iron comprises structural steel elements fabricated off-site under controlled conditions, typically using ASTM A992 or equivalent grade steel with specified yield strengths of 345-450 MPa, then transported for rapid assembly into building frames or infrastructure supports. Steel frames dominate current volume flows due to their established engineering codes and contractor familiarity, while modular components represent the fastest-expanding category as developers pursue factory-finished volumetric units that compress project schedules. Reinforced beams command premium positioning in seismic zones where ductility requirements elevate specification grades and testing protocols.
EMA's construction product oversight under the CPR framework, EPA stormwater regulations affecting site-based fabrication, and ISO 3834 welding quality standards collectively shape market access and product liability exposure for prefab iron manufacturers. India's BIS certification for structural steel and China's GB standards for prefabricated construction add compliance layers for cross-border suppliers. Stakeholders must monitor evolving carbon border adjustments and local content thresholds that will determine which production geographies retain cost-competitive access to major demand centers.
Market Dynamics
The EU Green Deal's embodied carbon disclosure requirements are forcing prefab iron suppliers to reconfigure supply chains and certify lifecycle emissions, compressing margins for uncertified producers while rewarding low-carbon steelmaking investments.
Growth Catalysts
- PMAY-Urban procurement mandates:India's urban housing initiative drives modular construction adoption across metropolitan corridors, creating guaranteed offtake for factory-finished volumetric units.
- Electric-arc-furnace alignment:Low-carbon steelmaking methods satisfy emerging procurement clauses in EU public construction tenders, opening preferential access channels.
- Seismic zone ductility upgrades:Reinforced beam specifications in earthquake-prone regions elevate testing protocols and grade requirements, expanding premium product categories.
Market Restraints
- Scrap steel price volatility:Input cost swings for recycled feedstock compress margins for electric-arc-furnace producers during commodity spikes.
- Chinese GB standards compliance:Cross-border suppliers face layered certification requirements for prefabricated construction exports to Chinese markets.
- Concrete substitution in low-rise:Cast-in-place methods retain cost advantages for single-story industrial builds in markets with abundant labor.
Strategic Opportunities
- German affordable housing acceleration:Residential developers in key cities are expanding prefab iron procurement for cost-controlled municipal projects.
- Carbon border adjustment positioning:Early certification under EU mechanisms creates defensive moats against tariff exposure for low-emission producers.
- BIM-to-fabrication integration:Digital modeling convergence with automated cutting and welding compresses engineering-to-delivery timelines.
Industry Challenges
- ISO 3834 welding certification timelines:Quality standard compliance creates bottlenecks for suppliers expanding into regulated European markets.
- On-site integration complexity:Legacy construction workflows resist adaptation to just-in-time steel frame delivery, requiring contractor retraining investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prefab Iron Market |
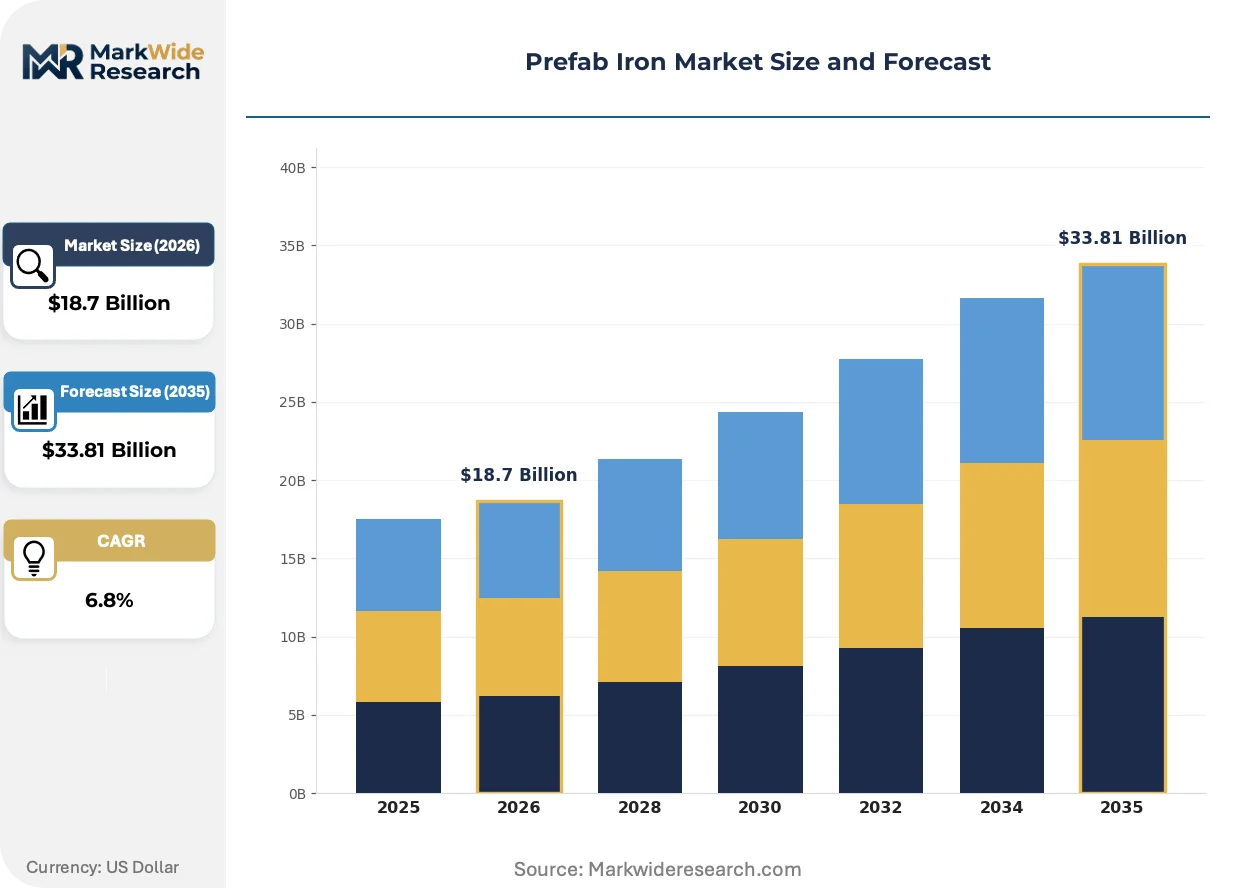
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Frames, Modular Components, Prefabricated Panels, Reinforced Beams End User: Construction Firms, Residential Developers, Industrial Manufacturers, Retail Builders Application: Residential Buildings, Commercial Structures, Infrastructure Projects, Temporary Installations Distribution Channel: Direct Sales, Online Retail, Wholesale Distributors, Construction Suppliers |
| Companies Covered | Abtech, Inc., Algeco Scotsman, Astron Buildings, Butler Manufacturing Company, Kirby Building Systems LLC, Nucor Building Systems, Schulte Building Systems, Inc., BlueScope Buildings North America, Cornerstone Building Brands, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prefab Iron Market Evolving Landscape
Digital fabrication and regulatory carbon accounting are converging to reshape how prefab iron moves from mill to building site, with implications for supplier qualification and buyer procurement criteria.
Advanced robotic welding systems is modularizing connection fabrication for high-rise structural frames, allowing developers in Indian urban corridors to compress erection schedules by half. Commercial contractors are adopting these systems fastest where labor shortages intersect with compressed project timelines. The technology is modularizing what was previously site-intensive assembly work into factory-controlled precision operations.
EMA construction product oversight under the CPR framework is expanding technical documentation requirements for structural steel imports, forcing non-EU suppliers to establish notified body relationships. Manufacturers must now maintain factory production control audits and performance declarations to retain market access. Prefab beam suppliers from Turkey and India are responding by acquiring CE marking capabilities ahead of border enforcement tightening.
Buyers are consolidating procurement around turnkey design-build contracts that bundle engineering, fabrication, and erection into single-source accountability. General contractors in German residential markets are displacing fragmented subcontractor arrangements with integrated supplier partnerships. This consolidation is most visible in affordable housing segments where schedule risk transfer outweighs first-cost optimization.
Prefab Iron Market Segmentation
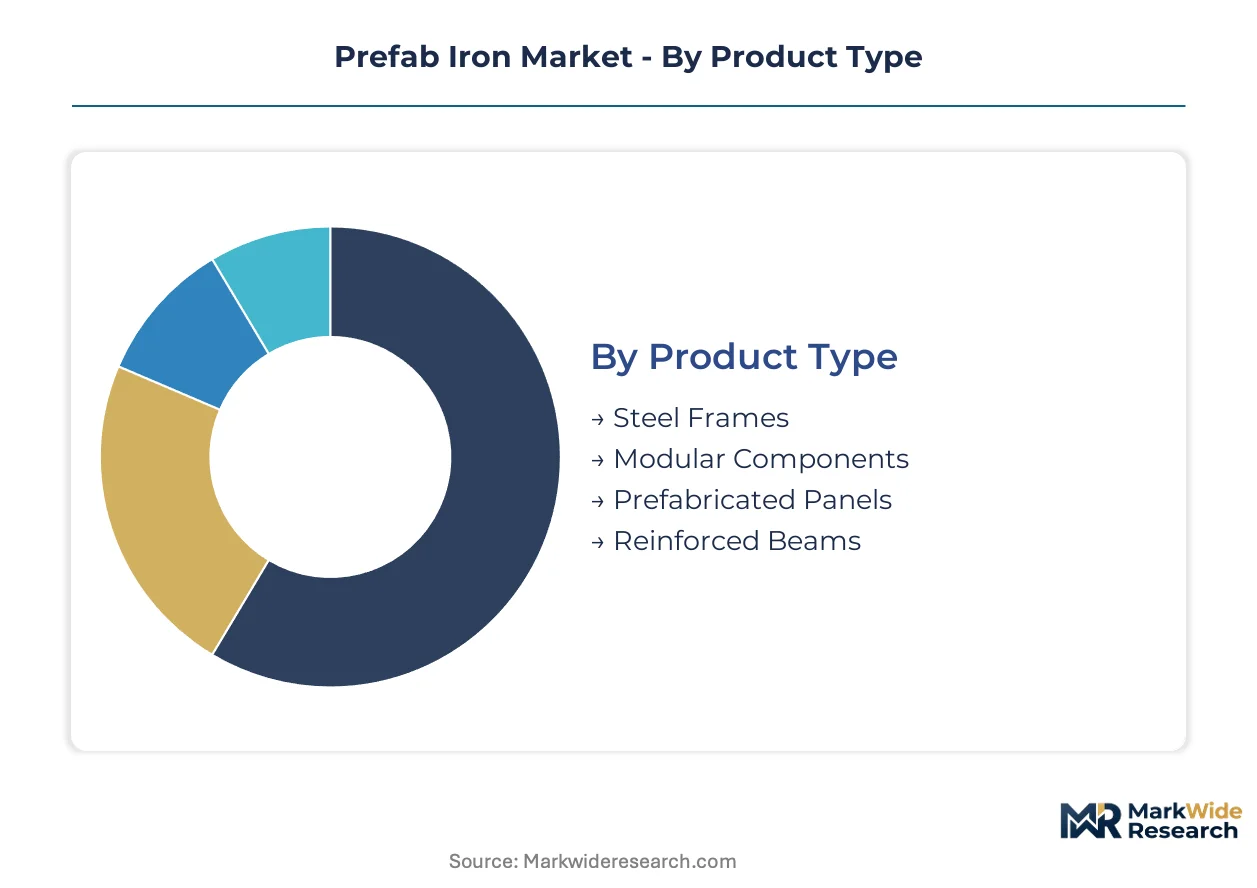
Prefab iron segmentation reveals how specification-grade requirements diverge across project types and procurement channels. Understanding these fault lines helps suppliers align certification investments with where margin pools concentrate.
Product Type:
Upgrade cycles vary dramatically across structural systems, with seismic code revisions and carbon disclosure mandates forcing replacement decisions on different timelines.
- Steel Frames:ASTM A992-grade structural elements with 345-450 MPa yield strengths dominate current procurement volumes. German residential developers specify these for affordable housing projects where established engineering codes reduce permitting friction.
- Modular Components:Factory-finished volumetric units integrate MEP rough-ins and interior finishes before site delivery. India's PMAY-Urban initiative drives procurement across metropolitan corridors where schedule compression outweighs first-cost premiums.
- Prefabricated Panels:Envelope systems combining structural skins with insulation layers. EU Green Deal embodied carbon benchmarks are reshaping material specifications for these assemblies.
- Reinforced Beams:Ductility-enhanced sections for seismic zones. Earthquake-prone regions elevate testing protocols and grade requirements, expanding premium positioning for certified producers.
Steel frames sit at the top of the volume ranking, with modular components climbing the fastest.
End User:
Customer sophistication tiers separate specification authority from pure procurement execution, with design-build consolidation blurring traditional boundaries.
- Construction Firms:General contractors managing turnkey projects bundle engineering, fabrication, and erection into single-source accountability. German markets show fastest consolidation here.
- Residential Developers:Municipal affordable housing specialists in Berlin and Munich accelerate prefab iron adoption for cost-controlled projects with fixed completion deadlines.
- Industrial Manufacturers:Warehouse and logistics facility builders seeking rapid enclosure. These buyers prioritize connection speed over architectural flexibility.
- Retail Builders:Big-box and quick-service restaurant developers with repeatable prototype designs. Standardized footprints allow maximum factory pre-assembly.
Construction firms command the largest procurement scale, though residential developers are expanding their share fastest as municipal mandates harden.
Application:
Project duration and permanence expectations create divergent performance specifications across use cases.
- Residential Buildings:Multi-family mid-rise structures in urban corridors. India's PMAY-Urban initiative guarantees offtake for volumetric suppliers meeting BIS certification requirements.
- Commercial Structures:Office and retail frames where open-span flexibility drives bay spacing decisions. Seismic zone projects command premium ductility grades.
- Infrastructure Projects:Bridges, transit facilities, and utility supports with century-scale design lives. These applications enforce the strictest welding protocol compliance under ISO 3834.
- Temporary Installations:Event structures and emergency housing with reuse requirements. Lower specification grades acceptable where disassembly cycles predominate.
Infrastructure projects anchor the premium tier by specification intensity, while residential buildings generate the steepest expansion trajectory.
Distribution Channel:
Channel economics reflect how much engineering risk intermediaries absorb versus pass through to end buyers.
- Direct Sales:Fabricator-to-contractor relationships for complex structural frames. Butler Manufacturing leverages captive steel supply chains to control input costs and delivery timelines through this channel.
- Online Retail:Standardized connection hardware and small-batch structural elements. Growing fastest for maintenance, repair, and operations procurement.
- Wholesale Distributors:Regional inventory positions for commodity-grade beams and columns. These intermediaries buffer lead time volatility for smaller contractors.
- Construction Suppliers:Integrated material yards bundling prefab iron with concrete, lumber, and finishing systems. Single-source convenience trades off against specification control.
Direct sales maintains the highest margin capture, with online retail gaining share fastest among fragmented buyer bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prefab iron manufacturing originated in the industrial Midwest of the United States during the early twentieth century, where standardized steel framing systems first displaced traditional timber construction for commercial and agricultural buildings. The technology spread through European reconstruction programs and post-colonial infrastructure development, establishing production footprints that persist in today's regional specialization patterns.
United States
Industrial warehouse construction and data center expansion drive specification-grade steel demand across Texas, Arizona, and Nevada. EPA stormwater regulations constrain site-based fabrication, pushing production toward controlled factory environments. The Dallas-Fort Worth metroplex anchors the largest concentration of structural steel fabricators serving southwestern commercial markets.
Germany
Residential developers in Berlin, Munich, and Hamburg accelerate prefab iron procurement for cost-controlled municipal affordable housing with fixed completion deadlines. The EU Green Deal's embodied carbon disclosure requirements compel suppliers to certify lifecycle emissions through notified body relationships. The Ruhr industrial corridor retains legacy steelmaking capacity now converting to electric-arc-furnace production.
India
The PMAY-Urban initiative guarantees offtake for volumetric modular units across Delhi-Mumbai, Bangalore-Chennai, and Hyderabad-Pune corridors. BIS certification for structural steel creates compliance layers for cross-border suppliers entering these metropolitan markets. Gujarat's Special Investment Regions attract prefab component manufacturing through streamlined land allocation and port access.
China
GB standards for prefabricated construction enforce layered certification requirements that domestic producers navigate more efficiently than foreign entrants. Dual carbon goals are reshaping material specifications for public infrastructure tenders in the Yangtze River Delta. Shanghai's Lingang New Area hosts integrated steel-fabrication-assembly complexes serving East Asian export markets.
United Arab Emirates
Expo legacy projects and logistics free zone expansion sustain demand for rapid-enclosure steel systems in Dubai and Abu Dhabi. Local content thresholds in government procurement favor regional fabrication facilities over direct mill imports. Jebel Ali Industrial Zone concentrates coating, cutting, and welding operations serving Gulf Cooperation Council construction markets.
Prefab Iron Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a market structure that rewards captive steel supply and vertical control over fabrication workflows. The supplier base separates into integrated mill-fabricator combinations, independent regional fabricators, and turnkey design-build operators. Strategic positioning concentrates on electric-arc-furnace steelmaking investments, automated welding system deployment, and BIM-to-fabrication digital integration. Consolidation pressures favor players with in-house production of structural connections and proprietary erection methodologies.
Among North American integrated producers, Butler Manufacturing Company and Nucor Building Systems exemplify the mill-captive archetype that controls input costs through backward integration into steelmaking. BlueScope Buildings North America occupies a position within the premium engineering tier where proprietary connection systems reduce field labor intensity. These three anchors illustrate how competitive advantage flows from supply chain control rather than fabrication scale alone.
| Leading Market Players |
|---|
| Abtech, Inc. |
| Algeco Scotsman |
| Astron Buildings |
| Butler Manufacturing Company |
| Kirby Building Systems LLC |
| Nucor Building Systems |
| Schulte Building Systems, Inc. |
| BlueScope Buildings North America |
| Cornerstone Building Brands, Inc. |
| Others |
Value Network & Pricing Analysis
Electric-arc-furnace conversion across the Ruhr corridor and American Midwest is simultaneously compressing carbon-adjusted production costs and concentrating supply among mill-captive fabricators with backward integration into steelmaking. This method shift rewards producers controlling scrap supply and renewable energy offtake while marginalizing traditional blast-furnace-dependent competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified low-carbon structural systems from commodity-grade alternatives. Price differentiation centers on ISO 3834 welding certification and EU Green Deal embodied carbon disclosure tiers. Pricing pressure stems from scrap steel volatility feeding electric-arc-furnace input costs. Residential developers under PMAY-Urban mandates exhibit highest price sensitivity, while infrastructure contractors with century-scale design lives accept premium positioning.
Supply Chain Analysis
Workforce availability constraints in Gujarat's Special Investment Regions and the Dallas-Fort Worth metroplex are forcing automation investments that reshape supplier economics. Supply concentrates in India, Germany, and the United States where port access and inland fabrication clusters align. Raw material flows draw from scrap recycling networks, ASTM A992-grade steel mills, and coating chemical suppliers. Single-source vulnerability runs through concentrated electric-arc-furnace electrode supply. Distribution runs through direct fabricator-to-contractor relationships for complex frames, with wholesale distributors buffering smaller contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The prefab iron market functions as a regulatory compounder where EU Green Deal embodied carbon disclosure mandates and India's PMAY-Urban procurement guarantees create dual demand engines with divergent compliance requirements.
For Market Incumbents: Extend certification capabilities ahead of carbon border adjustment enforcement to defend against tariff-exposed imports from uncertified producers. Prioritize captive steel supply chain investments in electric-arc-furnace capacity to control input cost volatility. Deepen BIM-to-fabrication integration to compress engineering-to-delivery timelines and lock in design-build contractor relationships. For New Entrants and Emerging Players: Robotic welding system deployment offers a technology-first wedge into Indian metropolitan corridors where labor shortages intersect with PMAY-Urban schedule compression mandates. Target modular component manufacturing in Gujarat's Special Investment Regions where streamlined land allocation reduces capital intensity. Pursue turnkey design-build partnerships with German municipal affordable housing developers seeking single-source accountability. For Investors and Strategic Acquirers: Roll-up economics work for regional fabricators with ISO 3834 capabilities because EU market access barriers create defensive moats against price competition. The 5-10 year viability window favors electric-arc-furnace-aligned producers over blast-furnace legacy assets. Watch carbon border adjustment implementation timelines as the inflection signal separating certified premium positioning from commodity margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Electric-Arc-Furnace Capacity Expansion | Aligns steelmaking with EU Green Deal low-carbon procurement mandates and carbon border adjustment positioning. |
| ISO 3834 Welding Certification Investment | Unlocks European market access under EMA construction product oversight and CPR framework requirements. |
| BIM-to-Fabrication Digital Integration | Compresses engineering-to-delivery timelines for Indian PMAY-Urban volumetric unit procurement. |
| Backward Integration into Scrap Supply | Buffers margin volatility from commodity price swings in recycled steel feedstock markets. |
| Turnkey Design-Build Partnership Formation | Consolidates German residential developer procurement around single-source accountability structures. |
Research Methodology
Multiple input streams — primary interviews with structural steel fabricators, EPC contractors, and municipal procurement officers; secondary validation through BIS certification databases, EU CPR framework documentation, and customs trade records; plus SEC filings from integrated mill-fabricator combinations — were reconciled through bottom-up and top-down triangulation to establish market sizing and growth trajectory parameters.
Historical shipment volumes were cross-referenced against panel input from industry participants to anchor projections across the analysis window. Segmentation modeling incorporated product type, end user archetype, application permanence expectations, and distribution channel economics. CAGRs were derived from demand elasticity analysis against PMAY-Urban offtake guarantees and EU public tender low-carbon procurement clause adoption curves.
The model holds under sustained regulatory enforcement of embodied carbon disclosure; deviation in carbon border adjustment implementation timelines or scrap steel price volatility spikes would shift competitive positioning and margin trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Global Artificial Rutile Market
Metals & Minerals
Gold Recycling Market
Metals & Minerals
Hot Briquetted Iron (HBI) Market
Metals & Minerals
Rare Earth Elements Market
Metals & Minerals
Manganese Mining Market
Metals & Minerals
Steel Powder Market
Metals & Minerals
Solder Materials Market
Metals & Minerals
India CRNO Steel Lamination Market
Metals & Minerals
Garnet Market
Metals & Minerals
Bauxite Mining Market
Metals & Minerals
Global Boron Market
Metals & Minerals
Ilmenite Market
Metals & Minerals
Recycled Scrap Metal Market
Metals & Minerals
Cobalt Sulphate Market
Metals & Minerals
Zinc Sulphate Market
Metals & Minerals
Global Ferrous Scrap Recycling Market