
 Colored Gemstones Market | 2026-2036
Colored Gemstones Market Size, Share, and Industry Trends Forecast 2026-2036
Colored Gemstones Market Analysis
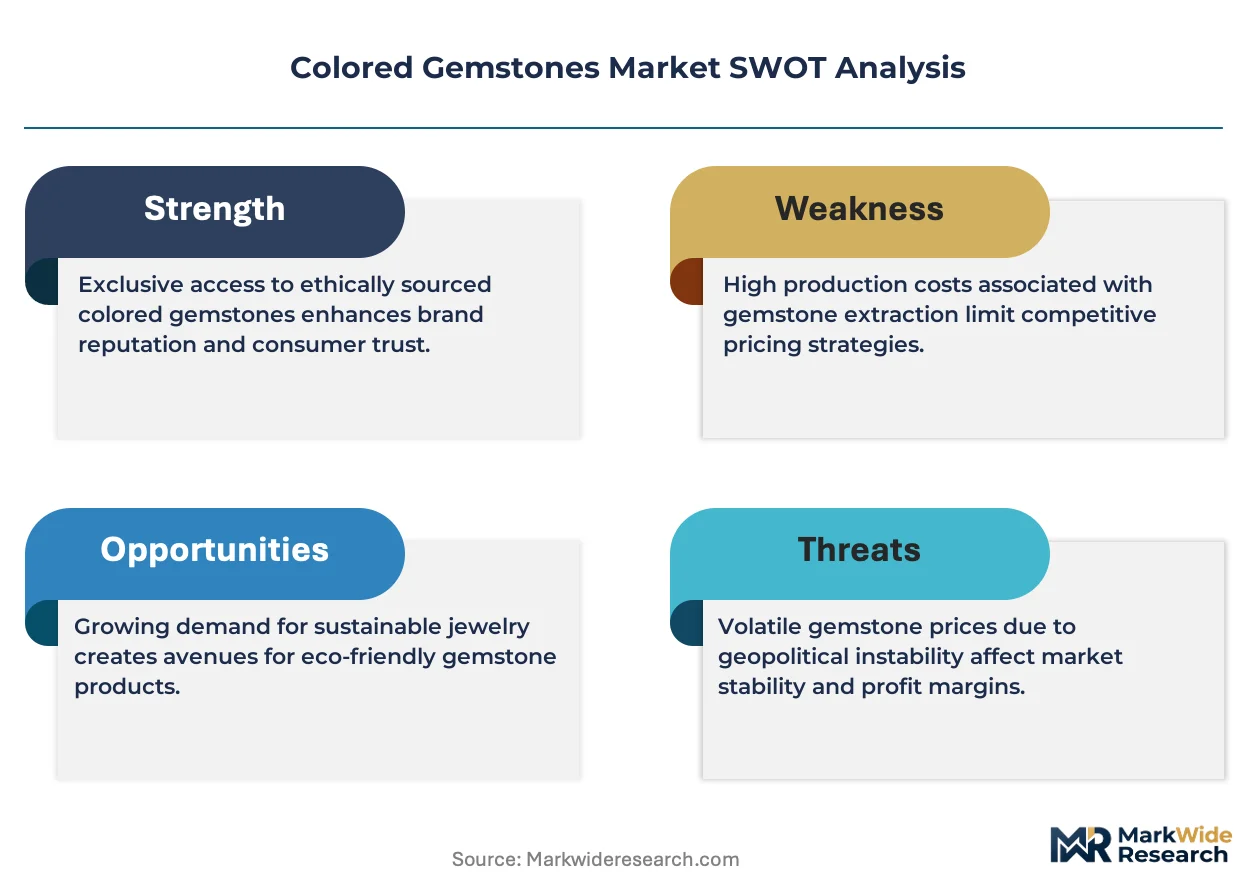
Luxury collectors and high-net-worth individuals are unwinding long-held preferences for diamond-centric portfolios, rotating capital into rare rubies, sapphires, and emeralds as alternative stores of value. Gemfields Group Limited leverages its Montepuez ruby mine in Mozambique to control premium rough supply from extraction to auction. Fura Gems Inc. anchors its growth strategy on Colombian emerald assets and Australian sapphire operations. Tiffany & Co. differentiates through vertically integrated provenance programs that trace stones from mine to retail counter.
Colored gemstones constitute naturally occurring mineral crystals prized for hue, saturation, clarity, and durability, with corundum-based rubies and sapphires ranking nine on the Mohs hardness scale and beryl-based emeralds ranking seven and a half to eight. These stones serve primarily as ornamental assets in fine jewelry, investment vehicles for wealth preservation, and cultural artifacts in ceremonial and heirloom contexts. Ruby and sapphire product categories dominate auction turnover and per-carat pricing records, while emerald segments face structural supply constraints from depleting Colombian deposits and rising African competition. Faceted form output commands the deepest margin pools due to precision cutting labor intensity and light-performance premiums, though rough stone trading sustains volume leadership in wholesale channels.
The Kimberley Process Certification Scheme, EU Conflict Minerals Regulation, and US Federal Trade Commission jewelry guides collectively enforce traceability, disclosure, and ethical extraction standards that shape market access and consumer trust. Thailand's Department of Mineral Resources and gemstone testing laboratories in Bangkok enforce export certification protocols that influence regional trade flows. Stakeholders must monitor tightening due diligence timelines and evolving synthetic disclosure rules that will determine competitive positioning in transparency-sensitive buyer segments.
Market Dynamics
Capital rotation from diamond portfolios into rare colored stones is compressing auction cycles and forcing upstream consolidation as miners seek direct-to-collector channels. Bangkok's cutting cluster now intermediates over half of global corundum processing, creating chokepoint vulnerability.
Growth Catalysts
- EU Conflict Minerals Regulation:Mandatory supply chain due diligence is filtering out non-compliant rough traders and concentrating volume among certified auction houses.
- Thai gemstone testing protocols:Bangkok's Department of Mineral Resources export certification has become a de facto quality passport for Southeast Asian origin stones.
- Mohs hardness premium:Corundum's nine-point rating enables everyday wearable jewelry designs that expand addressable occasions beyond ceremonial use.
Market Restraints
- Colombian emerald depletion:Muzo and Chivor deposit exhaustion is forcing cutters to absorb higher African rough prices or downgrade clarity standards.
- Single-cluster processing risk:Thailand's dominance in precision faceting creates geographic concentration exposure for auction liquidity.
- Synthetic corundum substitution:Lab-grown ruby and sapphire from hydrothermal producers is capturing price-sensitive bridal segments.
Strategic Opportunities
- Indian bridal market penetration:Untapped demand for untreated Pigeon Blood rubies in Mumbai and Surat jewelry districts offers volume expansion outside auction channels.
- Blockchain provenance integration:Distributed ledger verification from mine to retail counter addresses transparency premiums in EU and US collector segments.
- Investment-grade fund vehicles:Rare stone securitization platforms enable fractional ownership models for high-net-worth portfolios seeking non-correlated assets.
Industry Challenges
- Master cutter talent scarcity:Precision faceting expertise concentrated in Thailand's aging artisan workforce lacks replacement pipeline from vocational programs.
- Kimberley Process timeline compression:Certification documentation delays for Mozambican and Madagascan rough are extending inventory holding periods for traders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colored Gemstones Market |
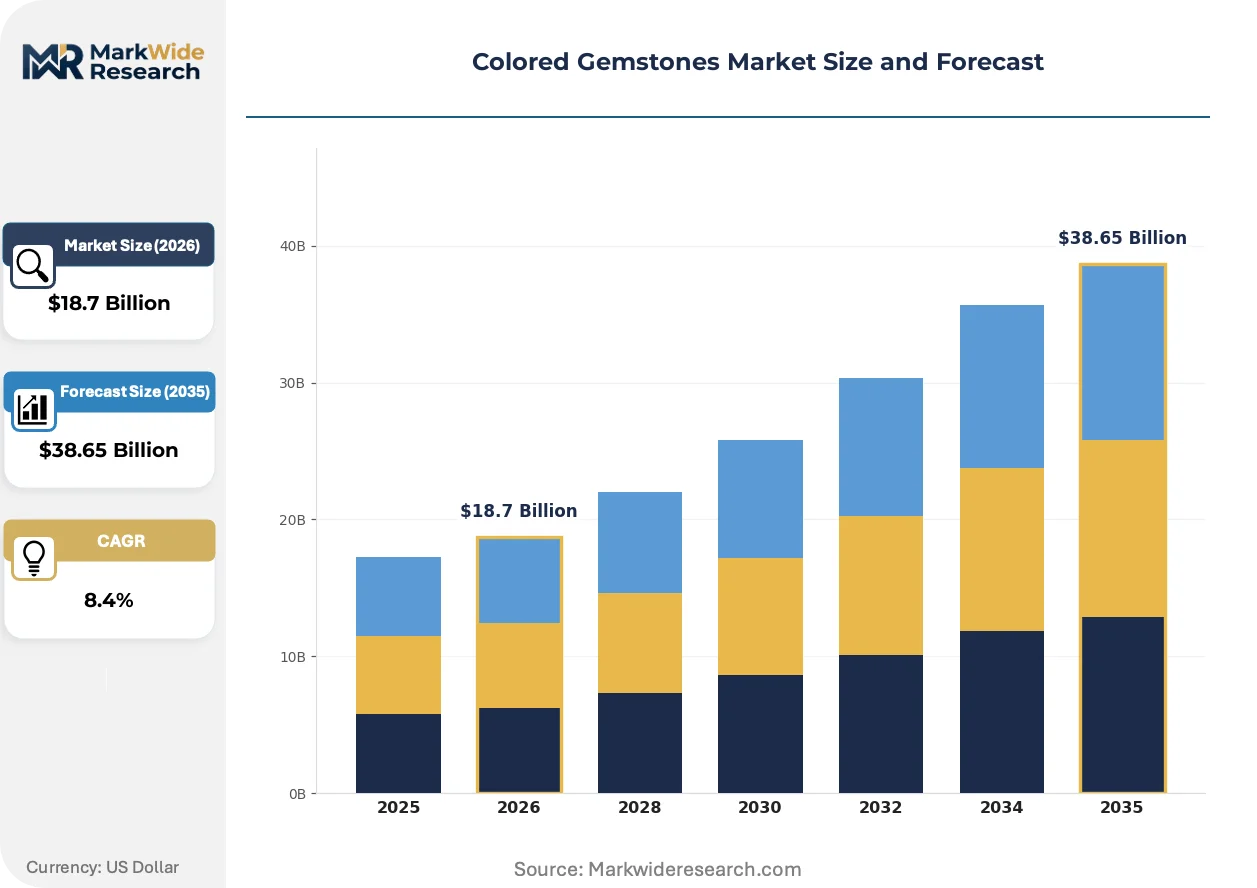
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ruby, Sapphire, Emerald, Amethyst Form: Faceted, Cabochon, Beads, Rough End User: Retail Jewelry, Wholesale, Collectors, Designers Market Application: Fine Jewelry, Fashion Jewelry, Industrial Use, Artisanal Crafts |
| Companies Covered | Gemfields Group Limited, Fura Gems Inc., Rio Tinto Group, Gem Diamonds Limited, PJSC ALROSA, Anglo American plc, KGK Group, Tiffany & Co., SWAROVSKI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colored Gemstones Market Emerging Trajectories
Synthetic disclosure requirements and provenance verification technologies are bifurcating buyer segments into transparency-prioritizing collectors and price-driven mass market channels. These shifts are reshaping competitive positioning across extraction, cutting, and retail tiers.
Laser-induced breakdown spectroscopy (LIBS) is fragmenting traditional gemological laboratory hierarchies by enabling rapid origin determination at auction preview events. Mid-tier dealers now deploy portable spectrometers to bypass centralized Bangkok certification queues. This compression of verification timelines is disintermediating legacy testing institutions and redistributing margin capture toward cutting clusters.
EU Corporate Sustainability Reporting Directive (CSRD) disclosure mandates are forcing jewelry houses to document Scope 3 emissions from artisanal mining networks. Large retailers are responding by consolidating supplier bases to reduce traceability complexity. Emerald and ruby categories face the steepest compliance burden given African and South American origin fragmentation.
Collector procurement is migrating from seasonal auction calendars toward continuous private treaty sales facilitated by digital platforms. High-net-worth buyers in Dubai and Singapore now source investment-grade stones through encrypted dealer networks rather than public auction houses. This channel shift is compressing price discovery transparency and privileging relationships over published transaction records.
Colored Gemstones Market Segmentation
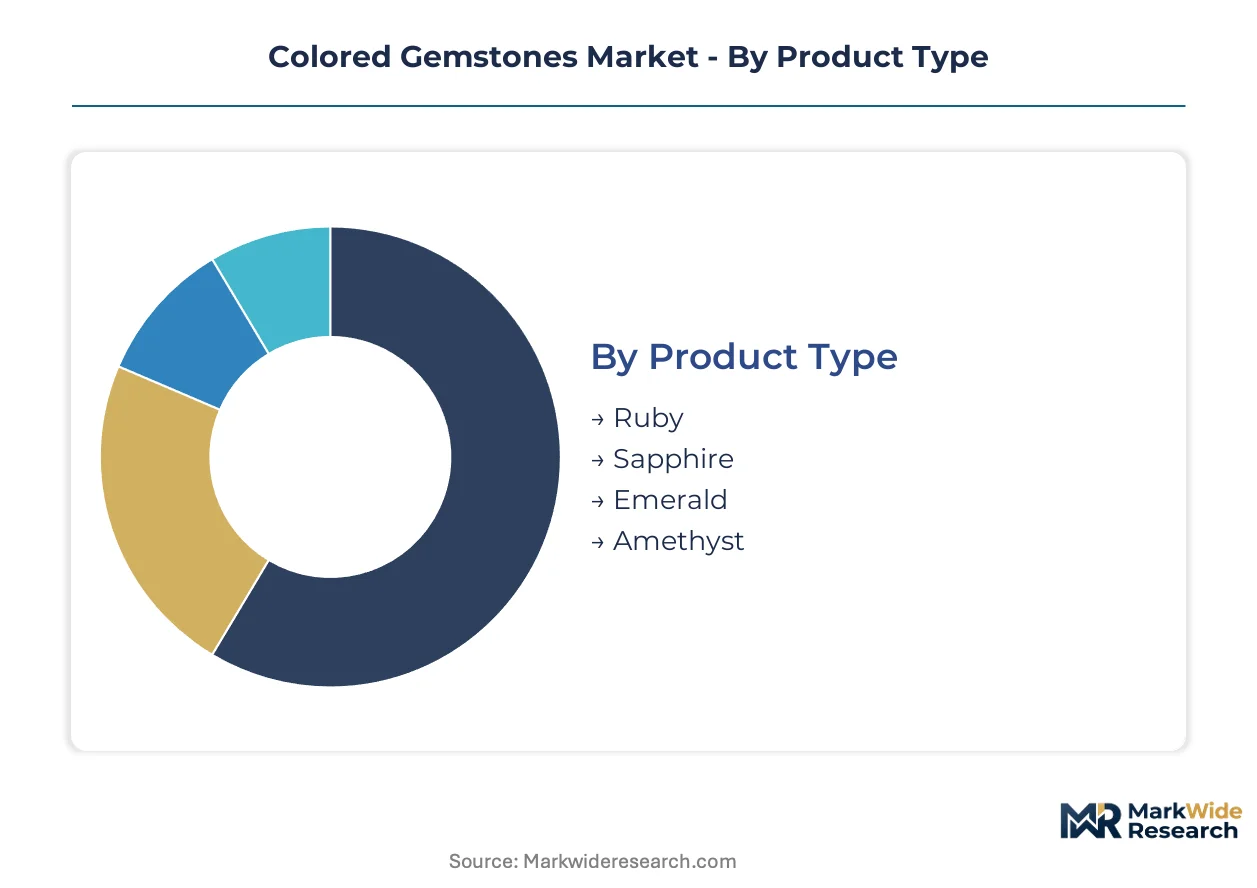
Segmentation in the colored gemstones trade separates volume-driven rough channels from margin-rich precision-cut finished goods. Distinct buyer profiles—mass-market jewelers, ultra-high-net-worth collectors, and artisanal designers—demand entirely different product specifications and certification standards.
Product Type:
Ruby and sapphire segments anchor export-heavy auction flows through Bangkok and Geneva, while emerald and amethyst categories serve more domestically concentrated cutting centers in Colombia and Brazil.
- Ruby:Corundum crystals with chromium-derived red saturation command the highest per-carat pricing at international auction. Collector demand concentrates in untreated Pigeon Blood specimens from Myanmar and Mozambique, driven by scarcity of unheated material above five carats.
- Sapphire:Aluminum oxide crystals span blue, pink, yellow, and padparadscha color varieties with Mohs hardness enabling daily-wear jewelry designs. Sri Lankan and Madagascar rough supplies dominate export channels to Thai cutting houses, where heat-treated material absorbs mid-market bridal demand.
- Emerald:Beryl-based stones with chromium and vanadium trace elements exhibit characteristic inclusions requiring oil or resin fracture filling. Colombian Muzo and Chivor deposits face depletion pressures, forcing cutters toward Zambian and Ethiopian rough sources.
- Amethyst:Purple quartz varieties represent the most accessible entry point for domestic jewelry manufacturers and mass-market retailers. Brazilian Rio Grande do Sul deposits supply volume-led fashion jewelry channels with minimal certification overhead.
Ruby commands the established base. The steepest expansion runs through sapphire as heat-treatment disclosure standards mature.
Form:
Processing intensity creates sharp cost tier differentiation, with precision-faceted goods absorbing skilled labor premiums while rough trading sustains volume liquidity.
- Faceted:Precision-cut stones with calibrated angles optimize light return for jewelry settings. Bangkok's artisan cluster processes over half of global corundum through this form, where master cutter scarcity constrains output expansion.
- Cabochon:Domed, unfaceted cuts preserve weight in translucent or heavily included material. Star ruby and star sapphire demand concentrates in traditional Middle Eastern and South Asian jewelry markets.
- Beads:Drilled spherical or rondelle shapes serve costume jewelry and accessory manufacturers. Chinese Guangdong province dominates mechanized bead production for export to fast-fashion supply chains.
- Rough:Unprocessed crystals trade through closed dealer networks and sealed tender auctions. Gemfields' Montepuez operations and Fura's Colombian assets anchor upstream supply concentration.
Rough trading commands the established base. The steepest expansion runs through faceted output as investment-grade buyers prioritize cut quality.
End User:
Customer type determines certification depth and channel structure, from mass-market retailers requiring streamlined documentation to collectors demanding mine-to-retail traceability.
- Retail Jewelry:Branded chains and independent jewelers stock calibrated sizes with standardized grading reports. EU and US disclosure mandates drive consolidation toward certified suppliers.
- Wholesale:Dealer-to-dealer transactions in Bangkok, Jaipur, and Tel Aviv sustain liquidity for uncertified parcels. Volume flows concentrate in corundum and quartz categories with established pricing benchmarks.
- Collectors:Ultra-high-net-worth individuals source rare untreated stones through private treaty and sealed auction. Provenance documentation and exclusivity premiums outweigh per-carat pricing sensitivity.
- Designers:Bespoke jewelry creators commission custom cuts and unusual shapes for one-of-a-kind pieces. Direct relationships with Bangkok cutting houses enable specification control unavailable through wholesale channels.
Wholesale channels command the established base. The steepest expansion runs through collectors as wealth preservation demand rotates from diamond portfolios.
Market Application:
Application scope spans ceremonial investment pieces to industrial abrasive consumption, with margin concentration inversely correlated to volume scale.
- Fine Jewelry:High-value pieces incorporating precious metal settings and certified center stones. Auction houses in Geneva and Hong Kong transact the category's price-setting transactions.
- Fashion Jewelry:Trend-driven designs using semi-precious stones and base metal mountings. Fast-fashion retailers drive volume with rapid style turnover and minimal durability requirements.
- Industrial Use:Synthetic and natural corundum in abrasive, bearing, and optical applications. Mohs hardness exploitation extends beyond ornamental markets into precision engineering.
- Artisanal Crafts:Hand-fabricated objects incorporating rough or minimally processed material. Direct-to-consumer platforms disintermediate traditional wholesale structures for this segment.
Fine jewelry commands the established base. The steepest expansion runs through artisanal crafts as maker-market platforms capture consumer preference for provenance transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangkok's Suvarnabhumi Airport cargo terminals handle the majority of global corundum rough shipments, cementing Thailand's chokehold on precision cutting infrastructure. Geneva's freeport vaults and Hong Kong's auction houses complete the triangular trade route that sets international price benchmarks.
Thailand
Bangkok's Chanthaburi cutting district processes over half of global ruby and sapphire rough, with master artisans commanding premiums for precision faceting. The Department of Mineral Resources enforces export certification protocols that function as de facto quality passports for Southeast Asian origin stones. Thai gemological laboratories in Silom and Yaowarat districts now compete with Swiss institutions for auction house accreditation.
Switzerland
Geneva's freeport storage facilities attract ultra-high-net-worth collectors seeking tax-advantaged custody for investment-grade stones. Swiss customs authorities apply the Kimberley Process Certification Scheme with stricter documentation timelines than competing jurisdictions. Christie's and Sotheby's maintain permanent colored stone specialists at their Rue du Rhône headquarters.
United States
New York's 47th Street diamond district has expanded dedicated colored stone trading floors as capital rotates from diamond portfolios. The Federal Trade Commission jewelry guides mandate synthetic disclosure standards that exceed international baselines. Tiffany & Co.'s Fifth Avenue flagship anchors vertically integrated provenance marketing to transparency-sensitive buyers.
Myanmar
Mogok's historic ruby mines supply untreated Pigeon Blood specimens that command auction premiums above heated material. Military-controlled export licensing creates supply volatility that Bangkok traders hedge through inventory stockpiling. Yangon's gem emporium maintains restricted access for foreign buyers, channeling premium rough through Thai intermediaries.
Colombia
Boyacá's Muzo and Chivor emerald deposits face depletion pressures that force cutters toward African rough alternatives. The National Mining Agency enforces royalty structures that disadvantage artisanal operators against mechanized African competitors. Bogotá's emerald district concentrates domestic cutting for lower-grade material while exporting premium rough to Geneva and Bangkok.
Colored Gemstones Market Vendor Landscape
Listed leaders compete with private specialists across auction channel access and rough supply security. Gemfields and Fura Gems anchor the publicly traded tier with mine-to-market operations, while family-held dealers dominate high-value private treaty sales. Three archetypes define competitive positioning: integrated miners controlling extraction-to-auction pipelines, luxury houses leveraging retail brand equity for provenance premiums, and specialist traders concentrating on single-origin sourcing. Consolidation pressures favor backward integration into captive rough supply and direct-to-collector digital platform development.
Within the integrated mining tier, Gemfields Group Limited and Fura Gems Inc. exemplify extraction-to-auction business models. Gemfields' London listing provides capital market access for African ruby development, while Fura's Toronto incorporation reflects North American investor appetite for Colombian emerald and Australian sapphire exposure. Rio Tinto Group and Anglo American plc occupy diversified resource positions where colored gemstones represent non-core portfolio elements. Tiffany & Co. anchors the luxury house archetype through Fifth Avenue retail integration, with SWAROVSKI representing the accessible-jewelry tier through Austrian crystal and synthetic gem distribution. KGK Group exemplifies the specialist trader model with Mumbai-Antwerp-Dubai corridor concentration.
| Leading Market Players |
|---|
| Gemfields Group Limited |
| Fura Gems Inc. |
| Rio Tinto Group |
| Gem Diamonds Limited |
| PJSC ALROSA |
| Anglo American plc |
| KGK Group |
| Tiffany & Co. |
| SWAROVSKI |
| Others |
Supply Flow & Price Mechanics
Zambian emerald rough displacing depleted Colombian material is simultaneously shifting procurement geography toward African auction houses and compressing margin structures for traditional cutters in Bogotá and Bangkok. This substitution dynamic concentrates pricing power among miners with diversified origin portfolios while forcing downstream processors to absorb higher transport and certification costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates untreated Pigeon Blood rubies from heat-treated corundum and mass-market quartz varieties. Price differentiation rests on certification depth and origin documentation, with Bangkok laboratory reports commanding premiums over uncertified parcels. Cost compression in the mid-market bridal segment is intensifying because hydrothermal synthetic producers capture price-sensitive demand. Mass-market retailers exhibit highest price sensitivity, while ultra-high-net-worth collectors prioritize provenance transparency over per-carat economics.
Supply Chain Analysis
Container availability constraints on the Mozambique-Thailand trade lane elevate inbound logistics costs for Montepuez rough shipments destined for Chanthaburi cutting houses. Geographic supply concentrates in Mozambique, Colombia, and Sri Lanka, with rough sourcing anchored in African and South American extraction zones. The chain draws from chromium-bearing corundum, beryl with vanadium trace elements, and aluminum oxide crystals as core inputs. Single-cluster processing vulnerability at Bangkok's artisan hub constitutes the dominant structural risk. Distribution runs through sealed tender auctions, dealer networks, and luxury retail flagships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense imperative as laboratory-grown corundum captures bridal market share and erodes mid-tier pricing floors.
For Market Incumbents: Secure captive rough supply through long-term offtake agreements with Mozambican and Zambian mining concessions before African competition consolidates auction access. Invest in blockchain provenance infrastructure to differentiate transparency credentials against synthetic producers and capture EU collector premiums. For New Entrants and Emerging Players: Anchor in the Indian bridal market's untreated ruby demand gap, where Mumbai and Surat jewelry districts lack established supplier relationships with Myanmar and Mozambique origin houses. Pursue direct-to-designer digital platforms that bypass Bangkok wholesale queues and offer custom cutting specifications. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated miners with auction house accreditation and diversified origin portfolios. Long-term viability across the five-to-ten year window favors operators controlling extraction-to-retail traceability infrastructure. Monitor synthetic disclosure regulation enforcement intensity in the EU and US as the primary inflection signal for natural stone premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rough Supply | Mine acquisitions in Mozambique and Zambia secure auction-grade material ahead of competitor consolidation. |
| Blockchain Provenance Deployment | Distributed ledger verification from Montepuez extraction to retail counter addresses EU CSRD disclosure mandates. |
| Master Cutter Apprenticeship Programs | Vocational pipeline development in Bangkok's Chanthaburi district alleviates precision faceting talent scarcity. |
| Direct-to-Collector Digital Platform | Encrypted private treaty sales bypass seasonal auction calendars and capture Singapore and Dubai HNWI demand. |
| Synthetic Disclosure Compliance Investment | FTC and EU regulatory alignment protects market access against lab-grown substitution in transparency-sensitive segments. |
Methodological Framework
Desk research of customs trade records, mining concession filings, and auction house transaction databases preceded structured interviews with rough procurement directors at Bangkok cutting houses, gemological laboratory certification officers, luxury retail buyers, and African mining operations managers. Primary fieldwork with Thai Department of Mineral Resources officials and Swiss freeport custody providers validated secondary trade flow estimates. Bottom-up volume modeling across extraction, cutting, and retail tiers was triangulated against top-down consumer expenditure analysis.
Variance decomposition across the projection horizon isolates volume drivers by product type, form intensity, end-user archetype, and regional regulatory cluster. Segmentation dimensions modeled include corundum versus beryl mineral families, precision-faceted versus rough trading channels, collector versus mass-market buyer profiles, and EU-compliant versus non-certified supply chains. CAGRs were derived from elasticity-adjusted demand projections incorporating Mohs hardness premium capture and synthetic substitution penetration rates.
Decision-makers should treat outputs as directional under assumptions of sustained EU due diligence enforcement and stable Myanmar export licensing regimes; material deviation would warrant model refresh. Specific risks that could revise trajectories include abrupt Kimberley Process timeline compression, accelerated Colombian deposit depletion, or synthetic producer cost breakthroughs in large-carat hydrothermal growth. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Global Mining Metals Market
Metals & Minerals
Recycled Aluminum Market
Metals & Minerals
Zinc Hydroxide Market
Metals & Minerals
Boron Ore Market
Metals & Minerals
Mineral Screening Market
Metals & Minerals
Phosphorus Ore Market
Metals & Minerals
Saudi Arabia and GCC Ferrosilicon Market
Metals & Minerals
Global Magnesium Market
Metals & Minerals
Global Antimony Market
Metals & Minerals
Iron Ore Pellets Market
Metals & Minerals
Cobalt Nitrate Market
Metals & Minerals
Moissanite Market
Metals & Minerals
Cobalt Sulphate Market
Metals & Minerals
Zinc Sulphate Market
Metals & Minerals
Nickel Nano Powder Market
Metals & Minerals
Pre-Painted Galvanised Iron (PPGI) Market