
 Mineral Screening Market | 2026-2036
Mineral Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Mineral Screening Market Insights
Modular screening plant design is shifting buyer preference away from standalone equipment purchases toward integrated crushing-and-screening configurations. Metso Outotec leverages its end-to-end minerals processing portfolio to anchor large copper-gold projects in South America. Sandvik AB competes through its digitalized equipment monitoring platform that extends aftermarket service revenue. Tega Industries specializes in polyurethane screen panel manufacturing, occupying a defensible niche in wear-part replacement cycles.
Mineral screening encompasses mechanical separation equipment that classifies crushed rock, ore, and aggregate by particle size using aperture-configured surfaces vibrating at frequencies between 800 and 3,600 RPM. These systems serve as critical upstream units in comminution circuits, ensuring downstream grinding mills receive optimally sized feed to prevent energy waste and liner damage. Wet screening techniques dominate iron ore and coal preparation flowsheets where water acts as both transport medium and dust suppressant, while dry screening remains entrenched in aggregate quarries with arid site conditions. Banana screens, with their variable-angle deck geometry, capture disproportionate margin pools in high-tonnage base metal operations where separation efficiency directly determines concentrate grade.
ISO 21873 governs mobile screening machinery safety standards, while EPA particulate emission thresholds in the United States and China's MEE dust control mandates jointly pressure operators to enclose vibrating screens and install negative-pressure dust collection. The EU F-Gas Regulation indirectly shapes equipment selection by restricting refrigerants used in associated compressed air systems for pneumatic screening aids. Stakeholders must weigh capital intensity against regulatory compliance timelines when selecting between refurbished legacy units and connected new-build platforms.
Market Dynamics
Modular crushing-and-screening configurations are displacing standalone equipment purchases as mining operators prioritize integrated circuit efficiency and faster commissioning timelines over component-level sourcing flexibility.
Growth Catalysts
- Iron ore beneficiation intensity:Australian miners are expanding wet screening capacity to process lower-grade deposits that require finer particle separation before downstream grinding.
- Tailings dam regulations:Brazil and Chile have tightened particulate discharge standards, compelling processors to invest in high-frequency screening for finer solid-liquid separation.
- Coal preparation retrofitting:Shanxi province coal plants are replacing legacy screens with high-frequency lines to meet stricter ash content specifications in coking coal output.
Market Restraints
- Polyurethane panel cost volatility:Raw material price swings for MDI and polyols squeeze margins for screen media suppliers serving high-wear applications.
- Specialized fabrication concentration:Heavy-duty screen frame manufacturing clusters in Germany and Finland, creating lead time vulnerability for remote project sites.
- Water scarcity constraints:Dry screening alternatives lack the separation efficiency of wet systems, limiting options for arid-region iron ore processors.
Strategic Opportunities
- Copper-gold project pipelines:South American greenfield developments require integrated crushing-and-screening packages with digital monitoring integration.
- Refurbished equipment channels:Secondary markets for certified-rebuilt banana screens offer entry points for mid-tier contractors in African copper belt operations.
- EU F-Gas compliance:Compressed air system retrofits for pneumatic screening aids create upgrade demand as refrigerant restrictions tighten.
Industry Challenges
- Vibration analysis expertise gap:Maintenance teams lack proficiency in predictive diagnostics for high-RPM screen bearings, accelerating unplanned downtime.
- Legacy control system integration:New sensor-equipped screens face protocol mismatches with existing DCS architectures in mature processing plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mineral Screening Market |
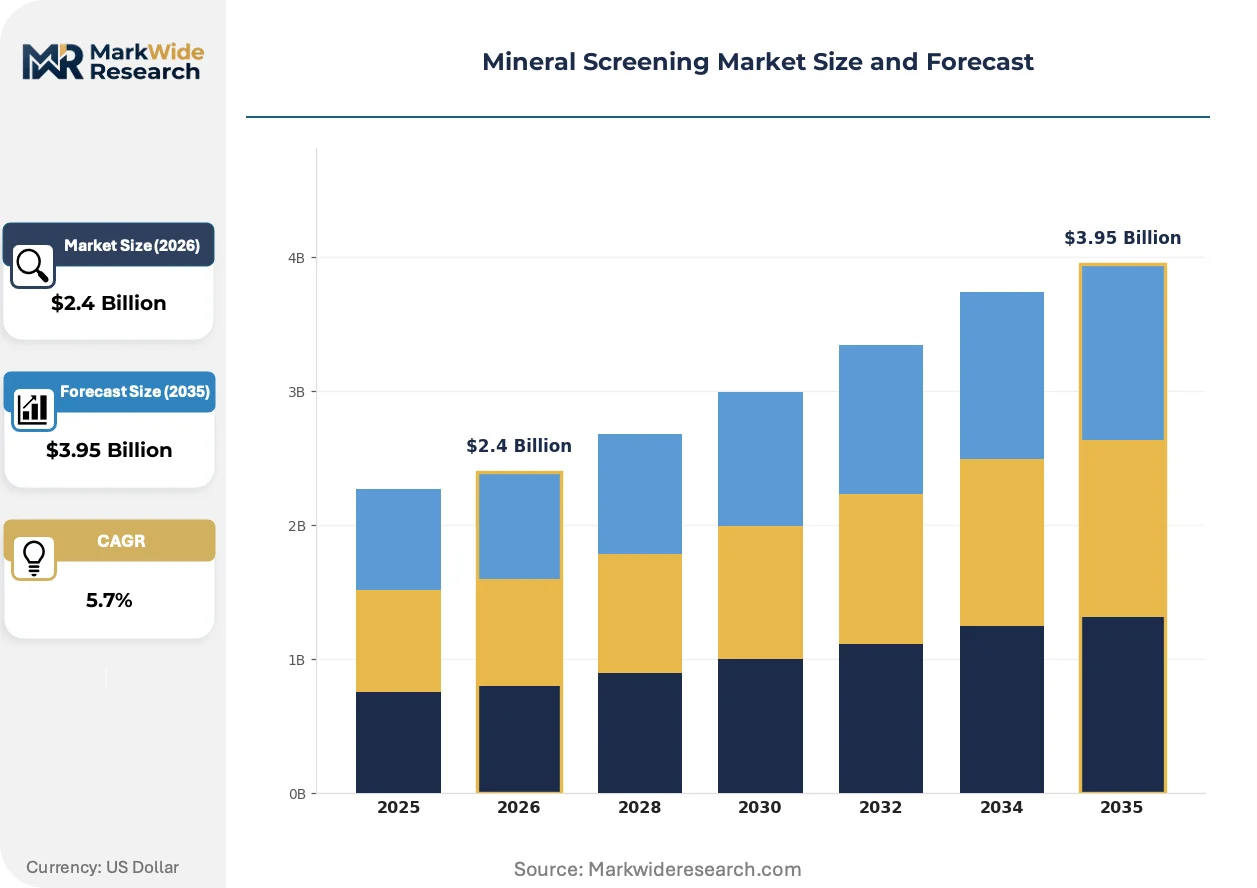
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.95 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Screening Equipment Type: Vibratory Screens, Trommel Screens, Disc Screens, Grizzly Screens, Banana Screens Screening Technique: Wet Screening, Dry Screening, High-Frequency Screening, Air Separation Application Sector: Mining Operations, Quarrying, Aggregate Production, Mineral Processing Plants, Construction Material Preparation End User Category: Mining Companies, Construction Contractors, Material Suppliers, Equipment Rental Firms |
| Companies Covered | Metso Outotec, Terex Corporation, Sandvik AB, Trelleborg Group, Multotec, Tega Industries, GKD, Polydeck Screen Corporation, Vibratech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mineral Screening Market Trends and Innovations
Digitalization is penetrating mineral screening through connected wear-part monitoring, automated aperture adjustment, and real-time efficiency optimization that shifts operator focus from reactive maintenance to throughput management.
Polyurethane screen panels with embedded RFID tags are absorbing the aftermarket service model. These intelligent surfaces transmit wear-depth data to plant control systems, enabling scheduled changeouts before aperture degradation affects product sizing. Iron ore and coal operators in Australia and China are deploying these systems fastest, compressing traditional time-based maintenance intervals toward condition-based protocols that reduce unplanned shutdown frequency.
EPA particulate emission thresholds in the United States and China's MEE dust control mandates are jointly mandating enclosed vibrating screen housings with negative-pressure dust collection. The regulatory pressure is forcing open-air quarry operations toward capital-intensive retrofit programs. Aggregate producers in California and Hebei province face the steepest compliance timelines as enforcement intensifies around respirable silica limits.
Service contract unbundling is fragmenting the traditional equipment-plus-aftermarket bundle. Mining houses now separately procure screen media, vibration analysis, and frame refurbishment from specialized providers rather than single-source OEM relationships. This disaggregation is most advanced in Chilean copper operations and South African platinum processing, where procurement teams prioritize unit-cost transparency over integrated supplier accountability.
Mineral Screening Market Segmentation
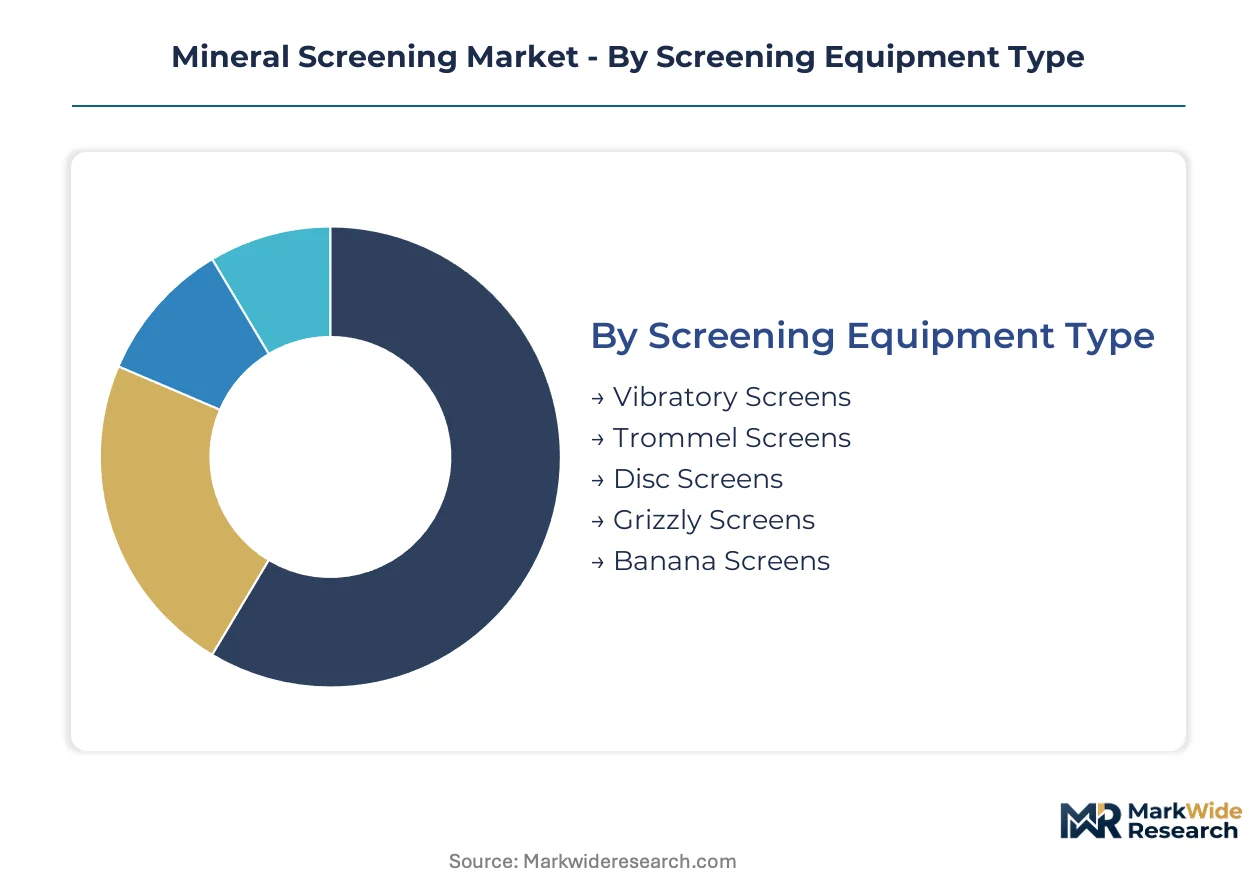
Mineral screening equipment selection hinges on ore characteristics, throughput requirements, and water availability at specific mine sites. Segmentation reveals how technology choices cluster around regional geology and regulatory environments rather than uniform global standards.
Screening Equipment Type:
Equipment differentiation centers on deck geometry, vibration frequency, and material transport mechanisms that determine separation efficiency for specific ore hardness and moisture content.
- Banana Screens:Variable-angle deck geometry enables progressive particle stratification across multiple slopes. Australian iron ore operations deploy these for high-tonnage lower-grade deposits where concentrate grade sensitivity justifies capital intensity.
- Vibratory Screens:Elliptical or linear vibration motion drives material across aperture-configured surfaces at 800–3,600 RPM. Coal beneficiation plants in Shanxi province favor high-frequency variants for fine coal dewatering under stricter ash content rules.
- Trommel Screens:Rotating cylindrical drums separate by size through gravitational tumbling action. Placer gold operations and coarse aggregate quarries employ these where water scarcity precludes wet screening alternatives.
- Grizzly Screens:Stationary or vibrating bar grids scalp oversized feed before primary crushing. Hard-rock mining circuits use these to protect downstream equipment from uncrushable material.
- Disc Screens:Rotating disc shafts create variable apertures for sticky or wet materials prone to blinding conventional wire mesh. Wood chip processing and certain industrial mineral applications specify these for non-blinding separation.
Banana screens lead on scale in base metal concentrators; high-frequency vibratory variants lead on momentum in coal retrofit cycles.
Screening Technique:
Process selection reflects water economics, dust control mandates, and particle size targets that vary sharply between arid quarry sites and humid ore processing corridors.
- Wet Screening:Water acts as transport medium and dust suppressant through spray-fed screen decks. Brazilian iron ore processors expanded capacity here after tailings dam failures triggered stricter solid-liquid separation requirements.
- High-Frequency Screening:Accelerations exceeding 4G enable fine particle dewatering and sharp size classification. Chilean copper concentrators adopted these for finer regrind circuit feeds that improve flotation recovery.
- Dry Screening:Air classification replaces water in arid-region aggregate operations. California quarries face EPA particulate thresholds that force enclosed housings and negative-pressure dust collection on these installations.
- Air Separation:Pneumatic classification exploits density differentials for specialized mineral sands and lightweight aggregate applications. Limited penetration outside niche industrial mineral flowsheets due to energy intensity.
Wet screening leads on scale across iron ore and coal preparation; high-frequency methods lead on momentum where water recovery and tailings management tighten.
Application Sector:
End-use segmentation tracks capital deployment cycles between greenfield mining developments and infrastructure-driven aggregate demand.
- Mining Operations:Hard-rock and surface mining circuits integrate screening as upstream comminution stage. Copper-gold projects in South America specify integrated crushing-and-screening packages with digital monitoring.
- Mineral Processing Plants:Dedicated beneficiation facilities separate valuable minerals from gangue through multi-stage classification. Chinese coal preparation retrofits concentrate demand here for high-frequency line replacements.
- Quarrying:Dimension stone and construction aggregate extraction employs mobile and semi-mobile screening trains. European producers face EU F-Gas Regulation compliance costs on associated compressed air systems.
- Aggregate Production:Sand and gravel operations supply ready-mix concrete and asphalt industries. Urbanization in developing markets sustains equipment demand despite cyclical construction lulls.
- Construction Material Preparation:Recycled concrete and manufactured sand processing requires flexible screening configurations. Regulatory pressure on natural sand extraction expands addressable scope for engineered alternatives.
Mining operations lead on scale through project-driven capital intensity; mineral processing plant retrofits lead on momentum as regulatory compliance forces technology refresh.
End User Category:
Procurement authority and maintenance capability shape whether screening equipment arrives as owned asset or contracted service.
- Mining Companies:Integrated majors and mid-tier miners own and operate fixed processing infrastructure. These buyers prioritize total cost of ownership and aftermarket service integration over upfront equipment pricing.
- Construction Contractors:Project-based firms favor rental or lease arrangements for mobile crushing-and-screening spreads. Fleet utilization rates and relocation frequency determine specification choices.
- Material Suppliers:Independent aggregate and industrial mineral producers operate smaller-scale stationary plants. Price-sensitive procurement concentrates on wear-part availability and local service presence.
- Equipment Rental Firms:Specialized lessors maintain mobile fleets for construction and demolition recycling. Asset utilization metrics and rapid deployment capability dominate investment criteria.
Mining companies lead on scale through captive processing infrastructure; rental firms lead on momentum as service-model unbundling fragments traditional OEM relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mineral screening technology originated in German and Finnish heavy engineering clusters during the mid-20th century, with banana screen designs and high-frequency vibratory systems first commercialized for Scandinavian iron ore and Central European coal operations. These foundational innovations established the technical standards that now govern separation efficiency across global mining corridors.
Australia
Pilbara iron ore miners drive wet screening expansion to process lower-grade hematite deposits requiring finer particle classification before grinding circuits. EPA Western Australia enforces dust suppression mandates that accelerate enclosed screen housing adoption. Perth-based engineering firms supply modular crushing-and-screening packages to remote mine sites with compressed commissioning timelines.
China
Shanxi province coal beneficiation plants retrofit high-frequency screening lines to meet stricter coking coal ash specifications under MEE environmental mandates. The country's dual carbon goals pressure processors to improve energy efficiency in comminution circuits. Yangtze River Delta equipment manufacturers dominate domestic polyurethane screen panel supply chains.
Brazil
Iron ore processors in Minas Gerais invest in finer solid-liquid separation technology following tailings dam failures that triggered ANM regulatory tightening. High-frequency screening capacity expands to reduce moisture content in concentrate shipments. Vale's Carajás operations anchor demand for large-tonnage banana screen installations.
Chile
Copper-gold concentrators in the Atacama Desert adopt integrated crushing-and-screening configurations with digital monitoring for regrind circuit optimization. Stricter particulate discharge standards under SMA environmental enforcement compel technology refresh cycles. Antofagasta-based contractors source refurbished banana screens to control capital deployment on mid-tier projects.
United States
California aggregate quarries face EPA respirable silica limits that mandate enclosed vibrating screen housings with negative-pressure dust collection. Nevada gold operations deploy high-frequency screens for fine carbon-in-leach circuit feeds. Phoenix-area equipment lessors maintain mobile screening fleets for Southwest construction markets.
Mineral Screening Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the technology sophistication spectrum, with integrated minerals processing portfolios commanding pricing power against standalone equipment vendors. The vendor base clusters around three strategic tiers: full-line OEMs with digital service platforms, specialized screen media manufacturers with captive polymer chemistry expertise, and regional fabricators serving aftermarket refurbishment channels. Consolidation pressure intensifies as mining houses unbundle service contracts and procurement teams prioritize unit-cost transparency over single-source relationships. Dominant competitive moves include backward integration into polyurethane raw materials and geographic expansion through certified-rebuild center networks.
Among Nordic engineering conglomerates, Metso Outotec and Sandvik AB occupy positions as full-line system integrators, while Tega Industries exemplifies the specialized screen media archetype with defensible positioning in wear-part replacement cycles. These three anchors represent divergent strategic paths: end-to-end minerals processing versus component-level manufacturing depth versus aftermarket service density.
| Leading Market Players |
|---|
| Metso Outotec |
| Terex Corporation |
| Sandvik AB |
| Trelleborg Group |
| Multotec |
| Tega Industries |
| GKD |
| Polydeck Screen Corporation |
| Vibratech |
| Others |
Pricing and Supply Chain Analysis
Polyurethane raw material costs for MDI and polyols cascade through three distinct pricing tiers as screen panel manufacturers in Germany and Finland pass volatility downstream to Australian iron ore operators and Chinese coal processors facing divergent procurement timelines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs mineral screening equipment transactions. Premium tiers attach to banana screens with digital monitoring integration demanded by South American copper-gold projects, while economy tiers serve African mid-tier contractors sourcing refurbished units. Price differentiation hinges on certification grade against ISO 21873 safety standards and aftermarket service bundling intensity. Cost compression in standard-tier vibratory screens is intensifying because polyurethane panel suppliers face MDI price volatility. Construction contractors exhibit highest price sensitivity due to rental fleet utilization pressures, whereas integrated mining majors prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Specialized welder and vibration engineer shortages in German and Finnish fabrication clusters extend lead times for heavy-duty screen frames destined for remote Chilean and Australian mine sites. Manufacturing gravity centers on Germany, Finland, and China, with Yangtze River Delta suppliers dominating polyurethane screen panel production. Raw material flows draw from petrochemical feedstocks for polymer chemistry, high-grade steel for frame construction, and rare earth elements for vibration motor magnets. Single-source vulnerability concentrates in German precision bearing supply for high-RPM drive systems. Distribution runs through OEM direct sales for large mining houses and regional distributors serving mid-tier aggregate producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mineral screening functions as a regulatory compounder where tailings dam legislation in Brazil and Chile forces capital deployment into finer separation technology regardless of commodity price cycles.
For Market Incumbents: Lock in aftermarket service density through RFID-enabled polyurethane panel deployments that compress maintenance intervals toward condition-based protocols. Backward integration into captive MDI supply buffers margin pressure from polyol cost volatility. Capacity addition in Perth engineering clusters captures Australian iron ore wet screening expansion while defending against Chinese equipment manufacturers with shorter delivery timelines. For New Entrants and Emerging Players: Digital-channel routes through equipment-as-a-service platforms offer lower-friction entry into African copper belt operations where mid-tier contractors prioritize utilization metrics over ownership. Refurbished banana screen certification programs represent the most penetrable segment, with Antofagasta-based contractors seeking capital-efficient regrind circuit solutions. Target aftermarket screen media supply rather than full equipment fabrication to bypass German-Finnish fabrication bottlenecks. For Investors and Strategic Acquirers: Consolidation pressure builds where service contract unbundling fragments traditional OEM relationships and procurement teams prioritize unit-cost transparency. Long-term viability favors specialized screen media manufacturers with captive polymer chemistry expertise over standalone equipment vendors facing digital platform competition from full-line integrators. Watch for SMA enforcement intensity in Chile as inflection indicator for high-frequency screening upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Chemistry | Captive MDI supply insulates margins against petrochemical volatility affecting Tega Industries competitors. |
| Certified-Rebuild Center Network Expansion | Antofagasta and Perth locations capture mid-tier contractor demand for capital-efficient banana screen deployments. |
| RFID-Enabled Smart Panel Deployment | Wear-depth telemetry shifts maintenance protocols from time-based to condition-based for Australian iron ore operators. |
| Digital Monitoring Platform Integration | Real-time vibration analysis extends aftermarket revenue streams beyond traditional spare part sales. |
| EU F-Gas Compliance System Retrofit | Compressed air upgrade demand creates attach revenue for pneumatic screening aid installations in European quarrying. |
Research Methodology
Bottom-up mining operation modeling reconciled against top-down equipment manufacturer production tracking forms the analytical core of this study. Primary interviews with maintenance directors at Pilbara iron ore sites, procurement leads at Shanxi coal beneficiation plants, aftermarket service heads at Chilean copper concentrators, and plant engineers at Brazilian iron ore processors supplied operational validation. Secondary sources include ANM regulatory filings on tailings dam standards, EPA particulate emission enforcement records, SEC 10-K disclosures from listed equipment manufacturers, and MEE environmental compliance databases. Cross-referencing bottom-up demand signals against top-down supply capacity produces volume estimates.
Input-output matrices map crushing-and-screening package deployments across technique type, application sector, and end-user category throughout the projection horizon. Segmentation dimensions include equipment type differentiation between banana and high-frequency vibratory systems, wet versus dry process selection, and mining company versus contractor procurement authority. CAGRs derive from regression analysis against iron ore beneficiation intensity indicators, coal preparation retrofitting cycles, and copper-gold project pipeline tracking. Forecast inputs incorporate water scarcity constraints affecting dry screening alternatives and vibration analysis expertise gaps influencing unplanned downtime assumptions.
The model assumes a particular technology adoption path; alternative pathways for dry screening efficiency breakthroughs would alter the outlook for arid-region iron ore processors. Forecasts reflect assumptions regarding regulatory enforcement timelines for tailings dam standards and dust control mandates. Material deviation in ANM or SMA enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Testing Inspection and Certification TIC for the Metals and Minerals Market
Metals & Minerals
Global Nickel Hydroxide Market
Metals & Minerals
India CRNO Steel Lamination Market
Metals & Minerals
Laminated Steel Market
Metals & Minerals
Andalusite Market
Metals & Minerals
Bauxite Market
Metals & Minerals
Phosphorus Ore Market
Metals & Minerals
Mexico Mining Market
Metals & Minerals
Global Boron Market
Metals & Minerals
Flake Graphite Market
Metals & Minerals
Pre-Painted Galvanised Iron (PPGI) Market
Metals & Minerals
Cobalt Sulphate Market
Metals & Minerals
Chromite Market
Metals & Minerals
Zellerite Market
Metals & Minerals
Saudi Arabia and GCC Ferrosilicon Market
Metals & Minerals
Dead Sea Mineral Market