
 Bauxite Market | 2026-2036
Bauxite Market Size, Share, and Industry Trends Forecast 2026-2036
Bauxite Market Intelligence
The automotive end-use vertical is rebalancing toward aluminum-intensive electric vehicle platforms, pulling higher-grade bauxite flows into metallurgical processing chains. Rio Tinto anchors Western Australian supply through its integrated mine-to-refinery infrastructure. Hindalco Industries Ltd. leverages captive bauxite reserves in Odisha to sustain cost positions in domestic alumina markets. Rusal competes through Siberian hydro-powered smelting networks that prize low-carbon bauxite sourcing.
Bauxite denotes a sedimentary rock containing hydrated aluminum oxides, primarily gibbsite, boehmite, and diaspore, with typical alumina content ranging from thirty to sixty percent depending on deposit geology and beneficiation. Miners extract and process this ore chiefly for alumina refining via the Bayer process, which feeds primary aluminum smelting and specialty chemical production. Metallurgical bauxite dominates volume flows as the feedstock backbone for alumina production, while refractory bauxite commands premium pricing in high-temperature industrial applications. Calcined bauxite occupies a specialized niche in abrasive and proppant markets where thermal treatment upgrades performance characteristics.
Guinea's mining ministry, Australia's Department of Climate Change, Energy, the Environment and Water, and China's Ministry of Ecology and Environment collectively shape extraction licensing, carbon accounting, and export quota frameworks that determine mine viability and trade flows. The EU's Carbon Border Adjustment Mechanism and evolving ISO 14064 protocols for product-level emissions disclosure are tightening accountability requirements across bauxite-to-aluminum value chains. Stakeholders must monitor regulatory divergence between carbon-intensive and low-carbon production jurisdictions to align sourcing strategies with emerging trade compliance thresholds.
Market Dynamics
China's dual carbon goals and stricter MEE emissions standards are compressing refinery investment timelines while redirecting capital toward Guinea's mining corridors, fundamentally restructuring bauxite-to-alumina supply economics.
Growth Catalysts
- Lightweighting mandates:Aerospace OEMs and automotive platforms are specifying higher-grade metallurgical bauxite to meet fuel efficiency and battery range targets, tightening quality premiums across supply contracts.
- EU Carbon Border Adjustment Mechanism:Import charges on carbon-intensive aluminum are incentivizing European smelters to source low-carbon bauxite from hydro-powered corridors, reshaping procurement geographies.
- Electric vehicle platform proliferation:Aluminum-intensive EV architectures are pulling metallurgical-grade ore into expanded refining capacity, with battery enclosure and body-in-white applications driving volume concentration.
Market Restraints
- Guinean supply concentration:Over two-thirds of incremental export capacity routes through Conakry-Boké infrastructure corridors, creating single-point vulnerability to port congestion or political disruption.
- Declining Australian ore grades:Weipa and Darling Range deposits require deeper stripping ratios and beneficiation energy, eroding cost competitiveness against West African greenfield projects.
- Bayer process energy intensity:Alumina refining consumes 8-12 MWh per tonne, exposing margins to natural gas and coal price volatility in carbon-regulated jurisdictions.
Strategic Opportunities
- Refractory-grade verticals:High-temperature industrial applications in cement and steel manufacturing command 40-60% price premiums over metallurgical feedstock, rewarding beneficiation investment.
- Siberian hydro-powered smelting networks:Rusal's En+ integration creates arbitrage for low-carbon bauxite sourcing into EU compliance markets, bypassing CBAM exposure.
- ISO 14064 product-level disclosure:Emerging Scope 3 accounting requirements favor miners with certified emissions baselines, enabling differentiated contracting with automotive OEMs.
Industry Challenges
- Geological modeling talent scarcity:Guinea's lateritic deposit complexity demands specialized bauxite geologists, with skill pipelines concentrated in Australian and Brazilian mining education systems.
- Integrated mine-to-refinery capex cycles:Greenfield alumina projects require 4-7 year construction timelines, misaligning with EV demand ramp schedules and creating interim supply gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bauxite Market |
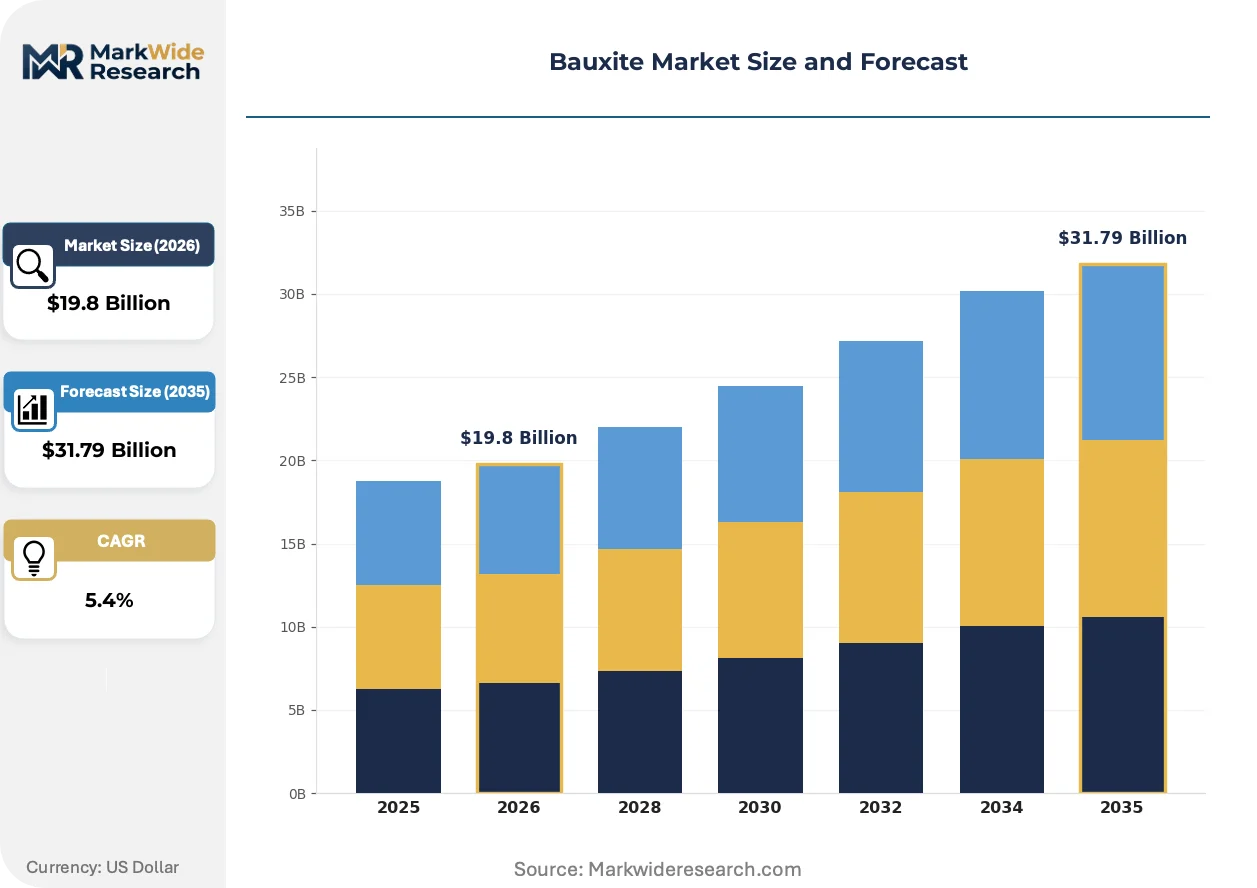
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $31.79 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Bauxite, Calcined Bauxite, Refractory Bauxite, Metallurgical Bauxite End Use Industry: Aerospace, Automotive, Construction, Chemical Manufacturing Sales Channel: Direct Sales, Distributors, Online Sales, Export Application: Alumina Production, Steelmaking, Refractory Products, Water Treatment |
| Companies Covered | Rio Tinto, Alcoa Corporation, Rusal, Aluminum Corporation of China Limited (CHALCO), Norsk Hydro ASA, NALCO India, Hindalco Industries Ltd., South32, Emirates Global Aluminium PJSC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bauxite Market Strategic Shifts & Innovations
Digital traceability platforms and process electrification are compressing emissions accounting cycles while enabling real-time quality verification across multi-modal bauxite supply chains.
Advanced sensor-based ore sorting is electrifying beneficiation economics by reducing energy-intensive crushing and grinding requirements. Rio Tinto's Western Australian operations are deploying X-ray transmission sorters to upgrade marginal ore before Bayer processing, cutting refinery feed variability and alumina recovery losses. The technology is compressing capital intensity for mid-tier miners seeking to compete against Guinea's high-grade laterites.
China's Ministry of Ecology and Environment is tightening MEE emissions standards for alumina refineries, forcing capacity closures in Shandong and Shanxi provinces. Smelters are responding by relocating integrated operations to Indonesia and Guinea, where coal-to-gas switching and renewable hybrid power reduce compliance costs. The policy is fragmenting Chinese supply dominance while accelerating overseas asset acquisition.
Automotive OEMs are unbundling bauxite procurement from traditional trader intermediaries, establishing direct offtake agreements with Guinean miners backed by blockchain-verified carbon accounting. Tesla, BMW, and Ford Motor Company have implemented supplier sustainability scorecards that weight Scope 3 emissions alongside metallurgical grade, concentrating contract awards toward certified low-carbon corridors. This pattern is most pronounced in European and North American battery supply chain construction.
Bauxite Market Segmentation
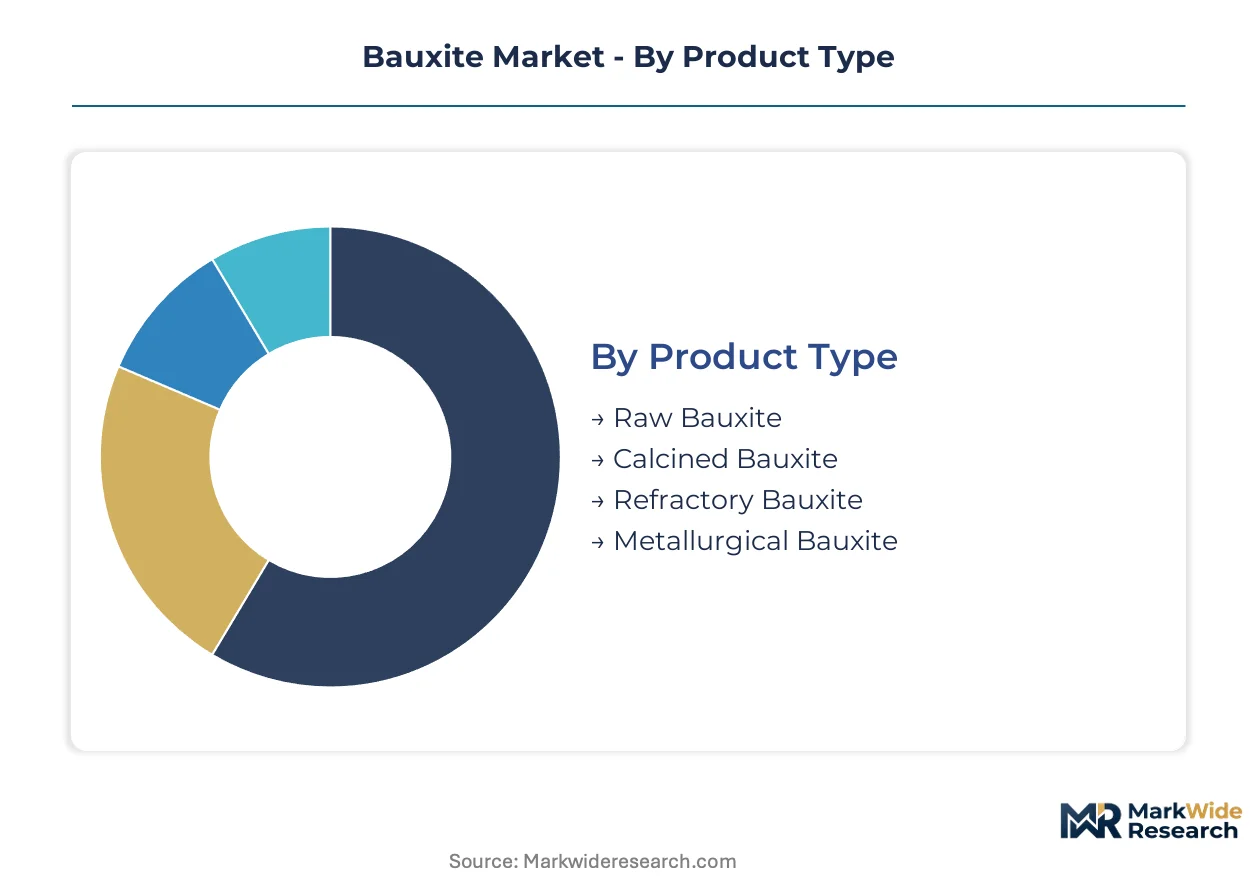
Product-grade differentiation determines bauxite valuation tiers across metallurgical and specialty markets. Refinery feedstock specifications and end-use performance requirements create distinct procurement channels that shape supplier positioning.
Product Type:
Grade upgrade cycles and beneficiation intensity separate commodity flows from premium specialty streams.
- Metallurgical Bauxite:Contains 45-60% alumina as gibbsite, boehmite, or diaspore, meeting Bayer process feedstock standards for primary aluminum production. Demand concentrates in Guinea's Boké mining corridor as Chinese refineries seek higher-grade ore to offset declining Australian supply quality.
- Refractory Bauxite:High-density, low-iron variants withstand temperatures exceeding 1,800°C in cement kiln and steel ladle applications. European steelmakers prioritize Guinean and Brazilian sources for magnesia-spinel brick production under tightening EU Carbon Border Adjustment Mechanism compliance.
- Calcined Bauxite:Rotary kiln processing at 1,600°C upgrades hardness and chemical stability for abrasive and proppant markets.
- Raw Bauxite:Unprocessed ore requiring beneficiation before refining, traded primarily for captive integrated operations.
Metallurgical bauxite sits at the top of the volume ranking, with refractory bauxite climbing the fastest.
End Use Industry:
Application-specific purity requirements and carbon accounting standards segment procurement by downstream intensity.
- Automotive:Aluminum-intensive electric vehicle platforms specify low-carbon metallurgical bauxite for battery enclosures and body-in-white structures. Tesla, BMW, and Ford Motor Company enforce Scope 3 emissions scorecards that favor certified supply chains from Siberian hydro-powered corridors.
- Aerospace:Airframe lightweighting mandates drive specification of high-gibbsite ore for aerospace-grade alumina. Boeing and Airbus procurement teams prioritize Guinean and Australian sources with ISO 14064 product-level emissions disclosure.
- Construction:Building and infrastructure applications consume standard-grade metallurgical bauxite for structural aluminum and cement additives.
- Chemical Manufacturing:Specialty alumina derivatives for catalysts and absorbents require controlled silica and iron content.
Automotive procurement represents the largest volume endpoint, with aerospace expanding most quickly.
Sales Channel:
Contract structure and logistics complexity determine channel economics across integrated and merchant supply chains.
- Direct Sales:Miners contract directly with integrated alumina refiners and automotive OEMs, bypassing trader intermediaries. Blockchain-verified carbon accounting supports long-term offtake agreements with European and North American battery supply chain constructors.
- Export:Cross-border bulk shipments through Conakry-Boké and Weipa port infrastructure serve Asian and European smelter demand.
- Distributors:Regional traders aggregate smaller volumes for mid-tier refractory and chemical manufacturers.
- Online Sales:Digital platforms facilitate spot market transactions for standardized metallurgical grades.
Direct sales channels capture the highest volume share, with export flows gaining share fastest.
Application:
Process chemistry and thermal performance requirements stratify bauxite consumption across alumina refining and industrial manufacturing.
- Alumina Production:Bayer process feedstock dominates volume consumption, converting hydrated aluminum oxides to smelter-grade alumina. China's Ministry of Ecology and Environment emissions standards are compressing domestic refinery capacity while redirecting investment toward Indonesian and Guinean integrated projects.
- Refractory Products:High-alumina bricks and monoliths for steel and cement manufacturing command 40-60% price premiums over metallurgical feedstock.
- Steelmaking:Flux and slag conditioning applications consume calcined bauxite for desulfurization and temperature control.
- Water Treatment:Activated alumina derived from bauxite removes fluoride and arsenic from municipal supplies.
Alumina production absorbs the dominant volume share, with refractory products showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guinea's Boké mining corridor anchors bauxite supply expansion as Chinese capital redirects toward West African greenfield projects. Australia's Weipa operations face grade decline pressures while Indonesian integrated refineries absorb displaced Chinese capacity. Regulatory divergence between carbon-intensive and low-carbon jurisdictions is fragmenting traditional trade flows.
Guinea
Chinese refinery investment is concentrating export capacity along the Conakry-Boké rail and port infrastructure. Guinea's mining ministry licenses greenfield concessions to integrated operators seeking to bypass Australian supply bottlenecks. The Boké-Kamsar corridor hosts the bulk of incremental metallurgical-grade production capacity serving Asian smelter demand.
Australia
Weipa and Darling Range deposits require deeper stripping ratios as ore grades erode, compressing cost positions against West African competition. The Department of Climate Change, Energy, the Environment and Water enforces emissions disclosure standards that reshape refinery investment timelines. Western Australia's integrated mine-to-refinery infrastructure retains strategic value for aerospace-grade alumina supply chains.
China
Domestic refinery closures in Shandong and Shanxi provinces are redirecting bauxite demand toward captive Indonesian and Guinean assets. The Ministry of Ecology and Environment's MEE emissions standards force coal-to-gas switching that raises processing costs. Guangxi and Henan smelters are accelerating overseas vertical integration to secure low-carbon feedstock compliance.
Indonesia
Integrated bauxite-to-alumina projects are absorbing Chinese capital flight from domestic emissions restrictions. The national mineral export ban framework incentivizes downstream processing investment over raw ore shipment. Kalimantan and Bintan Island host expanding refining capacity serving Chinese smelter offtake agreements.
Brazil
Refractory-grade bauxite from the Amazon basin commands premium pricing in European steel and cement manufacturing applications. ANVISA and environmental licensing frameworks govern extraction expansion in Pará and Minas Gerais states. The Trombetas River corridor sustains specialty calcined bauxite output for abrasive and proppant markets.
Bauxite Market Key Industry Players
Capacity expansion dominates the current landscape as integrated miners race to secure long-term offtake agreements with automotive OEMs. The supplier base concentrates around three tiers: diversified mining conglomerates with captive refining assets, state-backed national champions controlling strategic reserves, and mid-tier specialists focused on refractory-grade beneficiation. Strategic archetypes include hydro-powered low-carbon positioning, Guinea-based greenfield development, and Australian legacy infrastructure optimization. Geographic expansion and portfolio diversification represent the dominant competitive vectors as players seek to bypass EU Carbon Border Adjustment Mechanism exposure.
Among diversified mining conglomerates, Rio Tinto and Alcoa Corporation exemplify integrated mine-to-refinery operators with established Western Australian and Guinean positions. Rusal occupies a distinct archetype as a hydro-powered smelting network seeking low-carbon bauxite arbitrage into European compliance markets. State-backed national champions including Aluminum Corporation of China Limited and NALCO India represent strategic reserve holders redirecting capital toward overseas integrated projects.
| Leading Market Players |
|---|
| Rio Tinto |
| Alcoa Corporation |
| Rusal |
| Aluminum Corporation of China Limited (CHALCO) |
| Norsk Hydro ASA |
| NALCO India |
| Hindalco Industries Ltd. |
| South32 |
| Emirates Global Aluminium PJSC |
| Others |
Cost & Logistics Intelligence
Bayer process energy consumption at 8-12 MWh per tonne of alumina cascades through metallurgical bauxite contract tiers, compressing margins for coal-powered refineries while hydro-powered corridors capture carbon-accounting premiums from European automotive OEMs.
Pricing Analysis
Direct-to-OEM discounts bypass traditional trader markups as automotive manufacturers unbundle procurement through blockchain-verified carbon accounting. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14064-certified low-carbon ore from standard metallurgical grades and raw unbeneficiated feedstock. Cost compression in Australian legacy operations is intensifying because deeper stripping ratios erode cost positions against Guinean greenfield projects. Mid-tier refractory manufacturers exhibit highest price sensitivity, while aerospace OEMs prioritize quality premiums over unit economics.
Supply Chain Analysis
Bauxite supply rests on lateritic deposit geology concentrated in Guinea, Australia, and Indonesia, with Chinese capital redirecting toward West African integrated projects. Key inputs include diesel for mine haulage, caustic soda for Bayer processing, and natural gas or coal for calcination. Single-source vulnerability concentrates around the Conakry-Boké port corridor, where over two-thirds of incremental export capacity routes through shared rail and marine infrastructure. Distribution runs through long-term offtake contracts to captive refineries, with spot market liquidity limited to standardized metallurgical grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as automotive OEMs enforce Scope 3 emissions scorecards that concentrate contract awards toward certified low-carbon supply chains.
For Market Incumbents: Cement integrated mine-to-refinery positions in Guinea's Boké corridor through long-term port infrastructure commitments. Secure ISO 14064 product-level emissions certification to defend against hydro-powered Siberian competitors accessing EU Carbon Border Adjustment Mechanism compliance markets. Prioritize sensor-based ore sorting R&D to upgrade marginal Australian deposits against West African grade advantages. For New Entrants and Emerging Players: Launch via direct sales channels targeting European refractory manufacturers seeking Guinean and Brazilian high-alumina sources under tightening EU emissions standards. Exploit geological modeling talent scarcity by recruiting Australian-trained bauxite specialists for Guinea's lateritic deposit complexity. White-space exists in calcined bauxite beneficiation for abrasive and proppant markets where thermal treatment upgrades command specialty premiums. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier refractory-grade specialists because European steel and cement manufacturers prioritize magnesia-spinel brick sourcing under carbon border compliance. Five-to-ten year viability hinges on securing captive bauxite reserves ahead of Chinese state-backed national champions. Watch Indonesian integrated project completion rates as inflection indicator for Chinese capital redirection patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Guinean Mining Assets | Chinese refineries bypass Australian supply bottlenecks through Boké corridor concessions. |
| ISO 14064 Certification Program | Automotive OEMs weight Scope 3 emissions alongside metallurgical grade in supplier scorecards. |
| Sensor-Based Ore Sorting Deployment | Rio Tinto's X-ray transmission technology cuts refinery feed variability and recovery losses. |
| Long-term Supply Agreement with European Smelters | Hydro-powered corridors bypass EU Carbon Border Adjustment Mechanism exposure. |
| Refractory-Grade Beneficiation Investment | High-temperature applications command 40-60% price premiums over metallurgical feedstock. |
Research Approach
Direct dialogue with mine operations managers, alumina refinery procurement leads, automotive OEM sustainability officers, and Guinean mining ministry regulators grounded qualitative findings in operational reality. Secondary validation drew from customs and trade flow databases, SEC filings of integrated mining conglomerates, Chinese Ministry of Ecology and Environment emissions disclosures, and ISO certification registries. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across product grades and end-use industries.
Market size outputs trace alumina refining capacity expansion, electric vehicle platform aluminum intensity, and carbon border compliance thresholds across the projection horizon. Segmentation dimensions span metallurgical versus refractory versus calcined grade tiers, automotive versus aerospace versus construction end-use verticals, and direct sales versus export versus distributor channel structures. CAGRs derive from regression against historical bauxite-to-alumina price spreads and announced greenfield project timelines. Forecast inputs incorporate Chinese dual carbon policy enforcement intensity and EU Carbon Border Adjustment Mechanism implementation pace.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Guinean political disruption or accelerated Australian deposit depletion. Projections reflect assumptions regarding Chinese refinery relocation timelines and European automotive aluminum demand elasticity. A small set of named triggers warrants ongoing watch: Indonesian export ban enforcement, Siberian hydroelectric capacity expansion, and ISO 14064 adoption rates among Tier 1 automotive suppliers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Compacted Graphite Iron Market
Metals & Minerals
Tantalum Pentoxide Market
Metals & Minerals
Gold Recycling Market
Metals & Minerals
Recycled Steel Market
Metals & Minerals
Direct Reduced Iron (DRI) Market
Metals & Minerals
Nickel Nano Powder Market
Metals & Minerals
Global Magnesium Market
Metals & Minerals
Global Ferrous Scrap Recycling Market
Metals & Minerals
Mineral Ingredients Market
Metals & Minerals
Selenium Market
Metals & Minerals
Cesium Market
Metals & Minerals
Gemstones Market
Metals & Minerals
North America and EMEA Ferrosilicon Market
Metals & Minerals
Zellerite Market
Metals & Minerals
Saudi Arabia and GCC Ferrosilicon Market
Metals & Minerals
Californium Market