
 Diamond Market | 2026-2036
Diamond Market Size, Share, and Industry Trends Forecast 2026-2036
Diamond Market Analysis
Buyer concentration among luxury jewelry houses is realigning procurement power toward vertically integrated retailers. De Beers Group leverages its rough supply dominance to control pipeline allocations. ALROSA anchors its position through Siberian mine output and state-backed distribution channels. Kiran Gems specializes in Surat-based polishing at scale for mid-market jewelry brands.
Diamonds are crystalline carbon allotropes with a Mohs hardness of 10, formed under mantle conditions exceeding pressure and temperature thresholds, serving industrial cutting and gemstone markets. Natural diamonds retain premium positioning in bridal jewelry, while synthetic diamonds from chemical vapor deposition compete on price in fashion segments. Industrial grains command stable demand from wire drawing and electronics sectors despite thinner margins.
Kimberley Process certification shapes rough diamond trade access, while India's BIS mandates hallmarking standards for polished gemstone retail. The EU's forthcoming due diligence rules will extend supply chain disclosure requirements beyond conflict minerals. Stakeholders must monitor traceability technology investments and regulatory alignment across multiple jurisdictions.
Market Dynamics
The diamond market is experiencing a fundamental reconfiguration as the EU's Carbon Border Adjustment Mechanism rewrites sourcing economics for mined stones while synthetic production scales through chemical vapor deposition. This dual pressure is fragmenting procurement strategies across luxury jewelry houses and industrial buyers.
Growth Catalysts
- EU Carbon Border Adjustment Mechanism:The phased implementation of carbon border levies on imported goods is accelerating traceability investments across European jewelry retail, creating compliant supply chain premiums for verified low-carbon stones.
- Chemical vapor deposition scaling:Advances in microwave plasma reactors are expanding synthetic diamond wafer production for semiconductor heat spreaders and 5G infrastructure components.
- Surat polishing cluster concentration:India's gem processing hub continues consolidating cutting capacity, driving efficiency gains that lower finished goods costs for mid-market jewelry brands.
Market Restraints
- Energy input cost volatility:Synthetic diamond production depends on electricity-intensive plasma reactors, exposing manufacturers to grid price fluctuations in manufacturing regions.
- Rough supply concentration:Pipeline control by state-backed mining conglomerates in Russia and Botswana creates allocation uncertainty for independent polishers and traders.
- Technical limitation in large stones:Chemical vapor deposition remains constrained in producing colorless gems above three carats without detectable growth striations.
Strategic Opportunities
- Underpenetrated bridal markets in Southeast Asia:Vietnam and Indonesia present expansion potential as middle-class formation drives formalized jewelry purchasing traditions.
- Quantum sensing applications:Nitrogen-vacancy center diamonds are converging with photonics engineering for magnetic field sensors in medical imaging and defense systems.
- Direct-to-consumer certification platforms:Blockchain-enabled provenance tracking is creating new channel economics that bypass traditional wholesale tiers.
Industry Challenges
- Skilled cutter scarcity:Master faceting craftsmen in traditional cutting centers are aging out without sufficient apprenticeship pipeline replacement.
- Kimberley Process compliance timelines:Multi-jurisdictional certificate verification creates inventory friction and working capital compression for cross-border traders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diamond Market |
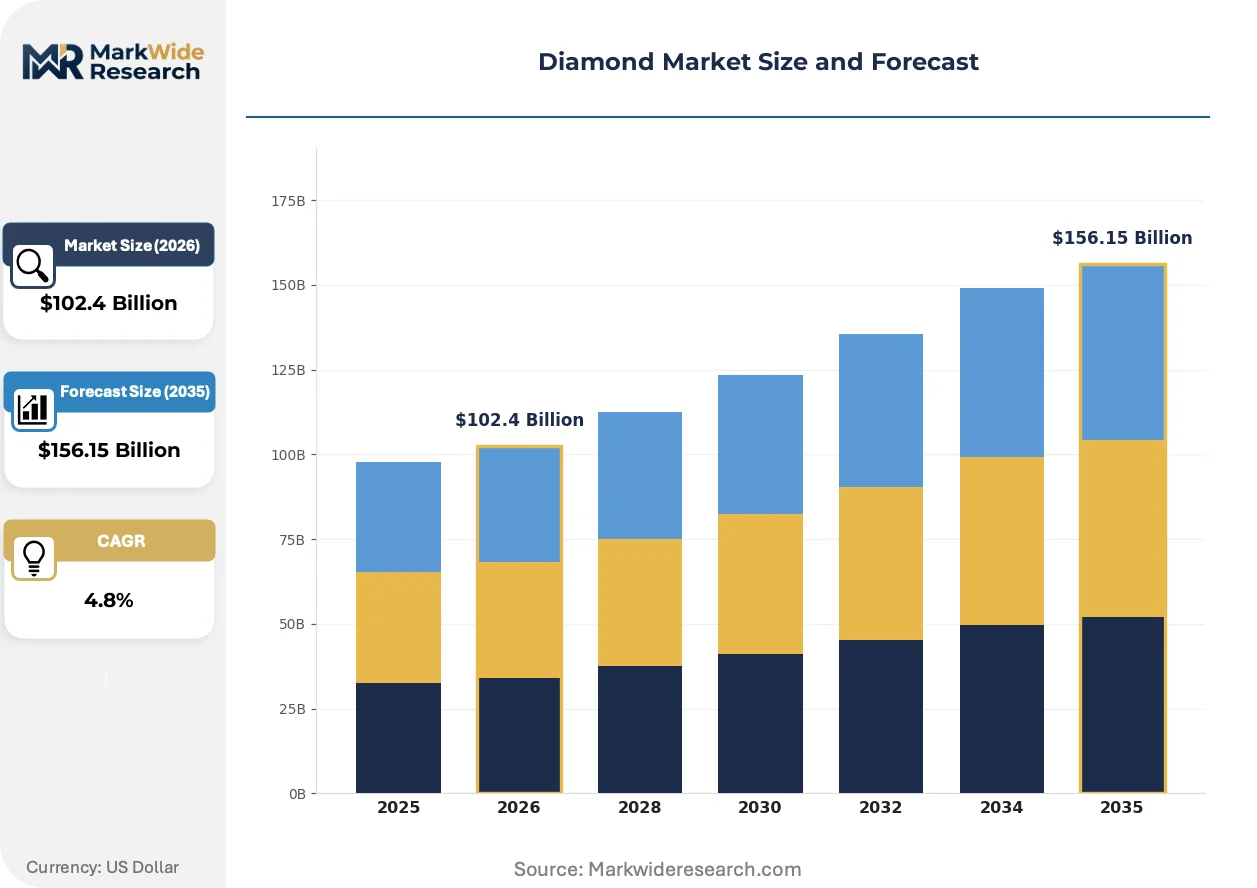
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $156.15 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Diamonds, Synthetic Diamonds, Fancy Colored Diamonds, Industrial Diamonds Form: Rough Diamonds, Polished Diamonds, Gemstone Cuts, Industrial Grains Application: Jewelry Manufacturing, Wire Drawing, Electronics, Optical Components End User: Jewelry Retailers, Manufacturers, Industrial Firms, Collectors |
| Companies Covered | Anglo American, Rosy Blue, De Beers Group, Bhavani Gems, Diarough NV, ALROSA, Kiran Gems, Lucara Diamond, Rio Tinto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diamond Market Emerging Trajectories
Traceability infrastructure and production automation are redefining competitive advantage across diamond value chains. Technology investments now separate margin leaders from commodity players.
Chemical vapor deposition reactors with real-time spectroscopic monitoring are modularizing synthetic diamond manufacturing. Industrial tool manufacturers and semiconductor substrate suppliers are adopting these systems to produce thermal management components in-house. This distributed production model is compressing lead times and eroding traditional merchant middleman roles.
The EU's forthcoming due diligence rules extending beyond conflict minerals are mandating supply chain disclosure for jewelry retailers above revenue thresholds. European luxury houses are restructuring supplier contracts to secure documented mine-to-market documentation. Bridal segment buyers in Germany and France are already showing measurable preference for fully traceable stones.
Certification-driven purchasing is displacing traditional four-Cs evaluation in high-value transactions. Auction houses and private wealth advisors are steering clients toward stones with blockchain-registered provenance and carbon footprint scoring. This behavioral shift is most pronounced in Swiss and UAE trading centers where ultra-high-net-worth collectors concentrate.
Diamond Market Segmentation
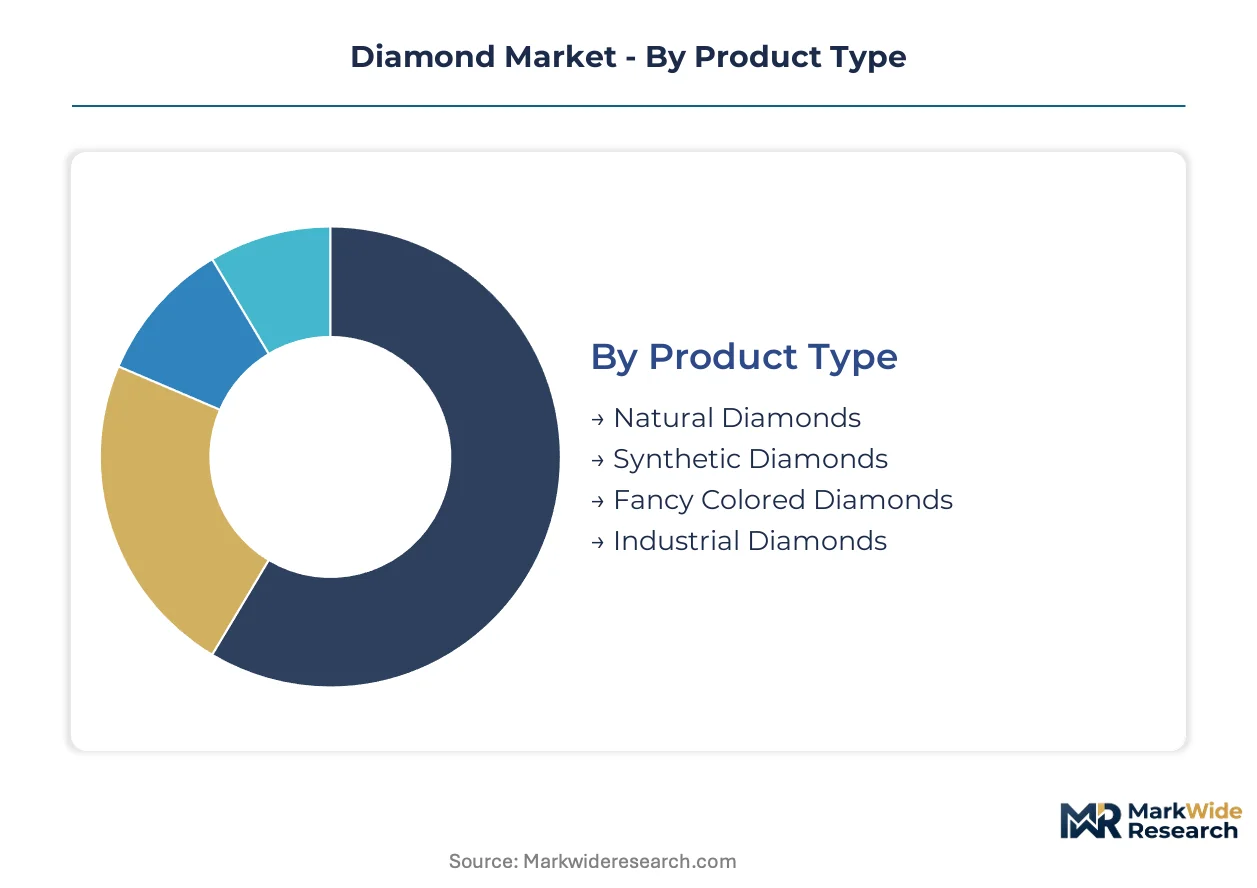
Diamond market segmentation reveals divergent value capture strategies across crystalline origins, processing stages, and application intensities. Procurement patterns differ sharply between bridal jewelry houses seeking certified provenance and semiconductor manufacturers prioritizing thermal conductivity specifications.
Product Type:
Standardization dominates at the industrial grade while customization intensity rises through gemstone tiers.
- Natural Diamonds:Mantle-formed crystalline carbon with Mohs hardness of 10 and characteristic inclusions. Bridal jewelry demand concentrates in North American and Chinese retail channels where Kimberley Process certification commands sourcing premiums. De Beers Group and ALROSA pipeline allocations shape availability for polished goods manufacturers.
- Synthetic Diamonds:Lab-grown stones produced through high-pressure high-temperature or chemical vapor deposition methods with identical optical properties to natural equivalents. Fashion jewelry adoption is accelerating in European markets under EU Carbon Border Adjustment Mechanism compliance pressure. Microwave plasma reactor advances are expanding wafer-scale production for thermal management applications.
- Fancy Colored Diamonds:Nitrogen, boron, or lattice distortion-induced hues including pink, blue, and yellow variants. Collector auction activity in Geneva and Dubai trading centers drives price formation for investment-grade stones.
- Industrial Diamonds:Lower-clarity crystalline or polycrystalline forms optimized for abrasive and cutting applications. Wire drawing die and precision machining sectors in Germany and Japan sustain offtake despite compressed margins.
Most installed capacity flows through Natural Diamonds. Expansion is steepest in Synthetic Diamonds.
Form:
Margin accumulation shifts downstream from extraction toward precision finishing, with geographic concentration determining access economics.
- Rough Diamonds:Unprocessed octahedral or dodecahedral crystals requiring evaluation and sorting. State-backed mining conglomerates in Russia and Botswana control release schedules, creating allocation uncertainty for independent polishers.
- Polished Diamonds:Faceted finished goods graded by cut, color, clarity, and carat weight. India's Surat cluster processes the majority of global volume, driving efficiency gains that lower costs for mid-market jewelry brands.
- Gemstone Cuts:Specialized faceting patterns including brilliant, princess, emerald, and cushion configurations. Master craftsmen scarcity in Antwerp and Tel Aviv is extending lead times for bespoke bridal orders.
- Industrial Grains:Crushed or synthesized particles for bonded and coated abrasive tools. Electronics substrate manufacturers are adopting in-house chemical vapor deposition systems to compress thermal management component lead times.
Volume concentrates in Rough Diamonds. Value capture is climbing fastest in Polished Diamonds.
Application:
Application diversity spans aesthetic display to functional thermal management, with specification stringency varying by end-use criticality.
- Jewelry Manufacturing:Gemstone setting into precious metal mountings for retail distribution. Bridal segment buyers in Germany and France are showing measurable preference for fully traceable stones with blockchain-registered provenance.
- Wire Drawing:Diamond die production for metal filament reduction. Stable demand persists from copper and steel processing facilities despite thinner margins compared to gemstone applications.
- Electronics:Heat spreader substrates and quantum sensing components leveraging nitrogen-vacancy center properties. Semiconductor manufacturers are integrating synthetic diamond wafers for 5G infrastructure thermal management.
- Optical Components:Infrared windows and laser exit ports exploiting diamond's transparency and thermal conductivity. Defense and medical imaging equipment specifications are driving purity requirements.
Revenue weight sits with Jewelry Manufacturing. Electronics is gaining share fastest.
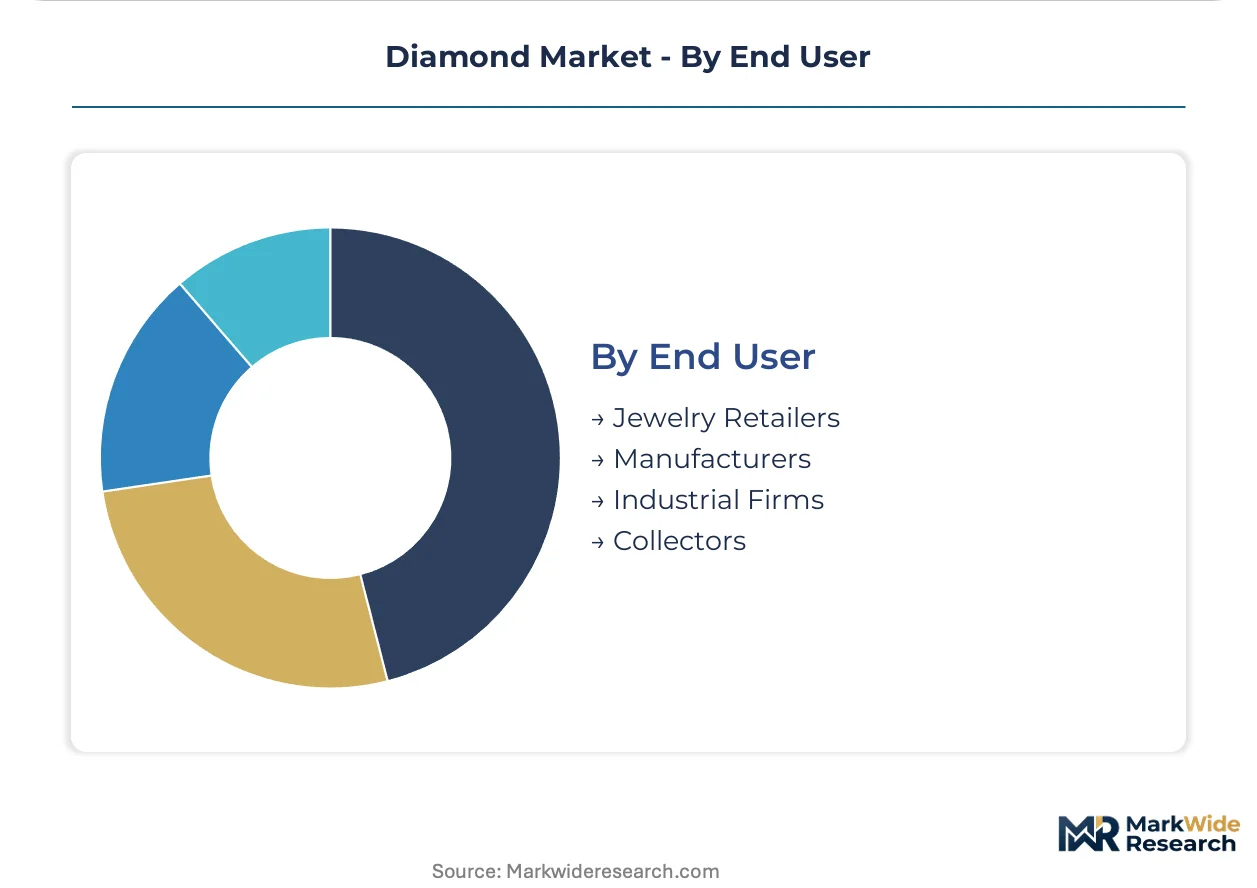
End User:
Buyer sophistication ranges from specification-driven industrial procurement to emotion-influenced retail selection, with channel economics diverging accordingly.
- Jewelry Retailers:Branded and independent storefronts serving bridal and fashion segments. European luxury houses are restructuring supplier contracts to secure documented mine-to-market documentation under forthcoming due diligence rules.
- Manufacturers:Industrial tool producers and precision component fabricators. In-house chemical vapor deposition adoption is eroding traditional merchant middleman roles in thermal management supply chains.
- Industrial Firms:Mining, construction, and materials processing operations consuming abrasive and cutting tools. Stable replacement demand characterizes this segment despite price sensitivity.
- Collectors:Ultra-high-net-worth individuals and investment funds acquiring rare stones for portfolio diversification. Swiss and UAE trading centers concentrate auction activity for certified provenance assets.
Transaction volume flows primarily through Jewelry Retailers. Collector segment expansion is most rapid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Master polishers and gemstone cutters concentrate in India's Surat cluster, while mining engineers and geologists anchor operations in Russia's Siberian deposits. These workforce distributions shape regional competitive advantages across extraction, processing, and retail channels.
India
Surat processes the majority of global polished diamond volume, driven by bridal jewelry export demand to the United States and China. The Bureau of Indian Standards mandates hallmarking standards for retail gemstone sales. Gujarat's diamond cutting workshops are automating faceting processes to offset aging master craftsman shortages.
Russia
ALROSA's Siberian mines supply rough stones to state-backed distribution channels serving cutters in India and Belgium. Russian mining regulations prioritize strategic mineral resource control through federal licensing frameworks. Yakutia's Mirny and Udachny mining complexes maintain year-round extraction despite extreme Arctic conditions.
Belgium
Antwerp's diamond district handles rough valuation and sorting for distribution to Surat and Tel Aviv polishing centers. EU REACH regulations and forthcoming due diligence rules extend supply chain disclosure requirements beyond conflict minerals. The city's bourse infrastructure supports blockchain-enabled provenance tracking for luxury retail clients.
United States
Bridal jewelry consumption drives polished stone demand through New York and Los Angeles retail channels. FTC guidelines govern gemstone marketing disclosures, including synthetic versus natural origin labeling. Manhattan's 47th Street diamond district maintains wholesale trading relationships with Surat-based manufacturers.
China
Domestic jewelry retailers expand synthetic diamond collections for fashion-conscious consumers in Shanghai and Shenzhen. MIIT standards and dual carbon goals pressure manufacturers toward lower-emission production methods. Zhengzhou's chemical vapor deposition reactor manufacturers supply equipment for in-house semiconductor substrate production.
Diamond Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across extraction, processing, and retail verticals. State-backed mining conglomerates in Russia and Botswana control rough supply allocations, creating tiered access for independent polishers. Three archetypes dominate: vertically integrated miners with captive polishing networks, mid-market scale processors serving jewelry brands, and technology-driven synthetic producers. Competitive moves center on traceability technology investments and strategic partnerships with certification platform providers.
Within the state-backed mining tier, ALROSA and De Beers Group exemplify rough supply dominance through pipeline allocation control. Anglo American occupies a diversified resources position spanning extraction through downstream marketing. Among specialized processors, Kiran Gems represents Surat-based scale polishing operations for mid-market jewelry brands.
| Leading Market Players |
|---|
| Anglo American |
| Rosy Blue |
| De Beers Group |
| Bhavani Gems |
| Diarough NV |
| ALROSA |
| Kiran Gems |
| Lucara Diamond |
| Rio Tinto |
| Others |
Supply Flow & Price Mechanics
Bridal jewelry buyers in Germany and France are demanding blockchain-registered provenance documentation, forcing polishers to absorb certification costs and compressing margins on mid-market stones while premium tiers capture traceability premiums.
Pricing Analysis
Capacity additions in China's Zhengzhou reactor manufacturing base are reshaping price floors for synthetic diamond wafers used in semiconductor thermal management. Three-tier pricing structure across premium certified natural, standard polished, and economy industrial grades reflects differentiation by Kimberley Process certification status and carbon footprint scoring. Cost compression in fashion-grade synthetics is intensifying because microwave plasma reactor yields are improving. Industrial tool manufacturers show highest price sensitivity, while collector auction participants demonstrate lowest sensitivity to provenance premiums.
Supply Chain Analysis
Direct-to-retail channels handling bridal and fashion jewelry demand are displacing traditional wholesale tiers in European and North American markets. Rough supply concentrates in Russia's Yakutia deposits and Botswana's Orapa mine, with polished goods flowing through India's Surat cluster. Plasma reactor equipment, high-purity methane feedstock, and skilled master cutters constitute critical input dependencies. Single-source vulnerability sits with ALROSA's pipeline allocations to state-backed distribution channels. Distribution runs through Antwerp's sorting houses for rough valuation before Surat processing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through synthetic production scale economies and certified provenance premiums in bridal segments, with automation offsetting craftsman scarcity costs.
For Market Incumbents: Anticipate EU due diligence rule implementation by restructuring supplier contracts to secure documented mine-to-market chains. Invest in real-time spectroscopic monitoring for chemical vapor deposition reactors to defend against in-house semiconductor manufacturer adoption. Prioritize backward integration into rough supply through offtake agreements with Russian and Botswana state mining conglomerates.
For New Entrants and Emerging Players: Blockchain certification platform providers offer partnership pathways to bypass entrenched wholesale tiers. Vietnam and Indonesia bridal markets present white-space expansion potential as middle-class formation accelerates formalized jewelry purchasing. Target direct-to-consumer channels with carbon-neutral synthetic collections positioned under EU Carbon Border Adjustment Mechanism compliance messaging.
For Investors and Strategic Acquirers: Asymmetric upside sits with synthetic diamond reactor manufacturers serving semiconductor thermal management demand. Five-to-ten year viability favors technology-driven producers with proprietary microwave plasma reactor designs over commodity polishers facing craftsman attrition. Watch nitrogen-vacancy center diamond adoption in quantum sensing applications as inflection signal for premium valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rough Supply | Secures pipeline allocations from ALROSA and De Beers Group against allocation uncertainty. |
| Blockchain Provenance Platform Partnership | Enables European luxury houses to meet forthcoming EU due diligence disclosure requirements. |
| Microwave Plasma Reactor Scale-Up | Expands synthetic wafer output for 5G infrastructure heat spreader demand from semiconductor OEMs. |
| Master Craftsman Apprenticeship Programs | Addresses faceting skill scarcity in Antwerp and Tel Aviv bespoke bridal segments. |
| Direct-to-Consumer Certification Launch | Bypasses wholesale margin extraction for mid-market synthetic fashion jewelry collections. |
Methodological Framework
Multiple input streams — primary interviews with rough diamond traders, polished goods manufacturers, and jewelry retail procurement heads; secondary validation through Kimberley Process certificate databases, BIS hallmarking records, and SEC mining conglomerate filings; plus customs trade data from India and Belgium — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across supply-side capacity assessments and demand-side procurement surveys informed analytical framework construction across the analysis window. Segmentation dimensions modeled include crystalline origin, processing stage, application intensity, and end-user sophistication tier. CAGRs were derived from volume trajectory analysis calibrated against value chain margin compression patterns and synthetic production yield improvements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Carbon Border Adjustment Mechanism enforcement timelines and skilled cutter attrition rates in traditional polishing centers. Forecasts reflect assumptions about plasma reactor yield curves and bridal market traceability preference stickiness. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Sodium Tungstate Market
Metals & Minerals
Chromite Market
Metals & Minerals
Cesium Market
Metals & Minerals
Testing Inspection and Certification TIC for the Metals and Minerals Market
Metals & Minerals
Middle-East and Africa Lithium Market
Metals & Minerals
Bauxite Mining Market
Metals & Minerals
Global Fabricated Metal Products Market
Metals & Minerals
Middle-East and Africa Sodium Sulfide Market
Metals & Minerals
Selenium Market
Metals & Minerals
Direct Reduced Iron (DRI) Market
Metals & Minerals
Zinc Citrate Market
Metals & Minerals
Prefab Iron Market
Metals & Minerals
Boron Ore Market
Metals & Minerals
India Colored Gemstones Market
Metals & Minerals
Selenium Mining Market
Metals & Minerals
Dolomite Market