
 Flake Graphite Market | 2026-2036
Flake Graphite Market Size, Share, and Industry Trends Forecast 2026-2036
Flake Graphite Market Analysis
Automotive battery makers is collapsing the historical buyer mix that favored steel refractory and lubricant offtake. GrafTech International leverages its vertical integration from mine to battery-grade purification to sustain pricing power in anode material contracts. SGL Carbon SE anchors European supply security through specialized synthetic flake production. BTR New Material Group dominates spherical graphite processing capacity, while NextSource Materials positions its Madagascar asset as a traceable alternative to Asian concentrate.
Flake graphite consists of crystalline carbon arranged in layered hexagonal sheets with flake sizes ranging from fine (+80 mesh) to jumbo (+50 mesh), typically assaying carbon content between carbon content between 80% and 99.9% depending on beneficiation intensity. Natural flake commands structural priority in battery anode applications due to superior crystallinity and conductivity compared to amorphous alternatives. The application split reveals batteries as the fastest-expanding margin pool while lubricants and fireproofing represent mature, volume-stable segments with lower price elasticity. Among end users, energy sector procurement is reshaping supplier qualification protocols, whereas electronics manufacturers maintain stringent purity specifications that filter out smaller producers.
China's MIIT enforces GB standards for battery-grade graphite purity, while the EU's CSRD and battery passport regulations mandate supply chain traceability from extraction to cell assembly. The EPA in the United States monitors air emissions from graphite processing facilities under Clean Air Act provisions, constraining expansion timelines for domestic purification plants. Stakeholders must monitor evolving jurisdiction-specific carbon intensity thresholds that threaten to disqualify coal-based processing routes from qualifying for clean energy procurement programs.
Market Dynamics
Battery-grade flake graphite procurement is concentrating around vertically integrated mine-to-purification assets as automakers enforce supply chain traceability from extraction through cell assembly. This structural pull is collapsing the historical buyer mix that favored steel refractory and lubricant offtake, forcing concentrate producers to requalify purification streams for anode specifications.
Growth Catalysts
- EU Battery Passport Mandate:The EU Green Deal's traceability requirements are accelerating qualification of non-Chinese feedstock sources as cell manufacturers seek compliant concentrate supply chains.
- Electric Vehicle Anode Demand:Lithium-ion battery manufacturers are expanding spherical graphite processing capacity to serve tightening electric vehicle mandates across multiple jurisdictions.
- Mozambique's Montepuez District:Concentrate production from this corridor is securing offtake agreements with battery makers seeking geographic diversification beyond traditional Asian supply.
Market Restraints
- Coal-Based Processing Carbon Intensity:China's dual carbon goals and EU carbon border adjustments threaten to disqualify coal-powered beneficiation routes from clean energy procurement programs.
- High-Purity Purification Capex:Battery-grade spherical graphite production requires acid leaching and thermal purification infrastructure that demands substantial capital deployment with extended payback periods.
- Amorphous Graphite Substitution:Lower-cost synthetic and amorphous alternatives retain share in refractory and lubricant applications where crystallinity requirements are less stringent.
Strategic Opportunities
- Madagascar's Ambatofinandrahana Corridor:NextSource Materials and similar developers are positioning traceable concentrate assets as alternatives to Asian supply for European battery passport compliance.
- Silicon-Graphite Composite Anodes:Converging silicon nanowire and flake graphite blending technologies are opening higher-energy-density cell architectures for premium electric vehicle platforms.
- US Domestic Purification Plants:The EPA's Clean Air Act oversight creates first-mover advantage for developers securing air permits and offtake agreements ahead of constrained expansion timelines.
Industry Challenges
- Spherical Graphite Metallurgist Shortage:Qualified process engineers capable of optimizing yield and purity in spherical graphite production remain concentrated among Chinese and Japanese specialists.
- Multi-Jurisdiction Certification Timelines:Simultaneous qualification under China's GB standards, EU REACH registrations, and US EPA facility permits extends product approval cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flake Graphite Market |
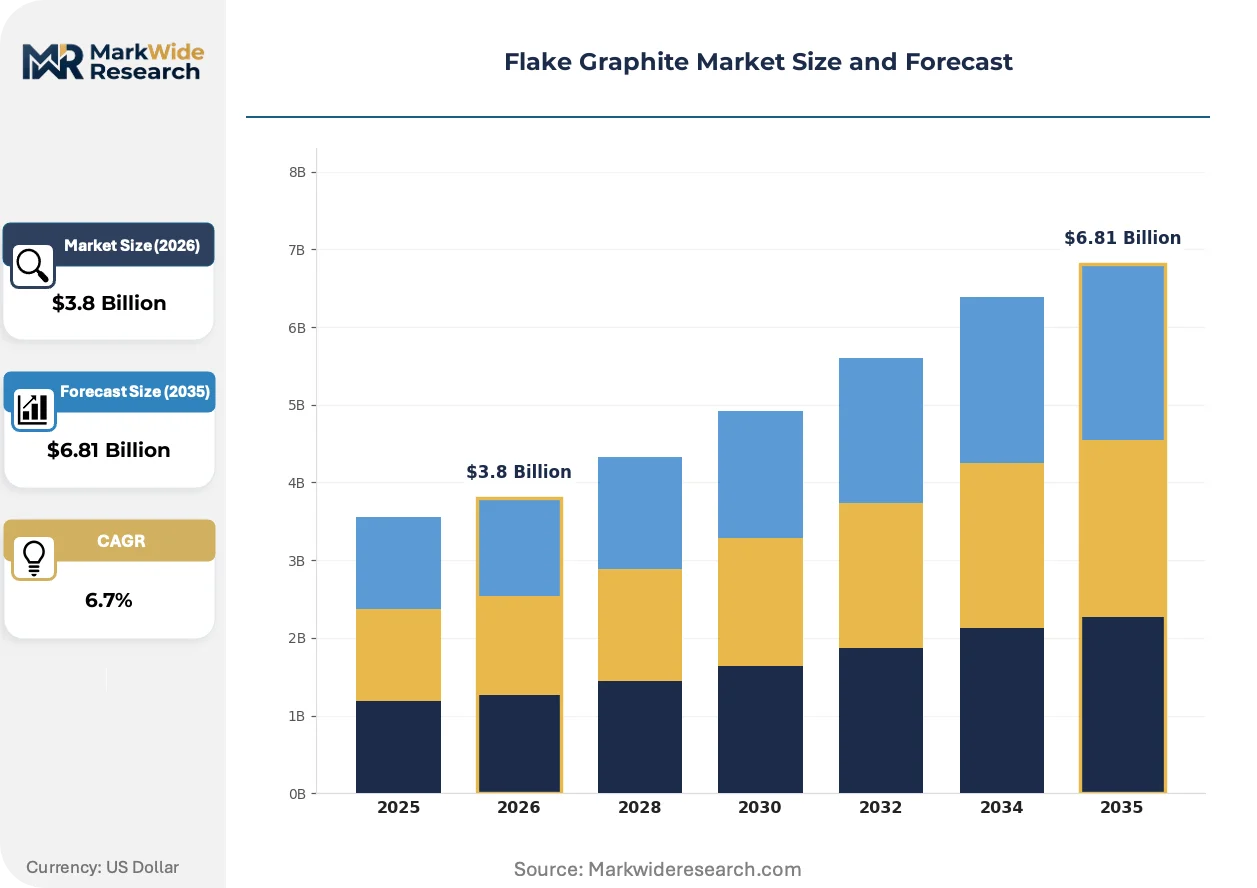
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flake, Synthetic Flake, Coated Flake, Expanded Flake Application: Batteries, Lubricants, Fireproofing, Electronics End User: Aerospace, Automotive Parts, Energy Sector, Electronics Manufacturers Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | GrafTech International Ltd., Nacional de Grafite, Fangda Carbon New Material Co., Ltd., SGL Carbon SE, NextSource Materials Inc., BTR New Material Group Co., Ltd., Graphite India Limited, Eagle Graphite, Graphit Kropfmühl GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flake Graphite Market Emerging Trajectories
Thermal and chemical purification technologies are advancing rapidly as battery makers tighten carbon content specifications for anode material. These process innovations are compressing the competitive set to operators with integrated beneficiation capabilities.
Mechanochemical exfoliation is displacing traditional acid-leaching routes for intermediate purity grades. Mid-tier battery manufacturers are adopting this lower-capex pathway to secure flake graphite feedstock for energy storage applications. The technology is displacing incumbent thermal purification vendors from the standard-grade anode material tier by reducing energy intensity and facility scale requirements.
China's MIIT enforcement of updated GB standards for battery-grade graphite purity is tightening impurity thresholds for sulfur, ash, and trace metals. Domestic concentrate producers must retrofit flotation and leaching circuits to maintain qualification for domestic cell manufacturer supply agreements. Synthetic graphite specialists in Japan and South Korea are accelerating pilot production to capture margin from stricter natural flake specifications.
Automotive OEMs are consolidating anode material procurement through direct offtake agreements with mine developers, bypassing traditional merchant concentrate traders. This channel compression is most visible in European and North American markets where Volkswagen, Tesla, and Ford have established direct supply relationships with Madagascar and Mozambique projects. The shift is forcing merchant traders to pivot toward smaller electronics and industrial buyers with less stringent traceability requirements.
Flake Graphite Market Segmentation
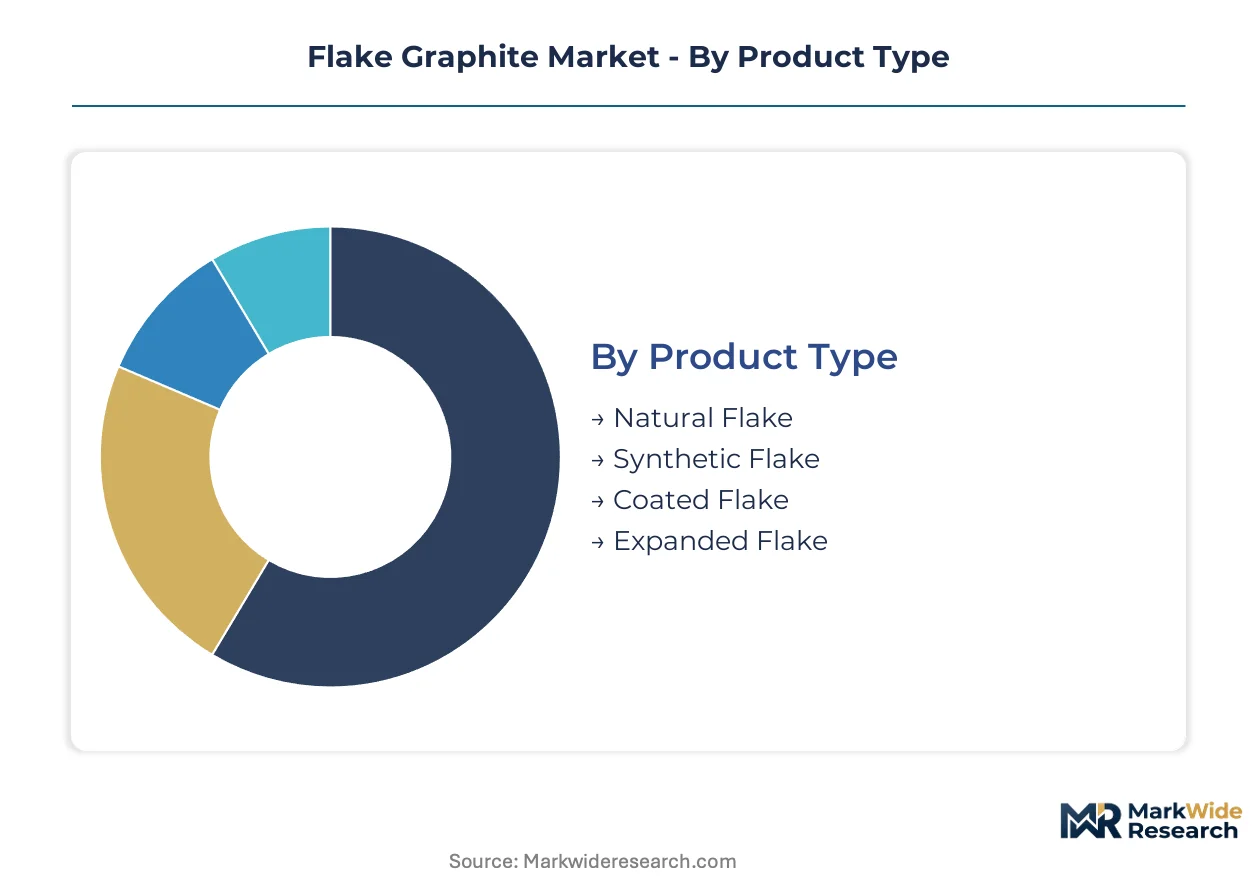
Segmentation in flake graphite reveals how substitution pressures and purity requirements reshape procurement patterns across battery, industrial, and specialty tiers. Understanding these divisions exposes which channels capture margin compression from synthetic alternatives and which retain pricing power through specification lock-in.
Product Type:
Natural flake faces the strongest substitution threat from synthetic alternatives in lower-specification applications, while coated and expanded variants defend position through performance differentiation that amorphous grades cannot replicate.
- Natural Flake:Crystalline carbon arranged in layered hexagonal sheets with carbon content ranging from 80% to 99.9% depending on beneficiation intensity. Battery anode procurement concentrates in Mozambique's Montepuez district and Madagascar's Ambatofinandrahana corridor as automakers enforce supply chain traceability requirements. The EU Battery Passport mandate accelerates qualification of these non-Chinese feedstock sources.
- Synthetic Flake:Manufactured through high-temperature graphitization of petroleum coke or pitch precursors, delivering consistent purity above 99.9% without geological impurity variation. SGL Carbon SE anchors European supply security through specialized production as domestic concentrate sources remain limited. Japan and South Korean specialists are accelerating pilot production to capture margin from stricter natural flake specifications.
- Coated Flake:Surface-modified variants with carbon or ceramic layers enhancing electrochemical stability in lithium-ion anodes.
- Expanded Flake:Thermally exfoliated material with expanded interlayer spacing serving fireproofing and thermal management applications.
Natural flake retains volume leadership; synthetic flake holds the steepest expansion curve as battery-grade purification requirements tighten.
Application:
Cost tier stratification separates premium battery-grade specifications from commoditized industrial uses where amorphous graphite competes aggressively on price.
- Batteries:Spherical graphite processed from jumbo flake (+50 mesh) commands structural priority in lithium-ion anodes due to superior crystallinity and conductivity. Volkswagen, Tesla, and Ford have established direct offtake agreements with Madagascar and Mozambique projects, bypassing traditional merchant concentrate traders. Thermal and chemical purification technologies are compressing the competitive set to operators with integrated beneficiation capabilities.
- Lubricants:Fine flake (+80 mesh) serves mature industrial demand with lower price elasticity and stable volume requirements. This segment faces persistent pressure from synthetic alternatives and petroleum-based lubricant formulations that erode natural graphite share in heavy machinery applications.
- Fireproofing:Expanded flake provides thermal barrier properties in construction materials and protective equipment.
- Electronics:Ultra-high-purity grades meet stringent specifications filtering out smaller producers from semiconductor and display manufacturing supply chains.
Lubricants retain volume leadership; batteries gain share fastest as electric vehicle mandates tighten across multiple jurisdictions.
End User:
Customer type differentiation separates energy sector procurement with traceability protocols from industrial buyers with less stringent qualification requirements.
- Energy Sector:Grid-scale battery storage and electric vehicle cell manufacturers reshape supplier qualification protocols through direct offtake agreements. Procurement concentrates around vertically integrated mine-to-purification assets as automakers enforce supply chain visibility from extraction through cell assembly.
- Automotive Parts:Brake linings, gaskets, and sealing applications utilize standard-grade flake with established supply relationships through traditional merchant channels.
- Aerospace:Thermal management and lubrication applications demand certified material with full batch traceability.
- Electronics Manufacturers:Display and semiconductor fabrication maintain purity specifications that exclude concentrate producers lacking acid leaching and thermal purification infrastructure.
Automotive parts retain volume leadership; energy sector holds the steepest expansion curve through direct procurement channel compression.
Distribution Channel:
Supply concentration patterns favor direct relationships for battery-grade material while distributors retain relevance in fragmented industrial segments.
- Direct Sales:Long-term offtake agreements dominate battery-grade procurement as automotive OEMs consolidate anode material sourcing. This channel captures the premium tier where traceability and qualification timelines justify relationship-specific contracting.
- Distributors:Merchant traders pivot toward smaller electronics and industrial buyers with less stringent traceability requirements as direct sales capture battery-grade volume.
- Online Sales:Digital procurement platforms serve spot market requirements and smaller volume buyers.
- Retail:Limited presence confined to specialty lubricant and hobbyist applications.
Distributors retain volume leadership; direct sales climb the fastest as channel compression accelerates in European and North American markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mozambique exports Montepuez corridor concentrate to European battery makers seeking EU Battery Passport compliance. Madagascar's Ambatofinandrahana deposits feed direct offtake agreements with North American automakers. Chinese spherical graphite processors retain dominant purification capacity despite geographic diversification pressures.
China
MIIT enforces updated GB standards tightening sulfur and trace metal thresholds for battery-grade material. Domestic concentrate producers retrofit flotation circuits to maintain qualification for cell manufacturer supply agreements. Heilongjiang and Shandong provinces host spherical graphite processing clusters where mechanochemical exfoliation displaces thermal purification vendors.
United States
EPA Clean Air Act oversight constrains expansion timelines for domestic purification plants as developers secure air permits. The Inflation Reduction Act's domestic content incentives accelerate mine-to-battery supply chain investments. Texas and Louisiana coastal zones attract spherical graphite facility proposals targeting Gulf Coast logistics.
Germany
EU CSRD and battery passport regulations mandate supply chain traceability from extraction through cell assembly. SGL Carbon SE anchors European synthetic flake production as domestic concentrate sources remain limited. Bavaria's advanced materials corridor hosts pilot facilities for silicon-graphite composite anode development.
Mozambique
Montepuez district concentrate production secures offtake agreements with battery makers seeking geographic diversification. The country's national mining regulator enforces environmental compliance standards aligned with EU import requirements. Cabo Delgado province's graphite belt attracts vertically integrated project development from Australian and Canadian mining firms.
Madagascar
NextSource Materials positions Ambatofinandrahana corridor assets as traceable alternatives to Asian concentrate for European compliance. The national mining cadastre issues permits under revised environmental codes addressing carbon intensity disclosure. Toamasina province hosts emerging export infrastructure serving Indian Ocean shipping routes to Asian and European markets.
Flake Graphite Market Vendor Landscape
Listed leaders compete with private specialists across capital access and project development velocity. The market structures around three tiers: integrated mine-to-purification operators, merchant concentrate traders, and synthetic graphite specialists. Strategic archetypes include vertically integrated battery-grade producers, African mine developers, and Asian spherical graphite processors. Dominant competitive moves encompass direct offtake contracting with automotive OEMs and backward integration into mining assets.
Among North American-listed developers, NextSource Materials exemplifies the African mine developer archetype positioning traceable concentrate assets. SGL Carbon SE represents European synthetic flake specialization serving supply security mandates. GrafTech International occupies a position within the integrated tier leveraging captive purification infrastructure. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning across the qualification-intensive battery supply chain.
| Leading Market Players |
|---|
| GrafTech International Ltd. |
| Nacional de Grafite |
| Fangda Carbon New Material Co., Ltd. |
| SGL Carbon SE |
| NextSource Materials Inc. |
| BTR New Material Group Co., Ltd. |
| Graphite India Limited |
| Eagle Graphite |
| Graphit Kropfmühl GmbH |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements with automotive OEMs lock in both concentrate supply access and five-year price visibility for battery-grade spherical graphite, insulating integrated producers from spot market volatility while exposing merchant traders to margin compression.
Pricing Analysis
Thermal purification versus mechanochemical exfoliation pricing gaps are widening as mid-tier battery manufacturers adopt lower-capex processing routes. Three-tier pricing structure across battery-grade, industrial-grade, and refractory-grade levels reflects purity thresholds and carbon content specifications. Cost compression in standard-grade anode material is intensifying because mechanochemical vendors displace incumbent thermal purification suppliers. Merchant traders serving lubricant and fireproofing segments exhibit highest price sensitivity, whereas automotive OEMs with direct offtake agreements demonstrate lowest elasticity due to traceability requirements.
Supply Chain Analysis
Spherical graphite processing capacity concentration in China's Heilongjiang and Shandong provinces underwrites global battery anode supply security despite geographic diversification pressures. Feedstock draws from Mozambique's Montepuez district, Madagascar's Ambatofinandrahana corridor, and China's Heilongjiang mining clusters. Acid leaching reagents and thermal purification energy inputs rest on coal-powered beneficiation routes vulnerable to EU carbon border adjustments. Distribution runs through vertically integrated mine-to-purification assets for battery-grade material, while merchant channels retain relevance in fragmented industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flake graphite sits at early-cycle expansion as electric vehicle mandates tighten procurement protocols for anode material traceability from extraction through cell assembly.
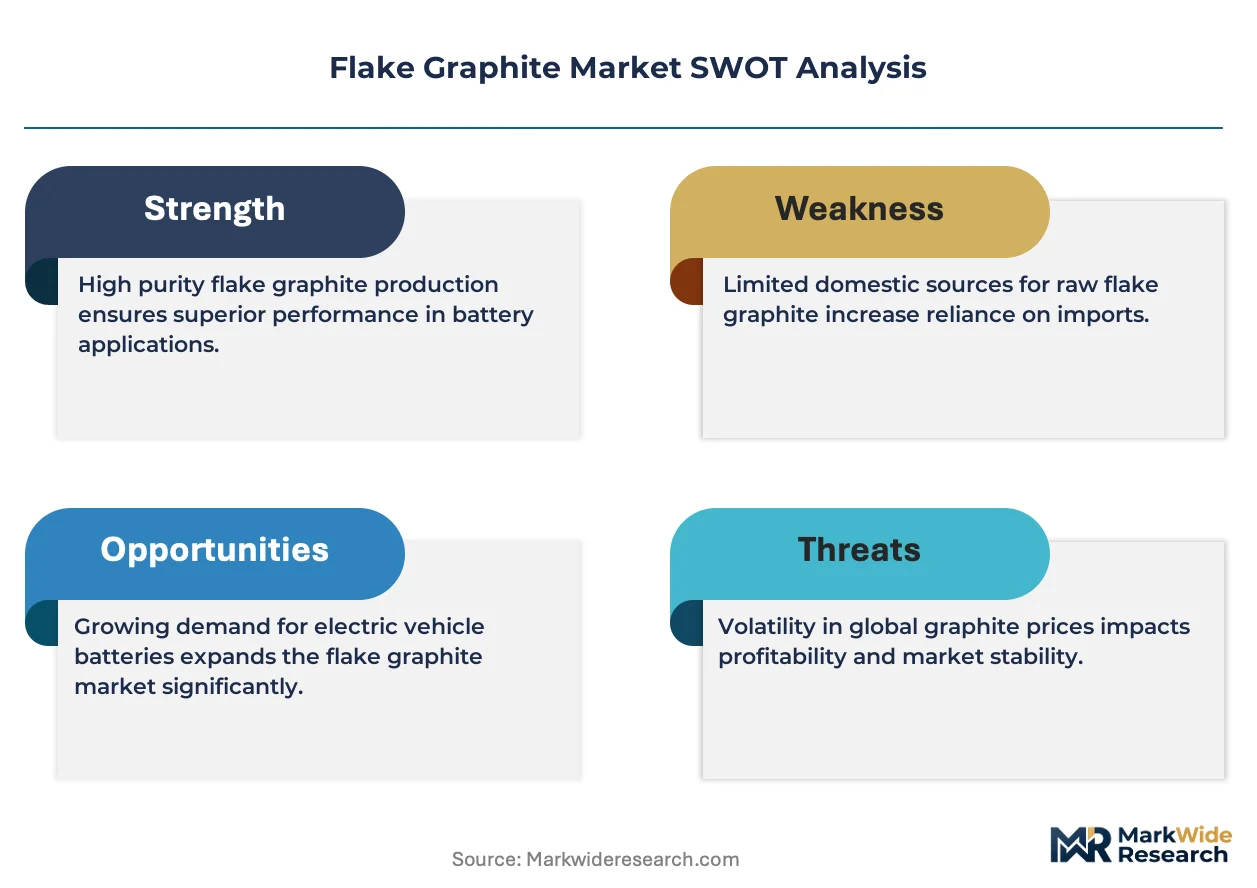
For Market Incumbents: Compound purification yield advantages through captive beneficiation infrastructure in Mozambique and Madagascar corridors. Automaker direct offtake agreements threaten merchant trader relevance; backward integration into spherical graphite processing secures margin retention. Investment in acid leaching and thermal purification capacity addresses stricter EU battery passport and China MIIT GB standards. For New Entrants and Emerging Players: Differentiate on EU battery passport compliance by positioning traceable concentrate assets outside Chinese supply chains. Madagascar's Ambatofinandrahana corridor offers most penetrable geography for European automaker qualification. Silicon-graphite composite anode pilot production provides differentiated go-to-market angle for premium electric vehicle platforms. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mine-to-purification operators with secured air permits under EPA Clean Air Act oversight. Five-to-ten year viability hinges on qualification timelines under multi-jurisdiction certification requirements. Watch spherical graphite metallurgist availability as inflection indicator for processing capacity expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mining Assets | GrafTech International secures captive concentrate supply for battery-grade purification infrastructure. |
| Green Manufacturing Transition | Mechanochemical exfoliation reduces carbon intensity to meet EU carbon border adjustment thresholds. |
| Long-term Supply Agreement | Volkswagen, Tesla, and Ford direct offtake contracts bypass merchant concentrate traders. |
| Joint Venture | SGL Carbon SE anchors European synthetic flake production amid limited domestic concentrate sources. |
| Capacity Expansion | Texas and Louisiana spherical graphite facilities target Gulf Coast logistics under IRA domestic content incentives. |
Methodological Framework
Cross-validation between primary interviews with spherical graphite plant managers, automotive OEM procurement leads, and battery cell manufacturer supply chain directors anchors the qualitative findings against secondary validation from China MIIT GB standard filings, EU battery passport regulatory texts, and SEC 10-K disclosures from listed graphite producers. Bottom-up concentrate production estimates from Mozambique and Madagascar mining jurisdictions triangulate against top-down battery anode demand projections.
Sensitivity analysis across flake size distribution, carbon content thresholds, and purification technology adoption rates shapes the analytical framework throughout the forecast period. Segmentation dimensions include product type, application tier, end-user category, and geographic production cluster. CAGRs derive from installed spherical graphite processing capacity expansion trajectories and electric vehicle mandate enforcement timelines across multiple jurisdictions.
Material uncertainties — regulatory revision to EU carbon border adjustments, EPA air permit issuance delays, and spherical graphite metallurgist labor pool constraints — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as jurisdiction-specific carbon intensity thresholds and battery passport traceability requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Cobalt Nitrate Market
Metals & Minerals
Global Ferrous Scrap Recycling Market
Metals & Minerals
Tantalum Pentoxide Market
Metals & Minerals
Chromium Mining Market
Metals & Minerals
Colored Gemstones Market
Metals & Minerals
Global Artificial Rutile Market
Metals & Minerals
Beryllium Hydroxide Market
Metals & Minerals
Sapphire Mining Market
Metals & Minerals
Nickel Mining Market
Metals & Minerals
Zellerite Market
Metals & Minerals
Chromite Market
Metals & Minerals
Electrolytic Manganese Dioxide Market
Metals & Minerals
Solder Materials Market
Metals & Minerals
Andalusite Market
Metals & Minerals
Cobalt Sulphate Market
Metals & Minerals
Mexico Mining Market