
 Frac Sand Market | 2026-2036
Frac Sand Market Size, Share, and Industry Trends Forecast 2026-2036
Frac Sand Market Analysis
Modular unit-train loading and destination-specific blending is broadening procurement flexibility for E&P buyers. US Silica Holdings leverages integrated rail-to-wellsite logistics to sustain volume commitments across multiple basins. Covia Holdings anchors its position through control of Northern White deposits in Wisconsin and Minnesota. Smart Sand competes on proximity to Permian demand centers, reducing last-mile trucking costs for operators.
Frac sand consists of high-purity silica quartz grains, typically 0.1 to 2 millimeters in diameter, mined and processed to meet American Petroleum Institute sphericity and crush-resistance specifications for hydraulic fracturing applications. The material functions as a proppant, holding induced fractures open to enable hydrocarbon flow from tight formations. Northern White sand commands premium positioning due to superior crush strength and turbidity performance in deep well applications. Brown sand occupies volume-driven segments where shallower wells and lower closure stresses reduce technical requirements. Oil extraction applications generate the dominant share of value, though natural gas extraction in Appalachia and Haynesville represents an expanding demand corridor.
OSHA enforces permissible exposure limits for respirable crystalline silica at hydraulic fracturing sites, while EPA ambient air standards shape permitting timelines for new mine developments. State-level regulators in Wisconsin and Texas impose additional reclamation and water-use conditions that extend project lead times. Stakeholders must monitor evolving proppant substitution dynamics, as resin-coated alternatives and ceramic formulations challenge raw sand economics in high-stress well environments.
Market Dynamics
Permian Basin operators are driving proppant intensity per well to record levels, while OSHA silica exposure enforcement and EPA mine permitting delays compress supply response times across North American supply chains.
Growth Catalysts
- Proppant Intensity Surge:Horizontal laterals in Texas and New Mexico now consume 50,000 tons per well, up from 15,000 tons a decade ago. This structural step-change in consumption per completion underpins volume expansion regardless of rig count fluctuations.
- OSHA Respirable Crystalline Silica Standard:Tighter workplace exposure limits at hydraulic fracturing sites are accelerating investment in dust suppression and closed-loop handling systems, creating equipment upgrade cycles that sustain service-provider revenues.
- Logistics Infrastructure Density:Unit-train terminals and transload facilities in Midland-Odessa, Kermit, and Monahans compress delivered costs to wellsite, enabling just-in-time inventory models that reduce operator working capital requirements.
Market Restraints
- Input Cost Volatility:Diesel prices and railcar lease rates swing with crude oil benchmarks, eroding margin predictability for mine-to-wellsite logistics operators who cannot pass through fuel surcharges on fixed-price contracts.
- Supply Concentration Risk:Northern White sand deposits in Wisconsin and Minnesota face depletion timelines and community opposition to new open-pit permits, constraining access to premium crush-strength material for deep well applications.
- Resin-Coated Substitution:Engineered proppants with polymer coatings deliver superior performance in high-closure-stress environments above 8,000 psi, threatening raw sand economics in the most technically demanding well segments.
Strategic Opportunities
- Haynesville Gas Corridor:Louisiana and East Texas dry gas development is reviving as LNG export capacity expands, creating incremental demand for 40/70 mesh sand in high-rate gas completions that prioritize conductivity over crush strength.
- Last-Mile Rail Integration:Destination-specific blending at origin terminals enables custom grain-size mixes without intermediate handling, reducing silica exposure points and cutting trucking miles from transload to wellsite.
- Reclamation Liability Arbitrage:Wisconsin's progressive mine rehabilitation bonding requirements have stalled greenfield projects, rewarding incumbents with grandfathered permits and established reclamation trust structures.
Industry Challenges
- Silica Competency Shortage:Industrial hygienists certified for respirable crystalline silica monitoring command premium wages, constraining expansion of in-house compliance teams at mid-sized logistics providers.
- Permitting Timeline Compression:EPA ambient air quality demonstrations and state water-use permits now stretch 18-24 months for Wisconsin greenfield sites, misaligning supply investment with demand cycle peaks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frac Sand Market |
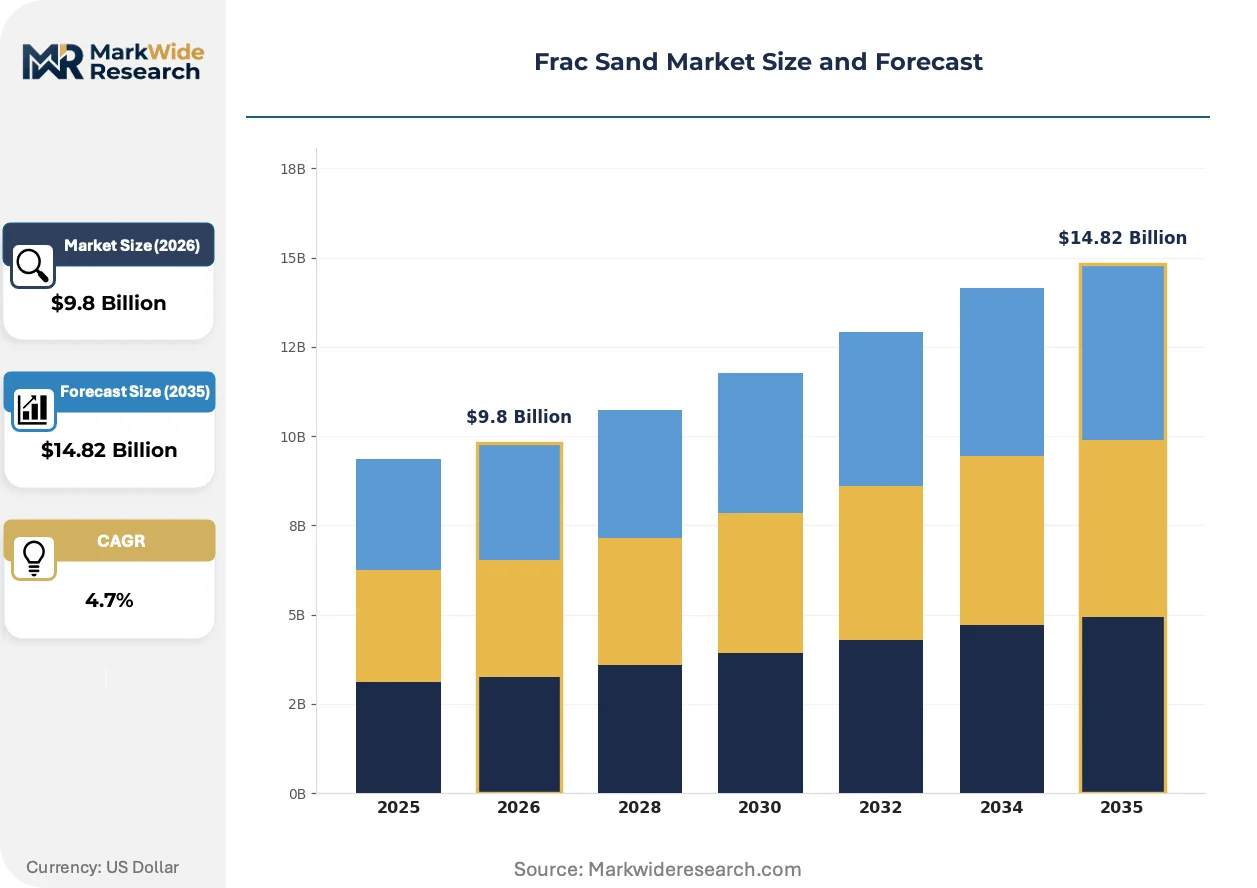
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.82 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Northern White, Southern White, Brown, Others Application: Oil Extraction, Natural Gas Extraction, Industrial Uses, Construction Delivery Mode: Open-Pit Mining, Hydraulic Mining, Dredging, Others End User: Oil & Gas Industry, Construction Firms, Chemical Manufacturing, Energy Sector |
| Companies Covered | Badger Mining Corporation, CARBO Ceramics, US Silica Holdings, Preferred Sands, Smart Sand, Hi-Crush Inc, Covia Holdings, Chieftain Sand, Emerge Energy Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frac Sand Market Emerging Trajectories
Digital logistics platforms and real-time proppant tracking are compressing inventory cycles, while regulatory pressure on silica exposure accelerates automation investments across the mine-to-wellsite chain.
Resin-coated sand is expanding into intermediate-depth shale plays where closure stresses of 6,000-8,000 psi previously favored raw Northern White material. Bakken and Eagle Ford operators are adopting hybrid load designs blending coated and uncoated proppants to optimize cost-performance ratios. This technology is expanding into volume-driven segments by reducing the premium gap versus raw sand through manufacturing scale efficiencies.
EPA's National Ambient Air Quality Standards for particulate matter are extending permitting timelines for new Wisconsin mine developments, forcing supply growth to concentrate in Texas brown sand expansion. State regulators in Barron and Chippewa counties are imposing additional groundwater monitoring requirements that add six to nine months to project schedules. Northern White producers are responding by deepening existing pits rather than pursuing greenfield approvals.
Operator procurement teams are consolidating supplier relationships around integrated rail-to-wellsite providers capable of destination blending and real-time inventory visibility. This consolidation displaces spot-market purchasing through regional sand brokers who lack transload assets. The shift is most visible in Permian operations where pad drilling schedules demand guaranteed proppant availability across multi-well zipper completion programs.
Frac Sand Market Segmentation
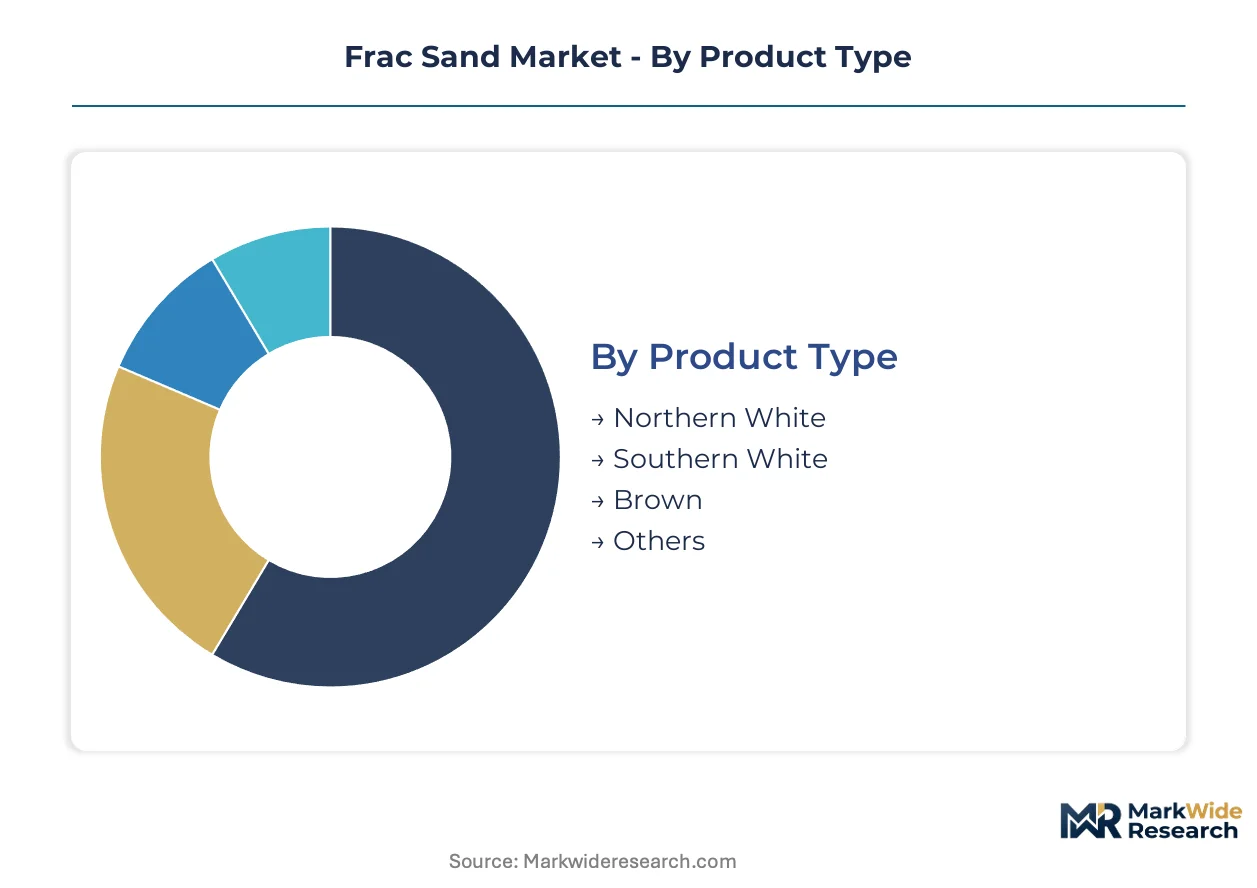
Frac sand procurement decisions hinge on crush-resistance specifications, logistics proximity, and regulatory compliance costs. Each segmentation dimension reveals distinct margin structures and capital intensity requirements across the value chain.
Product Type:
The customization-standardization spectrum runs from premium Northern White with strict API sphericity tolerances to commoditized Brown sand with minimal processing.
- Northern White:High-purity silica quartz from Wisconsin and Minnesota deposits delivers superior crush strength above 8,000 psi closure stress. Demand concentrates in Permian Basin deep laterals where turbidity and roundness specifications justify rail haul economics from upper Midwest mines.
- Brown:Lower-purity deposits in Texas and Oklahoma require minimal beneficiation, serving shallow well segments where closure stresses fall below 6,000 psi. Kermit and Monahans production clusters feed Permian operators through 50-mile trucking radii, eliminating unit-train logistics.
- Southern White:Arkansas and Alabama deposits offer intermediate crush characteristics for mid-depth shale plays.
- Others:Regional specialty sands including resin-coated variants and ceramic proppants for extreme stress environments.
Leading the category by volume: Brown. Expanding most quickly: Northern White in deep Permian applications.
Application:
Revenue concentration follows hydrocarbon price differentials and completion intensity trends across basins.
- Oil Extraction:Horizontal fracturing in tight oil formations consumes 50,000 tons per Permian well, with proppant representing 10% of total drilling and completion costs. Midland-Odessa logistics infrastructure anchors North American supply chains for this segment.
- Natural Gas Extraction:Haynesville and Appalachia dry gas development prioritizes 40/70 mesh conductivity over crush strength, creating demand for smaller grain sizes in high-rate completions feeding LNG export capacity.
- Industrial Uses:Foundry, glass manufacturing, and water filtration applications compete for Northern White supply during oilfield demand troughs.
- Construction:Concrete and masonry applications absorb lower-specification Brown sand from regional quarries.
Dominant revenue share: Oil Extraction. Steepest expansion trajectory: Natural Gas Extraction tied to Gulf Coast LNG export growth.
Delivery Mode:
Capital deployment intensity varies from heavy equipment open-pit operations to lower-fixed-cost dredging systems.
- Open-Pit Mining:Wisconsin and Minnesota Northern White extraction requires 18-24 month permitting timelines through EPA ambient air quality demonstrations and state water-use approvals, constraining supply response to demand spikes.
- Hydraulic Mining:Texas brown sand operations utilize high-pressure water jets to slurry ore through pipelines to wet processing plants, reducing diesel-powered haul truck requirements.
- Dredging:Limited domestic application for riverine deposits with lower silica purity profiles.
- Others:In-situ recovery and underground mining for specialty geological formations.
Highest volume throughput: Open-Pit Mining. Gaining share fastest: Hydraulic Mining in Texas Permian supply zones.
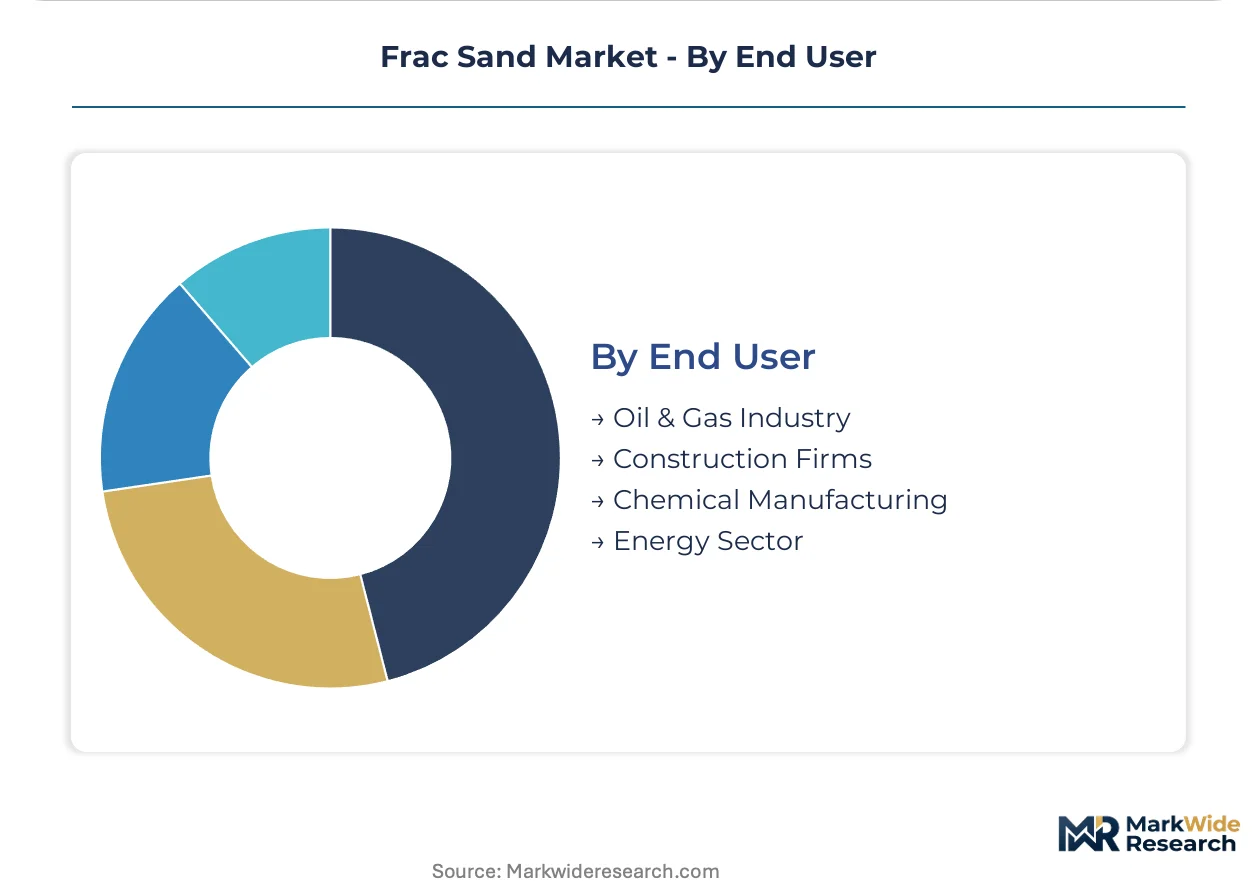
End User:
Procurement sophistication diverges between integrated E&P operators with dedicated logistics teams and fragmented construction buyers.
- Oil & Gas Industry:Supermajors and independents negotiate multi-year volume commitments with integrated rail-to-wellsite providers, demanding real-time inventory visibility and destination-specific blending capabilities.
- Construction Firms:Regional contractors source through aggregate distributors with limited technical specification requirements.
- Chemical Manufacturing:Specialty silica buyers for silicon metal and sodium silicate production compete for Northern White supply consistency.
- Energy Sector:Utility-scale sand storage and emergency fuel stockpile programs create non-cyclical demand pockets.
Largest procurement volume: Oil & Gas Industry. Growing fastest: Chemical Manufacturing as semiconductor supply chain reshoring accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midland-Odessa logistics corridors function as special economic zones for proppant distribution, concentrating unit-train terminals and transload infrastructure within 50-mile radii of Permian drilling pads.
United States
Horizontal laterals in Texas and New Mexico now consume 50,000 tons per well, driving record proppant intensity. EPA ambient air quality standards extend Wisconsin mine permitting timelines to 18-24 months. Wisconsin's Barron and Chippewa counties anchor Northern White supply through grandfathered open-pit operations with established reclamation trusts.
Canada
Alberta's Montney and Duvernay formations generate demand for 40/70 mesh sand in high-rate gas completions feeding Pacific LNG export terminals. Health Canada workplace exposure guidelines for respirable crystalline silica align with OSHA thresholds, standardizing cross-border logistics compliance. Grande Prairie logistics clusters serve as transload points for Wisconsin-origin unit trains.
Mexico
Burgos Basin dry gas development creates incremental demand for conductivity-optimized proppants in high-stress carbonate formations. Mexico's Secretariat of Environment and Natural Resources imposes water-use monitoring requirements on surface mining operations. Nuevo León industrial corridors near Monterrey host emerging transload infrastructure for Permian-sourced brown sand.
Saudi Arabia
Jafurah Basin unconventional gas development prioritizes proppant supply security for high-volume hydraulic fracturing campaigns. Saudi Aramco's domestic supplier qualification programs mandate API crush-resistance certification for all imported silica products. Eastern Province logistics hubs near Dammam consolidate regional proppant inventory for wellsite delivery.
Argentina
Vaca Muerta shale operators face proppant cost pressures as imported Northern White sand transits through Chilean ports with 30-day lead times. Argentina's Secretariat of Mining requires provincial environmental impact assessments for new silica extraction permits. Neuquén Basin drilling contractors maintain strategic sand stockpiles to buffer against supply chain volatility.
Frac Sand Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies into integrated rail-to-wellsite operators, regional mine-to-transload providers, and resin-coated technology developers. Three archetypes dominate: logistics-integrated volume leaders controlling unit-train terminals, proximity-based brown sand miners serving 50-mile trucking radii, and engineered proppant innovators challenging raw sand economics. Capacity expansion and destination-specific blending capabilities constitute the dominant competitive moves as operators consolidate supplier relationships.
Among North American logistics-integrated operators, US Silica Holdings exemplifies the rail-to-wellsite archetype through multi-basin volume commitments. Covia Holdings anchors premium positioning through Northern White deposit control in Wisconsin and Minnesota. Smart Sand occupies the proximity-driven tier with Permian-adjacent production clusters reducing last-mile trucking costs. These three represent distinct strategic postures without implying specific market share or operational metrics.
| Leading Market Players |
|---|
| Badger Mining Corporation |
| CARBO Ceramics |
| US Silica Holdings |
| Preferred Sands |
| Smart Sand |
| Hi-Crush Inc |
| Covia Holdings |
| Chieftain Sand |
| Emerge Energy Services |
| Others |
Supply Flow & Price Mechanics
Captive rail-to-wellsite integration anchors supply position and pricing power for frac sand operators, compressing delivered costs through unit-train terminals while locking in multi-year volume commitments that insulate against spot-market volatility. This vertical control over logistics infrastructure enables just-in-time inventory models that reduce operator working capital requirements and sustain margin premiums.
Pricing Analysis
Short lead-time premiums reward operators with transload assets positioned within 50-mile trucking radii of Permian drilling pads, while spot inventory discounts erode margins for non-integrated brokers lacking destination blending capabilities. Three-tier pricing structure across premium Northern White, standard regional Brown, and economy unprocessed sand segments reflects crush-resistance certification and turbidity performance. Cost compression in economy tiers intensifies as Texas brown sand expansion floods shallow-well segments with minimal beneficiation requirements. Independent E&P operators exhibit highest price sensitivity, prioritizing delivered cost over API specification compliance.
Supply Chain Analysis
Direct-to-pad distribution channels handle hyperscale demand from Permian supermajors through dedicated unit-train terminals in Midland-Odessa, Kermit, and Monahans. Supply concentrates in Wisconsin and Minnesota for premium Northern White deposits, with Texas and Oklahoma anchoring volume-driven Brown sand production. Raw material dependencies center on high-purity silica quartz ore, diesel fuel for overburden removal, and railcar lease capacity for long-haul logistics. Single-source vulnerability from EPA permitting delays in Wisconsin greenfield sites threatens supply response times. Distribution runs through integrated rail-to-wellsite operators displacing regional sand brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Frac sand supply is structurally constrained by 18-24 month EPA permitting timelines in Wisconsin, propping pricing power for incumbent Northern White producers with grandfathered open-pit operations and established reclamation trusts.
For Market Incumbents: Hedge against resin-coated substitution by deepening destination-specific blending capabilities at origin terminals, reducing silica exposure points while defending volume commitments. Secure backward integration into unit-train railcar fleets to buffer against lease rate volatility that erodes margin predictability on fixed-price contracts. Prioritize capacity addition in Texas brown sand corridors where permitting compression is least severe. For New Entrants and Emerging Players: Digital logistics platforms offer the most penetrable entry vector, enabling real-time proppant tracking and inventory visibility without captive transload asset ownership. Target Haynesville gas corridor demand for 40/70 mesh conductivity-optimized sand where technical barriers are lower than deep Permian applications. Pursue white-label blending partnerships with existing rail terminal operators to bypass greenfield permitting delays. For Investors and Strategic Acquirers: Exit pathways concentrate in logistics-integrated volume leaders with multi-basin rail commitments and grandfathered Wisconsin permits. Long-term viability favors operators with reclamation trust structures and established community relationships that deflect opposition to pit deepening. Monitor EPA National Ambient Air Quality Standard enforcement intensity as the critical inflection signal for supply expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Unit-Train Terminal Expansion | Compresses delivered costs to Permian pads through Midland-Odessa infrastructure density. |
| Destination-Specific Blending | Eliminates intermediate handling, reducing OSHA silica exposure points and trucking miles. |
| Reclamation Trust Structuring | Deflects Wisconsin community opposition through progressive mine rehabilitation bonding. |
| Resin-Coated Product Line Extension | Captures high-closure-stress well segments above 8,000 psi threatening raw sand economics. |
| Haynesville Corridor Logistics Partnership | Positions inventory for Louisiana dry gas development tied to Gulf Coast LNG export capacity. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving mine operations managers, E&P procurement leads, rail logistics coordinators, and industrial hygiene compliance officers. EPA enforcement databases, OSHA inspection records, FERC rail rate filings, and state water-use permit registries supplied quantitative benchmarks. Bottom-up well completion intensity models triangulated against top-down proppant consumption estimates from production volume forecasts.
Reconciliation of unit-train shipment manifests, transload facility throughput reports, and operator inventory disclosures generated volume baselines across the analysis window. Segmentation modeling incorporated product type tiering, application intensity by basin, delivery mode capital requirements, and end-user procurement sophistication. CAGRs derived from proppant intensity per well trajectories and rig count elasticity assumptions, stress-tested against diesel price and railcar lease rate volatility scenarios.
The model holds under stable EPA permitting timelines and OSHA enforcement intensity; deviation in Wisconsin greenfield approval acceleration or resin-coated manufacturing scale efficiencies would shift supply-demand balances. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Global Base Metal Mining Market
Metals & Minerals
Iron Ore Pellets Market
Metals & Minerals
Global Boron Market
Metals & Minerals
Middle-East and Africa Lithium Market
Metals & Minerals
Bauxite Market
Metals & Minerals
Recycled Scrap Metal Market
Metals & Minerals
Compacted Graphite Iron Market
Metals & Minerals
Recycled Copper Market
Metals & Minerals
Pre-Painted Galvanised Iron (PPGI) Market
Metals & Minerals
Cobalt Carbonate Market
Metals & Minerals
Global Chromium Salt Market
Metals & Minerals
Sapphire Mining Market
Metals & Minerals
Laminated Steel Market
Metals & Minerals
Global Nickel Hydroxide Market
Metals & Minerals
Coalingite Market
Metals & Minerals
Global Magnesium Hydroxide Market