
 Selenium Market | 2026-2036
Selenium Market Size, Share, and Industry Trends Forecast 2026-2036
Selenium Market Analysis
The EU Green Deal is realigning selenium sourcing priorities across European glass and chemical buyers. Qualitest Group leverages its testing infrastructure to verify selenium purity grades for export markets. Cigniti Technologies anchors quality-assurance protocols that chemical producers depend on for regulatory compliance. ScienceSoft specializes in digital traceability platforms that map selenium from mine to manufacturer.
Selenium is a non-metallic chemical element with atomic number 34, existing in several allotropic forms including gray crystalline, red amorphous, and black vitreous states, with gray selenium exhibiting photovoltaic and photoconductive properties that make it critical for photocopier drums and solar cell applications. High-purity selenium dominates value capture due to semiconductor-grade refining requirements, while selenium powder sustains volume leadership in glass manufacturing decolorization. Electronics applications represent the fastest-growing segment as photovoltaic manufacturers adopt copper indium gallium selenide thin-film technology.
REACH registration mandates ECHA oversight of selenium compound imports, while ISO 17025 accreditation governs laboratory testing protocols for purity verification. The EPA monitors selenium discharge limits from mining and refining operations, shaping production location decisions. Stakeholders must monitor evolving purity specifications from semiconductor fabs and solar panel manufacturers before committing to refining capacity investments.
Market Dynamics
The photovoltaic sector's pivot toward copper indium gallium selenide thin-film technology is compressing purity specifications and concentrating demand among East Asian solar manufacturers. This technology shift is forcing refiners to recalibrate metallurgical-grade output ratios against semiconductor-grade capacity.
Growth Catalysts
- EU Green Deal alignment:European glass manufacturers are expanding selenium procurement for low-carbon decolorization processes as the EU Green Deal tightens embodied carbon disclosure requirements.
- CIGS solar expansion:Photovoltaic manufacturers in South Korea and Japan are scaling copper indium gallium selenide deposition capacity, pulling high-purity selenium through dedicated offtake contracts.
- REACH traceability mandates:ECHA registration requirements for selenium compounds are filtering out non-compliant suppliers and consolidating import channels through accredited distributors.
Market Restraints
- Copper anode sludge concentration:Over 60% of selenium derives as byproduct from electrolytic copper refining, tying supply to copper smelter economics and concentrate availability.
- Tellurium substitution in thermoelectrics:Bismuth telluride compounds are displacing selenium-based materials in commercial thermoelectric generators, eroding a historical demand pillar.
- Refining energy intensity:Selenium purification to 5N or 6N grades requires energy-intensive vacuum distillation and zone refining, exposing margins to electricity cost volatility.
Strategic Opportunities
- Perovskite-silicon tandems:Emerging photovoltaic architectures incorporating selenium-doped transport layers offer entry points for specialty chemical suppliers ahead of mass production.
- India PLI scheme:India's production-linked incentive scheme for solar module manufacturing is attracting CIGS pilot lines that would localize selenium consumption.
- Digital mine-to-manufacturer traceability:Blockchain-enabled provenance platforms are opening premium pricing tiers for conflict-free selenium in European electronics supply chains.
Industry Challenges
- Semiconductor-grade certification timelines:Qualifying selenium for 300mm wafer manufacturing requires 18-24 month fab validation cycles that strain working capital.
- Pyrometallurgical expertise scarcity:The workforce capable of operating selenium roasting and reduction furnaces is aging, with limited apprenticeship pipeline replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Selenium Market |
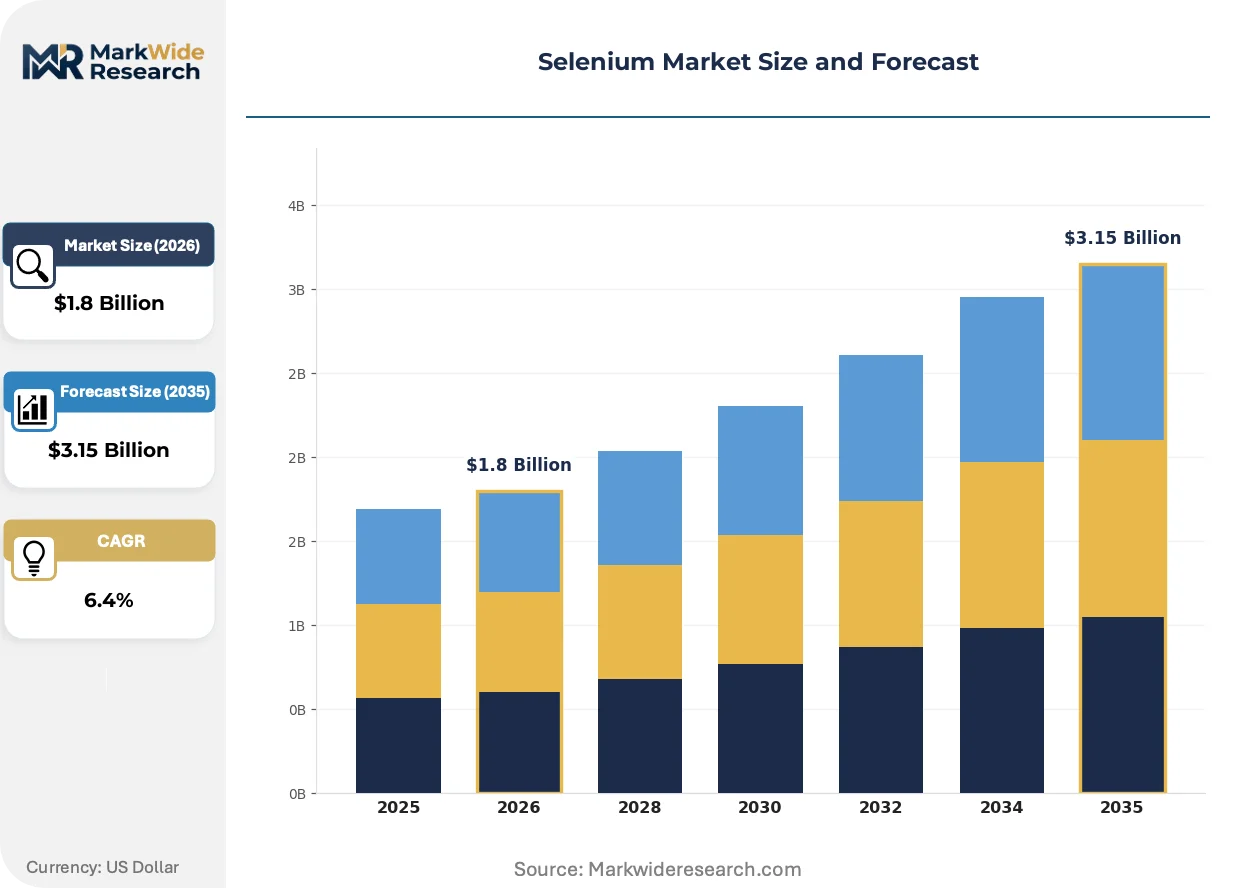
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Purity Selenium, Selenium Powder, Selenium Granules, Selenium Pellets Application: Glass Manufacturing, Chemicals Production, Electronics, Agriculture End User: Pharmaceuticals, Semiconductor Industry, Renewable Energy, Food Industry Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Qualitest Group, Cigniti Technologies, DeviQA, QualityLogic, Wildnet Edge, Dean Infotech Pvt. Ltd., ScienceSoft, QASource, SaM Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Selenium Market Emerging Trajectories
Refining automation and digital traceability are compressing quality assurance timelines while regulatory disclosure mandates are reshaping procurement specifications across electronics and glass verticals.
Automated optical sorting and laser-induced breakdown spectroscopy are automating real-time purity verification at selenium ingot production lines. Solar panel manufacturers in Malaysia and Vietnam are adopting these systems to bypass batch sampling delays. The technology is automating certificate-of-analysis generation and reducing reject rates at CIGS deposition facilities.
REACH Article 33 disclosure obligations now require downstream users to document selenium compound concentrations above 0.1% weight in articles placed on the European market. Glass coating producers in Germany and Belgium are requalifying supply chains to preempt compliance gaps. The regulation is accelerating substitution of selenium-based pigments in decorative glass applications where disclosure burden exceeds performance value.
Integrated smelter-refiner offtake agreements are displacing spot market procurement for high-purity selenium. Photovoltaic manufacturers are locking five-year supply contracts directly with copper smelters possessing captive refining capacity. This consolidation is visible in South Korean electronics clusters where module producers have abandoned merchant distributor channels entirely.
Selenium Market Segmentation
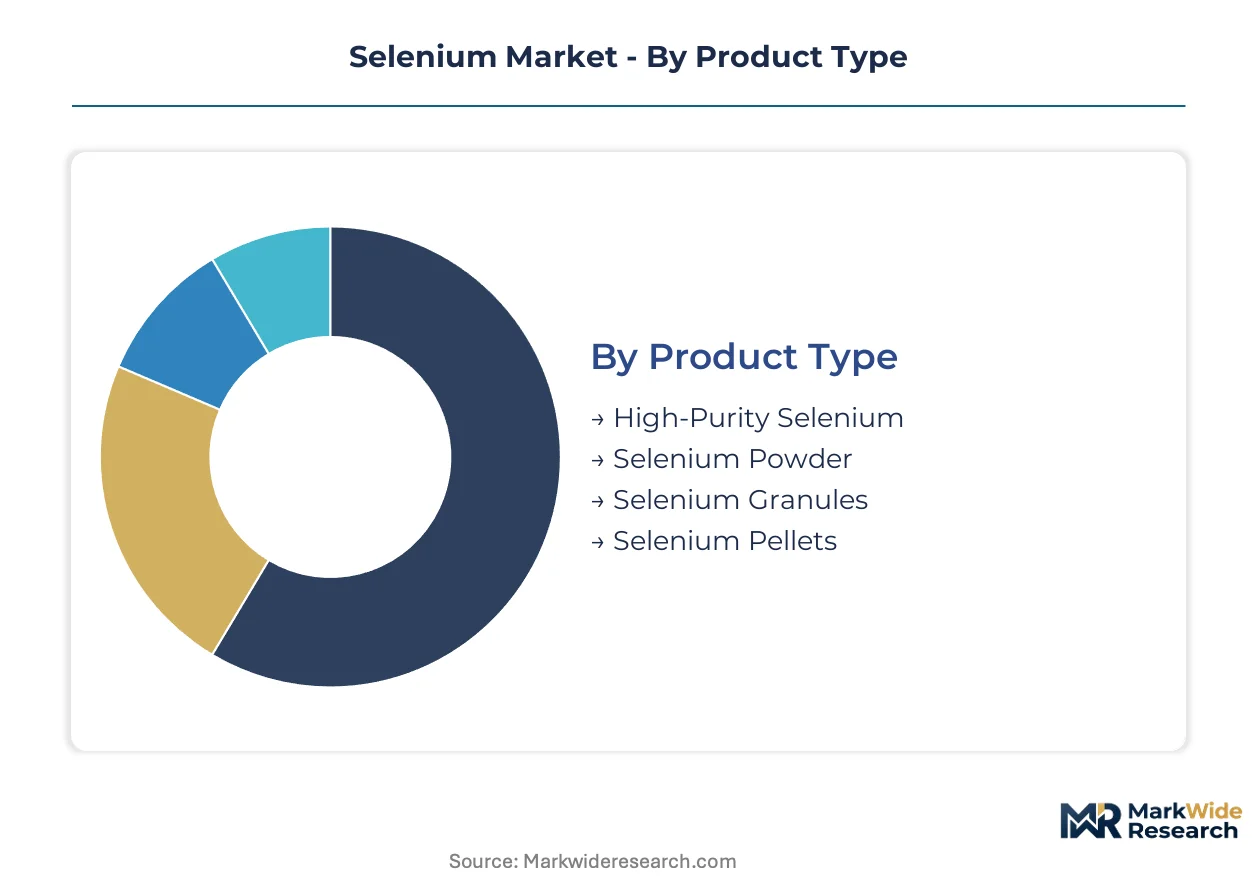
Selenium market segmentation reflects divergent certification burdens across purity grades and end-use specifications. Semiconductor fabs impose 5N-6N purity mandates that filter supplier pools, while glass manufacturers operate under broader metallurgical-grade tolerances.
Product Type:
Certification requirements stratify sharply across purity tiers, with semiconductor-grade material demanding ISO 17025-accredited laboratory verification and REACH-compliant documentation for European electronics supply chains.
- High-Purity Selenium:Vacuum-distilled and zone-refined material meeting 5N to 6N purity specifications for photovoltaic and semiconductor applications. South Korean CIGS manufacturers and Japanese solar panel producers concentrate procurement through direct smelter offtake agreements, compressing merchant distributor margins.
- Selenium Powder:Finely divided metallurgical-grade material produced through reduction of selenium dioxide. Chinese glass manufacturers in Shandong and Hebei provinces dominate consumption for decolorizing flint glass, with procurement volumes tied to construction sector float-glass output cycles.
- Selenium Granules:Pelletized intermediate form offering controlled dissolution rates for chemical synthesis operations.
- Selenium Pellets:Compressed cylindrical form factor optimized for vacuum deposition and thermal evaporation processes.
Leading the category by volume: Selenium Powder. Growing fastest: High-Purity Selenium.
Application:
Application segments diverge by energy intensity and regulatory exposure, with electronics-facing verticals bearing heavier ECHA disclosure obligations and EPA discharge monitoring.
- Glass Manufacturing:Decolorization of container and flat glass using selenium powder to neutralize iron-induced green tint. European manufacturers in Germany and Belgium face EU Green Deal embodied-carbon disclosure requirements that favor selenium over alternative decolorizers.
- Electronics:Copper indium gallium selenide thin-film deposition and photocopier drum manufacturing. Malaysian and Vietnamese solar panel producers are scaling CIGS capacity, pulling high-purity selenium through dedicated supply contracts.
- Chemicals Production:Intermediate synthesis for agrochemicals, pigments, and rubber processing additives.
- Agriculture:Micronutrient supplementation in livestock feed and fertilizer formulations.
Highest margin concentration: Electronics. Steepest expansion trajectory: Electronics.
End User:
End-user segments separate by qualification timelines and volume predictability, with semiconductor fabs imposing 18-24 month validation cycles that strain supplier working capital.
- Semiconductor Industry:300mm wafer manufacturing and compound semiconductor substrates requiring 6N+ purity with full lot traceability. Taiwan and South Korea fabs dominate procurement, with qualification protocols filtering out non-integrated refiners.
- Renewable Energy:CIGS photovoltaic module production and emerging perovskite-silicon tandem research lines. India's PLI scheme for solar manufacturing is attracting pilot CIGS capacity that would localize consumption.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and diagnostic reagent manufacturing.
- Food Industry:Nutraceutical and dietary supplement applications with FSSAI and FDA compliance requirements.
Longest sales cycles: Semiconductor Industry. Fastest contract velocity: Renewable Energy.
Distribution Channel:
Channel selection correlates with purity grade and customer scale, with high-purity material bypassing intermediaries entirely.
- Direct Sales:Smelter-to-fab contracts for semiconductor and photovoltaic-grade material, locking five-year supply agreements with price volatility clauses.
- Distributors:Accredited channel for REACH-compliant chemical-grade selenium into European glass and chemical processors.
- Wholesale:Bulk metallurgical-grade material for agricultural and industrial chemical buyers.
- Online Retail:Small-laboratory and research-quantity procurement with certificate-of-analysis documentation.
Dominant by value: Direct Sales. Fastest channel shift: Distributors consolidating under REACH pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Busan-Ulsan anchors selenium consumption in South Korea through dedicated CIGS photovoltaic deposition facilities. The industrial corridor processes high-purity material under direct smelter offtake contracts that bypass traditional distribution channels.
China
Shandong and Hebei provinces dominate metallurgical-grade selenium consumption for float-glass decolorization. MEE discharge monitoring shapes refinery location decisions along the Bohai Rim. Qingdao glass manufacturers are expanding procurement volumes to serve construction sector recovery.
United States
EPA selenium discharge limits from copper smelting operations constrain domestic refining capacity expansion. Arizona and Utah mining clusters supply anode sludge to third-party processors. Solar panel assemblers in California rely on imported high-purity material for CIGS pilot lines.
Germany
EU Green Deal embodied-carbon disclosure requirements favor selenium decolorization over alternative glass treatments. ECHA REACH Article 33 obligations filter import channels through accredited distributors. Belgian and Dutch glass coaters source through German chemical distributors to preempt compliance gaps.
India
PLI scheme incentives for solar module manufacturing attract CIGS pilot capacity in Gujarat and Rajasthan. BIS certification requirements for industrial chemicals create entry barriers for unaccredited suppliers. Tamil Nadu electronics clusters are negotiating direct smelter contracts to localize high-purity consumption.
Japan
METI energy transition targets accelerate copper indium gallium selenide deployment among domestic solar manufacturers. Kyushu-based photovoltaic producers lock five-year supply agreements with integrated copper smelters. JIS standards for semiconductor-grade material impose qualification timelines that strain working capital.
Selenium Market Vendor Landscape
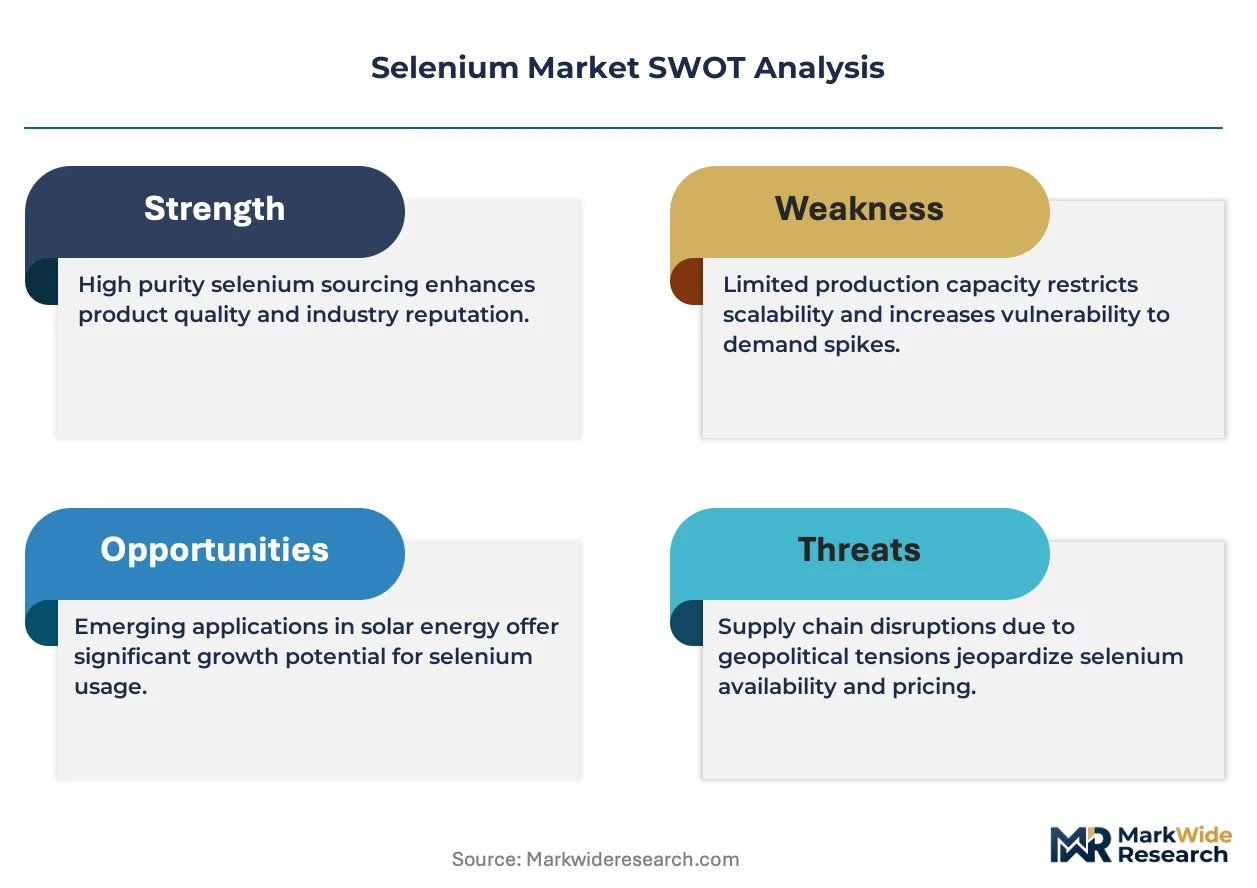
Premium-margin players sit above commodity-margin players across purity-grade certification tiers in the selenium supply base. The market structure concentrates around integrated copper smelters with captive refining capacity and specialized chemical processors serving electronics verticals. Three archetypes dominate: integrated mining-refining conglomerates, merchant chemical distributors with REACH accreditation, and digital traceability platform providers. Competitive moves center on backward integration into copper smelter offtake agreements and technology licensing for automated purity verification systems.
Within the quality-assurance and testing services tier, Qualitest Group and Cigniti Technologies exemplify archetypes that chemical producers and glass manufacturers depend upon for regulatory compliance infrastructure. ScienceSoft occupies a position among digital platform specialists that map supply chain provenance from mine to manufacturer. These entities represent the service-layer concentration that has emerged alongside physical selenium production as disclosure mandates tighten across European and North American procurement specifications.
| Leading Market Players |
|---|
| Qualitest Group |
| Cigniti Technologies |
| DeviQA |
| QualityLogic |
| Wildnet Edge |
| Dean Infotech Pvt. Ltd. |
| ScienceSoft |
| QASource |
| SaM Solutions |
| Others |
Supply Flow & Price Mechanics
Copper indium gallium selenide thin-film deposition technology is compressing cost economics at the high-purity tier while concentrating supply power among integrated copper smelters with captive refining capacity. This dual compression forces merchant distributors to absorb margin erosion or exit semiconductor-grade procurement entirely.
Pricing Analysis
Yield-based pricing anchors high-purity selenium contracts, with photovoltaic manufacturers paying premiums tied to CIGS cell conversion efficiency rather than raw material weight. Three-tier pricing structure across semiconductor-grade, solar-grade, and metallurgical-grade levels separates 6N material for Taiwan fabs from 5N solar feedstock and powder for Chinese glass. Cost compression in solar-grade material is intensifying because South Korean module producers are forcing annual price step-downs through five-year offtake renegotiations. Glass manufacturers in Shandong province exhibit highest price sensitivity, while semiconductor fabs accept 40% premiums for lot-level traceability documentation.
Supply Chain Analysis
ISO 17025 accreditation gates filter supplier pools before geographic concentration even matters, with only twelve laboratories worldwide qualified to certify 6N selenium for Japanese JIS standards. Primary supply draws from China, Japan, and South Korea, with Chinese copper smelters in Jiangxi and Gansu provinces dominating metallurgical-grade output. Selenium supply rests on electrolytic copper anode sludge, sulfuric acid throughput, and vacuum distillation furnace availability. Single-source vulnerability concentrates in South Korean CIGS manufacturers who rely entirely on Busan-Ulsan corridor refining. Distribution runs through direct smelter contracts for high-purity tiers and accredited chemical distributors for REACH-compliant European glass channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Selenium supply is becoming a vertical-integration race where backward integration into copper smelter offtake agreements separates viable players from margin-squeezed distributors. Control over anode sludge sourcing and captive refining capacity represents the decisive upstream lever.
For Market Incumbents: Lock in five-year direct contracts with Jiangxi and Gansu copper smelters before India's PLI scheme localizes demand. Invest in automated laser-induced breakdown spectroscopy systems to compress certificate-of-analysis generation timelines. Bismuth telluride substitution in thermoelectrics eliminates a historical demand pillar, making CIGS solar offtake the priority defensive perimeter. For New Entrants and Emerging Players: Launch via digital traceability platforms serving European electronics manufacturers under REACH Article 33 disclosure mandates. Target India's Gujarat solar cluster where CIGS pilot lines lack qualified local suppliers. White-space exists in blockchain-enabled provenance verification for conflict-free selenium premiums. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated copper mining conglomerates seeking downstream refining integration. Five-to-ten year viability hinges on perovskite-silicon tandem commercialization sustaining selenium-doped transport layer demand. Watch South Korean fab qualification timelines as the inflection signal—compression below eighteen months indicates merchant refiner distress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Smelter Offtake | Jiangxi and Gansu smelters secure anode sludge supply for captive refining capacity. |
| Automated Purity Verification Deployment | Laser-induced breakdown spectroscopy compresses certificate-of-analysis generation for Malaysian solar producers. |
| REACH-Accredited Distribution Consolidation | Belgian and Dutch glass coaters filter procurement through ECHA-compliant channels. |
| Digital Mine-to-Manufacturer Traceability Platform | Blockchain provenance opens premium pricing tiers for European electronics supply chains. |
| Perovskite-Silicon Tandem R&D Partnership | Selenium-doped transport layer development creates entry ahead of mass production scale. |
Methodological Framework
Independent corroboration across copper smelter operations managers, photovoltaic procurement leads at South Korean module manufacturers, ECHA regulatory affairs specialists, and glass manufacturing plant engineers in Shandong province underwrites the qualitative findings. Secondary validation draws from customs trade data, SEC filings of integrated mining conglomerates, ECHA registration databases, and Japan METI energy transition disclosures. Bottom-up segment sizing triangulates against top-down copper anode sludge availability models.
Comparable-period anchoring to electrolytic copper refining output cycles and CIGS solar capacity buildout timelines structures the projection horizon. The analytical framework models purity grade tier, end-use application, and regional production hub segmentation throughout the forecast period. CAGRs derive from elasticity-adjusted demand curves incorporating semiconductor fab qualification velocity and EU Green Deal embodied-carbon disclosure adoption rates. Forecast inputs include copper concentrate availability forecasts and photovoltaic technology substitution curves.
Copper smelter economics volatility, perovskite-silicon tandem technology maturation delays, and REACH regulatory scope expansion are the dominant revision risks. Forecasts reflect assumptions about CIGS solar efficiency improvements and Chinese construction sector float-glass demand stability. A model refresh is warranted upon material change in South Korean fab qualification protocols or Indian PLI scheme localization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Global Base Metal Mining Market
Metals & Minerals
Garnet Market
Metals & Minerals
Middle East and Africa Aluminum Extrusion Market
Metals & Minerals
India CRNO Steel Lamination Market
Metals & Minerals
US Lithium Market
Metals & Minerals
Electrolytic Manganese Dioxide Market
Metals & Minerals
Recycled Steel Market
Metals & Minerals
Pre-Painted Galvanised Iron (PPGI) Market
Metals & Minerals
Direct Reduced Iron (DRI) Market
Metals & Minerals
Middle-East and Africa Sodium Sulfide Market
Metals & Minerals
Frac Sand Market
Metals & Minerals
Recycled Scrap Metal Market
Metals & Minerals
Dolomite Market
Metals & Minerals
Compacted Graphite Iron Market
Metals & Minerals
Wegscheiderite Market
Metals & Minerals
Gemstones Market