
 Direct Reduced Iron (DRI) Market | 2026-2036
Direct Reduced Iron (DRI) Market Size, Share, and Industry Trends Forecast 2026-2036
Direct Reduced Iron (DRI) Market Outlook
Skilled metallurgical engineers with direct reduction expertise is reorganizing capacity expansion timelines across the DRI value chain. ArcelorMittal leverages its integrated HYL and Midrex technology portfolio to control project economics at greenfield sites. Emirates Steel Arkan anchors Middle Eastern supply through its access to low-cost natural gas feedstock. Nucor Corporation dominates electric arc furnace steelmaking in North America and extends its backward integration into captive DRI production via Louisiana operations.
Direct reduced iron is a metallic iron product manufactured by reducing iron ore below its melting point using reducing gases or solid carbonaceous materials, yielding a sponge iron with metallization rates typically exceeding 90 percent and carbon content between 1.5 and 4.5 percent depending on process parameters. Its primary commercial purpose is to serve as a high-purity scrap substitute in electric arc furnace steelmaking and as a blast furnace burden component to improve productivity and lower coke rates. The Midrex Process leads technology deployment due to its operational maturity and natural gas efficiency, while the HYL Process competes for projects targeting hydrogen integration pathways. DRI Pellets command premium positioning in seaborne trade because of their superior handling characteristics and consistent metallurgical performance.
The EPA enforces emissions standards that elevate the cost competitiveness of natural gas-based direct reduction relative to coke-intensive blast furnace routes. India's Ministry of Steel coordinates with the CEA on power and gas infrastructure allocation for DRI cluster development under national steel policy frameworks. The EU Carbon Border Adjustment Mechanism administered by the European Commission reshapes import eligibility by assigning embodied carbon penalties to conventional ironmaking feedstocks. Stakeholders must evaluate hydrogen-ready DRI technology commitments against the pace of renewable hydrogen cost decline and grid infrastructure buildout.
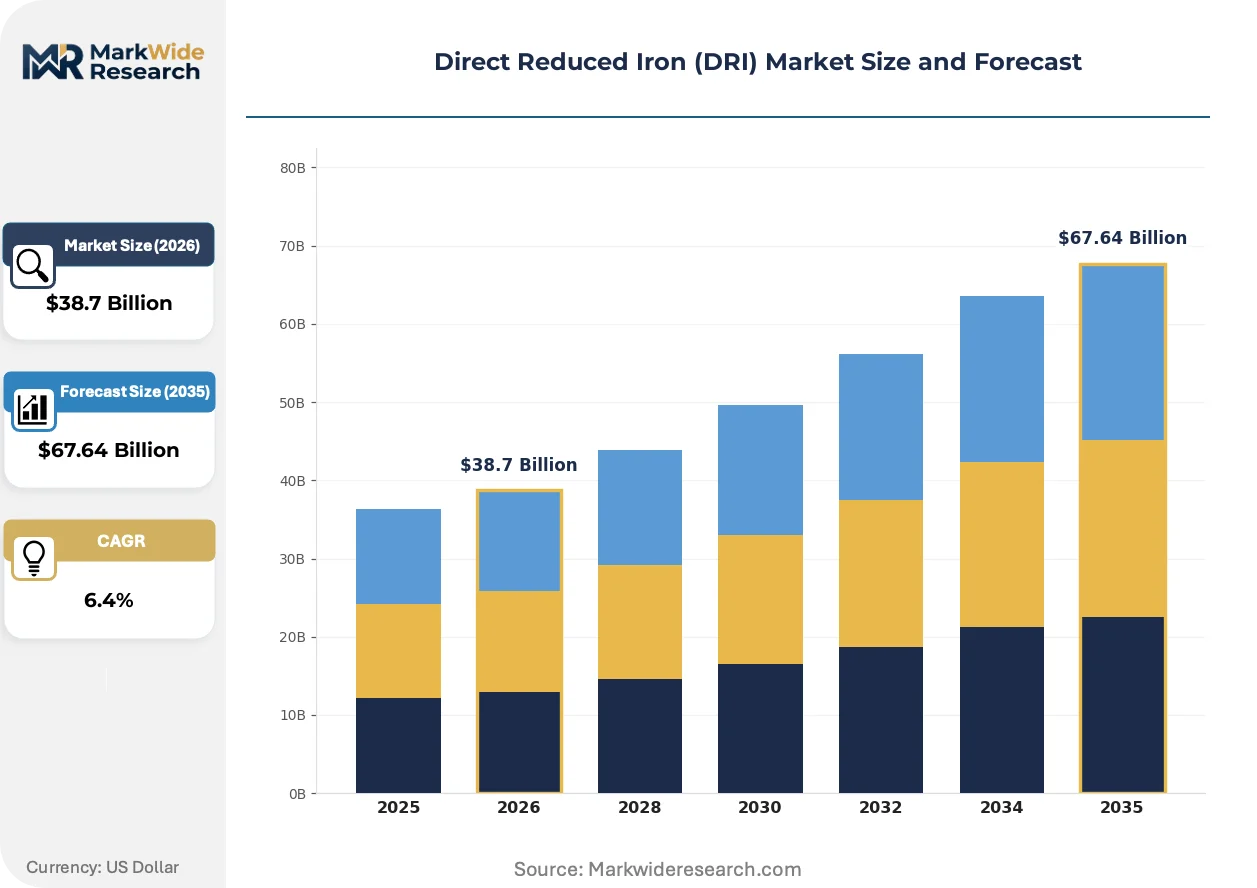
Market Dynamics
Blast furnace carbon cost pressure is forcing electric arc furnace steelmakers to restructure feedstock sourcing around direct reduced iron, compressing traditional coke-based ironmaking margins and accelerating hydrogen-ready technology commitments across the value chain.
Growth Catalysts
- EU Carbon Border Adjustment Mechanism:The European Commission's embodied carbon penalty system redirects import eligibility toward certified low-emission feedstocks, pulling DRI into European steelmaking supply chains.
- Automotive grade steel demand:Flat-rolled product specifications from passenger vehicle manufacturers require high-purity metallic inputs that DRI pellets deliver consistently.
- Natural gas-based process economics:Midrex and HYL technology deployments in regions with stranded gas assets achieve cost structures competitive with scrap-dependent electric arc furnace operations.
Market Restraints
- Iron ore pellet feedstock concentration:High-grade pellet supply concentrates in Brazil, Sweden, and Canada, exposing DRI producers to maritime freight volatility and single-source contract risks.
- Natural gas price exposure:Gas-based direct reduction routes face input cost instability in markets without long-term indexed supply agreements or domestic production.
- Scrap steel substitution:Obsolete scrap generation in mature industrial economies competes directly with DRI as electric arc furnace metallic charge, particularly when scrap prices fall below sponge iron premiums.
Strategic Opportunities
- India national steel policy implementation:The Ministry of Steel coordinates gas pipeline and power grid allocation for DRI cluster development in Odisha, Chhattisgarh, and Jharkhand.
- Hydrogen integration pathways:HYL technology retrofits and greenfield designs accommodate shifting reducing gas compositions from natural gas toward renewable hydrogen blends.
- Middle Eastern export positioning:Low-cost gas feedstock access in the UAE and Saudi Arabia enables seaborne DRI pellet supply to European and Asian electric arc furnace mills seeking carbon footprint reduction.
Industry Challenges
- Metallurgical engineering talent scarcity:Direct reduction plant design, operation, and optimization requires specialized expertise in shaft furnace kinetics and gas reforming that exceeds conventional steelmaking training pipelines.
- Greenfield project capital intensity:World-scale DRI facilities demand billion-dollar commitments for ore preparation, reduction reactors, and hot briquetted iron handling systems before revenue generation begins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct Reduced Iron (DRI) Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DRI Pellets, DRI Lumps, Hot DRI, Cold DRI Technology: HYL Process, Midrex Process, Siemens Process, Energiron Process End User: Steel Manufacturers, Foundries, Pipe Manufacturers, Automotive Industry Application: Steelmaking, Casting, Welding, Pipe Production |
| Companies Covered | Qatar Steel, Emirates Steel Arkan, ArcelorMittal, Kobe Steel Ltd., Baosteel Co., Ltd., Tosyalı Holding, JSW Steel Ltd., Cleveland-Cliffs, Nucor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct Reduced Iron (DRI) Market Strategic Shifts
Process intensification and feedstock flexibility are compressing plant footprints while expanding the range of iron ore grades suitable for direct reduction, altering where and how steelmakers deploy new capacity.
Modular shaft furnace designs are miniaturizing. Smaller-scale Midrex units now serve captive electric arc furnace operations at 500,000-ton annual outputs rather than the traditional two-million-ton merchant plants. Steelmakers in Turkey and Egypt adopt these compact configurations to match local scrap availability gaps. The technology is miniaturizing project economics, enabling brownfield integration at existing steel mill sites without greenfield infrastructure commitments.
REACH chemical registration requirements in Europe are tightening emissions disclosure obligations for imported iron and steel feedstocks. The regulation forces DRI exporters to document process carbon intensity through certified life-cycle assessments. Indian and Middle Eastern suppliers are responding by commissioning third-party verification of plant-level greenhouse gas protocols to maintain EU market access.
Long-term offtake contracting is displacing spot market purchasing for seaborne DRI pellets. European electric arc furnace mills now secure five-to-ten-year supply agreements with fixed-volume, indexed-price structures. This behavioral shift compresses working capital requirements for producers while locking in metallization quality specifications. The pattern is most visible in German and Italian steelmaking, where automotive customer audit requirements demand feedstock traceability incompatible with volatile spot sourcing.
Direct Reduced Iron (DRI) Market Segmentation
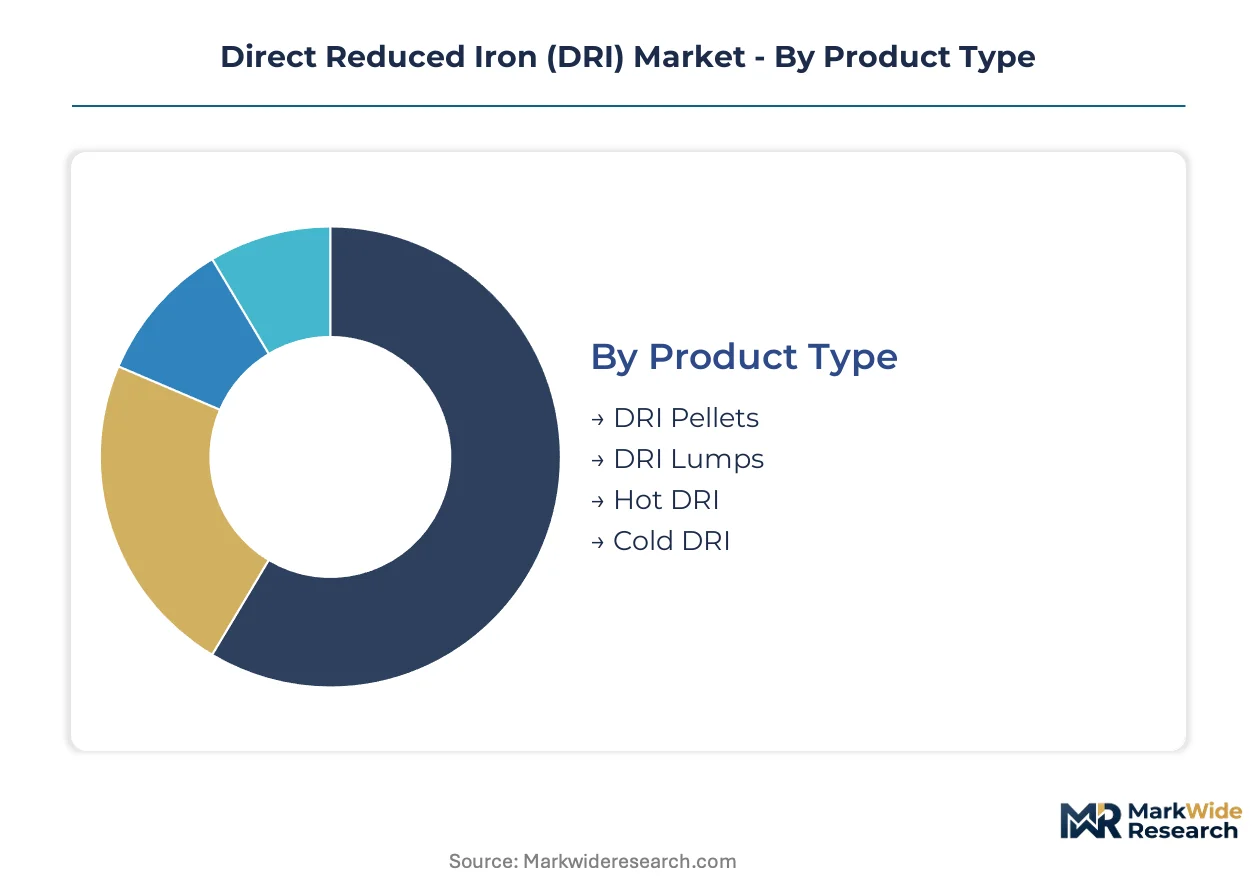
DRI market segmentation reveals distinct value chain positions where product form determines logistics economics, technology choice shapes carbon intensity, and end-user specifications drive metallization requirements. Understanding these divisions exposes where pricing power concentrates and where substitution risks emerge.
Product Type:
Channel flows diverge sharply by physical form, with seaborne trade favoring pellets while captive operations optimize around hot DRI energy recovery.
- DRI Pellets:Spherical, high-density metallized iron ore pellets with uniform size distribution and superior handling characteristics. Demand concentrates in European electric arc furnace mills under EU Carbon Border Adjustment Mechanism compliance pressure, where automotive grade specifications require consistent metallization above 92 percent.
- Hot DRI:Direct-reduced iron discharged at elevated temperatures for immediate electric arc furnace charging, preserving chemical energy and reducing reoxidation risk. Steel manufacturers in India and the Middle East prioritize this form for captive integration, cutting electricity consumption per ton of liquid steel.
- DRI Lumps:Irregular metallized iron pieces suited for blast furnace burden supplementation or foundry cupola charging. Pipe manufacturers in Turkey and Egypt source lumps when pellet premiums exceed freight-adjusted economics.
- Cold DRI:Cooled, passivated material for merchant trade and inventory buffering. Foundries in North America and Southeast Asia rely on cold DRI when scrap availability fluctuates seasonally.
By volume, DRI Pellets leads. By growth pace, Hot DRI is ahead.
Technology:
Process selection locks in feedstock flexibility and future hydrogen compatibility, creating divergent capital recovery profiles across installation vintages.
- Midrex Process:Shaft furnace technology using natural gas reforming to generate reducing gases, achieving metallization rates up to 95 percent with established operational track records. Steel producers in regions with stranded gas assets favor this route for its proven reliability and modular scalability.
- HYL Process:Flexible shaft furnace system accommodating hydrogen-rich reducing gas blends without fundamental reactor redesign. Project developers in Europe and Australia prioritize HYL for greenfield sites anticipating renewable hydrogen grid integration.
- Siemens Process:Rotary hearth-based direct reduction suited for fine ores and steel mill dust recycling. Specialty applications in Japan and South Korea exploit this technology for waste valorization.
- Energiron Process:Zero-reformer configuration using high-purity hydrogen or syngas directly, minimizing equipment footprint. Emerging deployments in Saudi Arabia and the UAE leverage this design for low-carbon export positioning.
Midrex Process dominates installed capacity. HYL Process claims the steepest expansion trajectory.
End User:
Customer concentration varies by metallic charge flexibility, with steel manufacturers commanding procurement scale while automotive qualification requirements create specification lock-in.
- Steel Manufacturers:Electric arc furnace and integrated blast furnace operators consuming DRI as scrap substitute or burden component. Indian mills JSW Steel and Tata Steel anchor demand through national steel policy capacity additions.
- Foundries:Gray and ductile iron producers using DRI for cupola charging or induction furnace metallic input. German and Italian foundries source certified low-emission material for automotive casting supply chains.
- Pipe Manufacturers:Longitudinal submerged arc welding and seamless pipe mills requiring consistent chemical composition for sour service grades. Turkish pipe exporters balance DRI against scrap for API specification compliance.
- Automotive Industry:Direct procurement of hot briquetted iron for specialty steelmaking in captive operations. Premium vehicle manufacturers in Germany and Japan specify traceable carbon footprints for body-in-white material.
Steel Manufacturers absorb the largest volume share. Automotive Industry procurement is climbing the fastest.
Application:
Use case differentiation separates commodity metallic feed from value-added processing where DRI chemistry enables performance specifications.
- Steelmaking:Primary electric arc furnace charging and blast furnace burden supplementation representing the dominant consumption mode. European mills under EU Carbon Border Adjustment Mechanism pressure accelerate DRI substitution for pig iron.
- Casting:Foundry cupola and induction furnace applications demanding controlled sulfur and phosphorus levels. Indian foundry clusters in Rajkot and Coimbatore source DRI for automotive component exports.
- Pipe Production:High-strength line pipe and OCTG grades requiring low residual element content. U.S. Gulf Coast pipe mills integrate captive DRI for API 5L specification consistency.
- Welding:Consumable electrode and flux cored wire manufacturing utilizing DRI-derived iron powder. Japanese welding material producers specify hydrogen-reduced grades for premium arc stability.
Steelmaking leads by volume. Casting is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Ministry of Steel coordinates national capacity expansion through gas pipeline allocation and power grid development for DRI cluster formation. Steelmakers in Odisha and Chhattisgarh commission new gas-based plants under policy frameworks designed to reduce import dependence. The country's CEA regulates power infrastructure buildout to support metallurgical load growth.
India
JSW Steel and Tata Steel drive domestic capacity additions targeting automotive and construction grade requirements. The Ministry of Steel's national policy channels infrastructure investment toward eastern mineral belts. Odisha's Kalinga Nagar industrial hub hosts integrated DRI-electric arc furnace complexes with captive gas supply agreements.
United States
Nucor Corporation extends backward integration through Louisiana DRI operations serving Gulf Coast steelmaking. The EPA enforces emissions standards that elevate natural gas-based direct reduction cost competitiveness against coke-intensive routes. Electric arc furnace mills in the Southeast source captive sponge iron to manage scrap price volatility.
Germany
ThyssenKrupp and Salzgitter evaluate hydrogen-ready DRI technology commitments against renewable hydrogen cost decline timelines. The EU Carbon Border Adjustment Mechanism administered by the European Commission assigns embodied carbon penalties to conventional ironmaking feedstocks. Industrial clusters in North Rhine-Westphalia pilot renewable hydrogen integration for steel decarbonization pathways.
United Arab Emirates
Emirates Steel Arkan leverages low-cost natural gas feedstock access to anchor Middle Eastern export supply. The country's MOHAP oversees industrial emissions frameworks affecting carbon intensity certification for European-bound shipments. Abu Dhabi's KIZAD industrial zone concentrates world-scale DRI pellet production for seaborne trade.
Turkey
Tosyalı Holding and pipe manufacturers balance DRI procurement against scrap availability for API specification compliance. The country's national steel regulator monitors import eligibility under EU Carbon Border Adjustment Mechanism alignment protocols. Iskenderun Bay industrial corridor hosts compact Midrex units serving regional electric arc furnace operations.
Direct Reduced Iron (DRI) Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with technology licensors and merchant producers occupying distinct competitive positions. The upper tier combines captive steelmaking integration with technology ownership, while mid-scale operators concentrate on regional supply security and export positioning. Two strategic archetypes dominate: integrated steelmakers controlling reduction technology portfolios, and gas-rich region specialists monetizing feedstock access through seaborne pellet trade. Competitive moves center on hydrogen-ready technology licensing agreements and long-term offtake contracting for carbon-certified material.
Within the integrated steelmaker archetype, ArcelorMittal occupies a position representing technology portfolio control across HYL and Midrex systems. Nucor Corporation exemplifies North American backward integration into captive DRI production. Emirates Steel Arkan anchors Middle Eastern supply positioning through gas feedstock access and export-oriented capacity scale.
| Leading Market Players |
|---|
| Qatar Steel |
| Emirates Steel Arkan |
| ArcelorMittal |
| Kobe Steel Ltd. |
| Baosteel Co., Ltd. |
| Tosyalı Holding |
| JSW Steel Ltd. |
| Cleveland-Cliffs |
| Nucor Corporation |
| Others |
Value Chain & Pricing Dynamics
The EU Carbon Border Adjustment Mechanism gates both supply qualification and price differentiation simultaneously, forcing exporters to document process carbon intensity through certified life-cycle assessments before accessing premium European electric arc furnace procurement channels. This regulatory filter compresses margins for uncertified producers while rewarding verified low-emission feedstock with contract premiums and long-term offtake security.
Pricing Analysis
Seaborne DRI pellet spreads between Middle Eastern export hubs and European discharge ports reflect freight-adjusted differentials of 15-25 percent above regional scrap benchmarks. Pricing stratifies across carbon-certified premium, standard metallization, and unverified economy tiers based on embodied emissions documentation and metallization consistency. Cost compression in the standard tier is intensifying because Brazilian and Swedish pellet feedstock concentrates expose producers to maritime freight volatility. Merchant electric arc furnace mills in Germany and Italy exhibit lowest price sensitivity due to automotive customer audit requirements, while Turkish pipe manufacturers demonstrate highest sensitivity during scrap price troughs.
Supply Chain Analysis
Strategic stockpiling of high-grade iron ore pellets dominates over just-in-time inventory strategies due to single-source concentration risks and maritime logistics lead times. Supply concentrates in Brazil, Sweden, and Canada for pellet feedstock, with reduction capacity clustering in India, the Middle East, and the United States. The chain rests on natural gas reforming equipment, shaft furnace refractories, and hot briquetted iron handling systems as critical component dependencies. Single-source vulnerability from Brazilian pellet supply exposes DRI producers to contract renegotiation leverage and force majeure disruption. Distribution runs through long-term offtake contracting with indexed-price structures rather than spot market purchasing, compressing working capital requirements for producers while locking in metallization specifications.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized metallurgical engineering expertise in shaft furnace kinetics and gas reforming now constrains capacity expansion timelines more than capital availability, creating acquisition premiums for teams with operational track records across Midrex and HYL technology platforms.
For Market Incumbents: Secure long-term offtake agreements with European electric arc furnace mills before EU Carbon Border Adjustment Mechanism compliance deadlines harden procurement criteria. Lock in pellet supply contracts with Brazilian and Canadian miners to defend against feedstock concentration risk. Prioritize HYL technology retrofits for hydrogen-ready positioning as renewable hydrogen cost curves decline.
For New Entrants and Emerging Players: Anchor in Indian eastern mineral belts where the Ministry of Steel coordinates gas pipeline and power grid allocation for DRI cluster development under national steel policy frameworks. Target captive integration opportunities at existing electric arc furnace mill sites in Turkey and Egypt using compact Midrex configurations. Pursue technology licensing partnerships rather than greenfield proprietary development to compress time-to-revenue.
For Investors and Strategic Acquirers: The EU Carbon Border Adjustment Mechanism reshapes the acquisition landscape by assigning embodied carbon penalties to conventional ironmaking feedstocks and rewarding certified low-emission supply chains. Prioritize targets with operational hydrogen-ready DRI assets and established third-party carbon verification protocols. Watch renewable hydrogen production cost inflection and grid infrastructure buildout pace as the signal determining technology substitution timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Technology Licensing | HYL process retrofits enable ArcelorMittal and Emirates Steel Arkan to shift reducing gas compositions toward renewable hydrogen blends without reactor replacement. |
| Backward Integration into Pellet Supply | Nucor Corporation's Louisiana DRI operations secure captive sponge iron production to manage scrap price volatility for Gulf Coast electric arc furnace steelmaking. |
| Carbon Certification Investment | Indian and Middle Eastern suppliers commission third-party greenhouse gas protocol verification to maintain EU market access under REACH emissions disclosure obligations. |
| Long-Term Offtake Contracting | German and Italian mills secure five-to-ten-year supply agreements with fixed-volume indexed-price structures incompatible with volatile spot sourcing. |
| Modular Shaft Furnace Deployment | Compact Midrex units at 500,000-ton annual outputs enable brownfield integration at existing steel mill sites in Turkey and Egypt without greenfield infrastructure commitments. |
Study Parameters
A spread of perspectives from shaft furnace operations managers, electric arc furnace procurement leads, metallurgical engineering consultants, and gas reforming technology licensors converged on the working assumptions underlying capacity expansion timelines and hydrogen integration pathways. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC filings from integrated steelmakers, national steel ministry policy documents, and IEA hydrogen cost tracking databases. Bottom-up installation capacity tallies triangulated against top-down steel production forecasts and scrap availability projections.
Segmentation dimensions modeled span product form, reduction technology, end-user industry, and application use case across the projection horizon. The analytical framework derived CAGRs from plant-level operating rates, feedstock cost trajectories, and regulatory compliance cost layering. Industry-specific forecast inputs incorporated natural gas price index movements, renewable hydrogen production cost decline curves, and EU Carbon Border Adjustment Mechanism implementation phase-in schedules.
Underlying assumptions cover sustained electric arc furnace steelmaking expansion, natural gas supply continuity in producing regions, and renewable hydrogen infrastructure buildout pace, with deviation risk concentrated in iron ore pellet supply disruption and metallurgical engineering talent scarcity. Practitioners should keep alternative scenarios live as hydrogen cost parity timing and carbon border adjustment enforcement stringency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Sapphire Mining Market
Metals & Minerals
Boron Ore Market
Metals & Minerals
North America and EMEA Ferrosilicon Market
Metals & Minerals
Global Ferrous Scrap Recycling Market
Metals & Minerals
Recycled Steel Market
Metals & Minerals
India Colored Gemstones Market
Metals & Minerals
Bauxite Market
Metals & Minerals
Colored Gemstones Market
Metals & Minerals
Global Gold Potassium Cyanide Market
Metals & Minerals
Electrolytic Manganese Dioxide Market
Metals & Minerals
Pyroxenite Market
Metals & Minerals
Solder Materials Market
Metals & Minerals
Chromium Mining Market
Metals & Minerals
US Coated Steel Market
Metals & Minerals
Gemstones Market
Metals & Minerals
Middle-East and Africa Lithium Market