
 Global Magnesium Oxide Market | 2026-2036
Global Magnesium Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Magnesium Oxide Market Intelligence
The unbundling of technical support services from bulk material sales is restructuring procurement patterns for industrial buyers. This shift allows for more flexible sourcing strategies among end-users in the steel and cement sectors. RHI Magnesita dominates the market with its integrated refractory solutions and extensive service network. In contrast, Haicheng Magnesite Group leverages its vast domestic mineral reserves in China to compete on scale and cost.
Magnesium oxide, or magnesia, is a solid mineral produced via the calcination of magnesium-bearing ores like magnesite at high temperatures. Its primary industrial value stems from an extremely high melting point of 2,852 °C and excellent corrosion resistance. Dead-burned magnesia for refractory materials represents the largest product type segment, tied directly to steel production cycles. Demand for agricultural grade caustic-calcined magnesia is also expanding, driven by its use as a soil amendment and animal feed supplement.
Regulatory frameworks such as Europe's REACH directive and US EPA emission standards for kilns directly influence production costs. In China, MEE policies on pollution control for heavy industry shape the operational landscape for major producers. These rules create stringent quality and environmental performance requirements. Strategic decisions must weigh the cost benefits of concentrated supply against the imperative for supply chain diversification to mitigate risks.
Market Dynamics
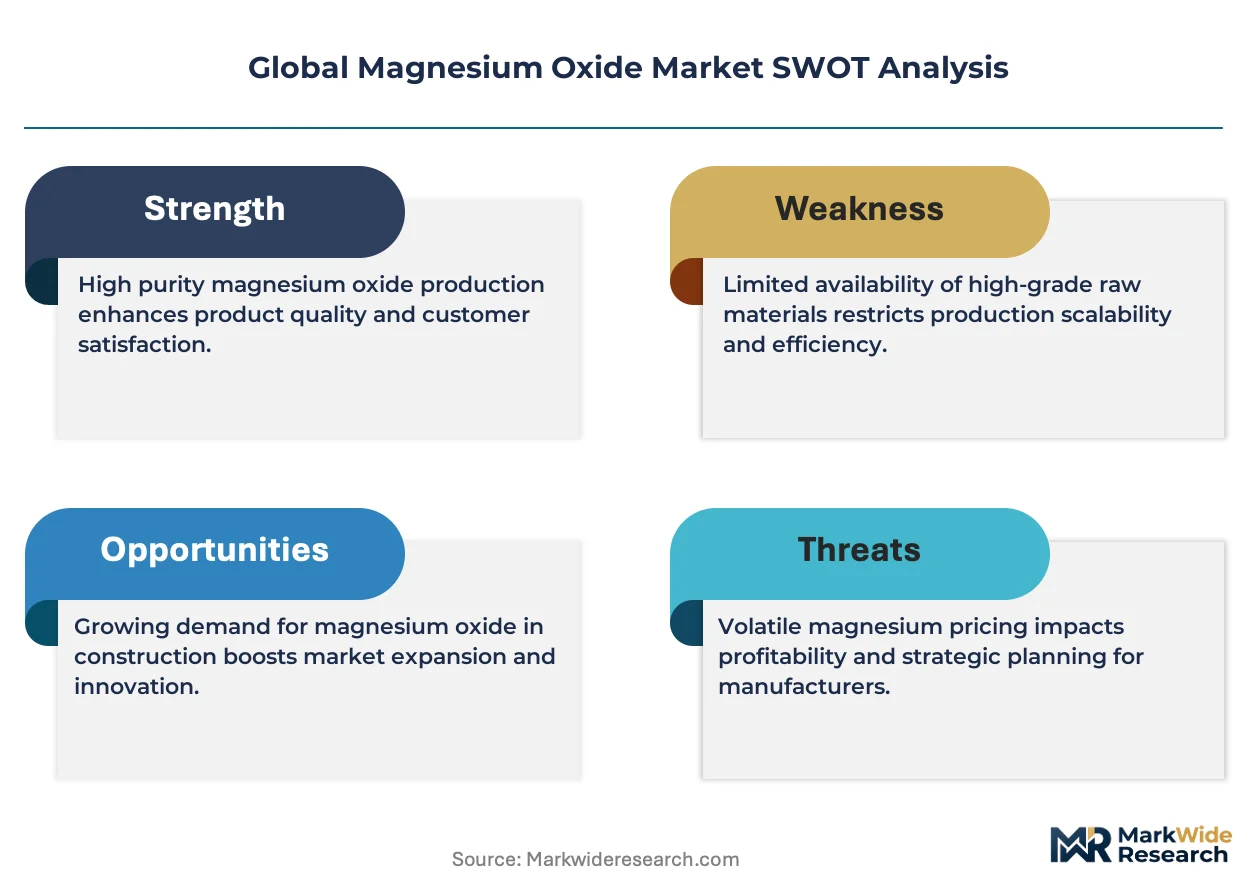
The market's central dynamic is the tension between heavy supply-side concentration in China and mounting global pressure for environmentally sustainable production. This friction influences cost structures, supply chain strategies, and the pace of technological adoption for kiln operations.
Growth Catalysts
- Refractory Demand:The steel industry's continuous need for high-performance refractory linings for furnaces and ladles remains the primary demand driver, directly linking magnesium oxide consumption to industrial output and infrastructure development cycles.
- Agricultural Soil Health:Expanding use of caustic-calcined magnesia as a vital soil conditioner and an essential nutrient in animal feed supplements is creating a consistent, non-cyclical demand stream, particularly in regions focused on improving crop yields.
- Raw Material Control:China's vast magnesite ore reserves and established calcination capacity provide a cost-competitive foundation for the global supply of dead-burned and fused magnesia, anchoring production volumes in the Asia-Pacific region.
Market Restraints
- Energy Price Volatility:The calcination process is extremely energy-intensive, making production costs highly susceptible to fluctuations in electricity and natural gas prices, which can compress margins for producers without long-term energy contracts.
- Geopolitical Supply Risk:Over-reliance on China for raw magnesite and processed magnesia creates significant supply chain vulnerability, with potential export restrictions or policy changes by entities like the MEE posing a risk to global availability.
- Threat of Substitution:In certain refractory applications that do not require extreme temperature resistance, alternative materials such as alumina, silica, and dolomite can serve as viable, and sometimes lower-cost, substitutes for magnesia-based products.
Strategic Opportunities
- High-Purity Applications:Development of high-purity and ultra-high-purity magnesium oxide opens new markets in advanced ceramics, specialty glass, and as a substrate material in the electronics industry, commanding premium pricing.
- Environmental Technologies:The use of magnesium oxide in flue-gas desulfurization systems to capture sulfur dioxide emissions presents a major opportunity, driven by stricter air quality regulations like those enforced by the US EPA.
- Demand in Industrializing Economies:Rising steel and cement production in industrializing nations, particularly in India and Southeast Asia, offers significant growth potential for refractory suppliers looking to diversify their geographic footprint beyond mature markets.
Industry Challenges
- Capital-Intensive Modernization:Upgrading or building new kilns to meet stringent environmental standards and improve energy efficiency requires substantial capital investment, creating high barriers to entry and challenging smaller operators.
- Regulatory Compliance Burden:Navigating complex chemical safety regulations like Europe's REACH framework demands extensive testing, data submission, and administrative resources, adding significant overhead and time-to-market for producers.
- Specialized Labor Scarcity:A shortage of skilled engineers and technicians capable of operating and maintaining modern, automated calcination facilities and managing quality control for specialty-grade products can hinder operational efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Magnesium Oxide Market |
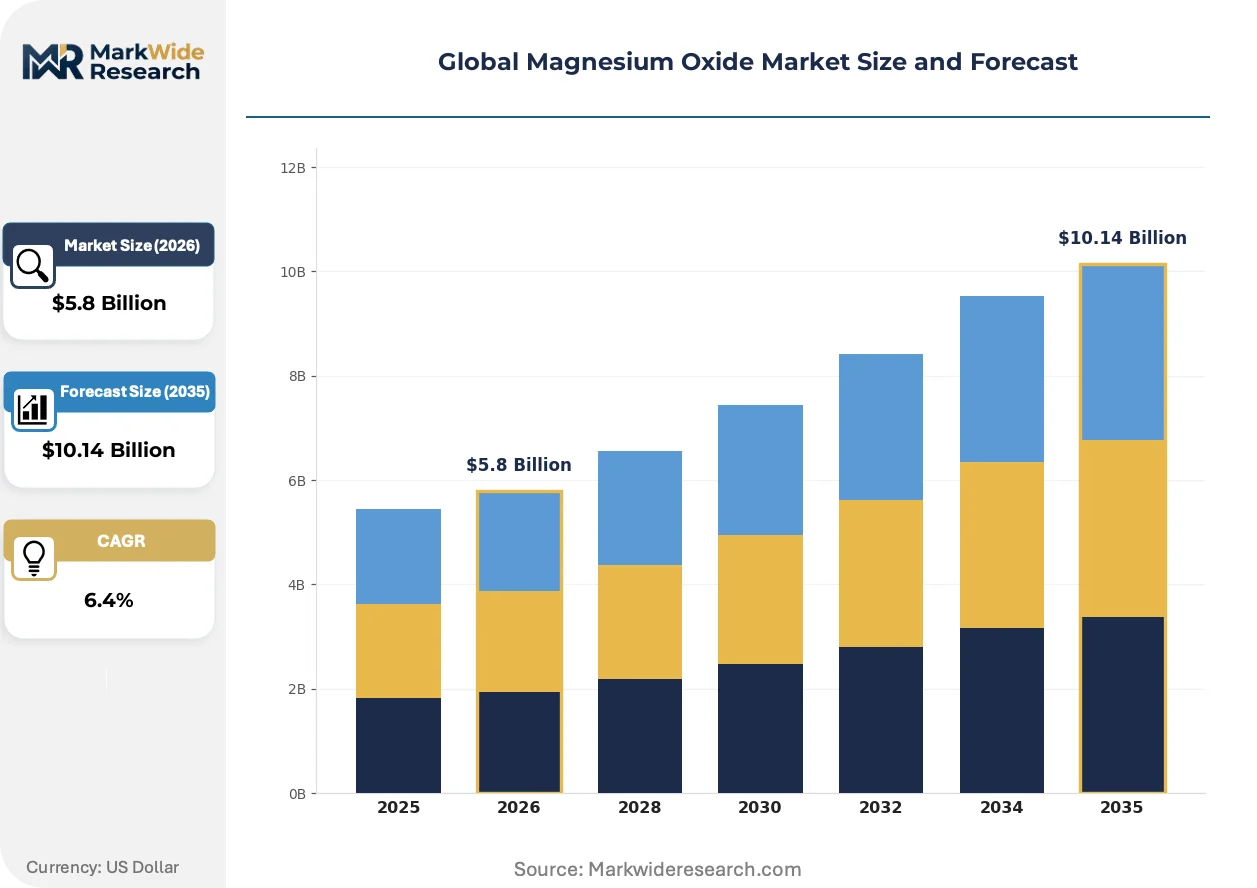
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light-burned, Dead-burned, Caustic-calcined, Sintered, Electrolytic Application: Refractory Materials, Agriculture Amendment, Environmental Protection, Construction, Chemical Industry Grade: Technical Grade, Food Grade, Pharmaceutical Grade, Agricultural Grade, Industrial Grade Packaging Type: Bagged, Bulk, Bulk Big Bags, Paper Bags, Polywoven Sacks |
| Companies Covered | Premier Magnesia, Grecian Magnesite, Haicheng Magnesite Group Co., Ltd., Ube Industries Ltd., Israel Chemicals Ltd., Magnezit Group, Martin Marietta Magnesia Specialties, Meishen Technology Co., Ltd., RHI Magnesita, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Magnesium Oxide Market Strategic Shifts & Innovations
Innovations in production technology and product formulation are increasingly focused on enhancing purity, improving thermal performance, and reducing the environmental footprint of calcination. These advancements are a direct response to stricter emissions controls and demand from high-performance end-use sectors.
High-purity fused magnesia, produced in electric arc furnaces, offers superior density and corrosion resistance compared to standard dead-burned grades. Electronics and specialty alloy manufacturers are its primary adopters due to stringent performance requirements. The growing availability of distinct purity levels is modularizing refractory design, enabling furnace operators to specify materials for discrete zones based on thermal and chemical stress.
Environmental regulations, particularly China's MEE policies targeting industrial pollution, are forcing a technological overhaul in magnesia production. These rules mandate investments in advanced dust collection systems and more efficient kiln technologies to curb particulate matter and CO2 emissions. The dead-burned and caustic-calcined magnesia segments are most affected, especially in Liaoning province, leading to industry consolidation as smaller, non-compliant plants are phased out.
A notable shift in purchasing behavior involves the disaggregation of material supply from technical services. End-users in the steel and cement sectors are moving away from single-source, integrated refractory contracts toward multi-sourcing strategies for bulk materials. This change creates opportunities for independent engineering consultants and installation specialists, a pattern most visible in North American and European markets where buyers prioritize operational flexibility.
Global Magnesium Oxide Market Segmentation
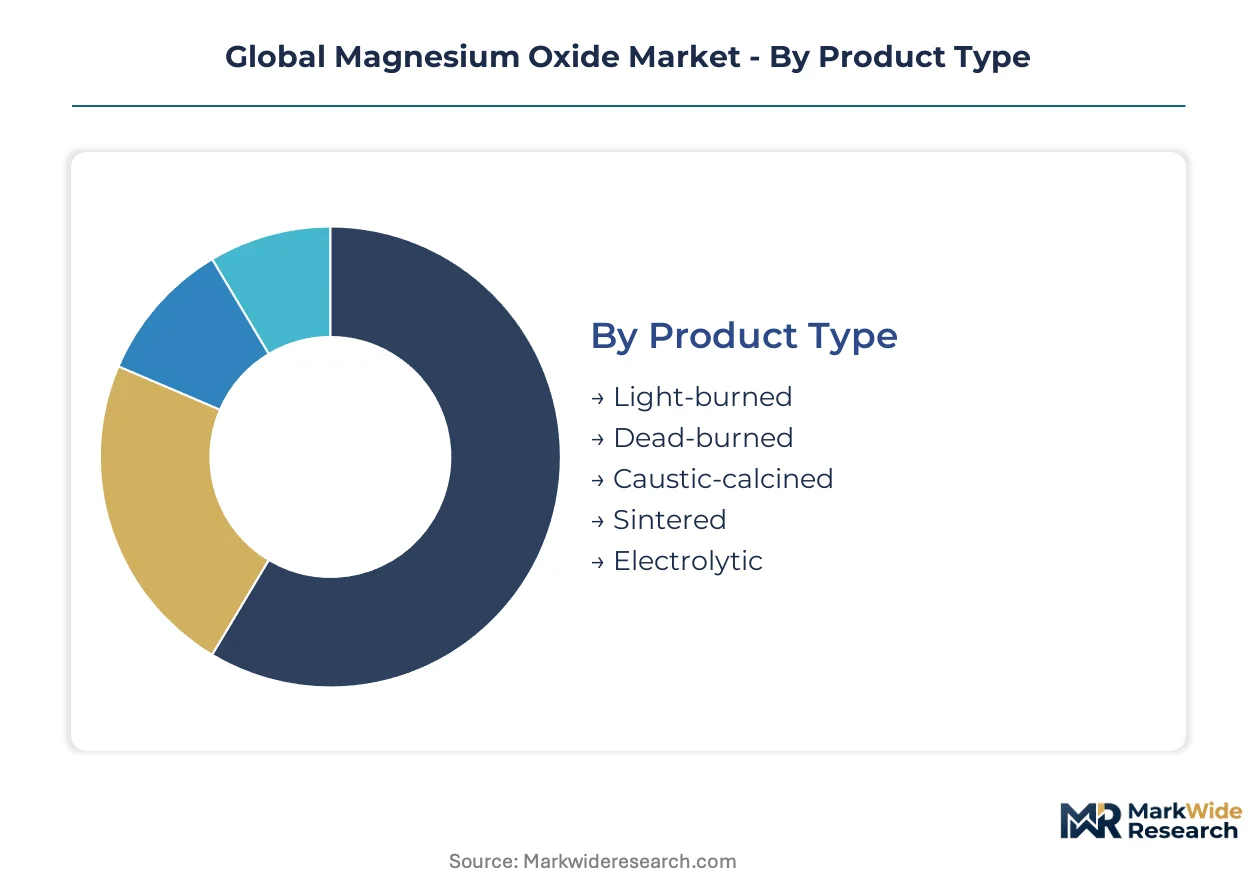
The magnesium oxide market is segmented to reflect the diverse forms and applications of this critical industrial mineral. Understanding these distinct segments reveals specific demand drivers, competitive dynamics, and regulatory influences across various end-use sectors. Each segment presents unique value propositions for buyers and producers.
Product Type:
The product type segmentation highlights how magnesium oxide forms are integrated into end-user processes, ranging from standalone bulk materials to specialized components.
- Light-burned:This moderately calcined magnesia retains some chemical reactivity, finding use in various industrial processes requiring specific chemical properties.
- Dead-burned:This highly calcined form of magnesia possesses exceptional thermal stability and chemical inertness, making it ideal for extreme high-temperature environments. Demand concentrates heavily in China's steel industry, driven by the continuous need for robust refractory linings in furnaces.
- Caustic-calcined:Produced at lower temperatures, this reactive form of magnesia offers higher solubility and surface area, making it suitable for chemical and agricultural applications. Global demand is expanding in regions focused on improving crop yields, where it serves as a vital soil amendment.
- Sintered:Characterized by high density and low porosity, sintered magnesia provides enhanced resistance in demanding refractory applications.
- Electrolytic:High-purity electrolytic magnesia is produced through electrochemical processes for specialized applications requiring extreme purity.
Dead-burned magnesia leads volumes today; caustic-calcined magnesia is gaining share fastest.
Application:
This segmentation by application demonstrates the varied end-use demand for magnesium oxide, linking its properties directly to industrial output and environmental imperatives.
- Refractory Materials:Magnesium oxide's high melting point and corrosion resistance make it indispensable for linings in steel furnaces, cement kilns, and glass melting tanks. Steel production cycles in Asia-Pacific countries, particularly China, dictate the bulk of this demand.
- Agriculture Amendment:Caustic-calcined magnesia improves soil pH, provides essential magnesium nutrients for plant growth, and serves as a feed supplement for livestock. Regions striving for food security and enhanced crop productivity, such as India, drive consistent consumption.
- Environmental Protection:Magnesium oxide is utilized in flue-gas desulfurization systems and wastewater treatment for pollution control.
- Construction:The material is incorporated into magnesium oxychloride cement and insulating panels for its fire-resistant and structural properties.
- Chemical Industry:Magnesium oxide acts as a raw material for various magnesium compounds and as a catalyst in chemical synthesis.
Refractory materials drive the largest demand; environmental protection applications show significant expansion.
Grade:
Different grades of magnesium oxide reflect specific purity levels and performance requirements, influencing their suitability for sensitive or high-volume industrial uses.
- Technical Grade:Technical grade magnesia meets specific industrial standards for various manufacturing processes.
- Food Grade:This high-purity grade is regulated for use as a food additive, anticaking agent, and dietary supplement.
- Pharmaceutical Grade:Pharmaceutical grade magnesia adheres to stringent purity standards for medicinal and health product formulations.
- Agricultural Grade:This grade is formulated for use as a soil conditioner, animal feed supplement, and fertilizer component, requiring specific nutrient content and solubility. Demand for agricultural grade magnesia is consistent across North America, driven by livestock and crop health initiatives.
- Industrial Grade:Characterized by its cost-effectiveness and suitability for large-scale processes, industrial grade magnesium oxide serves as a primary input for refractory production and general chemical manufacturing. High-volume industrial activity in China underpins the majority of this segment's consumption.
Industrial grade magnesia dominates consumption; agricultural grade magnesia experiences consistent growth.
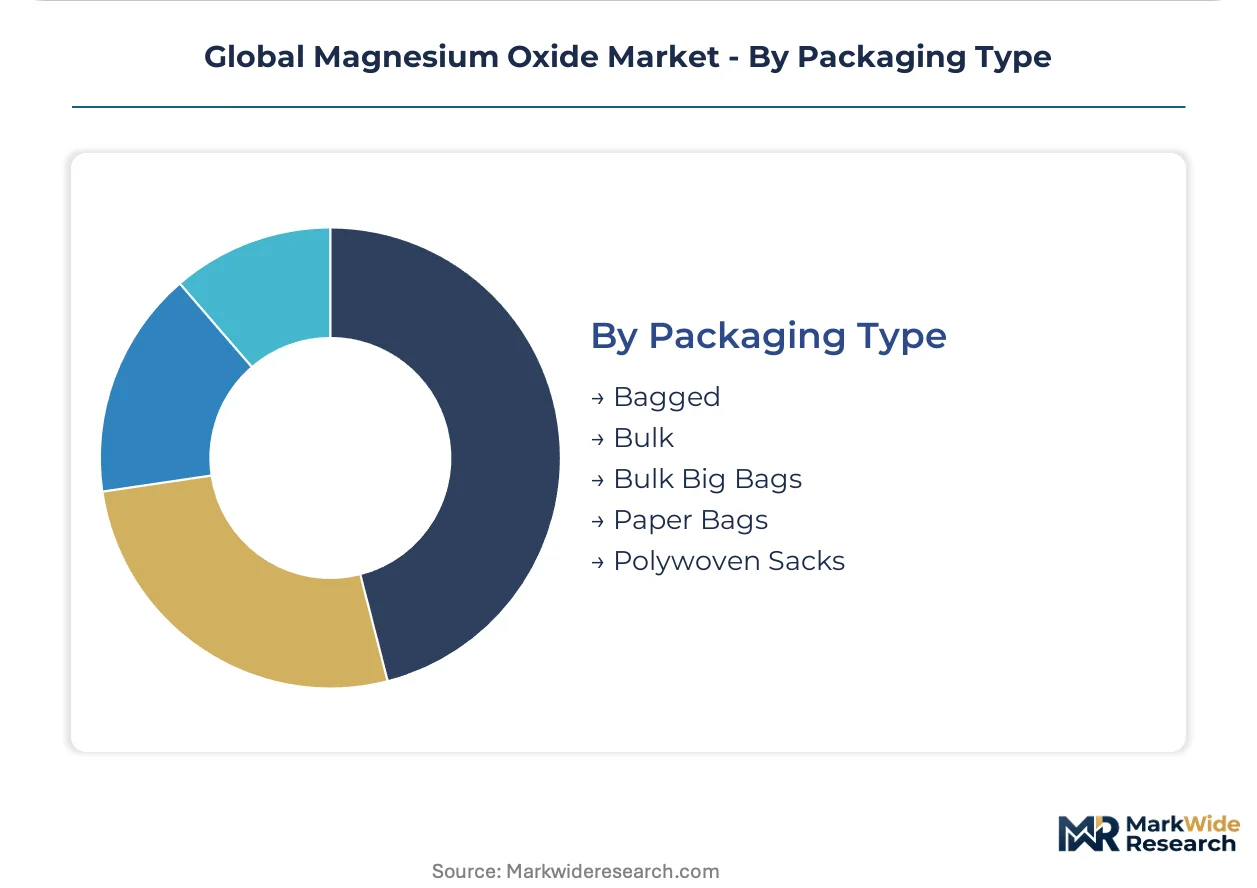
Packaging Type:
The segmentation by packaging type illustrates the logistical considerations and volume requirements for transporting magnesium oxide to various industrial clients.
- Bagged:Smaller, conventional bags are used for lower volume shipments, offering convenience for smaller industrial users or specialty applications.
- Bulk:Large quantities of magnesium oxide are transported loose in railcars, trucks, or ships for direct delivery to major industrial consumers like steel mills and cement plants. This method reduces packaging costs and facilitates high-volume material handling at production sites.
- Bulk Big Bags:Intermediate bulk containers, often made of woven polypropylene, offer a flexible solution for transporting significant volumes while allowing for easier handling than traditional bulk. These bags are preferred for their efficiency in managing large but not continuous supply needs.
- Paper Bags:Environmentally friendly paper bags are utilized for specific grades or smaller quantities, particularly where dust control is critical.
- Polywoven Sacks:Durable polywoven sacks provide robust protection for magnesium oxide during transport and storage, suitable for various industrial settings.
Bulk packaging accounts for the majority of shipments; bulk big bags are increasingly utilized for efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Magnesium oxide production historically scaled in regions with abundant magnesite reserves, particularly in China. Early industrial applications in refractories established demand patterns. This foundational supply base continues to influence global distribution and pricing dynamics for the mineral.
China
China's vast magnesite ore reserves drive dead-burned magnesia production for its steel industry. The Ministry of Ecology and Environment (MEE) policies enforce stringent pollution controls on heavy industry. Liaoning province, a major mining hub, sees significant investment in advanced kiln technologies.
United States
Demand in the United States stems from agricultural applications and environmental protection. US EPA emission standards influence production methods for caustic-calcined magnesia. The Gulf Coast region, with its chemical processing infrastructure, utilizes magnesia in flue-gas desulfurization.
Germany
Germany's industrial base requires high-purity magnesia for advanced ceramics and specialty refractories. Europe's REACH directive mandates comprehensive chemical safety assessments for all magnesia products. The Rhine-Ruhr area, a traditional industrial heartland, hosts specialized magnesia processing facilities.
India
India's expanding steel and cement sectors fuel demand for refractory-grade magnesium oxide. The Bureau of Indian Standards (BIS) sets quality benchmarks for industrial minerals. Odisha, with its growing steel production, represents a significant consumption hub for magnesia.
Global Magnesium Oxide Market Key Industry Players
Premium-margin players sit above commodity-margin players across product purity and service integration in the magnesium oxide market. The industry exhibits a tiered structure, with integrated solution providers at the top and raw material extractors at the base. Strategic archetypes include global solution providers, regional specialists, and cost-driven commodity producers. Companies pursue capacity expansion and strategic partnerships to secure market share.
RHI Magnesita, a global leader, exemplifies the integrated refractory solution provider archetype. Haicheng Magnesite Group Co., Ltd., a Chinese entity, anchors the cost-competitive, scale-driven segment due to its extensive domestic reserves. Martin Marietta Magnesia Specialties, a US-based firm, occupies a position among regional specialists focusing on high-value applications.
| Leading Market Players |
|---|
| Premier Magnesia |
| Grecian Magnesite |
| Haicheng Magnesite Group Co., Ltd. |
| Ube Industries Ltd. |
| Israel Chemicals Ltd. |
| Magnezit Group |
| Martin Marietta Magnesia Specialties |
| Meishen Technology Co., Ltd. |
| RHI Magnesita |
| Others |
Cost & Logistics Intelligence
Large, state-influenced producers leveraging vast domestic reserves connect directly to supply behavior and pricing discipline in the magnesium oxide market. This structural dynamic ensures cost-competitiveness for bulk materials while influencing global availability.
Pricing Analysis
Contract-based long-term offtake agreements dominate pricing for industrial-grade magnesium oxide, reflecting stable demand from steel and cement sectors. Price differentiation stems from product purity levels, such as high-purity fused magnesia, and geographic delivery costs. Pricing pressure stems from energy price volatility affecting calcination processes, compressing margins for producers without long-term energy contracts. Buyers in the steel industry are highly price-sensitive for dead-burned magnesia, while electronics manufacturers exhibit lower sensitivity for ultra-high-purity grades.
Supply Chain Analysis
Regulatory compliance requirements, including Europe's REACH directive for chemical safety, critically gate entry into certain markets. Supply concentrates heavily in China, drawing from its extensive magnesite ore reserves, with other significant sources in the United States and Germany. The supply chain relies on magnesite ore and energy inputs like natural gas and electricity. Geopolitical supply risk, particularly potential export restrictions from China, represents a significant structural vulnerability for global buyers. Distribution typically runs through direct sales to large industrial consumers, complemented by specialized distributors for smaller volume or niche applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a margin-expansion story driven by increasing demand for high-purity applications and investments in energy-efficient production technologies.
For Market Incumbents:
Deepen vertical integration into raw material sourcing to mitigate geopolitical supply risks and stabilize input costs. Modernize kiln technologies in key production hubs like China's Liaoning province to meet stricter MEE environmental standards and improve energy efficiency. Invest in R&D for advanced ceramics and specialty glass applications, commanding premium pricing. Diversify geographic production footprints beyond concentrated regions to enhance supply chain resilience against regulatory shifts.
For New Entrants and Emerging Players:
A significant price-point gap exists between commodity-grade and high-purity magnesium oxide, offering entry opportunities. Target underserved industrializing economies, particularly India and Southeast Asia, where steel and cement production are expanding rapidly. Focus on niche specialization in agricultural-grade caustic-calcined magnesia, which offers consistent, non-cyclical demand. Develop a go-to-market strategy emphasizing bundled technical services and customized product formulations for specific end-use processes.
For Investors and Strategic Acquirers:
Valuations sit cheapest among commodity-focused producers lacking diversified product portfolios or advanced production capabilities. The long-term viability of magnesium oxide as an essential industrial input remains strong over a 5-10 year window, particularly with growing specialty demand. Identify acquisition targets among regional specialists with proprietary high-purity processing technologies or strong environmental compliance track records. The signal to watch is the pace of technological adoption for green production methods and shifts in global trade policies impacting raw material flows.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Adopting advanced kiln technologies reduces CO2 emissions, aligning with global environmental policies like China's dual carbon goals. |
| Long-term Supply Agreements | Securing stable raw material access mitigates price volatility and ensures consistent production for key customers. |
| Capacity Expansion in Industrializing Economies | Building new production facilities in India capitalizes on rising steel and cement demand, diversifying geographic footprint. |
| R&D in High-Purity Applications | Developing ultra-high-purity magnesia opens new markets in electronics and advanced ceramics, commanding premium pricing. |
| Backward Integration into Magnesite Mining | Gaining upstream control over magnesite reserves enhances cost stability and reduces reliance on external raw material suppliers. |
Research Approach
Bottom-up steel industry modeling reconciled against top-down magnesite ore supply tracking forms the analytical core for this market study. The methodology combines extensive primary interviews with plant managers, procurement leads, R&D directors, and environmental compliance officers. Secondary validation draws from customs data, company annual reports, government environmental agency reports, and industry association publications, ensuring robust data triangulation.
An input-output matrix frames the analytical framework across the projection horizon, modeling demand and supply dynamics without specific year references. Segmentation dimensions include product type, application, grade, packaging type, and regional production capacity. Compound annual growth rates were derived from historical data analysis and projected market dynamics, factoring in steel production forecasts and agricultural yield trends as key inputs.
Caveats apply where geopolitical trade policies or significant energy market volatility could materially shift the outlook. Forecasts reflect assumptions regarding regulatory stability and technological advancements in calcination. A model refresh is warranted upon material change in global industrial output or environmental policy enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Global Magnesium Carbonate Minerals Market
Metals & Minerals
USA and Canada Copper Market
Metals & Minerals
Dolomite Market
Metals & Minerals
Middle-East and Africa Sodium Sulfide Market
Metals & Minerals
Global Artificial Rutile Market
Metals & Minerals
Flake Graphite Market
Metals & Minerals
Bauxite Market
Metals & Minerals
Global Ferrous Scrap Recycling Market
Metals & Minerals
Global Nickel Hydroxide Market
Metals & Minerals
Bauxite Mining Market
Metals & Minerals
Manganese Mining Market
Metals & Minerals
Pre-Painted Galvanised Iron (PPGI) Market
Metals & Minerals
Ilmenite Market
Metals & Minerals
Diamond Market
Metals & Minerals
Beryllium Hydroxide Market
Metals & Minerals
Recycled Copper Market