
 Middle-East and Africa Sodium Sulfide Market | 2026-2036
Middle-East and Africa Sodium Sulfide Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Sodium Sulfide Market Foresight
Membrane electrolysis technology is tilting sodium sulfide production away from traditional carbon-reduction furnaces toward cleaner electrochemical pathways. Dubichem leverages its Gulf-based logistics network to sustain just-in-time deliveries across UAE and Saudi industrial zones. Solvay anchors European technical standards into African operations through its regional distribution partnerships. Iran Sodium Sulphide Company dominates indigenous supply across Central Asian trade corridors.
Sodium sulfide (Na₂S) is an inorganic alkali metal sulfide typically manufactured via reduction of sodium sulfate with carbonaceous material at temperatures exceeding 900°C, yielding products with 60-62% Na₂S content for industrial mercerization and sulfur dye reduction. The compound serves as a critical depilatory agent in leather processing and as a pulping chemical in kraft paper manufacturing. Liquid sodium sulfide commands the largest volume share due to its ease of handling in continuous-process tanneries, while flake sodium sulfide captures premium pricing from remote mining operations requiring stable shelf-life. Water treatment applications are expanding fastest as Gulf states enforce stricter effluent standards on petrochemical complexes.
South Africa's Department of Water and Sanitation enforces General Authorisation limits on sulfide discharge, while Saudi Arabia's Presidency of Meteorology and Environment mandates environmental impact assessments for new chemical processing facilities. Egypt's Environmental Affairs Agency inspects tannery clusters in Cairo's Robbiki Leather City for compliance with hazardous chemical storage protocols. Stakeholders must monitor how Gulf Cooperation Council harmonization of industrial chemical standards reshapes cross-border procurement and local manufacturing investment decisions.
Market Dynamics
Membrane electrolysis technology is redirecting sodium sulfide production away from carbon-reduction furnaces toward electrochemical pathways with lower emissions intensity. This shift compresses capital requirements for new entrants while tightening environmental compliance standards across Middle Eastern and African manufacturing zones.
Growth Catalysts
- Egypt's Law 4/1994 wastewater amendments:Tanneries and textile mills in Cairo's Robbiki Leather City must upgrade chemical treatment protocols, expanding sodium sulfide consumption for effluent sulfide precipitation.
- KwaZulu-Natal pulp integration:South Africa's paper sector maintains captive sulfide supply chains that absorb steady volumes for kraft pulping operations.
- Leather processing expansion:Dehairing operations across Morocco and Tunisia are scaling sodium sulfide offtake as North African tanneries serve European footwear supply chains.
Market Restraints
- Carbon-based reduction furnace dependency:Traditional manufacturing requires temperatures exceeding 900°C with petroleum coke or coal inputs, exposing producers to volatile fossil fuel pricing.
- Central Asian supply corridor dominance:Iranian production concentration creates transit vulnerabilities for Gulf Cooperation Council buyers dependent on overland routes through geopolitically sensitive territory.
- Sodium hydrosulfide substitution:Mining flotation and some leather applications can substitute NaHS for Na₂S, capping pricing power in commodity-grade segments.
Strategic Opportunities
- Saudi Arabia's environmental impact assessment mandate:The Presidency of Meteorology and Environment requires comprehensive chemical facility reviews, creating demand for cleaner electrochemical sulfide production technologies.
- UAE petrochemical effluent enforcement:Stricter Gulf state discharge standards on petrochemical complexes are accelerating water treatment applications as the fastest-expanding sodium sulfide consumption category.
- Flake format premium capture:Remote mining operations across Southern Africa require stable shelf-life products, allowing solid-form suppliers to command pricing premiums over liquid alternatives.
Industry Challenges
- Electrochemical process engineering expertise:Membrane electrolysis adoption requires specialized technical talent scarce in regional chemical engineering labor markets.
- Legacy furnace asset stranding:Existing carbon-reduction infrastructure in Egypt and Iran faces accelerated obsolescence risk as environmental standards tighten, complicating capital recovery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Sodium Sulfide Market |
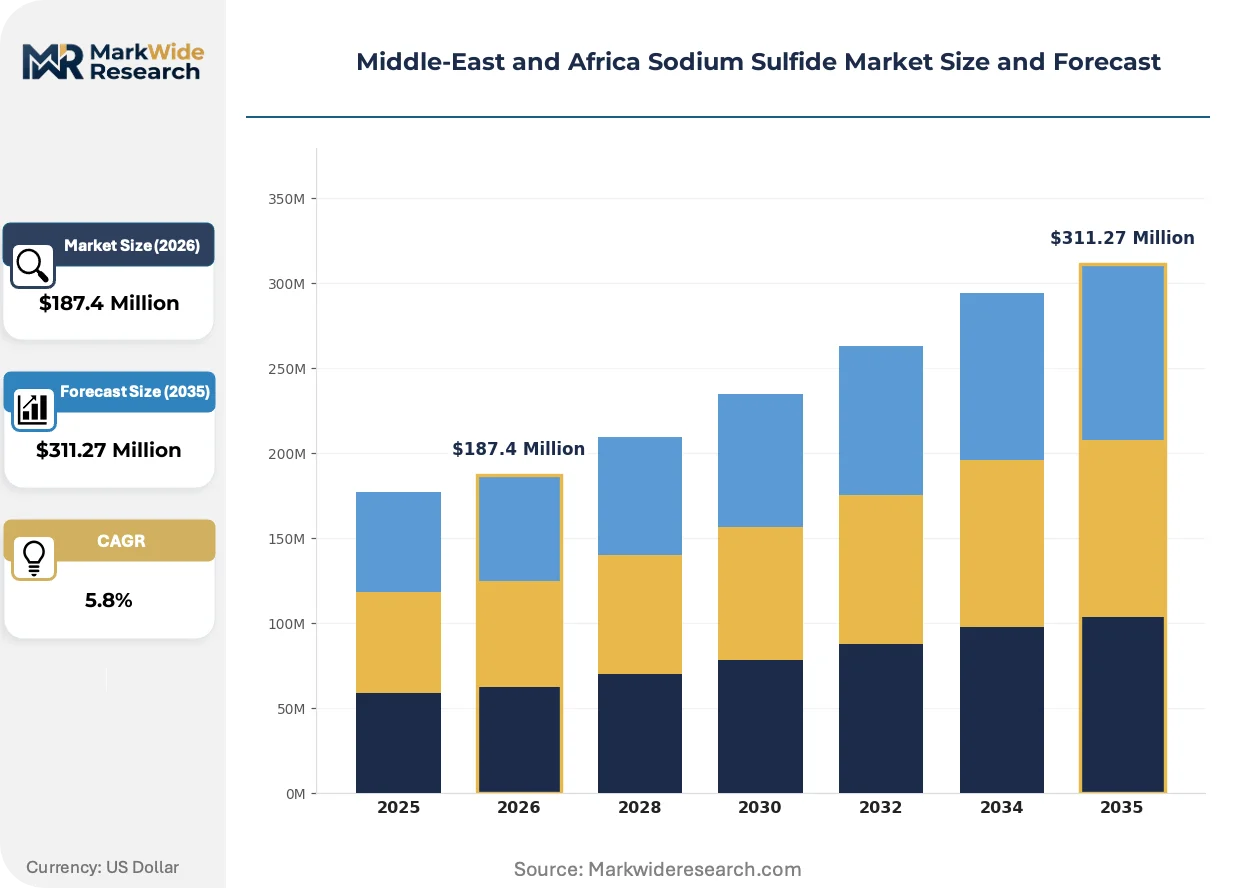
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Sodium Sulfide, Powdered Sodium Sulfide, Granulated Sodium Sulfide, Flake Sodium Sulfide End User: Pulp & Paper Industry, Textile Industry, Leather Processing, Water Treatment Application: Pulping, Dyeing, Dehairing, Wastewater Treatment Form: Solid, Liquid, Crystalline, Amorphous |
| Companies Covered | Alfa Aesar, Innova Priority Solution, Dubichem, ISSC, Kimia, Solvay, Eltee International, Tessenderlo Group, Iran Sodium Sulphide Company, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Sodium Sulfide Market Shifts & Advancements
Production technology and regulatory enforcement are converging to reshape competitive positioning across Middle Eastern and African sodium sulfide supply chains. Three developments are restructuring how value is created and captured in this market.
Membrane electrolysis systems are eliminating hydrogen sulfide byproduct streams while cutting energy intensity versus traditional furnace reduction. South African and UAE chemical processors are piloting these installations to preempt regulatory penalties. Carbon-intensive furnace operations are rendering obsolete for new capacity additions in jurisdictions with enforceable emissions ceilings.
Saudi Arabia's Presidency of Meteorology and Environment has mandated environmental impact assessments for all new chemical processing facilities, extending review timelines by 12-18 months. This procedural friction favors incumbent producers with established permits while raising barriers for greenfield entrants. Domestic Saudi manufacturers are responding by retrofitting existing assets rather than pursuing new site approvals.
Continuous-process tanneries are consolidating procurement volumes through direct offtake agreements with sulfide producers, bypassing traditional chemical distributor networks. This disintermediation compresses margins for trading intermediaries while locking in volume commitments for primary manufacturers. The pattern is most visible in Tunisia's tanning cluster, where large integrated tanneries have established direct supply relationships with Gulf-based producers.
Middle-East and Africa Sodium Sulfide Market Segmentation
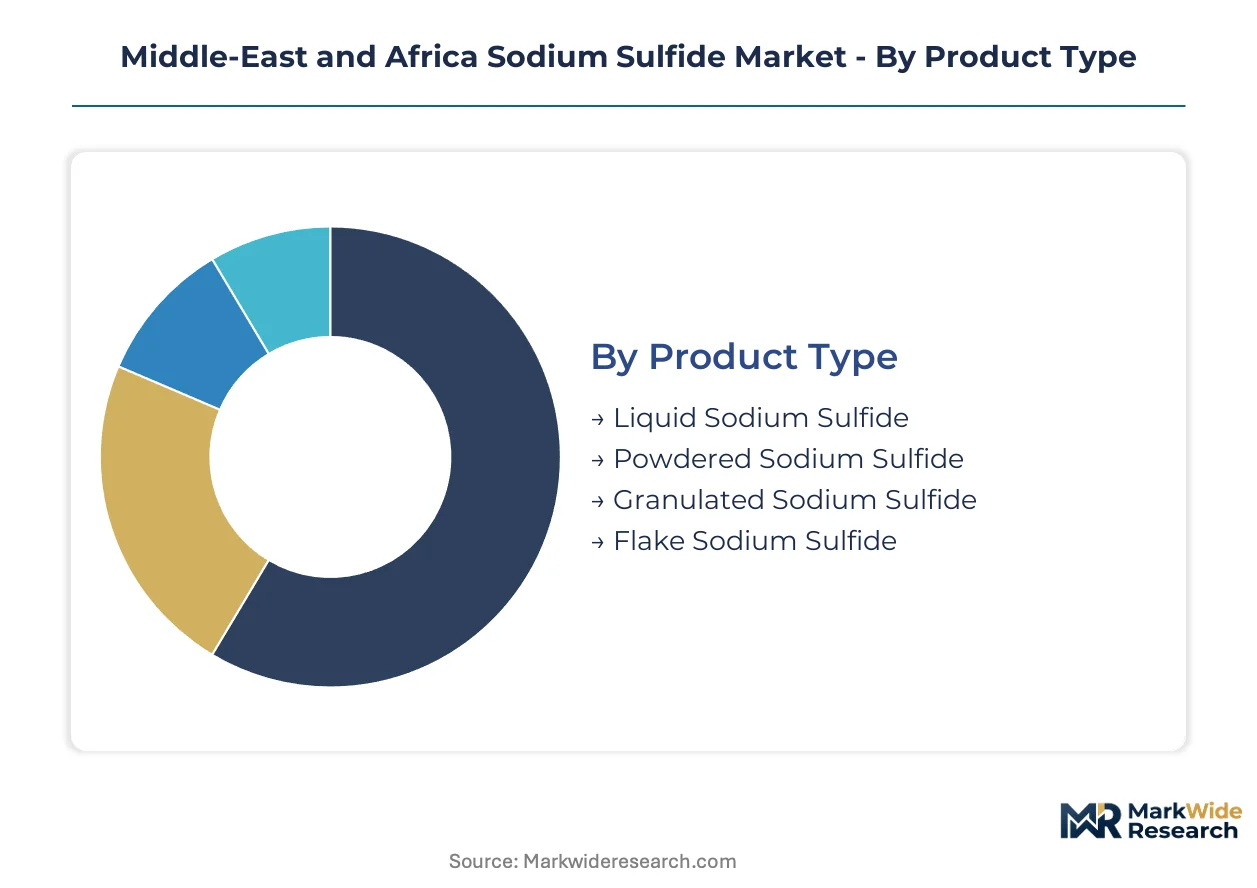
Segmentation in the Middle-East and Africa Sodium Sulfide Market reveals how physical form, end-use chemistry, and regional regulatory pressure differentially shape procurement patterns. Distinct technical requirements across tanneries, pulp mills, and petrochemical complexes fragment demand into specialized supply channels with varying service intensity needs.
Product Type:
After-sales service intensity varies sharply across physical formats, with liquid systems demanding continuous technical support for storage and handling infrastructure.
- Liquid Sodium Sulfide:Aqueous solutions with 30-60% Na₂S concentration enable direct injection into continuous-process tanneries without dissolution equipment. Demand concentrates in Tunisia's integrated tanning clusters where European footwear supply chains require consistent dehairing chemistry.
- Flake Sodium Sulfide:Solid plates with 60-62% Na₂S content offer extended shelf stability critical for remote mining operations across Southern Africa. KwaZulu-Natal's pulp sector absorbs steady volumes through captive supply chains optimized for kraft pulping operations.
- Powdered Sodium Sulfide:Fine particulate form enables rapid dissolution for batch textile processing in Egypt's Robbiki Leather City facilities.
- Granulated Sodium Sulfide:Free-flowing spherical particles reduce dust exposure during handling in Saudi petrochemical wastewater treatment installations.
Liquid sodium sulfide holds the largest share; momentum sits with flake formats as remote mining applications expand.
End User:
Cost tier differentiation separates commodity-grade sulfide buyers from premium-specification purchasers with stringent purity requirements.
- Leather Processing:Dehairing operations across Morocco and Tunisia absorb technical-grade sodium sulfide for hide depilation, with Egyptian tanneries upgrading treatment protocols under Environmental Affairs Agency inspections.
- Pulp & Paper Industry:Kraft pulping in South Africa's KwaZulu-Natal province maintains integrated sulfide supply chains with dedicated logistics infrastructure for white liquor regeneration cycles.
- Water Treatment:Petrochemical complexes across UAE and Saudi Arabia deploy sulfide for heavy metal precipitation as Gulf states enforce stricter effluent discharge standards.
- Textile Industry:Sulfur dye reduction for fabric coloration operates through merchant chemical distributors in Egypt's textile manufacturing zones.
Leather processing commands the dominant volume position; water treatment is climbing the fastest as environmental compliance tightens.
Application:
Application chemistry determines whether sulfide functions as a reductant, precipitant, or depilatory agent, with each use case imposing distinct purity and concentration specifications.
- Dehairing:Hide depilation in North African tanneries requires controlled alkalinity for collagen preservation without grain damage, with Cairo's Robbiki cluster representing concentrated demand.
- Wastewater Treatment:Heavy metal sulfide precipitation in Gulf petrochemical facilities demands rapid reaction kinetics for cadmium, lead, and mercury removal under tightening discharge limits.
- Pulping:White liquor regeneration in kraft processes consumes sulfide for lignin solubilization, with South African paper mills maintaining captive chemical recovery systems.
- Dyeing:Sulfur vat reduction for textile coloration operates at lower specification grades through merchant distribution channels.
Dehairing retains the largest application share; wastewater treatment shows the steepest expansion trajectory as industrial effluent standards proliferate.
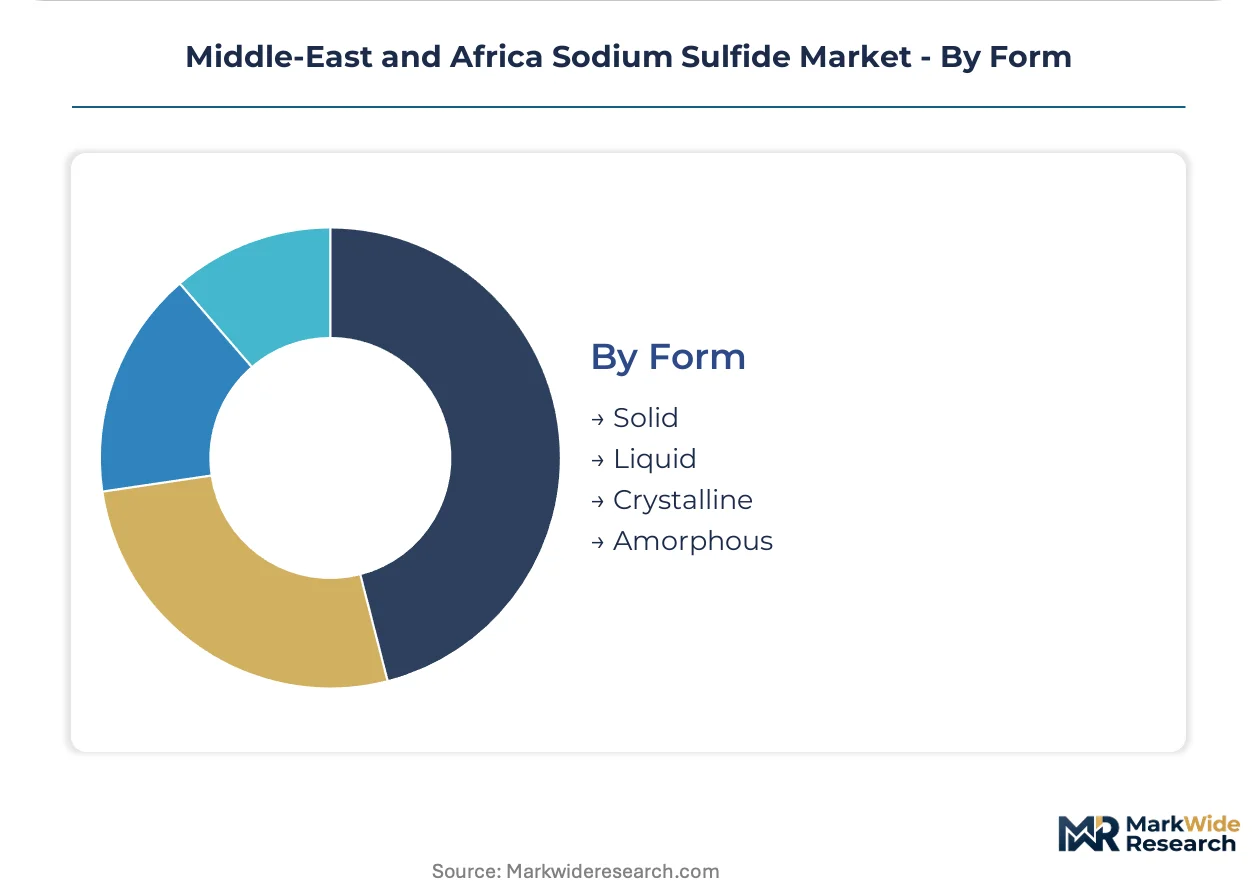
Form:
Supply concentration in crystalline production creates procurement advantages for buyers with dissolution infrastructure, while amorphous alternatives serve niche specifications.
- Solid:Flake and powder formats enable long-distance transport to remote mining sites across Southern Africa with minimal degradation risk.
- Liquid:Ready-to-use solutions eliminate dissolution capital for continuous-process tanneries in Tunisia and Morocco.
- Crystalline:Purified sodium sulfide nonahydrate serves analytical and specialty chemical applications with stringent impurity limits.
- Amorphous:Rapidly quenched glassy sulfide accommodates specialized metallurgical flux applications with non-standard dissolution profiles.
Solid forms dominate procurement volumes; crystalline grades are gaining share fastest in specialty chemical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iranian producers supply Central Asian trade corridors feeding Gulf Cooperation Council buyers, while South African integrated pulp operations maintain captive sulfide networks. Egyptian tannery clusters and Moroccan leather processing drive North African consumption patterns.
South Africa
KwaZulu-Natal province anchors regional pulp and paper sulfide demand through kraft pulping operations with dedicated white liquor regeneration systems. The Department of Water and Sanitation enforces General Authorisation limits on sulfide discharge into receiving waters. Durban-based chemical processors maintain integrated supply chains serving paper mills with continuous sulfide delivery infrastructure.
Egypt
Cairo's Robbiki Leather City concentrates dehairing chemical demand from tanneries serving European footwear supply chains. The Environmental Affairs Agency inspects facilities for compliance with hazardous chemical storage protocols under Law 4/1994 wastewater amendments. Alexandria port logistics enable Red Sea transit for sulfide imports reaching Nile Delta textile manufacturing zones.
Saudi Arabia
Petrochemical wastewater treatment applications are expanding fastest as the Presidency of Meteorology and Environment mandates environmental impact assessments for new chemical processing facilities. Eastern Province industrial cities host the kingdom's heaviest sulfide consumption for heavy metal precipitation in effluent streams. Jubail petrochemical complexes deploy sulfide dosing systems for cadmium and mercury removal under tightening discharge standards.
UAE
Dubai and Abu Dhabi industrial zones absorb Gulf-based logistics networks sustaining just-in-time sulfide deliveries to continuous-process operations. Stricter federal effluent enforcement on petrochemical complexes accelerates water treatment chemical procurement. Jebel Ali port infrastructure supports re-export trade serving neighboring Gulf states with limited indigenous chemical production capacity.
Morocco
Tangier and Casablanca tanning clusters scale sodium sulfide offtake for hide dehairing operations integrated into European leather goods supply chains. The country's national environmental regulator monitors tannery chemical discharge into Mediterranean coastal waters. Fez traditional tanneries modernize depilatory chemical handling as export certification requirements tighten for EU market access.
Middle-East and Africa Sodium Sulfide Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement and distribution layers. The vendor base separates into Gulf-based logistics integrators, European technical standard-setters, and indigenous furnace operators. Three archetypes dominate: regional distributors with port-adjacent storage, multinational chemical houses leveraging technical specifications, and national champions serving protected domestic markets. Capacity expansion and direct offtake agreements with large tanneries represent the dominant competitive moves.
Among Gulf-based distributors, Dubichem occupies a position exemplifying logistics-integrated supply chain control. Solvay represents the European technical standards archetype through regional distribution partnerships. Iran Sodium Sulphide Company anchors the indigenous production tier serving Central Asian trade corridors. These three entities illustrate how geographic positioning and regulatory relationships structure competitive advantage across the Middle-East and Africa sodium sulfide market.
| Leading Market Players |
|---|
| Alfa Aesar |
| Innova Priority Solution |
| Dubichem |
| ISSC |
| Kimia |
| Solvay |
| Eltee International |
| Tessenderlo Group |
| Iran Sodium Sulphide Company |
| Others |
Supply & Pricing Matrix
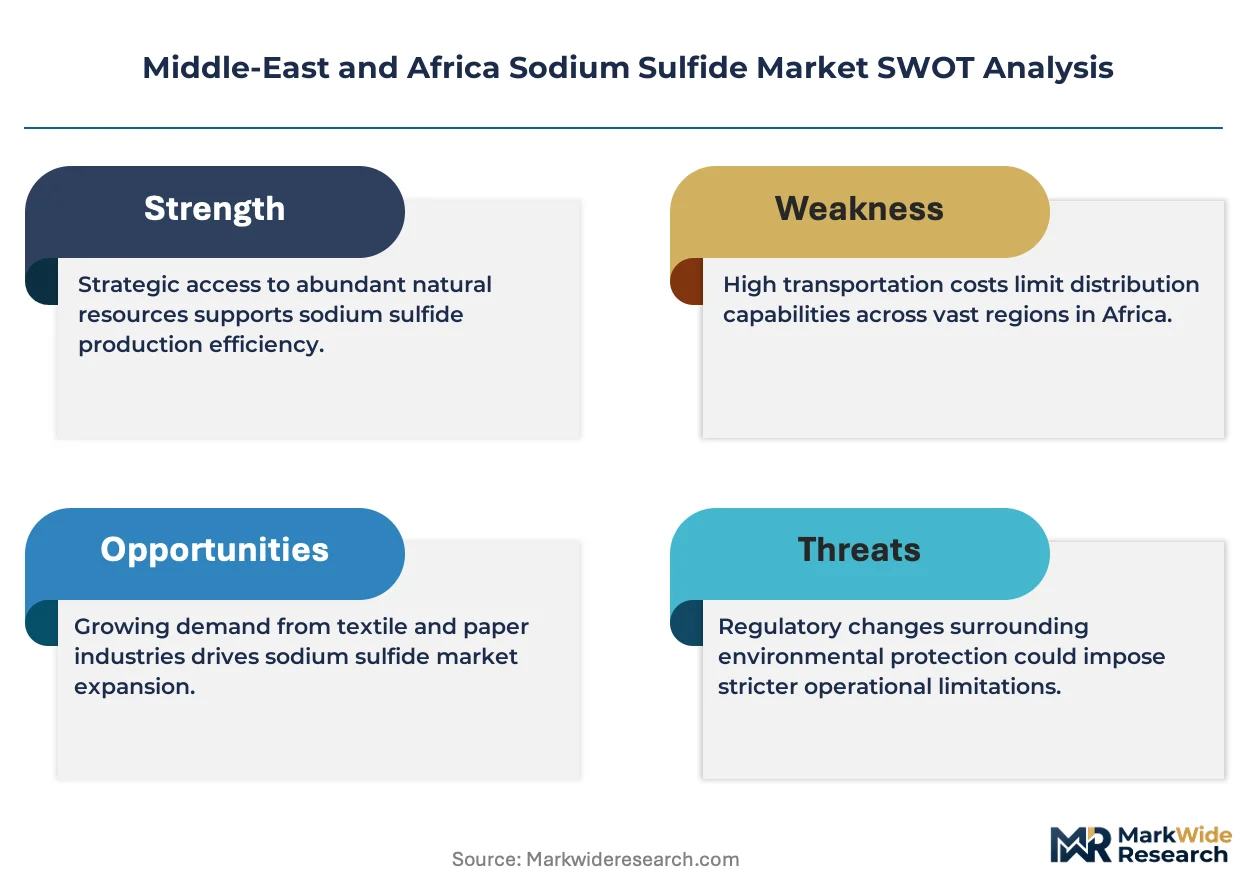
KwaZulu-Natal's captive pulp mill supply chains concentrate regional sodium sulfide procurement power, allowing integrated paper producers to negotiate long-term offtake terms that compress margins for merchant suppliers serving smaller tanneries and textile processors across North Africa.
Pricing Analysis
Carbon-reduction furnace technology commands lower unit costs against membrane electrolysis installations, though the latter captures pricing premiums from Saudi and UAE buyers facing Presidency of Meteorology and Environment emissions mandates. Pricing stratifies across electrochemical-grade, technical-grade, and commodity-grade tiers, with flake formats commanding transport-adjusted premiums for remote Southern African mining operations. Cost compression in liquid sodium sulfide is intensifying because Dubichem's Gulf-based logistics network enables just-in-time delivery economics that undercut inventory-heavy distributor models. Continuous-process tanneries in Tunisia exhibit the highest price sensitivity due to direct procurement consolidation, while petrochemical wastewater treatment operators accept specification premiums for granulated formats with reduced handling exposure.
Supply Chain Analysis
Petroleum coke and sodium sulfate feedstock costs tether Egyptian and Iranian furnace operators to volatile fossil fuel pricing, while membrane electrolysis adopters in South Africa and the UAE draw from more stable electrical input structures. Supply concentrates in Iran's Central Asian corridor, Egypt's Nile Delta production zones, and South Africa's KwaZulu-Natal chemical processing hub. Raw material dependencies span carbonaceous reductants, sodium sulfate, and specialized membrane components for electrochemical cell assemblies. Single-source vulnerability runs through Iranian overland transit routes subject to geopolitical disruption. Distribution runs through port-adjacent storage facilities at Jebel Ali, Alexandria, and Durban, with Gulf-based logistics integrators controlling last-mile delivery to continuous-process industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane electrolysis technology disruption is accelerating competitive restructuring across Middle-East and Africa sodium sulfide supply chains, as Saudi environmental impact assessment mandates and UAE effluent enforcement create preferential market access for cleaner production technologies.
For Market Incumbents: Pre-empt sodium hydrosulfide substitution threats by retrofitting existing carbon-reduction assets with electrochemical pilot lines in Saudi Arabia's Eastern Province, while securing long-term offtake agreements with Robbiki Leather City tanneries to lock in volume before direct procurement consolidation advances further. Backward integration into sodium sulfate supply through Red Sea port storage investments will defend margin position against feedstock volatility.
For New Entrants and Emerging Players: Pursue water treatment application specialization targeting UAE petrochemical complexes facing tightening federal discharge standards, where technical service intensity creates barriers to commodity distributor incumbents. The most penetrable segment lies in granulated sodium sulfide for heavy metal precipitation systems, with go-to-market execution through engineering-procurement-construction contractor partnerships rather than traditional chemical distribution channels.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors membrane electrolysis equipment suppliers and electrochemical-grade chemical processors with established Saudi permitting relationships over legacy furnace operators facing accelerated obsolescence. Long-term viability across the projection horizon rests on regulatory enforcement durability rather than commodity cycle exposure. Acquisition targets should demonstrate Presidency of Meteorology and Environment compliance certification and direct tannery offtake agreements. The signal to watch is Gulf Cooperation Council harmonization of industrial chemical standards, which would reshape cross-border procurement economics and local manufacturing investment thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Electrolysis Capacity Buildout | Presidency of Meteorology and Environment compliance unlocks Saudi and UAE market access against carbon-intensive competitors. |
| Backward Integration into Sodium Sulfate Supply | Red Sea port storage investments at Alexandria and Jebel Ali reduce feedstock cost volatility for Egyptian and Gulf producers. |
| Direct Offtake Agreements with Tannery Clusters | Robbiki Leather City and Tangier tanning cluster procurement consolidation bypasses distributor margin compression. |
| Granulated Format Specialization for Water Treatment | UAE petrochemical effluent enforcement creates specification-premium capture opportunities in heavy metal precipitation applications. |
| Joint Venture with Gulf Logistics Integrators | Dubichem's port-adjacent infrastructure enables just-in-time delivery economics for continuous-process industrial customers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with sodium sulfide plant managers, leather processing procurement leads, pulp mill chemical recovery directors, and Gulf-based distribution channel partners; and secondary validation against customs and trade flow data, ACC and Cefic chemical industry reports, SEC 10-K filings from multinational chemical houses, and environmental regulator disclosure databases. Bottom-up triangulation across product format, end-use industry, and regional production hub dimensions was cross-checked against top-down market sizing from consumption-side application analysis.
Forecast inputs considered electrochemical technology adoption curves, kraft pulp capacity utilization across KwaZulu-Natal, tannery cluster expansion in North Africa, and petrochemical wastewater treatment mandate enforcement timelines across the analysis window. Segmentation modeling spanned physical form, end-use chemistry, application chemistry, and crystalline versus amorphous structure. CAGRs were derived from regression analysis of historical consumption patterns against regulatory inflection points and capacity addition announcements, with electrochemical process economics and carbon-reduction furnace feedstock costs as primary industry-specific forecast drivers.
Sensitivities concentrate around Gulf Cooperation Council regulatory harmonization timing, Iranian transit corridor stability, and membrane electrolysis technology cost reduction trajectories. Cross-checking against chemical industry capacity utilization benchmarks and tannery cluster production data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Silver Salt Market
Metals & Minerals
Rare Earth Elements Market
Metals & Minerals
Cesium Market
Metals & Minerals
North America and EMEA Ferrosilicon Market
Metals & Minerals
Global Base Metal Mining Market
Metals & Minerals
20MnCr5 Steel Market
Metals & Minerals
Bauxite Mining Market
Metals & Minerals
Global Magnesium Oxide Market
Metals & Minerals
Zinc Sulfate Market
Metals & Minerals
Zellerite Market
Metals & Minerals
Dead Sea Mineral Market
Metals & Minerals
USA and Canada Copper Market
Metals & Minerals
Zinc Citrate Market
Metals & Minerals
Colored Gemstones Market
Metals & Minerals
Prefab Iron Market
Metals & Minerals
Selenium Market