
 Chromium Mining Market | 2026-2036
Chromium Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Chromium Mining Market Intelligence
Advanced ore characterization and certification services are decoupling the raw material price from its associated logistical and processing costs. This shift creates new value pools around data and supply chain management. Eurasian Resources Group leverages its extensive integrated logistics network to manage these separated cost components effectively. Samancor Chrome sustains its market position through large-scale, low-cost mining operations, while Glencore Plc competes across the entire value chain, from mine ownership to the global marketing of ferrochrome.
Chromium mining involves the extraction of chromite ore, a mineral composed primarily of iron, magnesium, aluminum, and chromium oxide (Cr2O3). The principal industrial application of this ore is the production of ferrochrome, an alloy essential for manufacturing stainless steel. The ferrochrome product form dominates market value, directly supplying the stainless steel production end-user segment which consumes the vast majority of output. While open-pit mining constitutes the bulk of extraction, the profitability of underground methods is entirely dependent on accessing high-grade ore deposits with significant chromite concentrations.
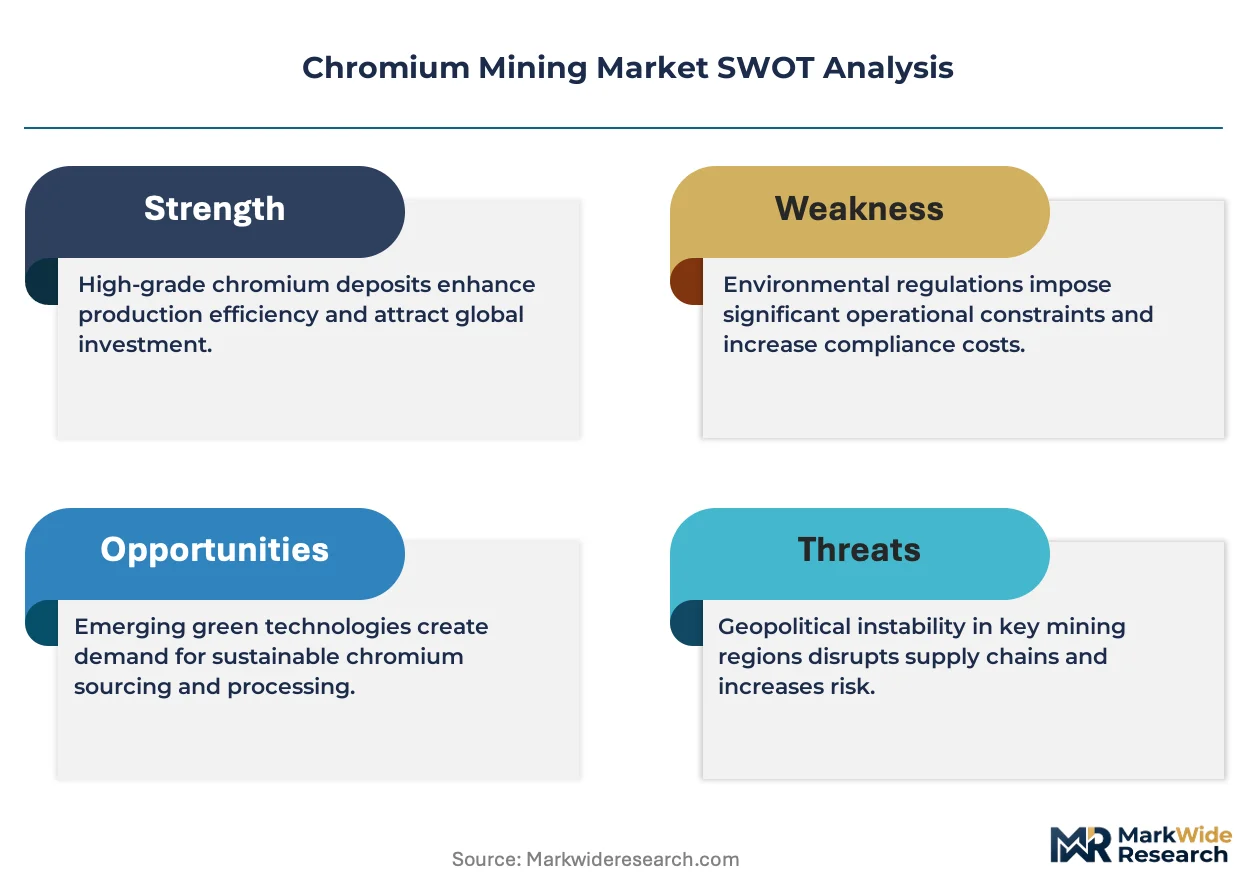
A complex web of national regulations, including South Africa's mining charters, China's MEE environmental mandates, and the EU's REACH substance registration, defines operational constraints. These policies dictate mine-site environmental compliance, worker safety protocols under frameworks like OSHA, and the specific chemical composition for exported chromium products. Future profitability will depend on successfully navigating divergent environmental standards and trade policies between major producing and consuming nations.
Market Dynamics
The fundamental market dynamic is the tension between highly concentrated chromite ore production, primarily in South Africa, and the stringent, divergent environmental and product standards of major consuming regions like China and the European Union, which complicates trade flows and pricing.
Growth Catalysts
- Stainless Steel Production:Continued expansion of the stainless steel sector, especially in China, remains the principal demand driver for ferrochrome, consuming the majority of chromite ore output.
- Furnace Technology:Innovations in electric arc furnace (EAF) and submerged arc furnace (SAF) technologies are improving energy efficiency and enabling the economic processing of lower-grade and fine chromite ores.
- Infrastructure Investment:Public and private spending on large-scale infrastructure projects globally stimulates demand for stainless steel and specialty steels, thereby increasing the underlying demand for chromium.
Market Restraints
- Energy Costs:The production of ferrochrome is an extremely energy-intensive process, making smelter operations highly vulnerable to electricity price volatility and supply interruptions, particularly in South Africa.
- Geographic Concentration:The heavy reliance on a few countries, notably South Africa and Turkey, for chromite ore supply creates significant logistical bottlenecks and exposes the market to geopolitical risks.
- Substitution Threats:In certain non-critical applications, the potential for substitution with other materials or with stainless steel grades that have lower chromium content poses a long-term restraint on value growth.
Strategic Opportunities
- Specialty Applications:Increasing use of chromium in non-metallurgical applications, such as chemical production, pigments, and leather tanning, offers diversification away from the cyclical stainless steel market.
- Data-Driven Logistics:The development of advanced ore characterization and certification services creates opportunities to generate value from supply chain data, decoupling raw material price from logistical costs.
- Resource Recovery:Investing in technologies to recover chromium from stainless steel slag and other industrial waste streams presents a circular economy opportunity that can supplement primary mining output.
Industry Challenges
- Regulatory Divergence:Miners and exporters face the operational challenge of complying with a complex web of conflicting regulations, such as South Africa's mining charters, China's MEE mandates, and the EU's REACH framework.
- Capital Intensity:Developing new mining projects, especially deep underground mines required to access high-grade deposits, demands substantial upfront capital investment and involves long project lead times.
- Water Management:Chromium mining operations are water-intensive and face increasing scrutiny and regulatory constraints regarding water usage and the management of wastewater to prevent contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chromium Mining Market |
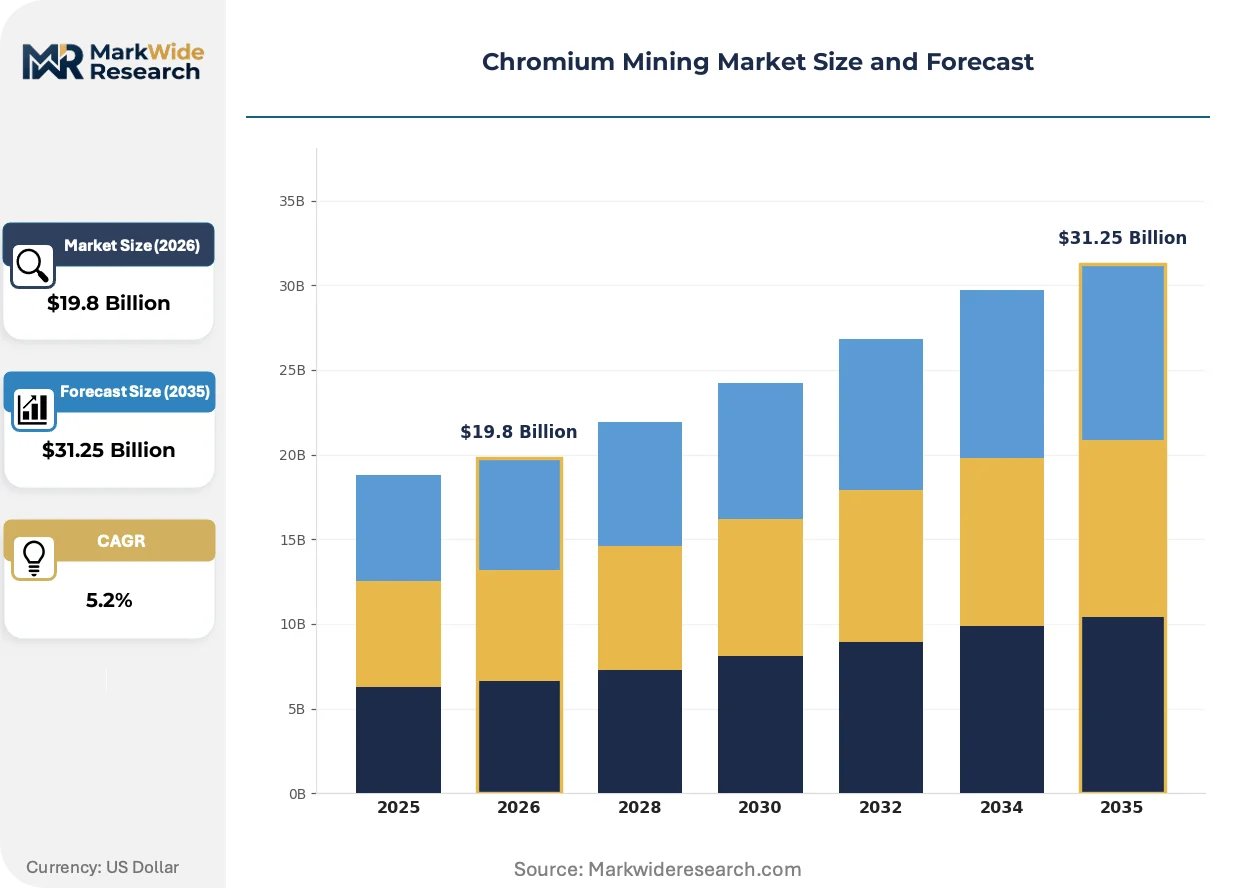
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $31.25 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Mining Method: Open-pit, Underground, Alluvial, Subsurface Product Form: Concentrate, Ferrochrome, Chromium Alloys, Powders End User Industry: Aerospace, Automotive Components, Stainless Steel Production, Refractory Materials Grade: High-grade, Low-grade, Ultra-low-grade, Metallurgical |
| Companies Covered | Eurasian Resources Group, Assore Limited, Samancor Chrome, Tharisa Plc, KWG Resources Inc, Glencore Plc, Outokumpu Oyj, Yilmaden, Afarak Group SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chromium Mining Market Strategic Shifts & Innovations
A significant evolution in the market involves the unbundling of the physical commodity from its associated data and logistical services. This shift, driven by technological advancements in ore characterization and processing, is creating new profit centers focused on supply chain optimization and verifiable product certification.
Advanced sensor-based ore sorting technology provides real-time, on-site analysis of chromite ore composition and grade. Major ferrochrome producers are adopting these systems to optimize furnace feed and reduce energy consumption per ton of alloy produced. This technology is decentralizing ore blending and quality control decisions from central laboratories directly to the mine face or processing plant, improving operational agility and resource utilization.
Environmental mandates, particularly China's "dual carbon" goals enforced by the MEE, are altering global trade dynamics. These policies compel Chinese ferrochrome smelters to reduce their carbon footprint, creating a premium for higher-grade chromite ores that require less energy to process. Ore exporters from South Africa and Kazakhstan are most affected, now needing to provide detailed chemical and carbon-intensity data to maintain access to this critical market.
A notable shift in buyer behavior is the demand for certified, traceable ore to meet corporate ESG commitments. This disrupts the traditional anonymous commodity market, as stainless steel manufacturers in Europe, bound by CSRD reporting, now require auditable proof of origin and compliance with labor and environmental standards. This trend is most visible in procurement for the automotive and construction sectors, where supply chain transparency is a key competitive differentiator.
Chromium Mining Market Segmentation
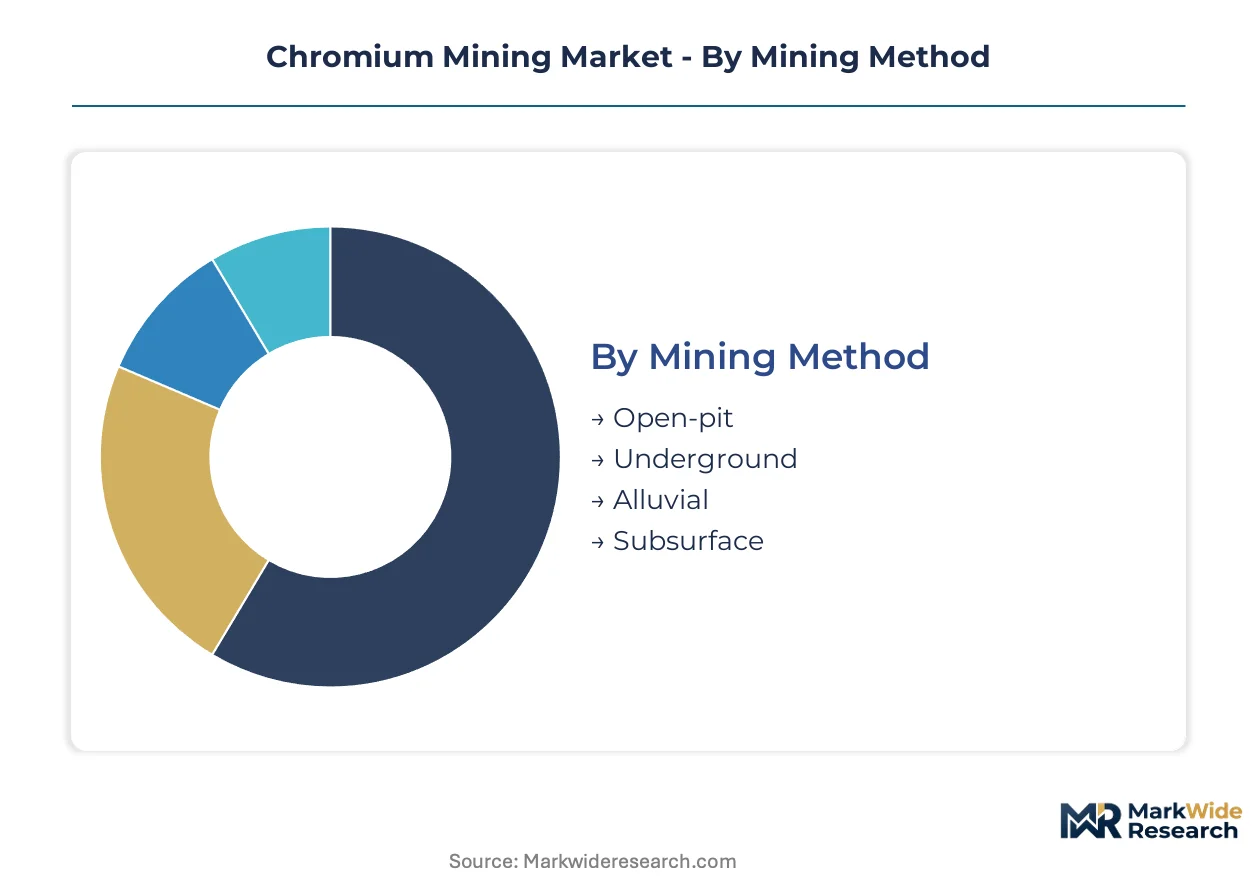
The Chromium Mining Market's segmentation reveals the intricate interplay between extraction methods, product forms, end-user requirements, and ore quality. Understanding these distinct segments allows for precise market valuation and strategic resource allocation across the complex supply chain. Each category presents unique operational challenges and market opportunities for stakeholders.
Mining Method:
Compliance with worker safety protocols under frameworks like OSHA and specific environmental mandates, such as China's MEE requirements, defines the operational viability of various chromium mining methods.
- Open-pit:This method involves extracting chromite ore from large surface excavations, offering high volume capacity and lower initial capital expenditure compared to underground operations. Open-pit mines constitute the bulk of global chromite extraction, particularly in South Africa.
- Underground:Underground mining accesses deeper, often higher-grade chromite deposits through shafts and tunnels, requiring significant upfront capital investment and advanced safety protocols. The profitability of these operations depends on accessing high-concentration ore bodies.
- Alluvial:Alluvial mining recovers chromite from riverbeds or ancient floodplains, typically involving dredging or hydraulic methods. These operations often target secondary deposits and are characterized by lower volumes.
- Subsurface:Subsurface mining refers to extraction below the earth's surface, encompassing various techniques to reach buried ore bodies. This method is employed for deposits not accessible via open-pit operations.
Leading the category by volume: Open-pit. Growing fastest: Underground.
Product Form:
The cost structure of chromium products varies significantly, influenced by processing intensity and end-use specifications across different forms.
- Ferrochrome:This alloy, composed of iron and chromium, is the primary product derived from chromite ore, essential for stainless steel manufacturing. Ferrochrome production dominates market value due to its direct supply to the stainless steel sector.
- Concentrate:Chromite concentrate is the beneficiated ore, typically enriched in chromium oxide (Cr2O3), serving as the raw material for ferrochrome and other chromium chemical production. Its quality directly impacts the energy efficiency of downstream processing.
- Chromium Alloys:These specialized alloys incorporate chromium with other metals to impart specific properties like corrosion resistance or hardness. Chromium alloys find applications in diverse industrial sectors beyond stainless steel.
- Powders:Chromium powders are finely milled metallic or alloy forms used in applications such as thermal spraying, 3D printing, and powder metallurgy. These high-purity forms cater to advanced manufacturing processes.
Ferrochrome holds the largest value share, while chromium alloys demonstrate significant expansion potential.
End User Industry:
Chromium's diverse properties support critical applications across multiple industrial sectors, each with distinct material requirements and regulatory compliance needs.
- Stainless Steel Production:This sector represents the largest consumer of ferrochrome, utilizing chromium to impart corrosion resistance and strength to various steel grades. China's expansive industrial base drives substantial demand in this segment.
- Automotive Components:Chromium is vital for producing corrosion-resistant and durable automotive parts, including exhaust systems and decorative trim. European manufacturers, bound by CSRD reporting, increasingly demand traceable chromium for these components.
- Aerospace:High-performance chromium alloys are critical in aerospace for components requiring extreme strength, heat resistance, and corrosion protection. This sector demands stringent material specifications and certifications.
- Refractory Materials:Chromite ore is used in refractory bricks and linings for furnaces, leveraging its high melting point and chemical stability. This application supports high-temperature industrial processes.
Stainless steel production commands the largest share of chromium consumption, with automotive components showing strong demand growth.
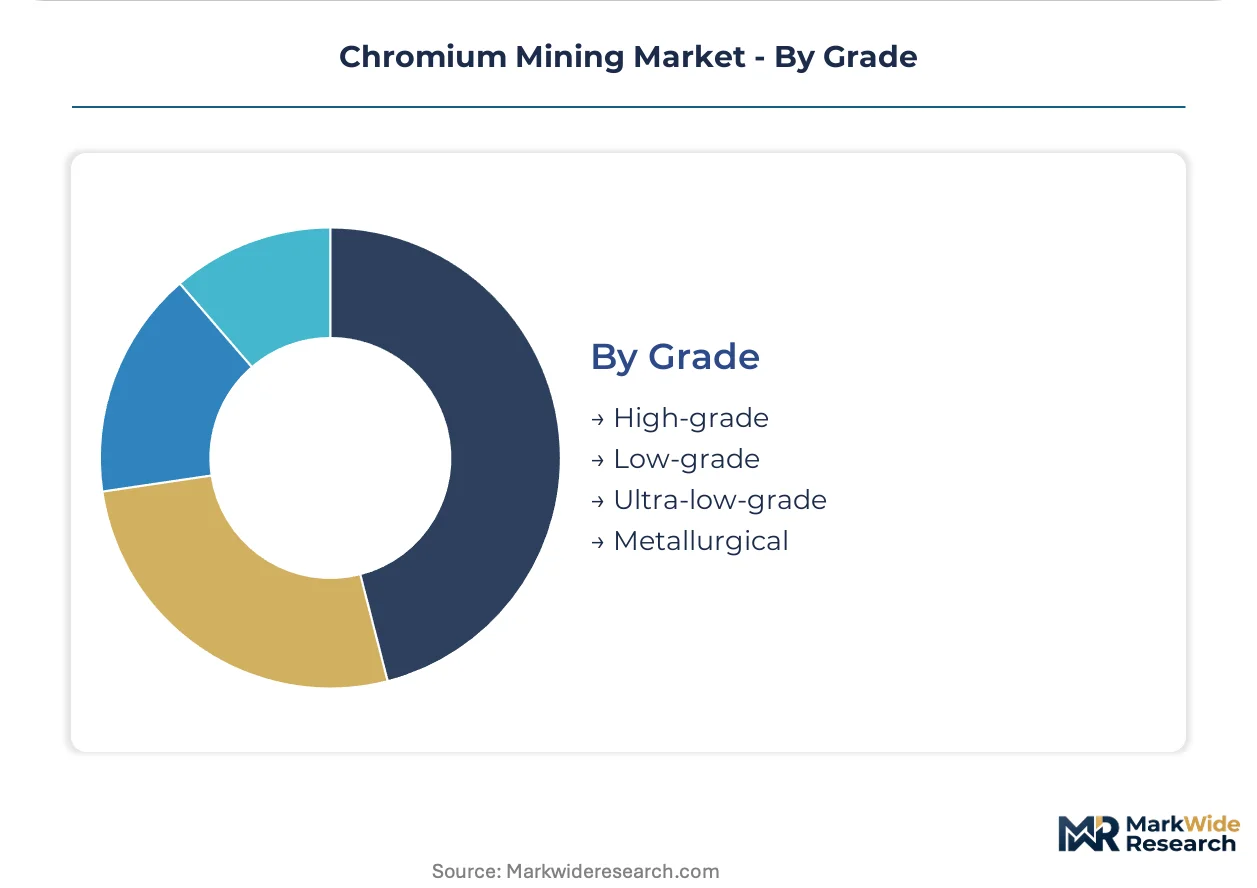
Grade:
The geographic distribution of chromite ore deposits dictates the availability and economic viability of different chromium grades for various applications.
- High-grade:Characterized by a high chromium oxide (Cr2O3) content, typically above 48%, high-grade ores command premium pricing. These ores are preferred by ferrochrome producers for their energy efficiency in processing.
- Low-grade:Containing lower Cr2O3 percentages, often between 30-45%, low-grade ores are increasingly processed due to innovations in furnace technologies like EAF and SAF. This enables economic extraction from previously uneconomical deposits.
- Ultra-low-grade:These ores possess very low chromium content, often below 30%, making their economic processing challenging. New beneficiation techniques are being explored to unlock value from these extensive resources.
- Metallurgical:Metallurgical grade chromite is specifically suited for ferrochrome production, typically requiring a high chromium-to-iron ratio. This grade is critical for stainless steel manufacturing.
High-grade ores maintain premium pricing, and lower-grade processing is gaining economic viability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global chromium mining market exhibits a fundamental divide between concentrated production and diverse consumption. South Africa dominates chromite ore supply, while major consuming regions like China and the European Union impose stringent environmental and product standards. This dynamic significantly shapes international trade flows and pricing structures.
South Africa
South Africa dominates global chromite production, supplying the majority of ore for stainless steel manufacturing. South Africa's mining charters dictate operational parameters and promote local beneficiation. The Bushveld Igneous Complex near Rustenburg represents a critical mining hub, extracting vast quantities of high-grade chromite ore.
China
China's expansive industrial base drives substantial demand for ferrochrome, primarily for stainless steel production. The MEE environmental mandates, particularly "dual carbon" goals, compel Chinese smelters to reduce their carbon intensity. Industrial clusters in provinces like Jiangsu process significant volumes of imported chromite, focusing on energy-efficient processing and higher-grade ores.
Germany
German stainless steel manufacturers require traceable chromium for automotive and construction components. The EU's REACH substance registration and CSRD reporting mandate supply chain transparency for imported chromium products. Major steel manufacturing centers in the Ruhr region depend on certified ferrochrome imports to meet these stringent requirements.
Turkey
Turkey contributes significantly to global chromite ore supply, exporting both lumpy ore and concentrates. National mining regulations govern extraction practices and environmental compliance for chromite operations. Mining regions in central Anatolia concentrate chromite extraction and initial processing activities before export.
Chromium Mining Market Key Industry Players
Top-tier vendors anchor the global chromium mining market, while specialized producers and commodity traders also hold significant positions. This market structure features vertically integrated giants managing extensive operations and focused low-cost producers. Diversified commodity traders also play a substantial role in global distribution. Strategic acquisitions and supply chain optimization represent dominant competitive moves among market participants.
Vertically integrated global players like Glencore Plc exemplify comprehensive value chain participation, spanning mine ownership to ferrochrome marketing. Samancor Chrome occupies a position as a large-scale, low-cost producer, sustaining its market presence through operational efficiency and robust output. Eurasian Resources Group represents another integrated entity, leveraging its extensive logistics network to manage complex supply chain components effectively. These companies collectively influence pricing and trade flows within the chromium mining industry.
| Leading Market Players |
|---|
| Eurasian Resources Group |
| Assore Limited |
| Samancor Chrome |
| Tharisa Plc |
| KWG Resources Inc |
| Glencore Plc |
| Outokumpu Oyj |
| Yilmaden |
| Afarak Group SE |
| Others |
Cost & Logistics Intelligence
Vertical integration by major players anchors their supply position and pricing power within the Chromium Mining Market. This strategic control over the value chain minimizes exposure to raw material price volatility and secures downstream production. Such integration is a critical competitive differentiator.
Pricing Analysis
Margin tightening across ferrochrome production reflects increasing energy costs, particularly in South Africa. The dominant pricing model remains commodity spot and long-term contract-based offtake agreements for ferrochrome. Price differentiation stems from ore quality grade, verifiable ESG certification, and geographic delivery costs. Price sensitivity is highest among bulk stainless steel producers, while aerospace manufacturers exhibit lower sensitivity due to stringent material specifications.
Supply Chain Analysis
South Africa's mining charters and China's MEE environmental mandates reshape sourcing strategies for chromite ore. Geographic supply concentrates heavily in South Africa and Turkey, creating reliance on these regions for chromite ore. This concentration introduces significant logistical bottlenecks and regulatory restriction as a structural supply chain risk. Distribution runs through a network of vertically integrated producers and specialized commodity traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Chromium Mining Market is experiencing a vertical-integration race as companies pursue upstream control over chromite ore resources. This strategy aims to secure supply and optimize processing efficiencies across the value chain.
For Market Incumbents:Anchor existing large-scale operations by optimizing processing efficiencies, especially for lower-grade ores using advanced EAF/SAF technologies. Invest in robust ESG certification and traceability systems to mitigate regulatory divergence threats from the EU's REACH and China's MEE. Consolidate logistics networks to reduce operational costs and enhance market responsiveness, countering energy cost pressures.
For New Entrants and Emerging Players:Begin with niche specialty applications, such as high-purity chromium powders for additive manufacturing, or chemical production. Target regions with less established local beneficiation mandates to gain initial market access. A go-to-market angle focused on data-driven logistics and verifiable product certification can differentiate offerings from traditional commodity players.
For Investors and Strategic Acquirers:Exit pathways concentrate in integrated low-cost producers with diversified asset bases or technology providers specializing in resource recovery. Long-term viability over a five-to-ten-year window hinges on securing high-grade deposits or innovative processing capabilities for lower-grade resources. A signal to watch is the increasing demand for certified, traceable ore beyond traditional automotive and construction sectors, indicating a shift in procurement priorities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in South Africa | Increases global chromite ore supply, addressing stainless steel production demand. |
| Backward Integration into Ore Mining | Secures raw material supply for ferrochrome producers, reducing price volatility exposure. |
| Green Manufacturing Transition for Ferrochrome | Meets MEE carbon reduction mandates, enhancing market access in China. |
| Long-term Supply Agreements with End-Users | Ensures stable ferrochrome demand for European stainless steel manufacturers. |
| Joint Venture for Advanced Ore Sorting | Optimizes furnace feed and reduces energy consumption for ferrochrome production. |
Research Approach
Independent corroboration across industry association reports, government mining statistics, and financial filings underwrites the qualitative findings. This approach combines insights from primary interviews with mining executives, ferrochrome producers, stainless steel manufacturers, and regulatory officials. Bottom-up and top-down triangulation validates market sizing and growth projections.
Rate-of-change decomposition across each market segment informs the quantitative framework. The analytical framework projects growth across the analysis window, considering segmentation dimensions such as mining method, product form, end-user industry, grade, and regional demand. Compound Annual Growth Rates (CAGRs) are derived from historical trends and key forecast inputs like global stainless steel production forecasts and energy price projections.
Geopolitical instability, regulatory shifts, and technological advancements are the dominant revision risks. Forecasts reflect assumptions documented through extensive primary and secondary research. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Global Magnesium Carbonate Minerals Market
Metals & Minerals
Lithium Ingots Market
Metals & Minerals
Cobalt Carbonate Market
Metals & Minerals
Global Base Metal Mining Market
Metals & Minerals
Zinc Sulfate Market
Metals & Minerals
Global Magnesium Hydroxide Market
Metals & Minerals
Phosphorus Ore Market
Metals & Minerals
Global Artificial Rutile Market
Metals & Minerals
Global Magnesium Oxide Market
Metals & Minerals
Manganese Market
Metals & Minerals
Andalusite Market
Metals & Minerals
Cobalt Nitrate Market
Metals & Minerals
Global Magnesium Market
Metals & Minerals
Zellerite Market
Metals & Minerals
Global Nickel Hydroxide Market
Metals & Minerals
Sodium Tungstate Market