
 Pre-Painted Steel Coil Market | 2026-2036
Pre-Painted Steel Coil Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Painted Steel Coil Market Intelligence
Asset-light leasing arrangements for coil coating lines is reconfiguring competitive entry barriers, allowing regional processors to scale without full capital ownership of continuous coating assets. ArcelorMittal leverages integrated raw steel supply to sustain margin control across European and North American pre-painted coil operations. POSCO anchors its position through captive supply of high-grade galvanized substrate from its Pohang complex. NLMK competes via specialized coil coating services tied to Russian and CIS construction cycles.
Pre-painted steel coil consists of flat-rolled steel sheet that receives protective organic coatings through continuous hot-dip or electro-coating processes, typically achieving dry film thickness of 15–35 micrometers for exterior architectural applications. The finished product serves primarily as durable, corrosion-resistant cladding and roofing material for commercial and residential construction, with secondary use in appliance housings and automotive body panels. Galvanized steel substrate dominates volume flows due to its cost-performance balance in building envelope applications, while polyvinylidene fluoride coatings command premium positioning through superior UV resistance and color retention in harsh environments. Polyester-coated aluzinc products occupy the fastest-growing niche for agricultural and industrial roofing in humid climates where sacrificial zinc-aluminum protection extends service life.
China's GB/T 12754 standard for color-coated steel sheets and Japan's JIS G 3312 specification govern coating adhesion, corrosion resistance, and color uniformity across East Asian supply chains, directly influencing mill qualification requirements for construction tenders. The EU's REACH regulation and RoHS directive restrict hexavalent chromium and specific solvent chemistries in coil coating formulations, forcing reformulation investments among European producers and export-oriented Asian mills. India's BIS certification mandate for imported pre-painted coils creates non-tariff market access conditions that favor domestic coating capacity expansion. Stakeholders must monitor divergence between regional chemical compliance regimes and substrate-recycling requirements as circular-economy rules tighten scrap value recovery for coated steel products.
Market Dynamics
Asset-light leasing models for coil coating infrastructure are redistributing manufacturing capacity toward regional processors who bypass full capital ownership of continuous coating lines, compressing traditional scale advantages held by integrated steel producers.
Growth Catalysts
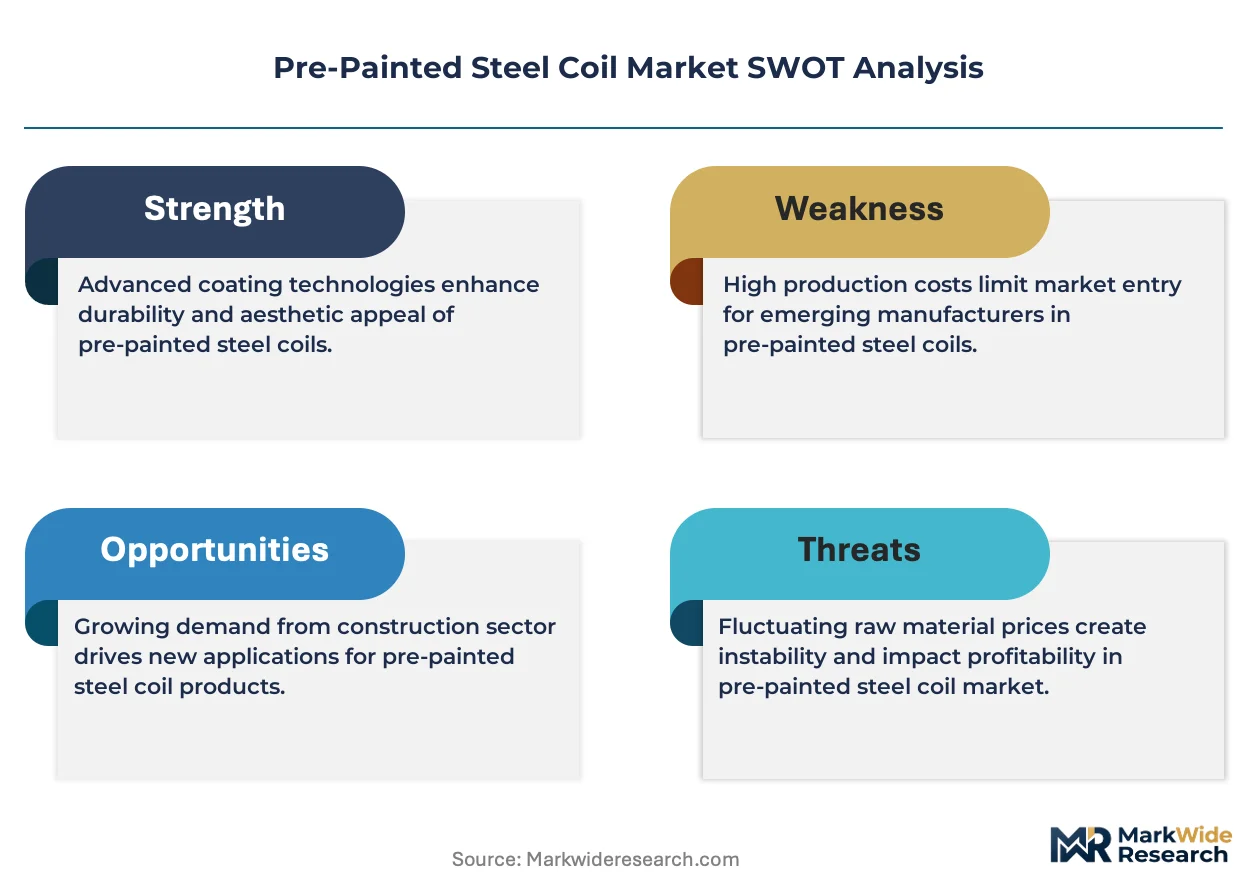
- GB/T 12754 adhesion standards:China's tightening coating durability specifications are disqualifying low-grade imports and stimulating domestic mill qualification investments for construction tenders.
- Galvanized substrate dominance:Cost-performance balance in building envelope applications sustains volume flows across commercial roofing and cladding procurement cycles.
- Yangtze River Delta concentration:Integrated steel-coating facilities in this cluster supply both domestic builders and export markets with streamlined logistics.
Market Restraints
- Zinc price volatility:Hot-dip galvanizing input costs fluctuate with London Metal Exchange pricing, squeezing coating line margins during commodity spikes.
- EU REACH chemical restrictions:Hexavalent chromium and solvent chemistry bans force reformulation investments that disadvantage smaller coating operations lacking R&D scale.
- Aluminum composite panel substitution:Lightweight cladding alternatives capture premium architectural specifications where weight reduction outweighs steel's cost advantage.
Strategic Opportunities
- India's BIS certification mandate:Import restrictions create protected market conditions favoring domestic coating capacity expansion near construction demand centers.
- Polyvinylidene fluoride coating convergence:UV-resistant formulations meeting JIS G 3312 color uniformity standards open premium positioning in harsh-environment infrastructure.
- Agricultural roofing applications:Polyester-coated aluzinc products address humid climate durability requirements underserved by conventional galvanized offerings.
Industry Challenges
- Coating technician scarcity:Continuous line operation requires specialized skills in thickness control and cure monitoring that outpace vocational training pipeline output.
- Multi-standard certification timelines:Simultaneous GB, JIS, and BIS qualification processes extend product launch cycles for export-oriented mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Painted Steel Coil Market |
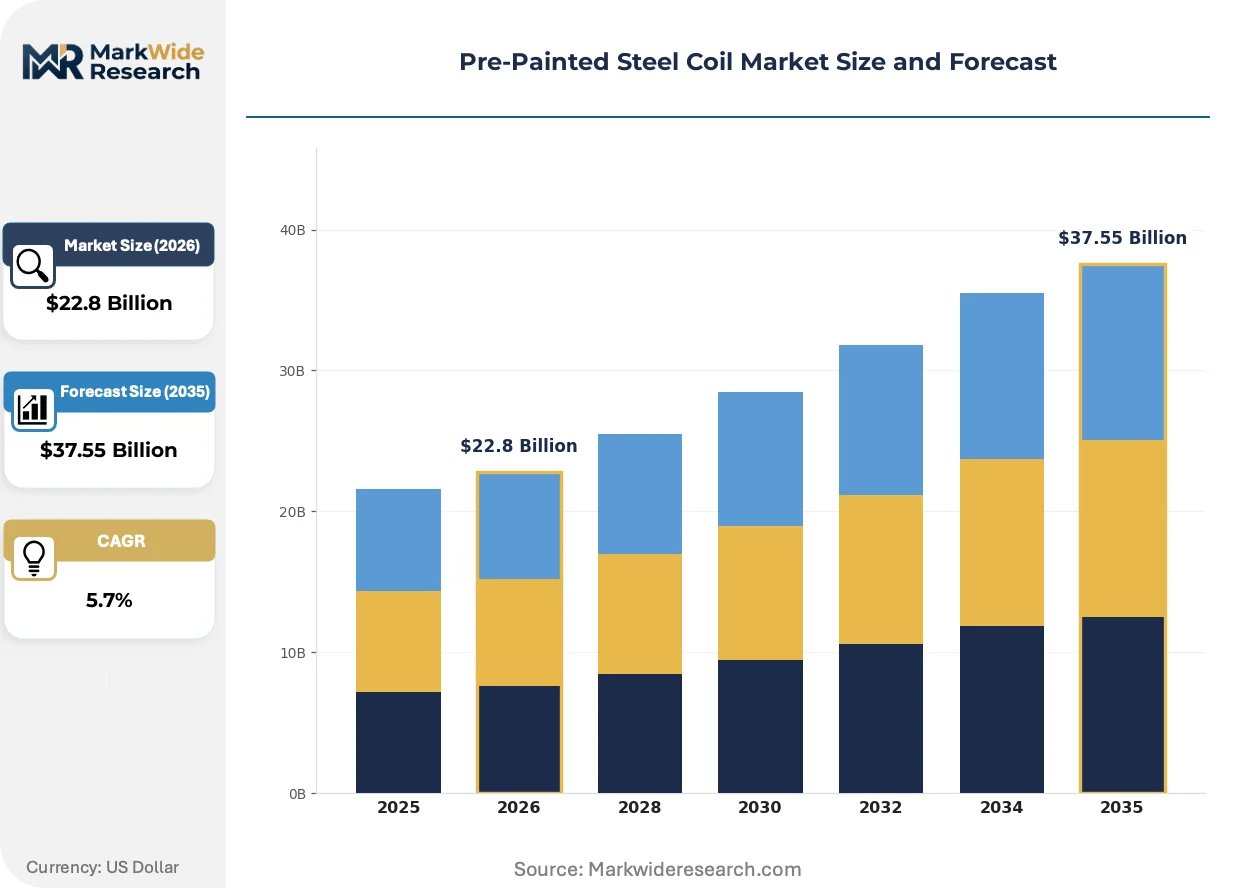
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $37.55 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Galvanized Steel, Aluzinc Steel, Stainless Steel, Cold Rolled Steel Coating Type: Polyester, Polyvinylidene Fluoride, Epoxy, Acrylic End User: Construction, Automotive, Appliances, Furniture Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | ArcelorMittal, POSCO, NLMK, Nippon Steel Coated Sheet Corporation, BlueScope Steel, Tata Steel, JFE Steel Corporation, Baosteel Group Corporation, Nucor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Painted Steel Coil Market Strategic Shifts & Innovations
Digital thickness monitoring and predictive cure optimization are replacing manual quality control protocols, while regulatory chemical bans and buyer consolidation reshape competitive requirements across coating specifications.
Electro-coating deposition technology is collapsing the thickness tolerance window that previously separated premium from standard coil grades. Japanese appliance manufacturers now specify electro-coated substrates for housing panels requiring uniform 15-micrometer films, eliminating the cost premium once commanded by precision hot-dip alternatives. This thickness precision is collapsing price differentiation across mid-tier coating service tiers.
REACH Annex XVII restrictions on chromium trioxide in passivation treatments are forcing European coil coaters toward trivalent chromium and silane-based pretreatment chemistries. The industrial consequence is elevated capital expenditure for conversion coating line retrofits. Export-oriented Chinese mills serving EU construction markets are responding by accelerating in-house REACH-compliant laboratory certification to maintain tender eligibility.
Consolidated procurement by multinational construction contractors is compressing supplier qualification cycles from multi-year frameworks to single-project trials. General contractors in Southeast Asian commercial development now mandate coil-specific BIS or JIS test reports before specification approval, displacing historical mill-brand loyalty. This behavior shift concentrates most visibly in Vietnam's industrial park construction wave where foreign EPC firms enforce unified global sourcing protocols.
Pre-Painted Steel Coil Market Segmentation
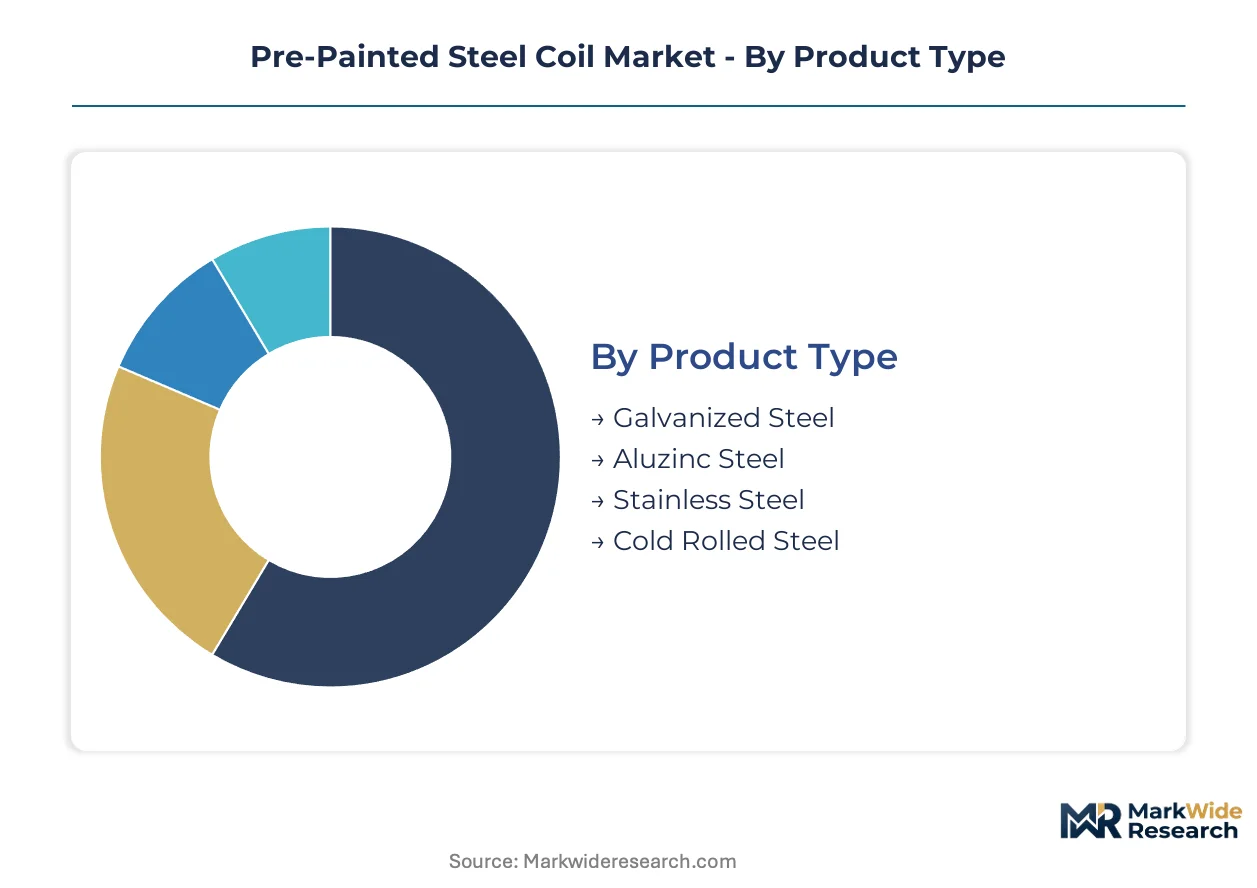
Pre-painted steel coil procurement patterns diverge sharply across substrate chemistry, coating durability specifications, and end-use performance requirements. Construction contractors, automotive OEMs, and appliance manufacturers each impose distinct qualification protocols that reshape supplier positioning across segment boundaries.
Product Type:
Cost tier determines substrate selection across building envelope and industrial applications, with zinc-based protection commanding volume flows while premium alloys capture specification-critical niches.
- Galvanized Steel:Zinc-coated carbon steel substrate delivers the dominant cost-performance balance for commercial roofing and cladding. Demand concentrates in China's Yangtze River Delta industrial cluster where integrated mills supply both domestic construction and export markets under GB/T 12754 adhesion standards.
- Aluzinc Steel:Zinc-aluminum alloy coating provides sacrificial corrosion protection extending service life in humid agricultural and industrial environments. Polyester-coated aluzinc products are climbing fastest in Southeast Asian procurement cycles where humidity degradation outpaces conventional galvanized durability.
- Stainless Steel:Chromium-nickel alloy substrates serve chemical processing and coastal infrastructure requiring maximum corrosion immunity.
- Cold Rolled Steel:Uncoated substrate feeds secondary coating operations and indoor appliance applications where atmospheric exposure is minimal.
Galvanized steel holds installed capacity. Aluzinc steel is rotating up the share rankings.
Coating Type:
Application environment dictates resin chemistry selection, with architectural longevity requirements separating premium fluoropolymer formulations from commodity polyester systems.
- Polyester:Saturated polyester resin systems dominate volume production for standard commercial roofing with 15-25 micrometer dry film thickness. China's construction procurement under GB standards sustains polyester's cost-driven positioning despite UV degradation limitations in tropical climates.
- Polyvinylidene Fluoride:PVDF resin chemistry achieves superior color retention and chalk resistance for harsh-environment infrastructure. JIS G 3312 color uniformity specifications in Japanese commercial development open premium positioning for fluoropolymer-coated coils in coastal and high-UV installations.
- Epoxy:Thermosetting epoxy primers enhance adhesion and chemical resistance in appliance and automotive interior panels.
- Acrylic:Water-based acrylic coatings serve interior architectural applications and furniture manufacturing with lower VOC emissions.
Polyester maintains volume leadership. PVDF is expanding most quickly in premium specification tiers.
End User:
Customer type imposes divergent performance certification requirements, from structural building codes to appliance surface finish standards.
- Construction:Commercial and residential building envelope applications consume the majority of coil-coated steel volume. India's BIS certification mandate for imported coils is redirecting procurement toward domestic coating capacity near major urban construction centers.
- Automotive:Body panel and structural component specifications demand precise thickness tolerance and corrosion warranties. Japanese OEMs now specify electro-coated substrates for housing panels requiring uniform 15-micrometer films.
- Appliances:Refrigerator and washing machine housings prioritize surface aesthetics and dent resistance over extended weathering performance.
- Furniture:Office systems and retail fixtures utilize pre-painted coils for decorative paneling with moderate durability requirements.
Construction anchors procurement volume. Automotive is gaining specification sophistication fastest.
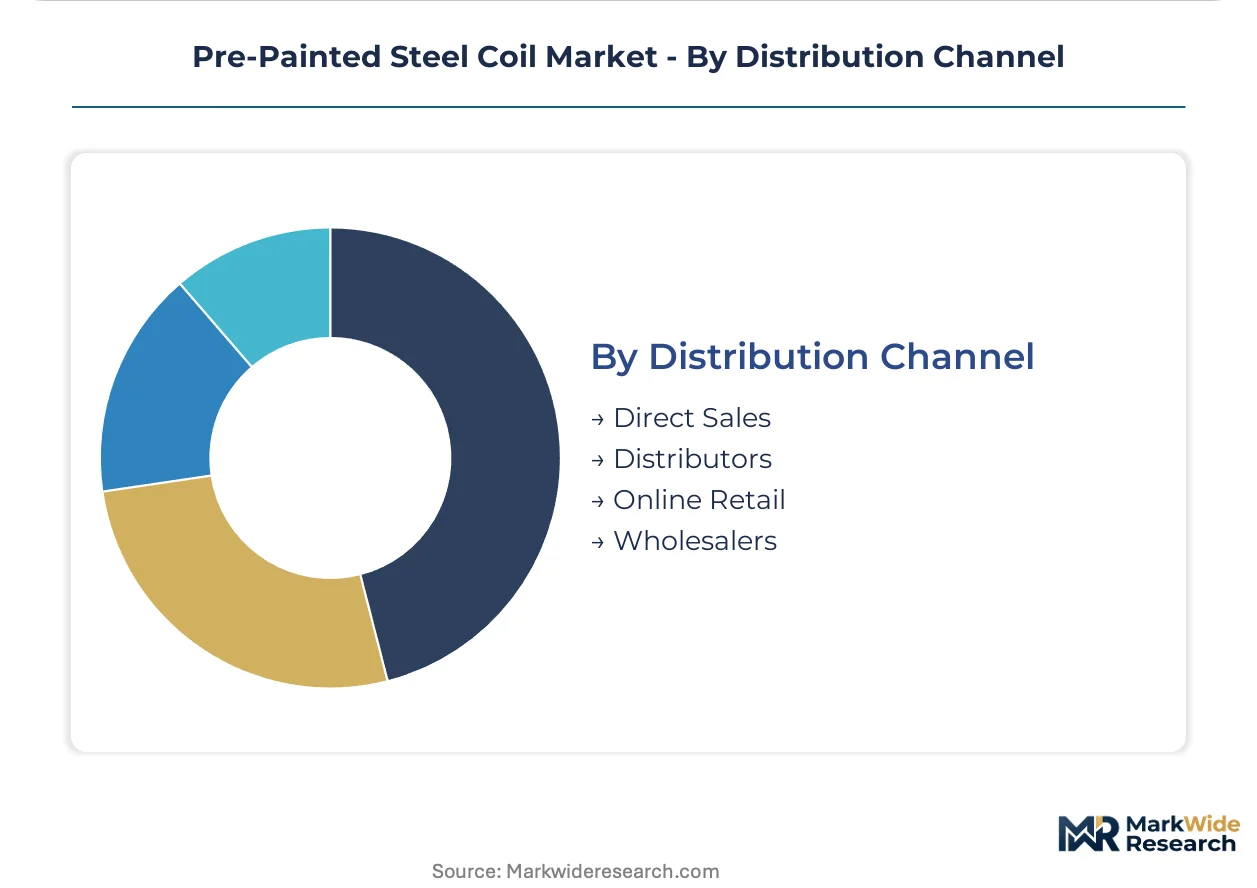
Distribution Channel:
Supply concentration shapes channel selection, with mill-direct relationships dominating high-volume construction while fragmented metal service centers feed specialized fabricators.
- Direct Sales:Mill-direct procurement serves large construction contractors and automotive OEMs with dedicated volume allocations. Consolidated multinational EPC procurement in Vietnam's industrial park wave now mandates coil-specific test reports before specification approval.
- Distributors:Regional metal service centers provide slitting, blanking, and just-in-time delivery to fabricators lacking continuous coil handling capability.
- Online Retail:Digital platforms penetrate small-batch architectural and furniture applications with standardized color catalog offerings.
- Wholesalers:Inventory aggregation serves secondary markets and emergency replacement procurement outside mill-direct minimums.
Direct sales commands project-scale volume. Distributors are deepening penetration among mid-tier fabricators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB/T 12754 coating durability standards are tightening product specifications and disqualifying low-grade imports across East Asian procurement channels. India's BIS certification mandate for imported pre-painted coils is redirecting procurement toward domestic coating capacity near construction demand centers. Japan's JIS G 3312 color uniformity specifications govern premium architectural specifications.
China
Commercial roofing and cladding procurement is accelerating in the Yangtze River Delta industrial cluster where integrated steel-coating facilities supply domestic builders and export markets. GB standards for coating adhesion and corrosion resistance are tightening mill qualification requirements for construction tenders. Shanghai and Jiangsu province coating lines are expanding capacity to meet both domestic infrastructure and Southeast Asian export demand.
India
BIS certification requirements for imported pre-painted coils are creating protected market conditions favoring domestic coating capacity expansion. The central government's infrastructure push is driving commercial building envelope procurement across Maharashtra and Gujarat construction corridors. Domestic mills near Delhi-NCR and Mumbai are qualifying under BIS specifications to capture procurement previously served by imports.
Japan
JIS G 3312 specifications for color uniformity and coating adhesion govern premium commercial development specifications in coastal and high-UV installations. METI oversight of industrial standards ensures rigorous mill qualification protocols for construction tenders. Kanto and Kansai regional coating operations serve domestic appliance and automotive panel demand alongside architectural applications.
United States
Commercial construction procurement of galvanized and aluzinc-coated panels is expanding across Sun Belt metropolitan development corridors. EPA regulations on volatile organic compound emissions from coating operations influence line technology investments. Texas and Southeast regional processors are scaling coil coating capacity to serve domestic building envelope demand without trans-Pacific logistics exposure.
Germany
EU REACH Annex XVII restrictions on hexavalent chromium in passivation treatments are forcing coil coaters toward trivalent chromium and silane-based pretreatment chemistries. ECHA compliance requirements disadvantage smaller coating operations lacking reformulation R&D scale. North Rhine-Westphalia and Bavaria coating facilities are retrofitting conversion coating lines to maintain tender eligibility across European construction markets.
Pre-Painted Steel Coil Market Key Industry Players
On the supply side, the industry is consolidating around integrated steel producers with captive substrate supply and regional processors leveraging asset-light leasing arrangements for coating line access. Three strategic archetypes dominate: integrated steel majors controlling raw material through finished coil, regional coating specialists serving construction procurement cycles, and automotive-focused precision coaters. Competitive moves concentrate on capacity expansion in protected certification markets and technology licensing for REACH-compliant pretreatment chemistries.
Within the integrated steel tier, ArcelorMittal anchors European and North American operations through captive raw steel supply, while POSCO exemplifies the Asia-Pacific model with integrated high-grade galvanized substrate from its Pohang complex. NLMK occupies a position serving Russian and CIS construction cycles through specialized coil coating services. These three companies represent distinct geographic anchoring strategies that mirror regional regulatory and demand fragmentation.
| Leading Market Players |
|---|
| ArcelorMittal |
| POSCO |
| NLMK |
| Nippon Steel Coated Sheet Corporation |
| BlueScope Steel |
| Tata Steel |
| JFE Steel Corporation |
| Baosteel Group Corporation |
| Nucor Corporation |
| Others |
Cost & Logistics Intelligence
Zinc price volatility on the London Metal Exchange determines both tiered pricing spreads across galvanized and aluzinc substrates and the geographic shape of supply chain concentration. Procurement managers face simultaneous margin compression from commodity spikes and qualification-driven premium capture for REACH-compliant and BIS-certified coil grades.
Pricing Analysis
Certification level creates the primary spread between premium and standard coil tiers. Three-tier pricing structure across PVDF-coated architectural grades, polyester commercial roofing, and commodity galvanized construction separates procurement budgets by durability specification. Price differentiation hinges on coating thickness precision and regional compliance documentation, with BIS-certified imports commanding premiums over uncertified alternatives. Cost compression in mid-tier polyester segments is intensifying because electro-coating technology collapses thickness tolerance advantages. Volume contractors in China's Yangtze River Delta exhibit highest price sensitivity, while Japanese appliance OEMs prioritize film uniformity over unit cost.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk calculus for Asian coil procurement. Production gravity centers on China, South Korea, and Japan, with integrated steel-coating facilities in the Yangtze River Delta and Pohang complex anchoring regional substrate flows. Raw material dependencies rest on zinc ingot from Australian and Peruvian mining operations, chromate pretreatment chemicals subject to REACH Annex XVII restrictions, and specialized PVDF resin from Japanese chemical producers. Single-source vulnerability concentrates in high-grade galvanized substrate from POSCO's captive Pohang supply. Distribution runs through mill-direct relationships for large construction contractors and regional metal service centers for fragmented fabricator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction procurement fragmentation across certification regimes creates niche entry points for specialized coaters. Divergent GB, JIS, and BIS qualification timelines segment addressable demand by compliance capability rather than scale alone.
For Market Incumbents: Harden qualification moats by accelerating in-house REACH-compliant laboratory certification to maintain EU tender eligibility against export-oriented Chinese mills. Anchor margin control through captive high-grade galvanized substrate supply from integrated complexes, while retrofitting conversion coating lines ahead of hexavalent chromium phase-outs. Defensive capacity positioning in India's protected BIS certification market neutralizes import competition from uncertified regional processors. For New Entrants and Emerging Players: Build out asset-light leasing arrangements for coil coating infrastructure to bypass full capital ownership barriers in Southeast Asian construction corridors. Agricultural roofing applications in humid climates represent the most penetrable white-space, where polyester-coated aluzinc products outpace conventional galvanized durability. Target Vietnam's industrial park construction wave through qualification under foreign EPC firms' unified global sourcing protocols. For Investors and Strategic Acquirers: India's BIS certification mandate reshapes the acquisition landscape toward domestic coating capacity with established regulatory compliance. Long-term viability across the analysis window favors regional processors with demonstrated multi-standard qualification capability rather than pure volume scale. Watch electro-coating technology diffusion as the inflection signal collapsing premium pricing for thickness precision.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Galvanized Substrate | Captive supply from Pohang-style complexes secures margin control against zinc price volatility. |
| REACH-Compliant Pretreatment Chemistry Licensing | Trivalent chromium and silane-based formulations maintain EU construction market access. |
| BIS Certification Laboratory Investment | In-house testing capacity captures procurement redirected from import-dependent contractors. |
| Asset-Light Coil Coating Line Leasing | Regional processors scale without full capital ownership of continuous coating assets. |
| Electro-Coating Technology Deployment | Thickness precision collapses price differentiation for mid-tier coating service tiers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from integrated steel producers, and national standards documentation from GB, JIS, and BIS repositories. Primary interviews engaged coating line operators, procurement managers at multinational construction contractors, technical directors at regional metal service centers, and regulatory compliance officers at export-oriented mills. Secondary validation drew from steel industry association reports, London Metal Exchange pricing archives, and ECHA regulatory guidance documents. Bottom-up demand modeling across construction, automotive, and appliance end-uses triangulated against top-down supply capacity assessments from integrated mill disclosures.
Forecast inputs include substrate chemistry segmentation, coating durability tier migration, and regional certification mandate implementation timelines across the analysis window. Modeled dimensions span galvanized versus aluzinc versus stainless substrate selection, polyester versus PVDF versus epoxy resin chemistry, and construction versus automotive versus appliance end-use concentration. CAGRs derive from volume trajectory analysis against capacity expansion announcements and qualification timeline compression. Industry-specific inputs incorporate zinc price correlation coefficients and REACH chemical restriction phase-in schedules.
Stress conditions across zinc commodity spikes, REACH enforcement acceleration, and BIS certification backlog scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding coating technology substitution rates and regional procurement consolidation patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Wear-Resistant Welding Wire Market
Industrial Materials
Gaskets and Seals Market
Industrial Materials
Metal Based Safety Gratings Market
Industrial Materials
Fiberglass Tanks Market
Industrial Materials
Industrial Round Wood Market
Industrial Materials
Magnet Rings Market
Industrial Materials
Southeast Asia Industrial Flooring Market
Industrial Materials
Wire Hoods Market
Industrial Materials
Global Thermally Modified Wood Market
Industrial Materials
Global Polycarbonate Sheets Market
Industrial Materials
Wood Protein Market
Industrial Materials
Crimped Wire Brushes Market
Industrial Materials
Self Locking Nuts Market
Industrial Materials
United States Graphite Electrodes Market
Industrial Materials
Magnetic Separator Market
Industrial Materials
Asia-Pacific Industrial Flooring Market